
 Mammalian Derived Proteins Market | 2026-2036
Mammalian Derived Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Mammalian Derived Proteins Market Foresight
Multi-source sourcing of cell culture media and protein expression systems is expanding as biopharmaceutical developers hedge against supply disruptions. Thermo Fisher Scientific leverages its end-to-end bioproduction portfolio to anchor large-molecule workflows across North America and Europe. Lonza sustains leadership in contract manufacturing through its mammalian expression platforms in Switzerland and Singapore. Merck KGaA differentiates via high-performance media formulations that reduce batch variability for monoclonal antibody producers.
Mammalian derived proteins comprise bioactive molecules extracted or expressed from mammalian cell lines, primarily Chinese hamster ovary (CHO) and human embryonic kidney (HEK) systems, yielding complex glycoproteins with post-translational modifications essential for therapeutic efficacy. These proteins serve as active pharmaceutical ingredients, diagnostic reagents, and research tools where human-like folding and glycosylation determine biological activity. Monoclonal antibodies command the largest value pool among product types due to their entrenched role in oncology and autoimmune therapy, while recombinant proteins represent the fastest-expanding category as gene therapy and cell therapy developers demand specialized growth factors. Within applications, therapeutic use dominates revenue, though vaccine development is accelerating as mRNA and viral vector platforms require novel adjuvant proteins.
FDA's Current Good Manufacturing Practice (CGMP) regulations and EMA's biosimilar comparability guidelines enforce stringent purity and identity testing that elevates barriers for new mammalian protein suppliers. The International Council for Harmonisation (ICH) Q5D and Q5A standards further codify cell line characterization and viral safety expectations that shape R&D investment priorities. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on continuous manufacturing guidelines, as this will determine which expression platforms and facility designs gain competitive approval advantages.
Market Dynamics
Continuous bioprocessing adoption is compressing batch cycle times and forcing mammalian protein suppliers to reconfigure facility layouts around single-use technologies rather than stainless-steel infrastructure.
Growth Catalysts
- CGMP modernization:FDA's updated guidance on process analytical technology is accelerating investment in real-time quality monitoring systems for monoclonal antibody production.
- Cell therapy manufacturing:CAR-T expansion protocols require recombinant growth factors at scales that traditional batch suppliers cannot match, creating pull-through demand for high-volume mammalian expression platforms.
- Singapore biologics hub:Government incentives under the Research Innovation Enterprise 2025 plan are concentrating contract manufacturing capacity for Asia-Pacific distribution.
Market Restraints
- Fetal bovine serum price volatility:Supply disruptions from BSE-related import restrictions in Brazil and Argentina are destabilizing cell culture media cost structures.
- Single-source dependency:CHO cell line intellectual property concentration in the United States creates licensing bottlenecks for new market entrants in Europe and Asia.
- Viral clearance validation:EMA's tightened adventitious agent testing requirements extend facility qualification timelines by twelve to eighteen months for mammalian protein producers.
Strategic Opportunities
- India CDMO expansion:CDSCO's streamlined biosimilar approval pathways and PLI scheme subsidies for biopharma manufacturing are attracting contract development investment.
- Continuous manufacturing:Convergence of perfusion bioreactors with inline analytics enables real-time release testing that reduces quality control overhead for high-volume antibody producers.
- Gene therapy adjuvants:AAV and lentiviral vector production requires novel recombinant helper proteins where specialized suppliers can command premium positioning.
Industry Challenges
- Bioprocess engineering talent scarcity:Universities in Germany and Switzerland cannot graduate sufficient cell culture specialists to staff expanding mammalian manufacturing capacity.
- Legacy equipment integration:Hybrid facilities combining stainless-steel and single-use systems face validation complexity that delays technology transfer from development to commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mammalian Derived Proteins Market |
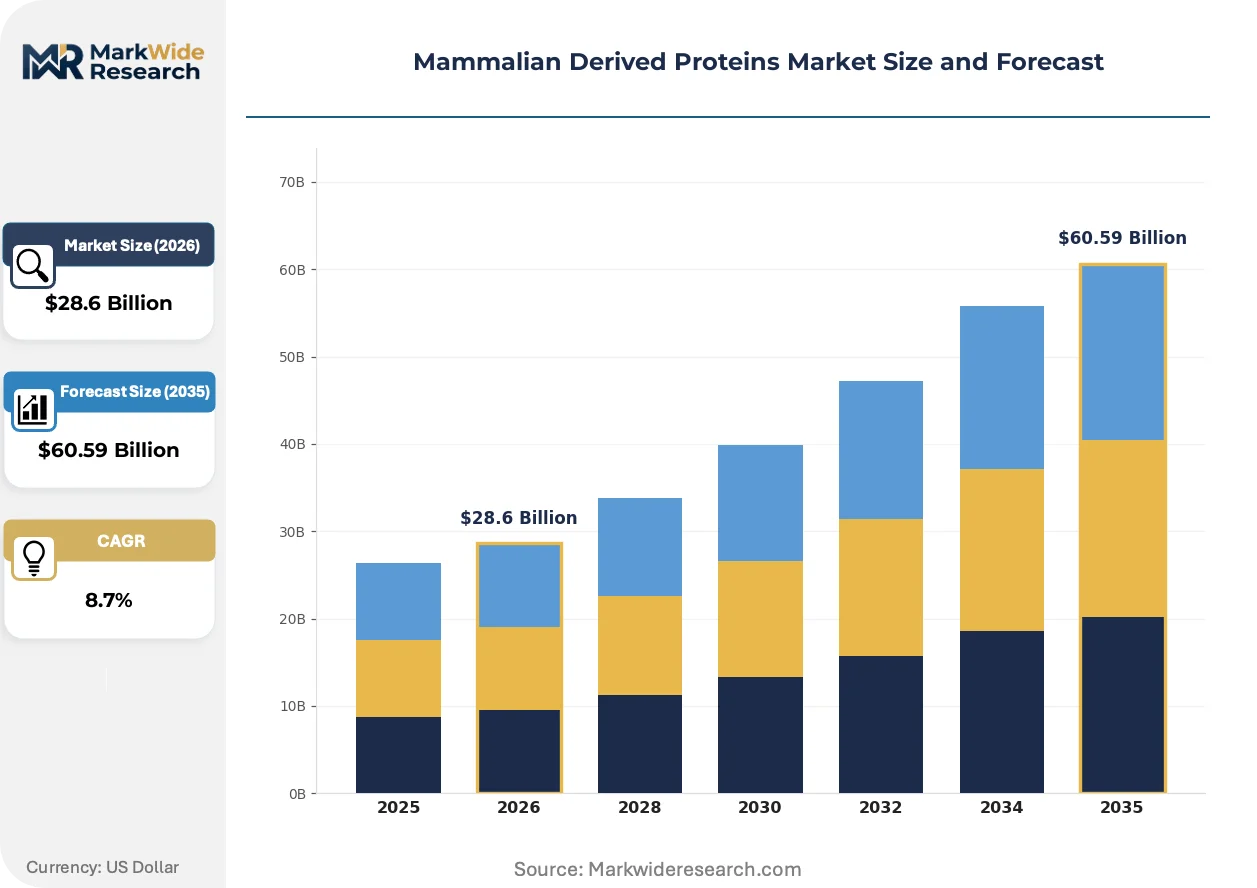
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Proteins, Vaccines, Hormones Application: Therapeutic, Diagnostic, Research, Vaccine Development End User: Pharmaceuticals, Biotechnology, Academic Institutes, Research Laboratories Delivery Mode: Injectable, Intranasal, Oral, Topical |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Lonza, F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Danaher Corporation, Sartorius AG, Agilent Technologies, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mammalian Derived Proteins Market Shifts & Advancements
Modular facility architectures and disposable manufacturing technologies are dismantling traditional capital barriers to mammalian protein production, enabling distributed manufacturing networks closer to end-use markets.
Single-use bioreactor technology is decentralizing large-molecule production by eliminating steam-in-place validation requirements and reducing facility construction timelines from thirty-six to eighteen months. Mid-size biopharma developers in the Netherlands and Sweden are adopting 2,000-liter disposable systems for Phase III commercial supply. This shift is compressing the minimum efficient scale for profitable mammalian protein manufacturing and fragmenting geographic production concentration.
EMA's forthcoming revision to Annex 1 on sterile manufacturing will mandate enhanced environmental monitoring and closed-system processing for all mammalian-derived parenteral proteins. The industrial consequence is accelerated replacement of open manipulations with isolator-based filling lines. Monoclonal antibody producers in Ireland and Belgium are front-loading capital expenditure to secure compliance ahead of the 2025 implementation deadline.
Buyers are consolidating supplier relationships from an average of twelve to four qualified vendors per therapeutic program, prioritizing those with dual-sourced raw material strategies and documented business continuity plans. This concentration is displacing spot-market purchasing for cell culture media and favoring multi-year supply agreements with volume commitments. The shift is most visible among oncology-focused biotechs in the Boston-Cambridge cluster, where procurement teams now require supplier disaster recovery documentation as a standard qualification criterion.
Mammalian Derived Proteins Market Segmentation
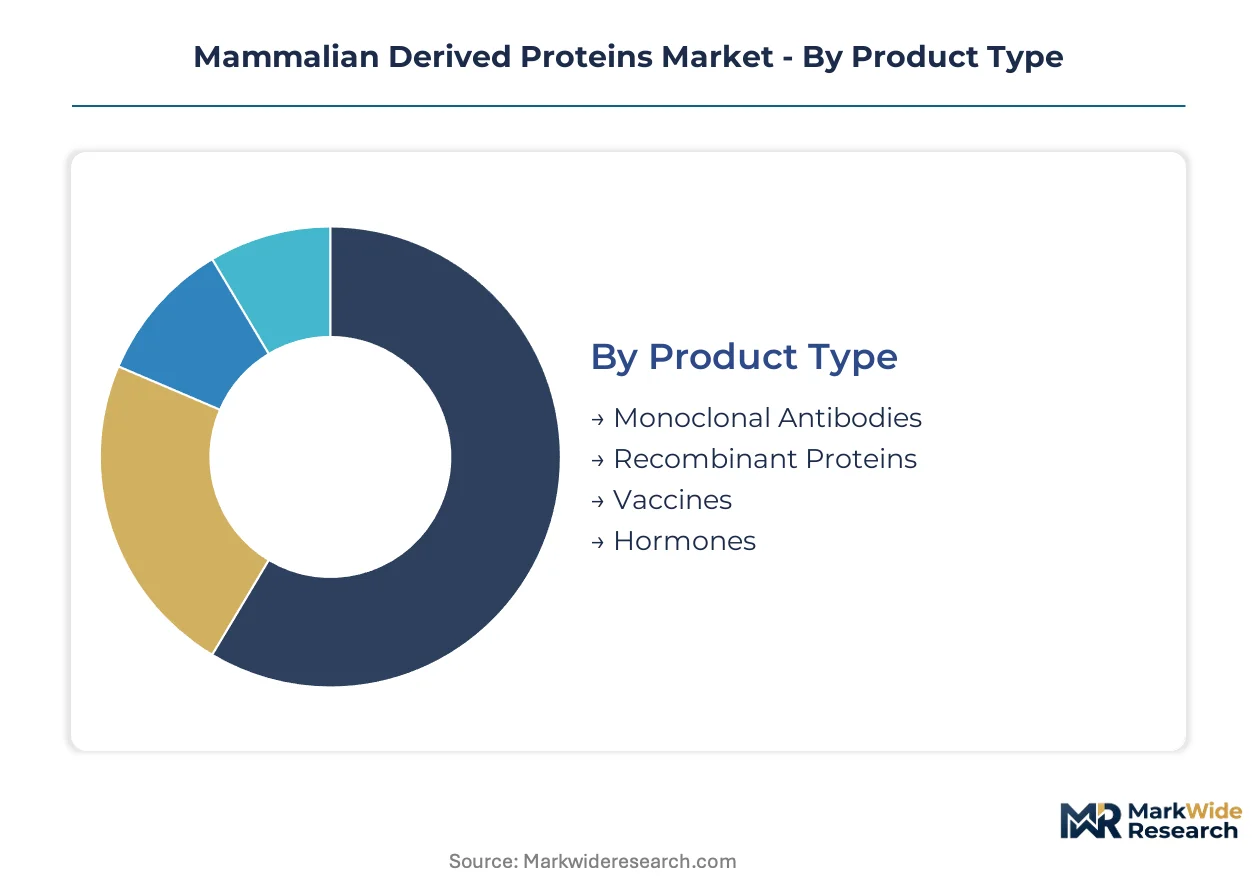
Segmentation in the mammalian derived proteins market reveals how therapeutic complexity, regulatory pathways, and manufacturing scale reshape supplier strategies across distinct value pools. Buyers prioritize glycosylation fidelity, batch consistency, and viral clearance documentation when selecting protein categories for their development pipelines.
Product Type:
Buyers differentiate primarily by therapeutic complexity and post-translational modification requirements, with oncology developers demanding higher glycan uniformity than research-grade purchasers.
- Monoclonal Antibodies:Complex glycoproteins requiring CHO cell expression systems with humanized glycosylation patterns for Fc-effector function. Demand concentrates among immuno-oncology developers in the United States and Germany where FDA and EMA biosimilar comparability guidelines enforce stringent lot-to-lot consistency. Pricing power reflects viral clearance validation burdens and cell line licensing costs.
- Recombinant Proteins:Engineered growth factors, cytokines, and enzymes produced through transient or stable HEK/CHO expression. Cell therapy manufacturers in Singapore and Switzerland are pulling high-volume orders for CAR-T expansion media components that exceed traditional batch supplier capacities.
- Vaccines:Adjuvant proteins and carrier molecules for viral vector platforms. mRNA developers require novel recombinant antigens with defined conformational epitopes.
- Hormones:Therapeutic peptides including erythropoietin analogs and follicle-stimulating hormone variants. Replacement therapy indications in Japan and South Korea sustain steady procurement volumes.
Monoclonal antibodies lead volumes today; recombinant proteins are gaining share fastest.
Application:
Application selection determines regulatory scrutiny intensity, with therapeutic use imposing CGMP compliance costs that research applications avoid entirely.
- Therapeutic:Active pharmaceutical ingredients for injectable biologics. FDA process analytical technology mandates are accelerating real-time quality monitoring adoption among monoclonal antibody producers in Massachusetts and California. Lot release timelines now hinge on continuous bioprocessing integration.
- Diagnostic:Capture reagents, calibrators, and controls for immunoassays. IVD manufacturers in Germany prioritize suppliers with documented ISO 13485 quality management systems and dual-sourced raw material strategies.
- Research:Non-GMP proteins for preclinical discovery. Academic institutes in the Netherlands and Sweden favor catalog offerings with rapid turnaround over customization.
- Vaccine Development:Adjuvant proteins and immunogen candidates for clinical trial material. Viral vector platforms require recombinant helper proteins with adventitious agent clearance documentation per EMA tightened standards.
Therapeutic applications command the largest revenue pool; vaccine development is climbing the fastest as mRNA and viral vector platforms scale manufacturing.
End User:
End user type shapes procurement sophistication, with pharmaceutical companies demanding multi-year supply agreements and disaster recovery documentation that research laboratories rarely require.
- Pharmaceuticals:Large-molecule drug developers with commercial manufacturing footprints. Boston-Cambridge cluster biotechs now consolidate supplier relationships from twelve vendors to four per program, prioritizing business continuity planning.
- Biotechnology:Emerging therapeutics companies without captive manufacturing. CDMO partnerships in Singapore and Ireland enable Phase III commercial supply without capital-intensive facility construction.
- Academic Institutes:Basic research institutions with grant-funded purchasing. Price sensitivity drives spot-market buying for cell culture media.
- Research Laboratories:Contract research organizations and government facilities. Batch size requirements remain below commercial scale, favoring catalog products over custom production.
Pharmaceutical end users dominate procurement value; biotechnology companies are expanding their share fastest through CDMO-enabled pipeline advancement.
Delivery Mode:
Delivery mode selection constrains formulation options and stability requirements, with parenteral routes demanding the highest purity standards and most extensive viral clearance validation.
- Injectable:Intravenous and subcutaneous administration of monoclonal antibodies and recombinant proteins. EMA Annex 1 sterile manufacturing revisions are mandating isolator-based filling lines for parenteral mammalian proteins in Ireland and Belgium ahead of compliance deadlines.
- Intranasal:Mucosal delivery for vaccine adjuvants and certain peptide therapeutics. Formulation stability challenges limit adoption to specialized indications.
- Oral:Gastrointestinal delivery of peptide hormones with enteric coating. Bioavailability constraints restrict this mode to non-critical therapeutic applications.
- Topical:Dermal and ophthalmic administration of growth factors for wound healing. Niche demand from dermatology-focused developers in Japan.
Injectable delivery leads volumes today; intranasal routes are gaining share fastest through vaccine platform diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping mammalian protein manufacturing geography as cost-of-compliance gaps between FDA and EMA jurisdictions drive facility investment decisions. Producers seek locations where biosimilar approval timelines and purity testing burdens minimize capital-at-risk per approved molecule.
United States
FDA's process analytical technology mandates accelerate real-time quality monitoring adoption among monoclonal antibody developers. The 21st Century Cures Act provisions streamline regenerative medicine advanced therapy designations. Massachusetts and California biotech clusters concentrate CDMO partnerships for Phase III commercial supply.
Germany
EMA biosimilar comparability guidelines enforce stringent lot-to-lot consistency requirements that elevate supplier qualification barriers. The country's national pharmaceutical regulator maintains accelerated assessment pathways for breakthrough therapies. Bavaria and North Rhine-Westphalia host the largest contract manufacturing footprints for European distribution.
Switzerland
Swissmedic alignment with ICH Q5D cell line characterization standards reduces duplicate testing for export-bound production. Federal innovation incentives under the Swiss Biotech Strategy 2025 concentrate R&D investment. Basel and Zurich regions anchor mammalian expression platform development for global biologics supply.
Singapore
Research Innovation Enterprise 2025 plan subsidies attract contract manufacturing investment for Asia-Pacific distribution. The country's national pharmaceutical regulator maintains mutual recognition agreements with FDA and EMA that compress multi-market approval timelines. Tuas Biomedical Park expansion concentrates single-use bioreactor capacity for regional cell therapy demand.
India
CDSCO streamlined biosimilar approval pathways and PLI scheme subsidies for biopharma manufacturing attract contract development investment. Import substitution policies for cell culture media reduce dependency on Brazilian and Argentine fetal bovine serum supply. Hyderabad and Bengaluru clusters expand mammalian protein production for export to regulated markets.
Mammalian Derived Proteins Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gene therapy adjuvant specialization and continuous manufacturing integration. The vendor base stratifies across three archetypes: diversified life science conglomerates with end-to-end bioproduction portfolios, focused CDMOs with captive mammalian expression platforms, and specialized media suppliers with high-performance formulation capabilities. Capacity expansion and strategic partnerships dominate competitive moves as firms secure multi-year supply agreements with consolidated buyer bases.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation anchor the standard tier through comprehensive bioproduction portfolios spanning reagents to analytical instrumentation. Lonza exemplifies the focused CDMO archetype with mammalian expression platform concentration in Switzerland and Singapore. Merck KGaA occupies a position within the specialized media supplier tier, differentiating through high-performance formulations that reduce batch variability for monoclonal antibody producers. These three entities represent distinct strategic postures without implying specific market share positions or competitive rankings.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Lonza |
| F. Hoffmann-La Roche Ltd |
| Eli Lilly and Company |
| Danaher Corporation |
| Sartorius AG |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Single-use bioreactor technology is compressing facility construction timelines from thirty-six to eighteen months while fragmenting geographic production concentration across distributed manufacturing networks. This shift simultaneously reduces capital-at-risk for new entrants and intensifies price competition among established suppliers as minimum efficient scale thresholds fall.
Pricing Analysis
Distributor margins for cell culture media and protein expression systems typically range from fifteen to twenty-five percent depending on volume commitments and geographic reach. Contract-based long-term offtake agreements dominate therapeutic-grade mammalian proteins, with price differentiation driven by viral clearance validation documentation and CGMP certification tier. Cost compression in research-grade catalog products is intensifying as academic institutes consolidate purchasing through group procurement organizations. Biotechnology companies with CDMO partnerships exhibit the lowest price sensitivity due to embedded quality assurance requirements, while academic laboratories remain highly price-sensitive and favor spot-market purchasing.
Supply Chain Analysis
Regional distribution centers in Switzerland, Singapore, and the United States operate hub-and-spoke patterns to serve biopharmaceutical manufacturing clusters. Manufacturing concentration rests on Switzerland for high-complexity monoclonal antibodies, Singapore for Asia-Pacific cell therapy supply, and the United States for FDA-regulated commercial production. Raw material dependencies include Chinese hamster ovary cell lines, fetal bovine serum from Brazil and Argentina, and single-use bioreactor components. Single-source vulnerability in CHO cell line intellectual property creates licensing bottlenecks. Distribution runs through qualified supplier programs with documented business continuity planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mammalian derived proteins hinges on continuous manufacturing adoption that reduces batch failure rates and quality control overhead. Premium-tier positioning through specialized gene therapy adjuvant capabilities commands pricing power unavailable in commoditized research-grade segments.
For Market Incumbents: Extend platform coverage into continuous bioprocessing equipment and inline analytics to defend against emerging entrants with modular facility architectures. Backward integration into high-performance media formulation reduces dependency on third-party suppliers facing fetal bovine serum price volatility. Capacity addition in Singapore leverages government subsidies under the Research Innovation Enterprise 2025 plan while anchoring Asia-Pacific distribution. For New Entrants and Emerging Players: Enter via gene therapy adjuvant specialization where viral vector production demands novel recombinant helper proteins with limited qualified supplier options. Target CDMO partnerships in India where CDSCO streamlined biosimilar approval pathways and PLI scheme subsidies reduce facility qualification burdens. Pursue go-to-market angles through direct technical collaboration with CAR-T developers requiring scale-mismatched growth factor volumes. For Investors and Strategic Acquirers: Roll-up economics work for specialized media suppliers because fragmented regional production creates consolidation value through formulation standardization and cross-facility technology transfer. Five-to-ten year viability favors platforms with demonstrated viral clearance validation and dual-sourced raw material strategies. Watch FDA-EMA convergence on continuous manufacturing guidelines as the inflection indicator for which expression platforms gain competitive approval advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Integration | Perfusion bioreactor adoption reduces quality control overhead for high-volume antibody producers in Massachusetts. |
| Gene Therapy Adjuvant Development | Specialized recombinant helper proteins for AAV production command premium positioning among viral vector developers. |
| India CDMO Expansion | CDSCO streamlined pathways and PLI subsidies attract contract development investment for export to regulated markets. |
| Dual-Sourced Raw Material Strategy | Business continuity documentation now qualifies suppliers for consolidated buyer relationships in the Boston-Cambridge cluster. |
| EMA Annex 1 Compliance Investment | Isolator-based filling line upgrades secure parenteral protein supply contracts ahead of sterile manufacturing deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and operational constraints in mammalian protein manufacturing. Primary interviews engaged bioprocess engineering directors, regulatory affairs leads at EMA and FDA, CDMO procurement managers, and academic laboratory purchasing coordinators. Secondary validation drew from FDA guidance documents, EMA biosimilar comparability guidelines, ICH Q5D standards, and customs trade data on cell culture media imports. Bottom-up modeling of expression platform capacities was triangulated against top-down therapeutic pipeline analysis.
Segment-weighting approaches applied differential growth assumptions across monoclonal antibodies, recombinant proteins, and vaccine adjuvants based on therapeutic complexity and regulatory pathway maturity. Modeled dimensions included product glycosylation requirements, application-specific CGMP compliance tiers, end-user procurement sophistication, and delivery mode stability constraints. CAGRs were derived from capacity expansion announcements, facility investment flows, and buyer consolidation patterns. Forecast inputs incorporated continuous bioprocessing adoption curves and viral clearance validation timeline assumptions.
Inputs from regulatory filings and facility investment databases were available through the study window; gaps in proprietary cell line licensing terms introduce uncertainty bands around supplier market share estimates. Forecasts reflect documented assumptions on EMA-FDA convergence timing and single-use technology penetration rates. Biosimilar approval pathway changes or raw material trade restrictions could materially revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Anti-Infective Drugs Market