
 Bicycle Lights Market | 2026-2036
Bicycle Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Lights Market Analysis
The EU Green Deal is consolidating demand for energy-efficient bicycle illumination across member states. Garmin Ltd. leverages GPS integration to differentiate its edge-lighting systems for navigation visibility. Lezyne sustains competitive pressure through in-house battery management and compact form factors. Cateye Co. Ltd. dominates Japanese domestic distribution while extending its optical lens technology into European StVZO-certified lines.
Bicycle lights are electroluminescent or LED-based signaling devices engineered to outputs between 15 and 2000 lumens, typically housed in aluminum or polymer casings with IPX4 to IPX7 ingress protection, designed to enhance rider visibility and comply with regional traffic safety codes. USB Rechargeable power sources capture the fastest upgrade cycle as consumers abandon disposable battery formats. Front Lights command the highest absolute dollar volume due to StVZO and CPSC beam-pattern mandates, while Rear Lights operate on thinner margins despite higher unit velocity in aftermarket channels.
Federal regulations in the United States fall under CPSC 16 CFR 1512 bicycle safety standards, while Germany enforces StVZO through KBA type approval; France applies additional ANSM visibility directives for urban fleet operators. These frameworks elevate compliance costs for non-certified imports but protect incumbent manufacturers with established testing relationships. Stakeholders must monitor whether emerging micromobility ordinances in dense cities will mandate daytime running lights as a condition of shared-bike licensing.
Market Dynamics
USB-C standardization and lithium-ion cell density improvements are compressing product design cycles while StVZO and CPSC beam-pattern mandates elevate compliance barriers for import-dependent suppliers.
Growth Catalysts
- EU Green Deal:The framework consolidates demand for energy-efficient bicycle illumination across member states, accelerating replacement cycles for non-compliant legacy lighting systems.
- Urban fleet mandates:Municipalities in Copenhagen and Amsterdam require ISO 6742-1 compliant lighting for road-legal bicycles, creating steady aftermarket demand from commuter populations.
- Lithium-ion density gains:Higher energy cells enable compact form factors that satisfy StVZO output requirements without increasing housing bulk or mounting complexity.
Market Restraints
- StVZO certification costs:German KBA type approval procedures impose testing timelines and documentation burdens that disadvantage smaller import suppliers lacking established laboratory relationships.
- Raw material concentration:Rare earth elements for LED phosphors and lithium carbonate for cells concentrate in limited supplier geographies, exposing manufacturers to input price volatility.
- Disposable battery substitution:Low-cost alkaline-powered alternatives persist in price-sensitive retail channels, delaying USB rechargeable penetration in emerging markets.
Strategic Opportunities
- Micromobility daytime running mandates:Dense cities considering shared-bike licensing conditions present a regulatory tailwind for integrated lighting systems on fleet bicycles.
- GPS-lighting convergence:Navigation-visible edge-lighting systems combine position signaling with route guidance, opening premium positioning for technology-integrated suppliers.
- Direct-to-consumer channels:Specialty cycling e-commerce platforms enable brands to bypass traditional distributor markups while capturing enthusiast upgrade cycles.
Industry Challenges
- Optical engineering talent scarcity:StVZO-compliant beam-pattern design requires specialized photometric expertise that concentrates in established German and Japanese suppliers.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of CPSC, StVZO, and ANSM approvals stretches quality assurance resources and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Lights Market |
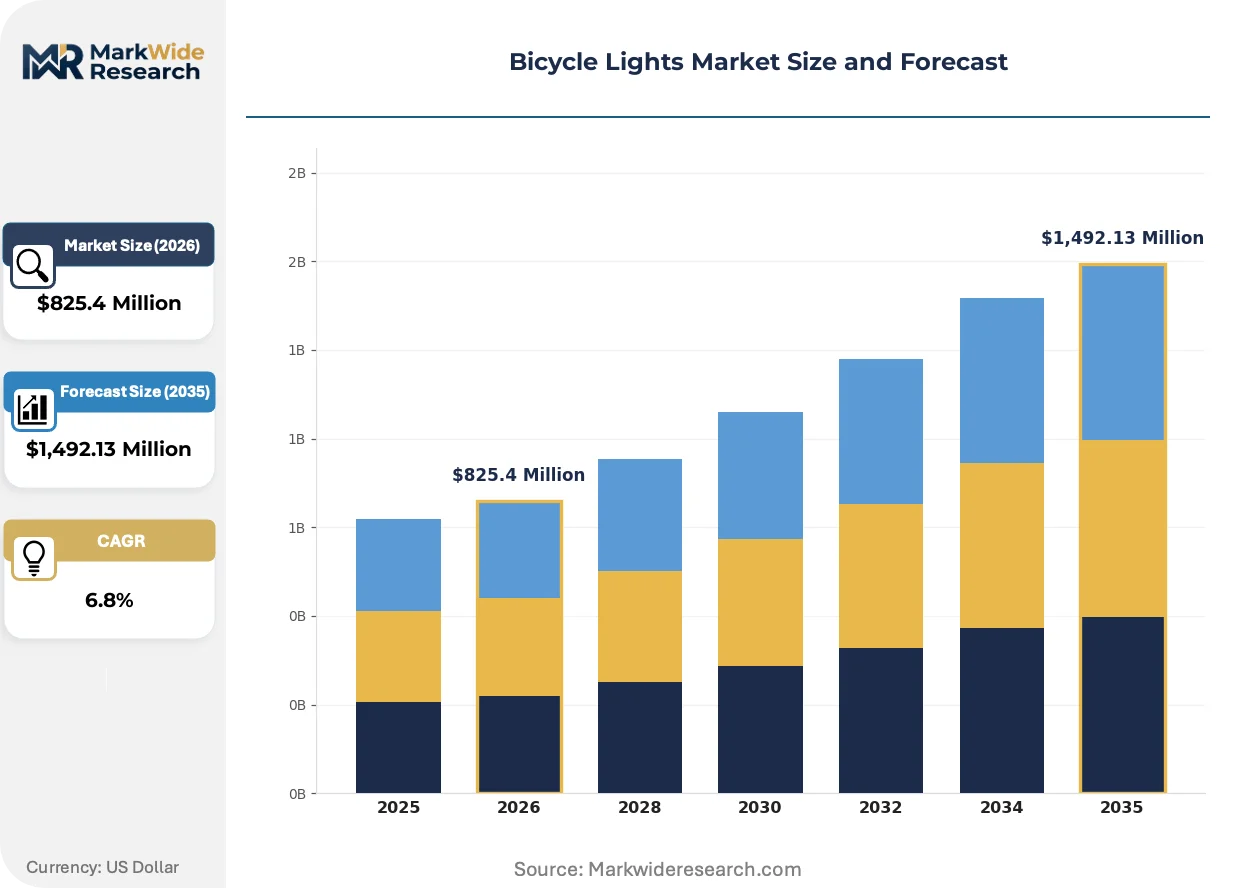
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Lights, Rear Lights, Reflectors, Combination Lights Power Source: Battery-Powered, Solar, Dynamo, USB Rechargeable Mounting Type: Handlebar Mount, Seat Post Mount, Helmet Mount, Magnetic Mount Brightness Level: Low, Medium, High, Flashing |
| Companies Covered | Cateye Co. Ltd., Lezyne, Garmin Ltd., Trek Bicycle Corporation, Cygolite, Knog Pty Ltd., NiteRider Technical Lighting, Blackburn, Lupine Lighting Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Lights Market Emerging Trajectories
Product architecture is converging around unified power interfaces and intelligent beam management, while regulatory fragmentation forces modular certification strategies.
USB-C is consolidating as the dominant power interface across rechargeable bicycle lighting systems. Urban commuters and fleet operators are adopting the standard at accelerating rates, abandoning proprietary connectors and disposable battery formats. This convergence is consolidating supplier ecosystems around interoperable components and compressing margins for manufacturers maintaining legacy connector inventories.
France's ANSM visibility directives for urban fleet operators are extending beyond minimum brightness thresholds into mandatory flash-pattern synchronization. The industrial consequence is a shift toward networked lighting systems with programmable firmware rather than fixed-mode hardware. Shared-bike operators in Paris and Lyon are responding by specifying connected rear lights with over-the-air update capability.
Aftermarket purchasing is fragmentating across specialty retail, direct brand channels, and mass-market e-commerce platforms. Traditional bicycle shop distribution faces disintermediation as enthusiast buyers research beam-pattern certifications independently and purchase through manufacturer websites. Germany exhibits the most pronounced channel shift, where StVZO-educated consumers bypass retail guidance entirely.
Bicycle Lights Market Segmentation
Segmentation in bicycle lighting reveals how regulatory mandates and rider use-cases split manufacturing investment across incompatible technical specifications. Suppliers must choose which certification burdens to absorb, as StVZO, CPSC, and ISO 6742-1 compliance each demands distinct optical engineering and testing outlays.
Product Type:
Capital intensity concentrates in front-facing illumination, where beam-pattern engineering and thermal management for high-lumen outputs dominate tooling budgets.
- Front Lights:LED arrays housed in aluminum casings with precision optics deliver 15 to 2000 lumens while managing heat dissipation. German StVZO certification requirements drive replacement demand as municipalities enforce KBA type approval for road-legal operation.
- Rear Lights:Compact polymer-housed signaling devices prioritize visibility angle and flash-pattern programming over raw output. French ANSM directives for urban fleet synchronization are accelerating adoption of networked, firmware-upgradable units in Paris and Lyon shared-bike systems.
- Reflectors:Passive optical components requiring minimal electronics investment.
- Combination Lights:Integrated front-rear systems with shared power management.
Front Lights absorb the bulk of installed capacity; Rear Lights are expanding most quickly.
Power Source:
Application context determines which power architecture riders accept, with urban commuters and touring cyclists presenting divergent willingness-to-pay for convenience versus reliability.
- USB Rechargeable:Lithium-ion cell packs with USB-C interfaces now dominate aftermarket upgrade cycles as Copenhagen and Amsterdam commuters abandon disposable formats. Cell density improvements enable StVZO-compliant outputs within compact housings that simplify handlebar mounting.
- Battery-Powered:Alkaline and coin-cell configurations persist in price-sensitive retail channels and emergency backup roles.
- Solar:Photovoltaic integration suits touring and remote-use cases where grid access is unreliable.
- Dynamo:Hub-generator systems with capacitive storage appeal to utility cyclists prioritizing elimination of charging logistics.
USB Rechargeable commands the steepest expansion trajectory as standardization eliminates proprietary connector fragmentation.
Mounting Type:
Rider positioning requirements and theft-risk exposure shape which mounting solutions attract development resources from accessory suppliers.
- Handlebar Mount:Clamp-based or bracket-fixed systems securing front lights to standard diameter bars. StVZO beam-pattern mandates require precise angular positioning, driving demand for tool-free adjustment mechanisms in German replacement markets.
- Seat Post Mount:Rear-facing clamp systems optimized for visibility angle compliance with minimum ground clearance requirements.
- Helmet Mount:Strap or adhesive fixtures positioning lights at rider eye level for enhanced conspicuity in dense urban traffic.
- Magnetic Mount:Quick-detach systems addressing theft prevention for parked bicycles in Amsterdam and Copenhagen city centers.
Handlebar Mount retains the largest production volume; Magnetic Mount is gaining share fastest as urban theft concerns intensify.
Brightness Level:
Regulatory minimums and battery runtime tradeoffs segment rider preferences across fixed-output and adaptive-mode systems.
- High:Continuous maximum output modes for unlit rural roads and trail riding, demanding substantial thermal design and cell capacity.
- Flashing:Intermittent patterns maximizing perceived brightness at lower power draw. French ANSM synchronization mandates are pushing fleet operators toward programmable flash sequences rather than fixed cadences.
- Medium:Balanced output for typical urban commuting with extended runtime.
- Low:Minimal illumination for battery conservation and group riding etiquette.
High brightness absorbs the bulk of premium-tier engineering investment; Flashing modes are climbing the fastest as visibility regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in East Asia while regulatory-driven consumption centers on Western Europe. German engineering standards and Japanese optical expertise anchor premium-tier production, with final assembly increasingly shifting to Vietnam and Taiwan for cost-sensitive segments.
Germany
KBA type-approval procedures for StVZO certification sustain replacement demand among commuter populations in Berlin and Munich. The EU Green Deal accelerates municipal enforcement of energy-efficient lighting mandates across federal states. Baden-Württemberg hosts precision optics workshops supplying beam-pattern engineering for premium front-light manufacturers.
United States
CPSC 16 CFR 1512 compliance requirements shape aftermarket purchasing in urban cycling corridors of Portland and San Francisco. Federal safety standards elevate testing burdens for import-dependent suppliers entering through West Coast distribution hubs. Colorado and Pacific Northwest trail networks sustain demand for high-lumen output systems among recreational riders.
Japan
METI efficiency guidelines and JIS standards govern domestic product specifications for Tokyo and Osaka metropolitan commuters. Cateye Co. Ltd. leverages established distribution relationships to maintain market presence. Nagoya-area electronics manufacturers supply LED driver components to regional lighting assemblers.
France
ANSM visibility directives for urban fleet operators mandate synchronized flash patterns in Paris and Lyon shared-bike systems. National regulations extend beyond minimum brightness into firmware-programmable lighting requirements. Île-de-France micromobility licensing frameworks are considering daytime running light mandates for dockless bicycle operators.
Netherlands
Amsterdam and Rotterdam municipal ordinances require ISO 6742-1 compliant lighting for road-legal bicycle registration. Dense urban cycling infrastructure sustains high-velocity replacement cycles for USB-rechargeable formats. Eindhoven-region electronics suppliers provide battery management components to assembly operations serving Benelux distribution channels.
Bicycle Lights Market Vendor Landscape
The competitive structure tilts toward specialty accessory manufacturers with established certification relationships. Incumbent players leverage StVZO and CPSC testing documentation as defensive moats against import competition. Three archetypes dominate: German-engineered premium specialists, Japanese optics-integrated suppliers, and Taiwan-based volume assemblers. M&A activity concentrates on battery management technology acquisitions, while geographic expansion targets direct-to-consumer e-commerce channels in cycling-dense urban markets.
Among Japanese and German fabricators, Cateye Co. Ltd., Lezyne, and Garmin Ltd. occupy distinct positioning archetypes within the premium tier. Cateye exemplifies the optics-integrated specialist model with domestic distribution depth. Lezyne represents the compact-form-factor engineering approach with in-house power management capabilities. Garmin anchors the technology-convergence segment where GPS integration differentiates navigation-visible lighting systems. Each occupies a defensible position against commodity competition through certification relationships and enthusiast brand equity.
| Leading Market Players |
|---|
| Cateye Co. Ltd. |
| Lezyne |
| Garmin Ltd. |
| Trek Bicycle Corporation |
| Cygolite |
| Knog Pty Ltd. |
| NiteRider Technical Lighting |
| Blackburn |
| Lupine Lighting Systems |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate and rare earth phosphors for LED arrays flow from concentrated upstream geographies through tiered pricing structures that separate StVZO-certified German-engineered units from mass-market alternatives. Certification investment and thermal management complexity anchor premium positioning, while USB-C standardization compresses margins on entry-level rechargeable formats.
Pricing Analysis
Certification-grade beam-pattern performance anchors value-based pricing tiers that separate road-legal StVZO units from recreational-grade alternatives. Price differentiation hinges on KBA type-approval documentation and aluminum thermal housing quality against polymer-based economy offerings. Cost compression in the standard tier intensifies as Taiwanese assemblers scale USB-rechargeable output, while enthusiast buyers in Germany exhibit lowest price sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Direct-to-specialty-retail channels handle enthusiast-grade demand, while mass-market e-commerce platforms absorb volume-tier distribution for price-sensitive segments. Manufacturing concentrates in Taiwan, Vietnam, and Guangdong province for final assembly, with precision optics workshops in Baden-Württemberg and Nagoya supplying beam-engineering components. Rare earth phosphors and lithium carbonate feedstocks draw from concentrated supplier geographies, exposing assemblers to commodity price volatility. Single-source vulnerability in LED driver ICs presents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where battery management technology and optical engineering talent represent the decisive upstream levers. Players securing in-house power electronics and photometric expertise build defensible margin positions against import competition.
For Market Incumbents: Deploy certification-documentation archives as competitive moats against emerging Asian suppliers lacking KBA and CPSC testing relationships. Deepen backward integration into lithium-ion cell management firmware to differentiate runtime performance. Acquire specialized photometric engineering talent in Germany and Japan to defend premium positioning as USB-C standardization erodes connector-based differentiation.
For New Entrants and Emerging Players: ANSM synchronization mandates in France open a window for firmware-programmable rear light specialists targeting Paris and Lyon fleet operators. Penetrate the micromobility daytime-running segment before dense cities formalize licensing requirements. Pursue direct-to-consumer e-commerce positioning in cycling-dense urban corridors to bypass established distributor markups.
For Investors and Strategic Acquirers: Distressed-cycle entries favor battery management technology specialists with existing StVZO laboratory relationships in Germany. Long-term viability centers on suppliers capable of spanning both premium certification-tier and volume USB-rechargeable production. Monitor municipal fleet procurement specifications for daytime-running mandates as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| StVZO Certification Investment | KBA type-approval documentation creates import barriers protecting incumbent margin structures. |
| Battery Management Acquisition | In-house lithium-ion firmware expertise differentiates runtime performance in compact form factors. |
| Direct-to-Consumer Channel Launch | Specialty cycling e-commerce platforms bypass distributor markups in Germany and Netherlands. |
| GPS-Lighting Convergence Development | Navigation-visible edge-lighting systems capture premium positioning among technology-integrated suppliers. |
| Micromobility Fleet Partnership | ANSM-compliant synchronized systems secure Paris and Lyon shared-bike operator specifications. |
Methodological Framework
Trade customs records, KBA type-approval databases, and EU Green Deal implementation documents formed the secondary backbone, supplemented by primary interviews with bicycle lighting product managers, StVZO testing laboratory directors, and specialty retail category buyers. Bottom-up assembly of segment-level volume estimates triangulated against top-down macroeconomic drivers across the analysis window.
Historical trendline analysis of replacement cycle velocities and regulatory enforcement intensity informed the projection framework. Segmentation modeling spanned product type, power source architecture, mounting configuration, and brightness mode across regional regulatory clusters. CAGRs derived from fitted growth curves incorporating lithium-ion density improvement trajectories and USB-C adoption S-curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery integration would alter the outlook for compact high-output designs. Forecasts reflect assumptions regarding municipal enforcement timelines and rare earth supply stability. Practitioners should monitor fleet procurement specifications and daytime-running mandate proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Air Suspension Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Grille Guard Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Headlight Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Collapsible Jerry Can Market