
 Grille Guard Market | 2026-2036
Grille Guard Market Size, Share, and Industry Trends Forecast 2026-2036
Grille Guard Market Foresight
Aluminum is restructuring grille guard economics as it displaces traditional steel in weight-sensitive applications. SteelCraft leverages vertical integration across stamping and powder-coating operations to sustain margin control. Ranch Hand anchors its position through specialized fabrication for heavy-duty truck platforms. Westin competes via channel dominance in big-box automotive retail and direct-to-consumer e-commerce.
A grille guard is a tubular or plate-frame protective barrier mounted to the front of trucks, SUVs, and vans, typically fabricated from steel, aluminum, or stainless steel with wall thicknesses between 0.120 and 0.250 inches, designed to absorb impact energy and protect radiators, headlights, and grille assemblies from collision damage. Full-width configurations dominate aftermarket revenue owing to their universal fitment across major truck platforms, while modular designs represent the fastest-expanding category as fleet buyers prioritize field-repairable components and customizable lighting integration. Steel retains the largest material share by volume, though aluminum is capturing premium positioning where fuel economy regulations and payload optimization drive specification changes.
NHTSA front-impact compatibility guidelines and EPA fuel efficiency mandates jointly shape product design requirements, forcing manufacturers to reconcile protective geometry with aerodynamic drag coefficients and pedestrian impact standards. The Department of Transportation's Federal Motor Carrier Safety Administration influences commercial fleet adoption through vehicle maintenance and crashworthiness protocols. Stakeholders must monitor evolving state-level bumper height statutes and insurance industry loss-cost data to anticipate specification shifts before design cycles lock.
Market Dynamics
NHTSA pedestrian safety standards are forcing manufacturers to redesign energy-absorbing geometries while commercial fleets simultaneously demand heavier-duty protection for collision repair cost containment. This regulatory-commercial tension is restructuring product development priorities across the value chain.
Growth Catalysts
- Fleet collision cost reduction:Commercial trucking operators in the United States are standardizing grille guard procurement to minimize radiator and headlight damage downtime. Texas-based fleet managers report measurable repair cost compression from full-width configurations.
- EPA fuel efficiency mandates:Lightweight aluminum specification is accelerating across weight-sensitive applications where payload optimization intersects with aerodynamic drag requirements. California and Michigan fleets lead this material transition.
- FMCSA maintenance protocols:The Federal Motor Carrier Safety Administration's vehicle crashworthiness guidelines are embedding grille guards into preventive maintenance schedules for interstate carriers.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs fluctuate with energy market swings, compressing margin predictability for stamped-steel fabricators dependent on commodity sourcing.
- Mounting geometry standardization gaps:OEM bumper variance across truck platforms forces SKU proliferation, inflating inventory carrying costs for aftermarket distributors serving multiple model years.
- Pedestrian impact compliance friction:NHTSA front-impact compatibility guidelines impose design constraints that conflict with traditional rigid-bar protection philosophies, extending engineering validation cycles.
Strategic Opportunities
- Modular field-repairable systems:Component-level replacement architectures are opening fleet procurement contracts previously locked into welded single-piece designs. Texas municipal fleets pilot this specification.
- LED integration white space:Lighting-embedded grille guards are capturing premium positioning as auxiliary illumination demand grows among off-road and work-truck segments in California.
- State-level bumper height harmonization:Pending legislative alignment across Michigan, Texas, and California would reduce regulatory fragmentation, enabling national SKU strategies for multi-state fleet operators.
Industry Challenges
- Welding automation skill scarcity:Tubular frame fabrication requires certified aluminum TIG operators, a labor pool concentrated in legacy steel-centric manufacturing regions with limited retraining infrastructure.
- Dual certification timeline compression:Products must simultaneously satisfy NHTSA pedestrian safety validation and SAE J684 towing equipment standards, forcing parallel testing tracks that extend launch windows.
- Legacy inventory obsolescence:Pre-2020 steel-intensive stock faces accelerated write-down risk as aluminum designs achieve fleet specification dominance in fuel-economy-sensitive segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grille Guard Market |
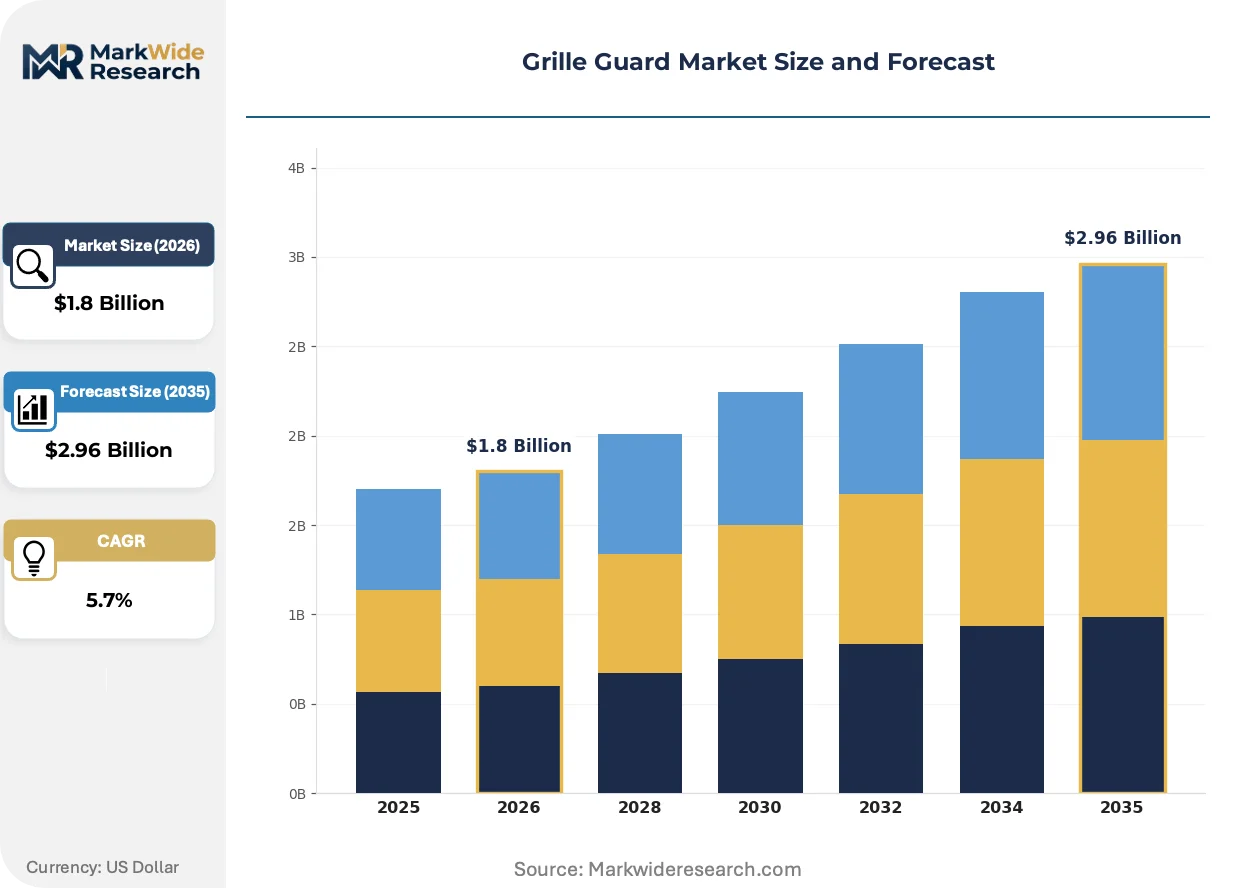
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Width, Modular, Custom Fit, Bolt-On Material: Steel, Aluminum, Plastic, Stainless Steel Vehicle Type: Truck, SUV, Van, Off-Road Vehicle Installation Method: Welded, Clamp-On, Universal Fit, Direct Bolt-On |
| Companies Covered | SteelCraft, Tuff-Bar, CURT Manufacturing LLC, Ranch Hand, Westin, Go Rhino, Onki Corporation, Iron Cross Automotive, Armordillo USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grille Guard Market Shifts & Advancements
Material substitution and regulatory compliance geometry are converging to reshape product architecture, while distribution channels fragment between direct-to-consumer digital platforms and consolidated fleet procurement.
Aluminum tubular construction is decentralizing protective equipment specification away from traditional steel dominance. Fleet buyers in California and Michigan are specifying 0.120-inch wall aluminum for weight-class-sensitive applications where fuel economy credits offset material premiums. This shift is decentralizing manufacturing concentration from legacy steel-stamping regions toward facilities with captive aluminum extrusion and heat-treatment capability.
NHTSA front-impact compatibility guidelines are mandating energy-absorbing mount designs that detach or deform under pedestrian contact loads. Manufacturers must now engineer crumple zones into previously rigid structures, compressing the protective envelope while maintaining radiator clearance for cooling airflow. Heavy-duty commercial platforms face the steepest redesign burden as they balance FMCSA crashworthiness expectations against pedestrian safety compliance.
Fleet procurement is consolidating through direct manufacturer relationships that bypass traditional jobber distribution. Large multi-state operators in Texas are negotiating volume contracts with fabrication houses for standardized specifications across mixed-model truck pools. This channel compression is squeezing regional distributors dependent on fragmented retail walk-in traffic and accelerating price transparency through digital quoting platforms.
Grille Guard Market Segmentation
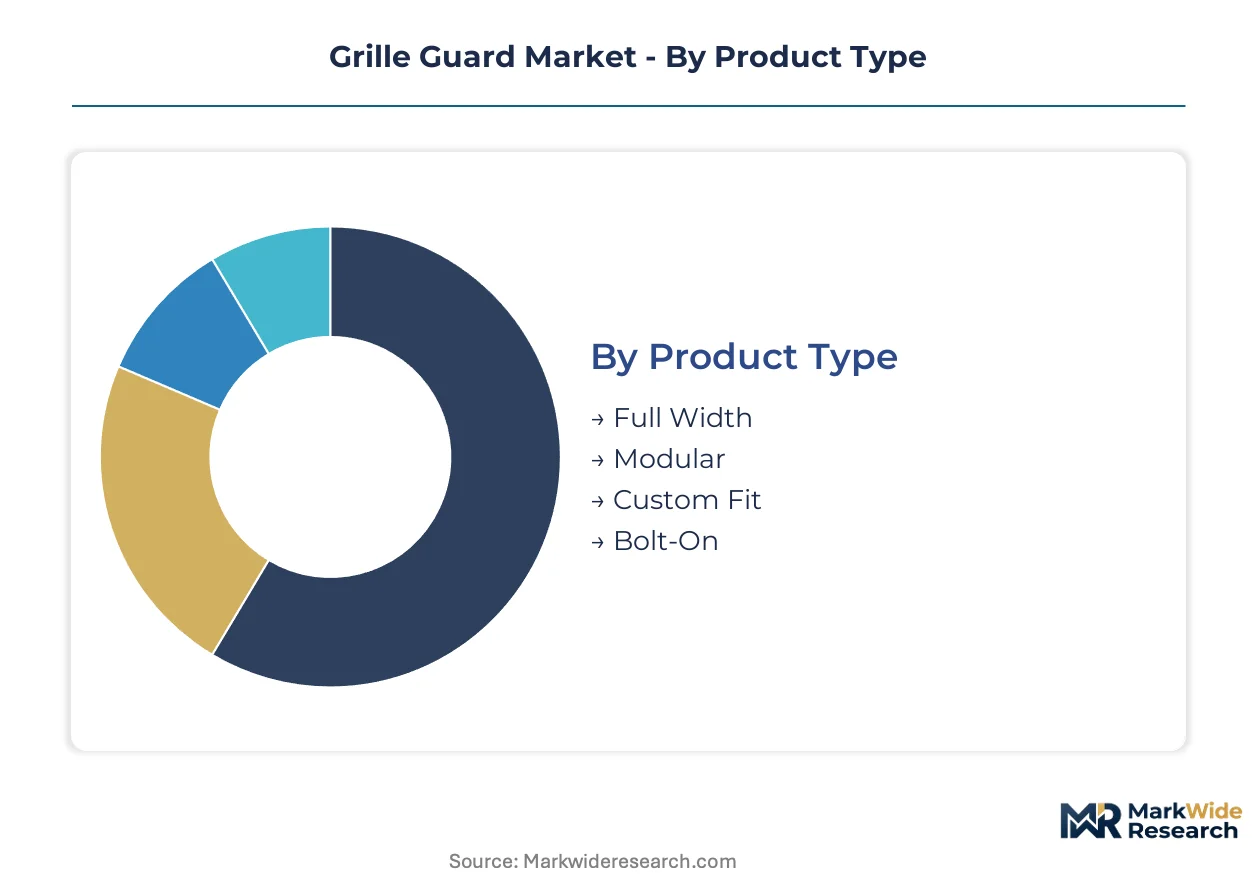
Grille guard procurement patterns diverge sharply across product architecture, material specification, and vehicle platform compatibility. Fleet buyers and individual owners prioritize different attribute bundles, forcing manufacturers to maintain parallel development tracks for collision protection systems.
Product Type:
Standalone full-width configurations dominate aftermarket volume through universal fitment across major truck platforms, while embedded modular systems integrate with factory bumper geometry for OEM-aligned specification.
- Full Width:Single-piece tubular or plate-frame barriers spanning the entire front fascia, typically 0.120 to 0.250 inch wall thickness. Texas and California fleet operators standardize this configuration for maximum radiator and headlight protection across mixed-model truck pools, accepting weight penalties for repair cost containment.
- Modular:Component-level architectures enabling field replacement of damaged sections without full guard removal. Municipal fleets in Michigan pilot this specification for reduced downtime, with individual tube or wing sections detachable via bolted junctions rather than welded joints.
- Custom Fit:Platform-specific geometries matching individual OEM bumper contours and mounting point patterns.
- Bolt-On:Pre-drilled configurations utilizing existing factory attachment locations without chassis modification.
Full Width leads volumes today; Modular is gaining share fastest.
Material:
Cost tier stratification separates premium lightweight specifications from commodity steel dominance, with fuel economy regulations accelerating aluminum penetration in weight-sensitive fleet applications.
- Steel:Hot-rolled and cold-formed carbon steel grades dominate volume through cost efficiency and impact absorption capacity. Stampers in legacy manufacturing regions maintain steel-centric operations despite price volatility from energy market swings.
- Aluminum:6061-T6 and 6063-T5 extruded tubing specified where payload optimization intersects with EPA fuel efficiency mandates. California and Michigan fleets absorb material premiums to capture aerodynamic and weight-class benefits.
- Plastic:Polymer composite guards for aesthetic protection and pedestrian impact compliance in urban delivery van applications.
- Stainless Steel:304 and 316 grades for corrosion resistance in coastal or chemical exposure environments.
Steel retains volume leadership; Aluminum is climbing the fastest.
Vehicle Type:
Application severity determines protection level specification, with commercial trucking platforms demanding heavier-duty architectures than passenger SUV installations.
- Truck:Heavy-duty platforms from Class 2b through Class 8 requiring FMCSA crashworthiness compliance. Full-width steel configurations anchor fleet procurement for interstate carriers prioritizing collision repair cost containment.
- SUV:Unibody and body-on-frame sport utility vehicles where aesthetic integration competes with protection geometry. Texas and California retail channels drive accessory volume for personal use and light commercial applications.
- Van:Commercial delivery and passenger transport platforms with constrained front overhang limiting guard depth.
- Off-Road Vehicle:Modified trucks and SUVs for recreational terrain use requiring winch mount integration and auxiliary lighting attachment points.
Truck anchors absolute volumes; Off-Road Vehicle shows steepest expansion trajectory.
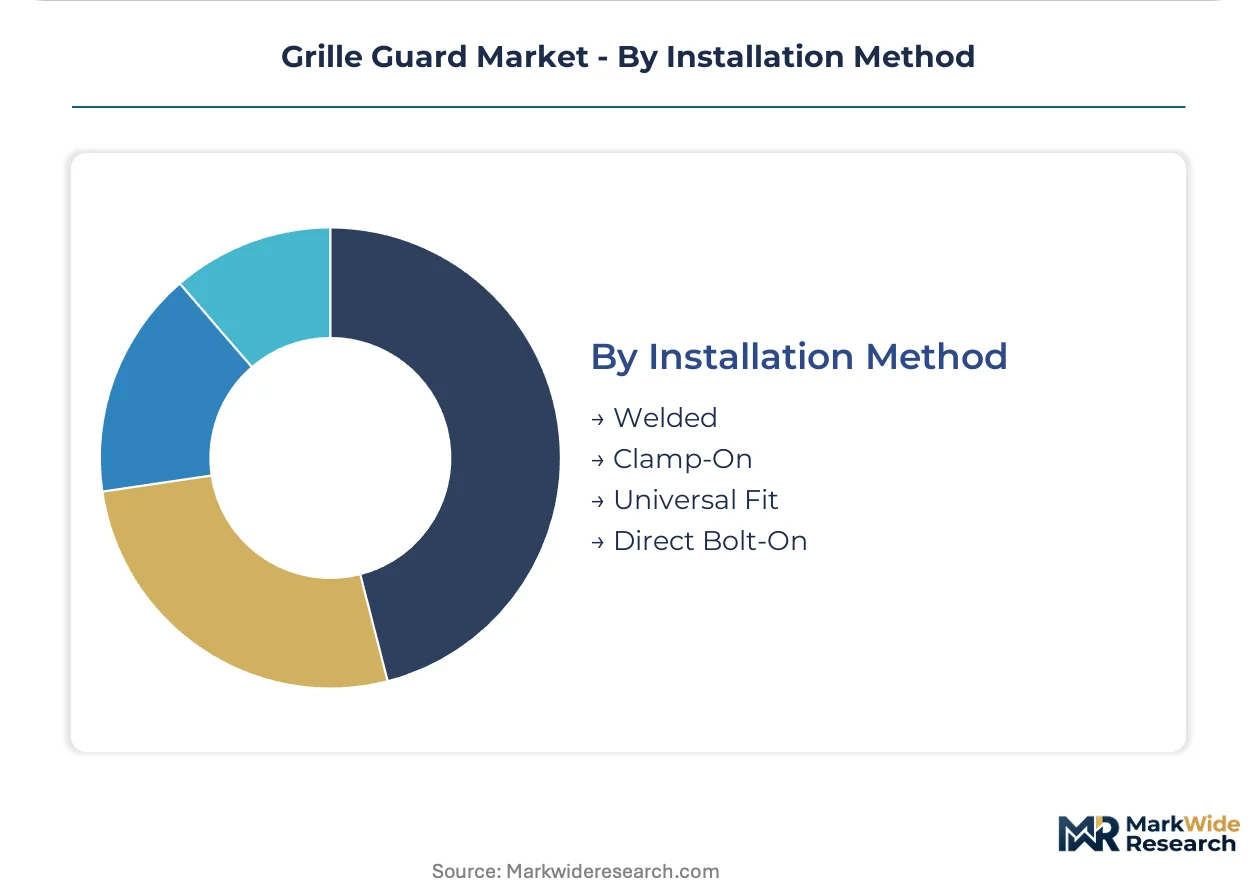
Installation Method:
Customer capability and warranty preservation dictate attachment complexity, with professional installation requirements filtering retail channel strategies.
- Welded:Permanent frame integration for maximum structural integrity in severe-service commercial applications. Certified aluminum TIG operators concentrate in legacy steel-centric manufacturing regions with limited retraining infrastructure.
- Clamp-On:Non-drilling attachment utilizing frame rail clamps for vehicle preservation. Personal use buyers in California prefer this method for lease vehicle compatibility.
- Universal Fit:Adjustable width and height configurations spanning multiple model years and manufacturers.
- Direct Bolt-On:OEM mounting point utilization without secondary drilling or welding.
Welded dominates commercial specification; Direct Bolt-On expands most quickly in consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas anchors the global grille guard demand concentration through its outsized commercial trucking fleet density and pickup accessory culture. State-level bumper height statutes and municipal fleet procurement standards create localized specification requirements that ripple through national distribution networks.
United States
Commercial trucking operators across interstate corridors standardize grille guard procurement to minimize collision repair downtime. NHTSA pedestrian safety standards and FMCSA crashworthiness protocols jointly shape product validation requirements. Texas, California, and Michigan account for disproportionate pickup and SUV accessory volumes, with Texas-based fleet managers driving full-width configuration adoption.
Canada
Resource extraction industries in Alberta and British Columbia specify heavy-duty protection for severe-service operating conditions. Transport Canada's Motor Vehicle Safety Standards align with NHTSA front-impact compatibility guidelines, reducing regulatory friction for cross-border fleet operators. Ontario's automotive supplier cluster supports aftermarket distribution infrastructure serving Prairie Provinces commercial fleets.
Mexico
Manufacturing export corridors linking Nuevo León and the Bajío Region generate commercial vehicle protection demand from logistics operators. Mexico's Secretariat of Economy automotive sector programs influence supplier localization decisions. Northern Border States concentrate fleet maintenance facilities serving maquiladora supply chain trucking.
Germany
Commercial van platforms for urban delivery applications drive pedestrian-impact-compliant guard specification. KBA type-approval requirements impose geometric constraints distinct from North American crashworthiness philosophies. Baden-Württemberg automotive engineering clusters support design validation for export-oriented manufacturers.
Australia
Rural mining and agricultural applications in Western Australia and Queensland sustain demand for animal-impact protection systems. The country's national automotive regulator enforces ADR compliance frameworks for frontal protection devices. New South Wales and Victoria distribute aftermarket volume through regional 4x4 accessory retail networks.
Grille Guard Market Competitive Landscape
Portfolio diversification dominates the current landscape as fabricators extend beyond traditional steel stamping into aluminum extrusion and lighting integration. The vendor base spans vertically integrated metalformers, specialized tubular frame shops, and diversified automotive accessory conglomerates. Three archetypes anchor competitive positioning: legacy steel stampers with captive coating operations, aluminum-focused lightweighting specialists, and diversified accessory platforms leveraging retail channel density. Geographic expansion into fleet-direct procurement and backward integration into aluminum extrusion represent the dominant competitive moves reshaping supply structure.
Among North American metalformers, SteelCraft and Ranch Hand occupy distinct positioning archetypes, with the former representing vertically integrated stamping-to-coating operations and the latter exemplifying specialized heavy-duty truck platform focus. Westin anchors the diversified accessory platform tier through big-box retail and direct-to-consumer channel density. These three fabricators collectively illustrate the competitive tension between material specialization, vertical scope, and distribution architecture that defines current market structure.
| Leading Market Players |
|---|
| SteelCraft |
| Tuff-Bar |
| CURT Manufacturing LLC |
| Ranch Hand |
| Westin |
| Go Rhino |
| Onki Corporation |
| Iron Cross Automotive |
| Armordillo USA |
| Others |
Supply & Pricing Matrix
Aluminum-steel specification bifurcation separates premium lightweight designs from commodity steel configurations, with this material divergence driving parallel supply chain investments in extrusion capacity alongside legacy stamping infrastructure. Fleet procurement contracts in California and Michigan absorb aluminum premiums to capture fuel economy credits, while Texas-based commercial operators prioritize steel durability despite commodity price swings.
Pricing Analysis
Hot-rolled coil volatility passes through to stamped-steel fabricators with 60-90 day lag structures, forcing margin compression when energy markets spike. Three-tier pricing structure across premium aluminum, mid-grade steel, and economy bolt-on configurations stratifies the aftermarket, with NHTSA pedestrian safety certification adding cost premiums to compliant designs. Pricing pressure stems from SKU proliferation driven by OEM bumper variance across truck platforms. Fleet buyers exhibit lowest price sensitivity due to collision cost containment calculus, while retail walk-in customers prioritize economy bolt-on options.
Supply Chain Analysis
Dual-sourcing requirements from multi-state fleet operators mandate qualified suppliers across both aluminum extrusion and steel stamping capabilities, preventing single-source dependency. Manufacturing concentrates in the United States, Mexico, and Canada, with Ontario automotive clusters supporting aftermarket distribution infrastructure. Raw material dependencies center on hot-rolled steel coil, 6061-T6 aluminum billet, and powder-coating chemicals. Tariff exposure on Mexican-sourced components creates structural risk for cross-border supply chains. Distribution runs through direct manufacturer relationships consolidating fleet procurement, alongside big-box retail and e-commerce channels serving fragmented consumer demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate where Texas fleet density meets Michigan aluminum specification leadership, with regulatory divergence between NHTSA pedestrian safety mandates and FMCSA crashworthiness protocols creating cost-structure differentiation.
For Market Incumbents: Cement market position through captive aluminum extrusion investments and NHTSA pre-certification of modular field-repairable architectures. Aluminum TIG welding skill scarcity threatens production scaling for lightweight product lines. Backward integration into heat-treatment operations secures margin control against commodity volatility. For New Entrants and Emerging Players: Capture municipal fleet procurement in Michigan and Texas through LED-integrated modular designs, the most penetrable white-space segment. Direct-to-consumer digital platforms offer lower channel entry costs than consolidated fleet-direct relationships. Target off-road vehicle accessory retailers for initial volume traction. For Investors and Strategic Acquirers: Consolidation pressure builds where aluminum fabrication capability concentrates in legacy steel-centric manufacturing regions with limited retraining infrastructure. Long-term viability favors vertically integrated metalformers spanning stamping, extrusion, and powder-coating operations. Watch NHTSA pedestrian safety standard finalization as inflection indicator for compliant design investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Extrusion Capacity Expansion | Captures EPA fuel efficiency mandate tailwinds in California and Michigan fleet procurement. |
| NHTSA Pre-Certification Investment | Compresses launch windows for pedestrian safety compliant geometries before design cycles lock. |
| Modular Field-Repairable Architecture | Opens municipal fleet contracts previously locked into welded single-piece guard specifications. |
| LED Integration Partnership | Targets premium positioning in California off-road and work-truck auxiliary illumination demand. |
| Direct Fleet Procurement Channel | Bypasses traditional jobber distribution squeezing regional distributors dependent on retail walk-in traffic. |
Research Methodology
Direct dialogue with fleet procurement managers, aftermarket distribution executives, aluminum fabrication specialists, and NHTSA regulatory affairs consultants grounded the qualitative foundation. Secondary validation drew from FMCSA vehicle maintenance protocol filings, EPA fuel efficiency mandate documentation, state-level bumper height statute databases, and commercial trucking insurance loss-cost data. Bottom-up and top-down triangulation cross-checked volume estimates against material consumption patterns and fleet penetration rates.
Bottom-up modeling anchored projections across product type, material specification, vehicle platform, and installation method dimensions, with regional regulatory clusters overlaying geographic splits. CAGRs derived from trend extrapolation of aluminum penetration rates, fleet standardization timelines, and pedestrian safety compliance adoption curves. Aluminum-steel price ratio forecasts and commercial vehicle production schedules fed industry-specific inputs.
Steel price volatility, NHTSA regulatory finalization delays, and aluminum welding labor availability are the dominant revision risks to the outlook. Deviation in pedestrian safety standard implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Sideloaders Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Hydrostatic Transmission Market