
 Intelligent Bus Shelter Market | 2026-2036
Intelligent Bus Shelter Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Bus Shelter Market Insights
Chinese smart city infrastructure spending is restructuring supplier dynamics across the intelligent bus shelter value chain. Kaich Smart City Facilities leverages its domestic manufacturing footprint to anchor municipal contracts across tier-one cities. JCDecaux competes through its global out-of-home advertising integration, while CIVIQ Smartscapes differentiates via North American digital kiosk specialization.
An intelligent bus shelter integrates IoT sensors, real-time passenger information systems, and environmental controls within a weatherproof urban structure, typically operating on 110-240V AC or photovoltaic supply with IP54+ enclosure ratings. These installations serve dual commercial purposes: enhancing public transit accessibility for commuters and generating advertising revenue streams for operators. Solar-powered shelters lead product type adoption where grid independence reduces installation costs, while cloud platforms dominate technology deployment by enabling centralized fleet management across distributed shelter networks. Interactive displays command premium positioning in transit hubs where dwell times support engagement metrics.
The EU Green Deal and F-Gas Regulation shape European procurement by mandating low-carbon materials and refrigerant-free climate systems, while China's GB standards and MIIT directives govern domestic connectivity protocols and data security requirements. In the United States, FCC certification and ADA accessibility compliance create multi-layered approval pathways for foreign suppliers. Stakeholders must monitor evolving cybersecurity mandates for connected transit infrastructure and assess backward integration into solar panel and sensor manufacturing to secure margin pools.
Market Dynamics
Municipal transit agencies are consolidating shelter procurement into multi-city framework agreements, compressing vendor margins while favoring suppliers with integrated IoT platforms and captive solar manufacturing capabilities.
Growth Catalysts
- EU Green Deal procurement mandates:European cities now require lifecycle carbon assessments for shelter materials, accelerating specifications for photovoltaic canopies and refrigerant-free climate systems.
- Real-time passenger information integration:Transit authorities in Germany and France are bundling shelter deployments with fleet management platforms, creating pull-through demand for cloud-connected sensor arrays.
- Out-of-home advertising digitization:Programmatic ad insertion capabilities are converting static shelters into revenue-generating media assets, shifting operator business models from cost centers to profit contributors.
Market Restraints
- Polysilicon supply concentration:Solar panel input costs fluctuate with Chinese ingot production quotas, exposing shelter manufacturers to margin compression during supply tightening.
- Cellular module certification delays:FCC Part 15 and CE RED testing timelines for embedded 5G connectivity extend deployment schedules by four to eight months in North American and European markets.
- Steel enclosure price volatility:Galvanized steel framing represents thirty to forty percent of bill-of-materials costs, with regional mill capacity constraints driving input unpredictability.
Strategic Opportunities
- India smart city mission expansion:Municipal corporations in Pune, Surat, and Coimbatore are issuing tenders for integrated transit infrastructure under the country's urban renewal programs.
- Edge AI convergence with environmental sensing:On-device inference engines are enabling predictive maintenance and air quality monitoring without cloud dependency, opening premium pricing tiers.
- Utility-backed energy-as-a-service models:Power purchase agreements with municipal utilities are eliminating upfront solar capex for transit agencies, accelerating adoption in budget-constrained municipalities.
Industry Challenges
- Embedded systems cybersecurity certification:IEC 62443 compliance for industrial IoT networks requires specialized firmware auditing capabilities that shelter OEMs must build or acquire.
- Legacy transit signal protocol integration:Proprietary AVL and CAD systems in aging municipal fleets demand custom middleware development, inflating deployment engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Bus Shelter Market |
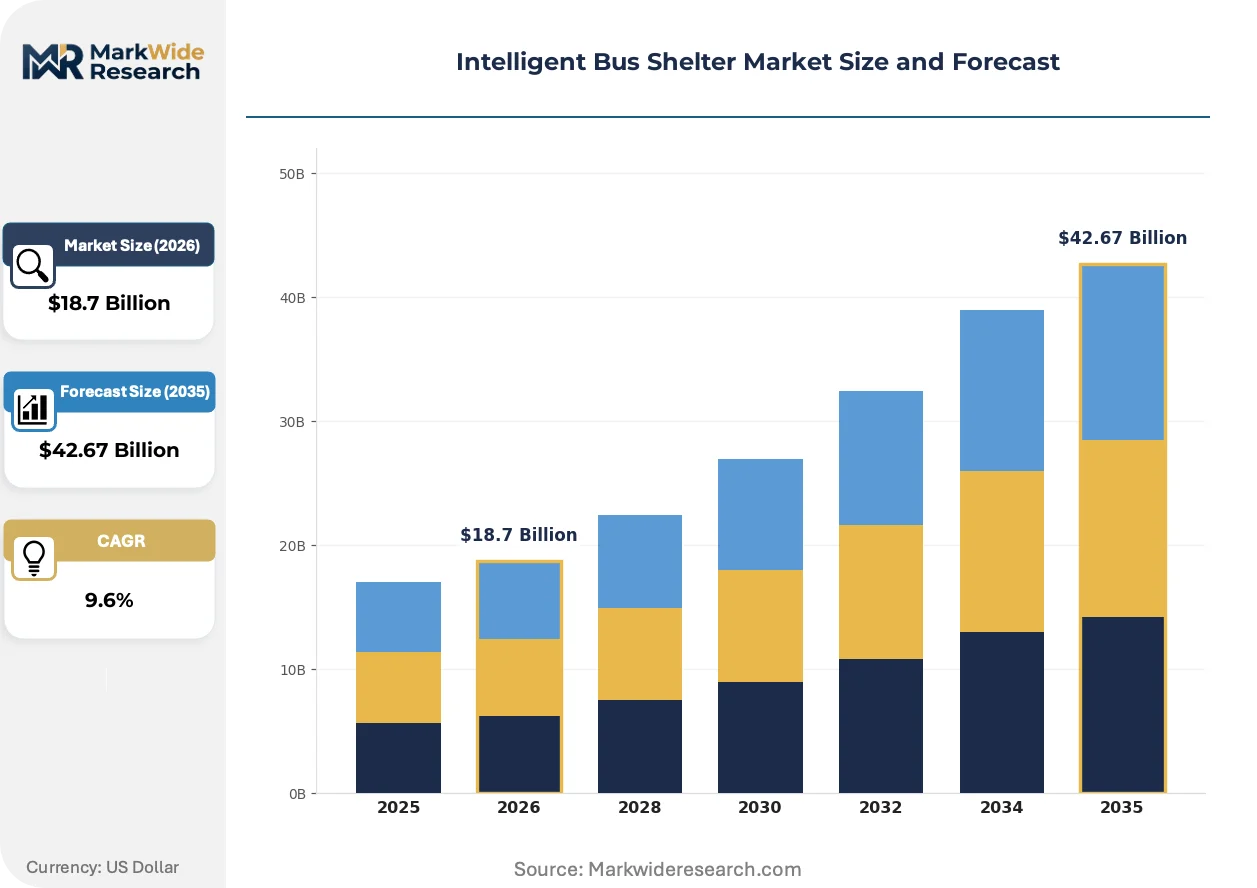
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $42.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Displays, Solar-Powered Shelters, Digital Signage, Wi-Fi Stations Technology: IoT Sensors, Mobile Connectivity, Cloud Platforms, Data Analytics End User: Public Transport Authorities, City Officials, Advertising Agencies, Commuters Installation Type: Street-Level Installations, Transit Hubs, Park-and-Ride Facilities, Remote Locations |
| Companies Covered | Outfront Media, Ampron, JCDecaux, Shanghai ZEMSO Electronic Technology, Kaich Smart City Facilities, Clear Channel Outdoor, CIVIQ Smartscapes, Hummax Display Systems, PARTTEAM & OEMKIOSKS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Bus Shelter Market Trends and Innovations
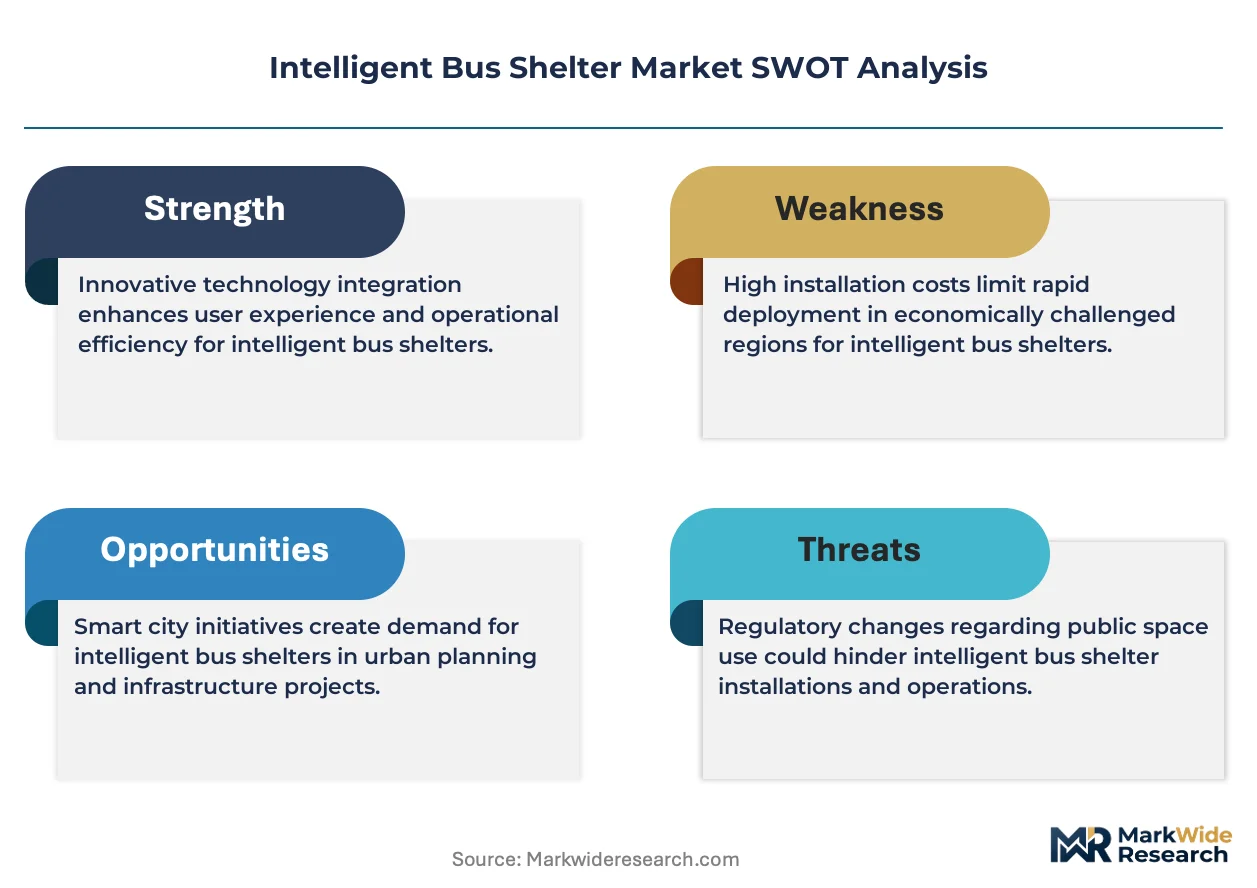
Digital infrastructure convergence is redefining shelter architecture from passive weather protection to active data collection nodes, with implications for component modularity, energy autonomy, and procurement contracting structures.
Photovoltaic canopy systems with bifacial cell technology and integrated microinverters are modularizing power generation subsystems, allowing transit agencies to scale energy capacity independently of structural footprints. German operators are piloting 800W peak-output configurations that eliminate grid connections entirely. This modularity is compressing installation timelines from weeks to days while reducing electrical contractor dependencies.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in climate-controlled shelters, forcing specification shifts toward thermoelectric cooling and phase-change materials. Manufacturers serving French and Belgian markets are redesigning HVAC subassemblies to eliminate compressor-based systems. This regulatory pressure is fragmenting product portfolios as regional variants diverge from global platforms.
Framework contracting is consolidating buyer power as regional transit authorities pool shelter procurement across multiple municipalities. The Île-de-France Mobilités aggregation model in France is displacing single-city tenders, favoring vendors with balance-sheet capacity to finance multi-year deployment schedules. This concentration is visible across European urban corridors where transit budgets face sustained fiscal pressure.
Intelligent Bus Shelter Market Segmentation
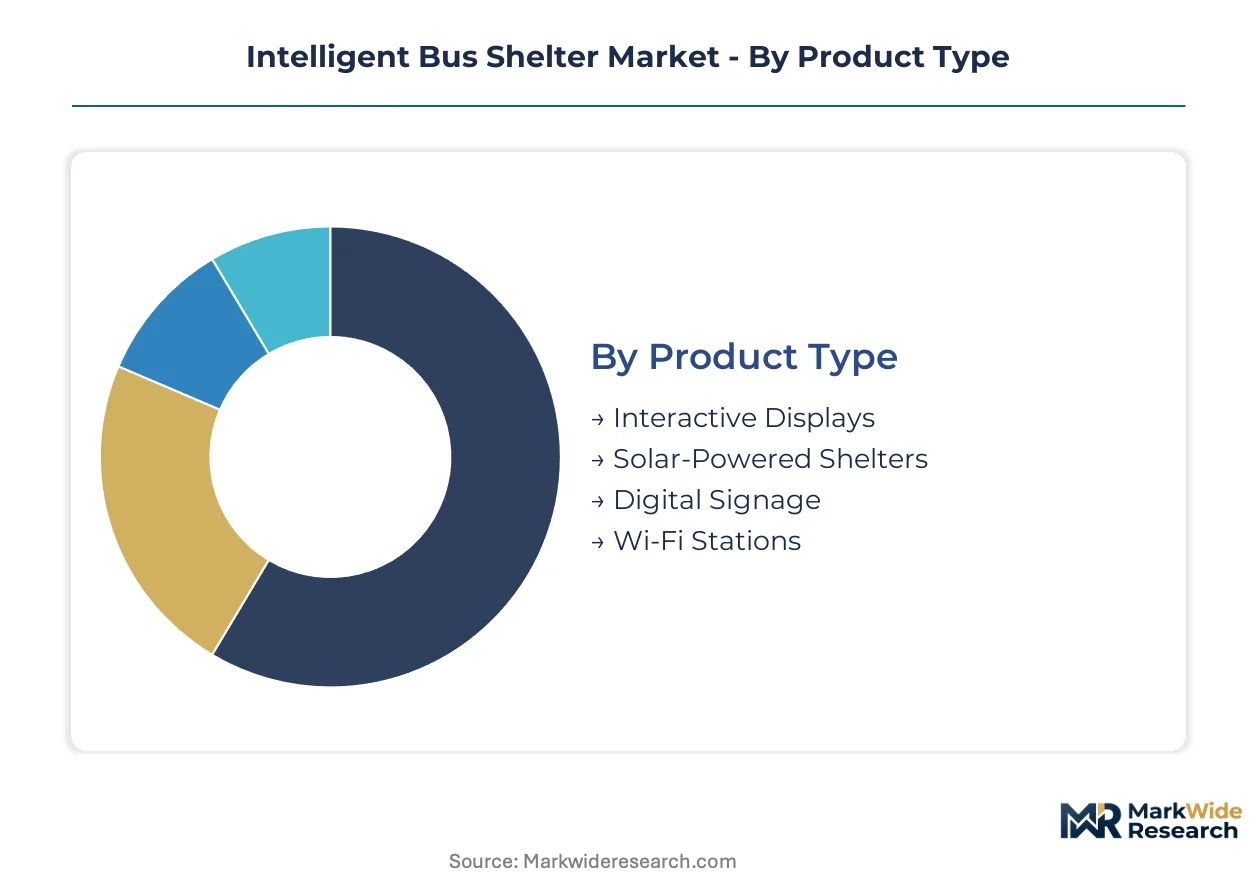
Intelligent bus shelter procurement decisions hinge on energy autonomy requirements, connectivity specifications, and revenue-generation potential. Municipal buyers evaluate total cost of ownership across photovoltaic integration, sensor density, and advertising monetization capabilities.
Product Type:
Transit agencies prioritize energy independence and passenger engagement depth when selecting shelter configurations.
- Solar-Powered Shelters:Photovoltaic canopy systems with bifacial cell technology and integrated microinverters eliminate grid connection dependencies. German operators are piloting 800W peak-output configurations that compress installation timelines from weeks to days while reducing electrical contractor dependencies. Demand concentrates in European corridors where EU Green Deal mandates accelerate refrigerant-free climate specifications.
- Interactive Displays:Touchscreen interfaces with real-time transit data, wayfinding, and emergency communication capabilities command premium positioning. These installations target transit hubs in China where Kaich Smart City Facilities and Shanghai ZEMSO Electronic Technology anchor domestic manufacturing capacity, driven by extended passenger dwell times that support engagement metrics.
- Digital Signage:Programmatic advertising screens convert static structures into revenue-generating media assets.
- Wi-Fi Stations:Connectivity hubs with captive portal authentication serve digital inclusion mandates in underserved corridors.
Solar-Powered Shelters lead on scale; Interactive Displays lead on momentum.
Technology:
Platform architecture choices determine operational scalability and cybersecurity exposure for connected shelter networks.
- Cloud Platforms:Centralized fleet management systems enable remote monitoring, firmware updates, and predictive maintenance across distributed shelter networks. Transit authorities in Germany and France are bundling shelter deployments with these platforms, creating pull-through demand for sensor arrays. Municipal procurement in France favors vendors with balance-sheet capacity to finance multi-year deployment schedules under framework contracting models.
- IoT Sensors:Environmental monitoring, occupancy detection, and air quality sensing modules generate operational data streams. Edge AI convergence is enabling on-device inference for predictive maintenance without cloud dependency, opening premium pricing tiers in budget-constrained municipalities.
- Mobile Connectivity:Embedded 5G and LTE modules face FCC Part 15 and CE RED certification timelines extending deployment schedules.
- Data Analytics:Passenger flow optimization and advertising performance measurement tools complete the technology stack.
Cloud Platforms anchor current procurement volumes; IoT Sensors are climbing the fastest as edge computing capabilities mature.
End User:
Budget authority and revenue capture mechanisms vary sharply across stakeholder types.
- Public Transport Authorities:Municipal agencies consolidate procurement into multi-city framework agreements that compress vendor margins while favoring integrated IoT platforms. The Île-de-France Mobilités aggregation model in France exemplifies this concentration, displacing single-city tenders across European urban corridors.
- Advertising Agencies:Out-of-home media operators seek programmatic ad insertion capabilities that shift shelter business models from cost centers to profit contributors. JCDecaux competes through global advertising integration, converting static inventory into addressable media assets.
- City Officials:Elected administrators prioritize smart city visibility and constituent service metrics.
- Commuters:End passengers drive implicit demand through accessibility expectations and digital service preferences.
Public Transport Authorities dominate contract value; Advertising Agencies are gaining share fastest as monetization models mature.
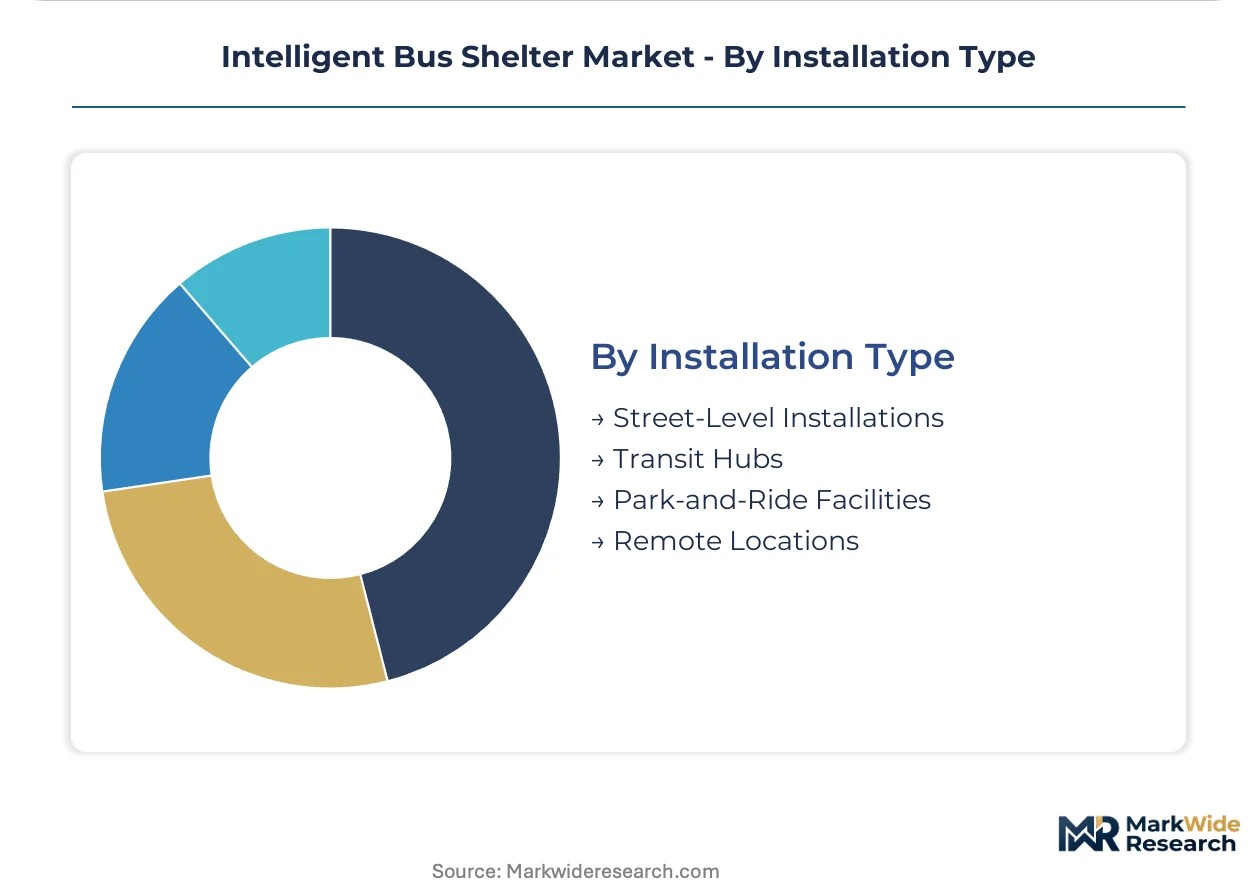
Installation Type:
Site constraints and passenger density determine structural specifications and connectivity requirements.
- Transit Hubs:High-density interchange points with extended dwell times support premium interactive display deployments and advertising revenue optimization. These locations in China and Germany command the highest per-unit investment given passenger throughput metrics.
- Street-Level Installations:Curbside shelters along arterial corridors represent the volume base, with solar-powered configurations reducing installation complexity where grid access is limited.
- Park-and-Ride Facilities:Suburban multimodal connection points serve commuter catchment areas with lower sensor density requirements.
- Remote Locations:Off-grid installations in rural or peripheral zones demand maximum energy autonomy and satellite connectivity backup.
Street-Level Installations lead on deployment volume; Transit Hubs lead on revenue intensity per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as shelter OEMs migrate production toward jurisdictions with streamlined connectivity certification and renewable energy incentives. Cost-of-compliance gaps between European F-Gas enforcement and Asian solar supply chain density are accelerating this geographic rebalancing.
Germany
Transit authorities in Berlin and Hamburg are bundling shelter deployments with fleet management platforms under the EU Green Deal lifecycle carbon mandates. The KBA enforces refrigerant-free climate system specifications that favor thermoelectric cooling architectures. Bavarian industrial clusters around Munich anchor photovoltaic canopy manufacturing for 800W peak-output configurations.
China
MIIT directives governing domestic connectivity protocols and data security requirements are consolidating procurement around state-affiliated platform providers. GB standards mandate encryption modules for passenger information systems. The Yangtze River Delta manufacturing corridor hosts Kaich Smart City Facilities and Shanghai ZEMSO Electronic Technology production bases serving tier-one municipal contracts.
France
The Île-de-France Mobilités aggregation model is displacing single-city tenders across Greater Paris and Lyon urban corridors. ANSM and CNIL oversight extends to passenger data handling in connected shelter networks. Auvergne-Rhône-Alpes transit operators are piloting edge AI inference engines for predictive maintenance without cloud dependency.
United States
FCC Part 15 certification timelines for embedded 5G connectivity extend deployment schedules by four to eight months in California and Texas transit corridors. ADA accessibility compliance creates multi-layered approval pathways for foreign suppliers. The Pacific Northwest and Northeast Corridor concentrate pilot programs for utility-backed energy-as-a-service models eliminating upfront solar capex.
India
Municipal corporations in Pune, Surat, and Coimbatore are issuing tenders for integrated transit infrastructure under the Smart Cities Mission. BIS certification requirements for electronic components create localization pressure on foreign OEMs. The Delhi-NCR and Maharashtra industrial zones are emerging as assembly hubs for solar-powered shelter subsystems.
Intelligent Bus Shelter Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent digital infrastructure spaces with specialized sensor integration. The vendor base stratifies across three maturity levels: global out-of-home advertising conglomerates with captive shelter operations, regional transit infrastructure specialists with captive solar manufacturing, and modular electronics fabricators supplying component subsystems. Dominant competitive moves include framework contracting aggregation to secure multi-year municipal deployments and backward integration into photovoltaic cell production to secure margin pools against polysilicon volatility.
Within the advertising-integrated tier, JCDecaux represents the global out-of-home archetype with transit infrastructure embedded within media network operations. Kaich Smart City Facilities and Shanghai ZEMSO Electronic Technology occupy positions within the China-based manufacturing cluster serving domestic smart city mandates. CIVIQ Smartscapes exemplifies the North American digital kiosk specialization model. These three anchors illustrate divergent strategic vectors: media monetization, state-contract manufacturing scale, and modular display technology.
| Leading Market Players |
|---|
| Outfront Media |
| Ampron |
| JCDecaux |
| Shanghai ZEMSO Electronic Technology |
| Kaich Smart City Facilities |
| Clear Channel Outdoor |
| CIVIQ Smartscapes |
| Hummax Display Systems |
| PARTTEAM & OEMKIOSKS |
| Others |
Pricing and Supply Chain Analysis
Polysilicon ingot pricing volatility cascades through photovoltaic canopy manufacturing into three-tier pricing structures across premium, standard, and economy shelter configurations, compressing margins for non-integrated assemblers while rewarding suppliers with captive solar cell production in China's Yangtze River Delta corridor.
Pricing Analysis
Distributor markups on embedded IoT sensor modules and cellular connectivity subsystems widen spreads between direct municipal procurement and advertising-network-integrated deployments. Price differentiation hinges on GB standard certification tier for Chinese deployments and CE RED compliance depth for European corridors, with budget-constrained transit authorities in India's Smart Cities Mission corridors exhibiting acute price sensitivity against German authorities prioritizing lifecycle carbon metrics over first cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from China's tier-one municipal contracts, while project-based integrators serve fragmented European framework agreements. Manufacturing concentrates in China, Germany, and Vietnam for steel enclosure fabrication and photovoltaic cell assembly, drawing from galvanized steel coil, polysilicon ingots, and cellular module chipsets. Single-source vulnerability in Chinese ingot production quotas feeds tariff exposure on US-bound solar components. Distribution runs through transit infrastructure specialists with captive installation crews rather than traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent bus shelter market compounds steadily as municipal transit digitization mandates replace discretionary infrastructure spending with recurring procurement cycles across OECD and BRICS corridors.
For Market Incumbents: Extend framework contracting coverage across multi-city transit authorities to lock out modular electronics fabricators lacking balance-sheet capacity for multi-year deployment financing. Deepen backward integration into bifacial solar cell production to defend margin pools against polysilicon volatility, while accelerating IEC 62443 cybersecurity certification to preempt regulatory disqualification in EU and North American tenders. For New Entrants and Emerging Players: Enter via India's Smart Cities Mission corridors where BIS localization requirements have slowed foreign OEM penetration, creating white-space for domestic assembly partnerships with Maharashtra and Delhi-NCR industrial zones. Target edge AI inference engine subsystems as the most penetrable technology tier, leveraging utility-backed energy-as-a-service models to bypass upfront solar capex barriers in budget-constrained municipalities. For Investors and Strategic Acquirers: Asymmetric upside sits with regional transit infrastructure specialists possessing captive solar manufacturing and active framework contract pipelines across European urban corridors. Long-term viability rests on shelter OEMs' capacity to pivot from hardware margins toward recurring software revenue from cloud fleet management platforms. Watch for inflection when cellular module certification timelines compress below four months, signaling supply chain normalization and accelerated deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photovoltaic Cells | Captive solar cell production insulates margin pools from Chinese ingot quota volatility. |
| Framework Contract Aggregation | Multi-city procurement consolidation favors vendors with project finance capacity under Île-de-France Mobilités models. |
| Edge AI Inference Engine Development | On-device predictive maintenance opens premium pricing tiers in thermoelectric cooling configurations. |
| Energy-as-a-Service Partnership | Utility power purchase agreements eliminate upfront solar capex barriers in India's municipal tenders. |
| IEC 62443 Cybersecurity Certification | Industrial IoT firmware auditing capabilities preempt regulatory disqualification in EU transit procurements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with transit authority procurement directors, shelter OEM engineering leads, out-of-home advertising network operators, and municipal smart city coordinators with secondary validation against MIIT directive filings, EU Green Deal procurement databases, FCC Part 15 certification records, and BIS electronic component standards. Bottom-up shelter deployment tallies across tier-one Chinese cities and top-down infrastructure spending forecasts from national urban renewal programs were triangulated to anchor volume estimates.
Segment-weighting approaches distributed value across solar-powered, interactive display, digital signage, and Wi-Fi station product types, with technology deployment modeled across cloud platforms, IoT sensors, mobile connectivity, and data analytics layers. End-user segmentation captured public transport authority, advertising agency, city official, and commuter demand patterns. CAGRs were derived from installed base growth rates and replacement cycle assumptions, with polysilicon price elasticity and cellular module certification timelines introduced as scenario variables across the projection horizon.
Inputs from transit authority procurement databases and shelter OEM order backlogs were available through the study window; gaps in real-time municipal budget execution data introduce uncertainty bands around near-term deployment velocity. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement consistency and MIIT data security directive implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
School Bus Market
Buses
Buses & Coaches Market
Buses
Luxury Bus Market
Buses
Bus Rental Market
Buses
Bus Flooring Market
Buses
Canada Transit Buses Market
Buses
Bus Bellows Market
Buses
Trolley Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
North America Bus Market
Buses
Canada School Bus Market
Buses
Bus Seat Market
Buses
Global Luxury Shuttle Bus Market
Buses
Airport Shuttle Bus Market
Buses
Solar Bus Market
Buses
Africa Electric Bus Market