
 North America Forklift Rental Market | 2026-2036
North America Forklift Rental Market Size, Share, and Industry Trends Forecast 2026-2036
North America Forklift Rental Market Insights
Telematics-enabled fleet management is pivoting forklift rental from a hardware transaction to a data-driven service model. United Rentals leverages its scale to embed IoT diagnostics across rental units, sustaining higher utilization rates than regional competitors. Herc Rentals differentiates through specialized industrial verticals, while Toyota Material Handling anchors its position with hybrid-electric portfolios that reduce total cost of ownership for lessees.
North America forklift rental encompasses short-term and long-term leasing of powered industrial trucks designed to lift, move, and stack materials, with load capacities typically spanning 3,000 to 36,000 pounds and mast heights reaching 20 feet or more. Electric forklifts now lead product type demand as battery chemistry improvements extend runtime per charge, while diesel units retain structural share in outdoor construction applications where torque and refueling speed outweigh emissions concerns. Narrow aisle forklifts represent the fastest-growing product configuration, driven by warehouse densification trends that compress aisle widths below 10 feet to maximize cubic storage utilization.
OSHA standards govern operator certification and equipment inspection protocols, directly shaping rental fleet turnover cycles as older units fall out of compliance. EPA Tier 4 Final emissions regulations constrain diesel forklift deployments in non-attainment zones, redirecting demand toward electric and LPG alternatives that rental providers must stock. Stakeholders should monitor state-level zero-emission mandates, as California's Advanced Clean Trucks framework signals regulatory pressure that could cascade to other jurisdictions and reshape fleet composition requirements.
Market Dynamics
Telematics integration is compressing rental decision cycles from months to weeks as fleet managers gain real-time visibility into utilization, maintenance alerts, and operator performance across distributed warehouse networks.
Growth Catalysts
- OSHA Compliance Mandates:Warehouse operators facing inspection penalties are accelerating fleet turnover toward rental units with pre-certified safety systems and documented maintenance histories.
- Lithium-Ion Battery Chemistry:Extended runtime per charge and opportunity charging capabilities are eliminating the productivity penalty that previously constrained electric forklift deployment in multi-shift operations.
- Southeast Logistics Corridor:Port expansion at Savannah and inland distribution hub construction near Atlanta are concentrating demand for short-term rental capacity to manage seasonal volume spikes.
Market Restraints
- Steel and Semiconductor Input Volatility:Forklift manufacturing costs fluctuate with commodity markets, compressing rental provider margins and limiting fleet expansion flexibility.
- Diesel Unit Stranding Risk:EPA Tier 4 Final emissions zones are shrinking the addressable market for internal combustion rentals in California and Northeast metropolitan areas.
- Skilled Technician Scarcity:Maintenance and repair capacity constraints in rural markets extend equipment downtime and reduce rental fleet availability during peak demand periods.
Strategic Opportunities
- Mexico Nearshoring Manufacturing:Automotive and electronics production relocation to Monterrey and Tijuana is generating first-mover advantage for rental providers establishing cross-border service networks.
- California Advanced Clean Trucks Framework:Zero-emission mandates for material handling equipment create guaranteed demand displacement toward electric and hydrogen fuel cell rental portfolios.
- IoT-Enabled Outcome Pricing:Telematics data allows rental contracts to shift from daily rates to productivity-based pricing tied to pallets moved or uptime guarantees.
Industry Challenges
- OSHA Operator Certification Bottlenecks:Training program capacity constraints delay workforce deployment and extend rental contract start dates in tight labor markets.
- Legacy Warehouse Management System Integration:Telematics platforms require API connectivity investments that many mid-sized 3PLs have deferred, limiting data-driven service adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Forklift Rental Market |
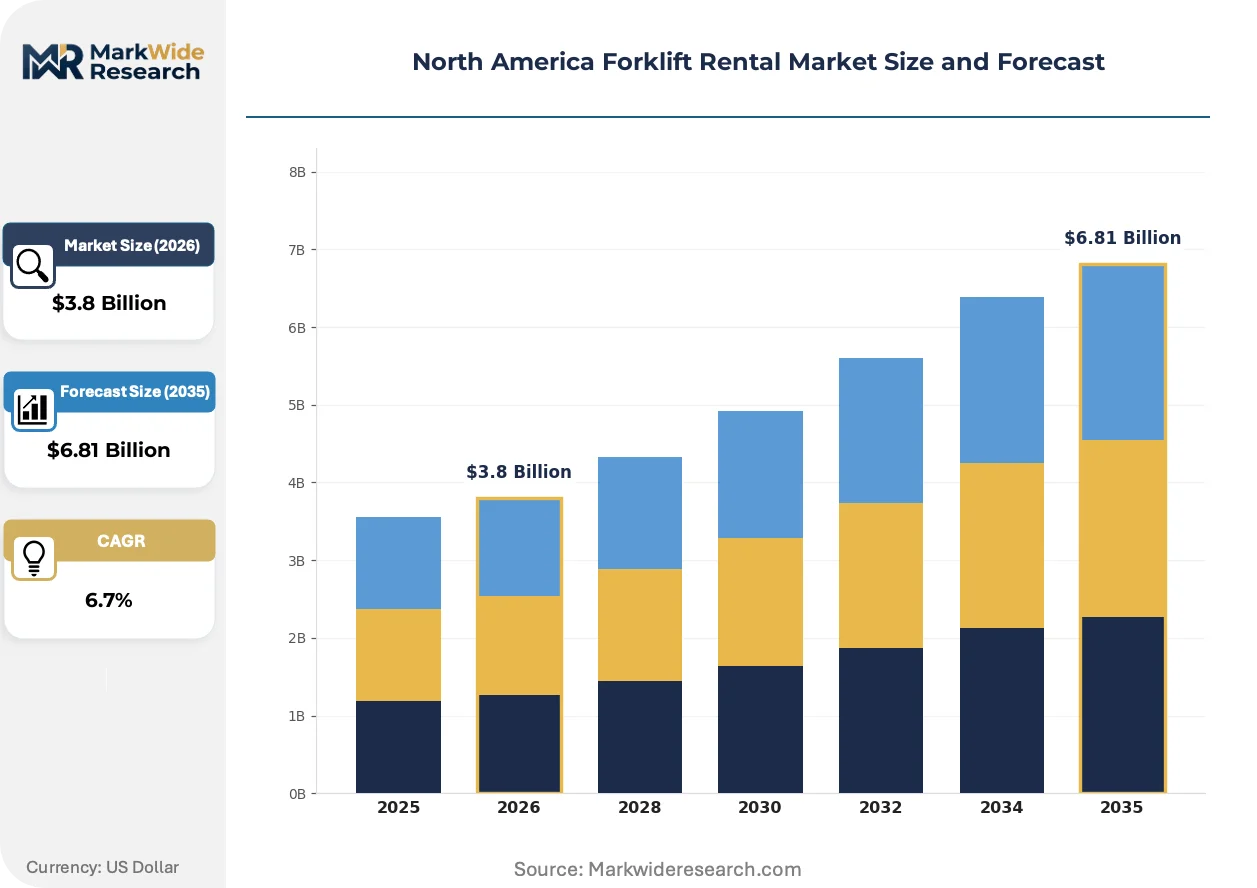
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Diesel Forklifts, LPG Forklifts, Narrow Aisle Forklifts End User: Construction, Manufacturing, Warehousing, Retail Application: Material Handling, Inventory Management, Construction Sites, Shipping and Receiving Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Emergency Rentals |
| Companies Covered | United Rentals, Inc., Sunbelt Rentals, Inc., Herc Rentals Inc., Toyota Material Handling, Crown Equipment Corporation, KION Group AG, Hyster-Yale Materials Handling, Inc., Jungheinrich AG, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Forklift Rental Market Trends and Innovations
Forklift rental is pivoting from equipment provision to integrated mobility services where uptime guarantees, energy management, and operator analytics bundle into single-contract relationships.
Autonomous mobile robots equipped with pallet-handling attachments are decentralizing material flow patterns within distribution centers. E-commerce fulfillment operators are deploying these systems in goods-to-person configurations that eliminate long forklift travel distances. Traditional aisle-based forklift routing is fragmenting into zone-specific automation cells that reduce reliance on human-operated counterbalance units.
EPA Tier 4 Final emissions regulations are constraining diesel forklift eligibility in non-attainment zones across California, Texas, and Northeast corridor states. Fleet managers in these jurisdictions face equipment replacement deadlines that favor rental contracts with built-in compliance upgrade pathways. Rental providers are responding by pre-positioning electric and LPG units in regional hubs near regulated metropolitan markets.
Usage-based contracting is displacing fixed-term leases as the dominant procurement structure among mid-sized warehouse operators. Third-party logistics providers are negotiating agreements where rental rates adjust monthly based on actual hours deployed rather than committed fleet size. This shift is most pronounced in the US Southeast where seasonal retail volume volatility makes capacity flexibility more valuable than rate predictability.
North America Forklift Rental Market Segmentation
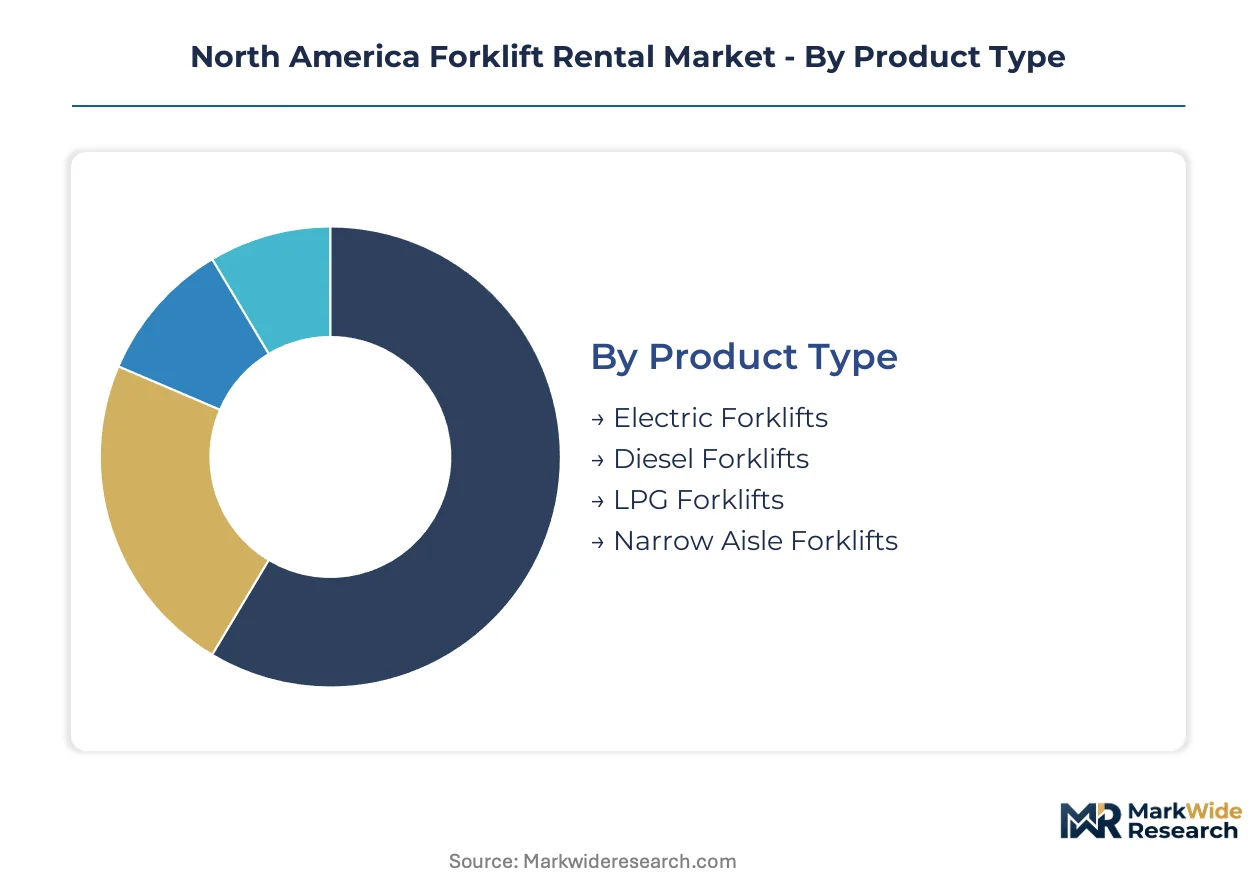
Forklift rental demand fragments across powertrain technologies, operational durations, and facility types. Each segment carries distinct compliance burdens and utilization patterns that reshape provider fleet composition.
Product Type:
Electric units dominate volume deployment while premium pricing attaches to specialized configurations.
- Electric Forklifts:Battery-powered units with lithium-ion chemistry extending runtime per charge beyond traditional lead-acid systems. Demand concentrates in California and Northeast distribution centers where EPA non-attainment zones restrict internal combustion alternatives and OSHA indoor air quality mandates accelerate fleet turnover.
- Narrow Aisle Forklifts:Articulating mast designs enabling operation in aisles under 10 feet wide for cubic storage maximization. Southeast warehousing corridors near Atlanta and Savannah drive deployment as e-commerce fulfillment operators densify existing footprints rather than expand square footage.
- Diesel Forklifts:Internal combustion units retaining torque advantages for outdoor construction and heavy manufacturing yards.
- LPG Forklifts:Liquid petroleum gas alternatives bridging indoor-outdoor flexibility with faster refueling than electric counterparts.
Mature deployment sits with diesel configurations in construction and heavy industrial yards. Newer deployment is concentrated in narrow aisle electric units responding to warehouse densification imperatives.
End User:
Application intensity varies sharply between cyclical construction demand and steady-state warehousing operations.
- Warehousing:Multi-shift distribution and fulfillment centers requiring predictable fleet availability with telematics-enabled utilization tracking. The Southeast logistics corridor generates concentrated short-term rental spikes during Q4 retail volume peaks.
- Construction:Project-based equipment needs with high seasonality and outdoor terrain requirements. Texas and Florida infrastructure projects sustain diesel and rough-terrain rental demand despite emissions regulatory pressure.
- Manufacturing:Just-in-time production facilities integrating rental fleets into lean inventory systems.
- Retail:Big-box and grocery distribution networks with seasonal inventory surges driving flexible capacity procurement.
Long-term contract structures prevail in manufacturing. Spot-market flexibility dominates construction procurement patterns.
Application:
Task specificity determines equipment specification and attachment configuration requirements.
- Material Handling:Core pallet movement and stacking operations across facility types. Multi-shift warehousing operations in the Southeast are expanding most quickly as regional distribution hub construction accelerates.
- Inventory Management:Cycle counting, order picking, and stock replenishment workflows requiring precision maneuverability.
- Construction Sites:Rough terrain and heavy load applications with exposure to weather and debris.
- Shipping and Receiving:Dock-to-stock movements with rapid turnaround requirements at port-adjacent facilities.
Standardized fleet configurations serve material handling. Customized attachments and terrain packages concentrate in construction site deployment.
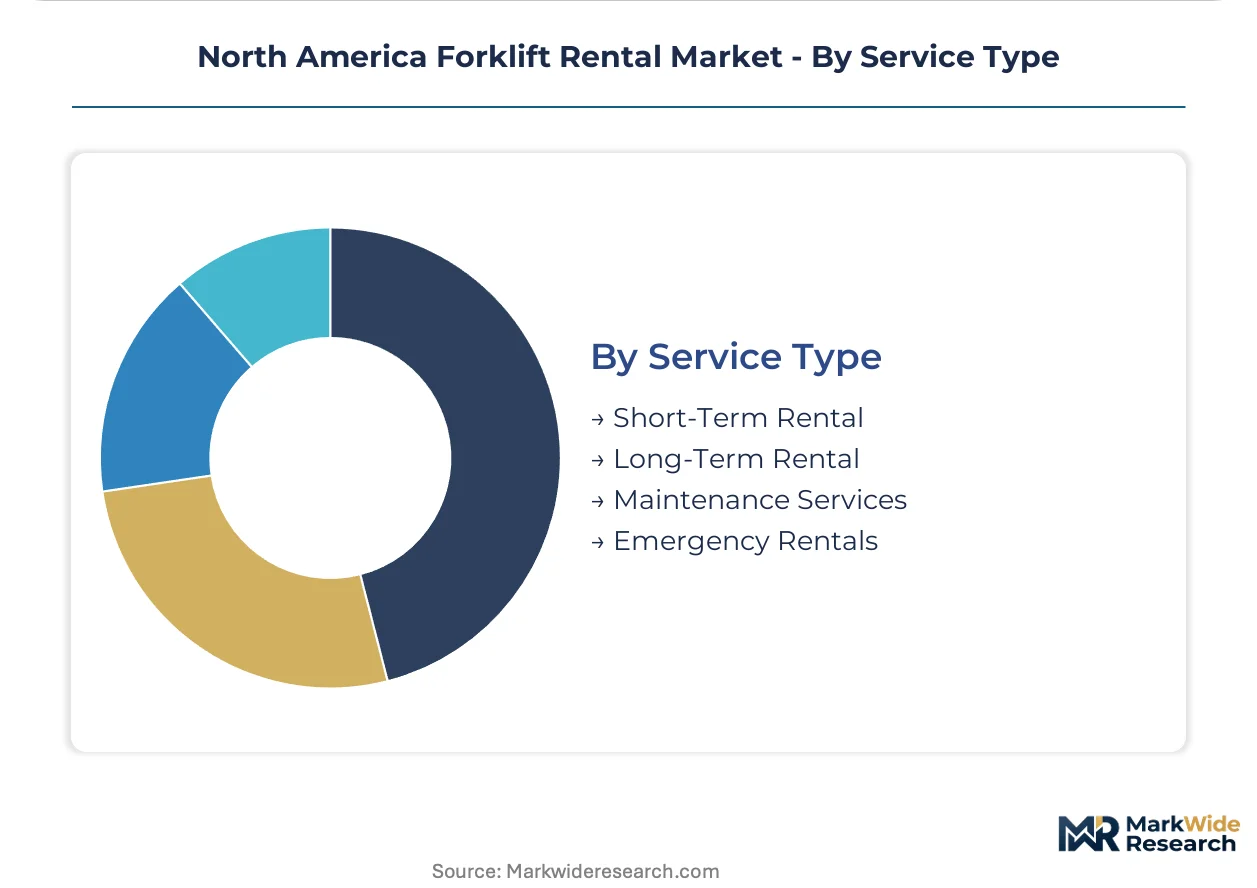
Service Type:
Contract duration and risk transfer mechanisms segment procurement approaches across customer sophistication levels.
- Long-Term Rental:Multi-year agreements with full maintenance inclusion and compliance upgrade guarantees. Large 3PLs negotiating these contracts in California are securing built-in pathways to zero-emission fleet transitions under state Advanced Clean Trucks frameworks.
- Short-Term Rental:Daily to monthly capacity augmentation for seasonal spikes and facility expansions. Savannah port expansion and Atlanta inland hub construction are driving concentrated demand in the Southeast corridor.
- Maintenance Services:Separate service contracts for customer-owned fleets.
- Emergency Rentals:Breakdown replacement and surge capacity with premium pricing for immediate availability.
Usage-based pricing penetration is deepest in short-term arrangements. Fixed-rate predictability anchors long-term contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the majority of forklift rental consumption across North America, while Canada and Mexico represent distinct procurement patterns shaped by resource extraction and nearshoring manufacturing respectively.
United States
Southeast logistics corridor expansion near Atlanta and Savannah drives concentrated short-term rental spikes. EPA Tier 4 Final emissions regulations restrict diesel forklift deployments in California and Northeast metropolitan non-attainment zones. Texas and Florida infrastructure projects sustain rough-terrain rental demand despite regulatory pressure.
Canada
Ontario and Quebec manufacturing hubs require steady-state electric forklift fleets for indoor warehousing operations. Environment and Climate Change Canada carbon pricing mechanisms accelerate lessee preference for battery-powered units over propane alternatives. Alberta oil sands and mining operations in Fort McMurray sustain specialized heavy-capacity rental demand for outdoor terrain applications.
Mexico
Automotive and electronics production relocation to Monterrey and Tijuana generates cross-border service network requirements. Mexican federal environmental regulations under SEMARNAT progressively tighten emissions standards for material handling equipment in metropolitan zones. Bajío Region industrial parks near Guanajuato attract foreign manufacturing investment requiring flexible rental capacity for facility ramp-ups.
Southeast United States
Port expansion at Savannah and inland distribution hub construction near Atlanta concentrate demand for seasonal capacity augmentation. OSHA enforcement intensification in Georgia and Florida warehousing operations accelerates fleet turnover toward compliant rental units. E-commerce fulfillment operators in the I-75 corridor densify existing footprints with narrow aisle configurations.
North America Forklift Rental Market Competitive Landscape
Top-tier vendors anchor national fleet scale, while regional specialists and equipment manufacturers with captive rental arms occupy differentiated competitive positions. The market structure reflects consolidated national coverage alongside specialized industrial verticals. Three archetypes dominate: telematics-enabled fleet managers, hybrid-electric portfolio providers, and construction-focused rough-terrain specialists. Competitive moves center on IoT platform integration and zero-emission fleet pre-positioning near regulated metropolitan markets.
Among national-scale rental providers, United Rentals, Inc. and Sunbelt Rentals, Inc. represent the telematics-enabled service model archetype, while Herc Rentals Inc. occupies a position within specialized industrial verticals. Toyota Material Handling anchors the manufacturer-captive rental segment with hybrid-electric portfolio positioning.
| Leading Market Players |
|---|
| United Rentals, Inc. |
| Sunbelt Rentals, Inc. |
| Herc Rentals Inc. |
| Toyota Material Handling |
| Crown Equipment Corporation |
| KION Group AG |
| Hyster-Yale Materials Handling, Inc. |
| Jungheinrich AG |
| Caterpillar Inc. |
| Others |
Pricing and Supply Chain Analysis
Steel price index volatility cascades through forklift manufacturing into rental rate stratification, with commodity surges compressing provider margins and forcing tiered fleet investment decisions that segment the market into premium telematics-enabled units and standard configurations.
Pricing Analysis
Margin tightening in standard electric forklift tiers reflects lithium-ion battery cost fluctuations and semiconductor module scarcity. Three-tier pricing structure across premium telematics-integrated, standard compliance-certified, and economy legacy units dominates contract structures. Price differentiation hinges on EPA Tier 4 Final certification status and bundled maintenance uptime guarantees. Cost-down pressure on diesel configurations accelerates because California and Northeast non-attainment zones restrict deployment eligibility. Mid-sized 3PLs in the Southeast corridor exhibit highest price sensitivity, prioritizing flexible short-term rates over long-term predictability.
Supply Chain Analysis
Regional distribution centers in Illinois, Texas, and Georgia anchor hub-and-spoke fleet positioning for rapid deployment response. Manufacturing concentration centers on Japan, Germany, and China for core chassis and mast assemblies. Raw material dependencies span high-grade steel for masts, lithium carbonate for battery packs, and semiconductor components for telematics control modules. Single-source vulnerability in battery management system chipsets creates fleet delivery bottlenecks during automotive sector demand spikes. Distribution runs through manufacturer-authorized service depots that maintain parts inventory and certified technician pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forklift rental sits in a powertrain transition phase as lithium-ion electric configurations displace legacy lead-acid and Tier 4 diesel units across compliance-sensitive warehousing corridors.
For Market Incumbents: Cement fleet-scale advantages by pre-positioning zero-emission electric and hydrogen fuel cell units near California's Advanced Clean Trucks enforcement zones. Deepen backward integration into telematics platform development to capture recurring software revenue streams. Counter autonomous mobile robot substitution threats by bundling operator training and uptime guarantees into long-term contracts. For New Entrants and Emerging Players: IoT-native fleet management platforms offer entry wedges into mid-sized 3PLs with deferred warehouse management system upgrades. Target Mexico's Bajío Region manufacturing parks where foreign facility ramp-ups demand flexible short-term capacity without established incumbent relationships. Lead with usage-based pricing contracts that align rental costs to seasonal volume volatility. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with dense Southeast corridor service networks during steel price correction periods. Long-term viability hinges on electric fleet transition completion and cross-border Mexico operational capabilities. Monitor California Air Resources Board zero-emission mandate enforcement timing as inflection indicator for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Emission Fleet Pre-Positioning | California CARB mandates guarantee demand displacement toward compliant electric and hydrogen units. |
| Telematics Platform Integration | Real-time utilization data enables outcome-based pricing contracts with large 3PL operators. |
| Cross-Border Mexico Service Network | Monterrey and Tijuana nearshoring generates first-mover rental demand from automotive suppliers. |
| Operator Certification Program Investment | OSHA-compliant training capacity reduces contract start delays in tight labor markets. |
| Narrow Aisle Configuration Expansion | Atlanta and Savannah warehouse densification drives articulating mast forklift procurement. |
Research Methodology
Independent corroboration across fleet manager interviews, OEM procurement leads, and aftermarket service heads underwrites the qualitative findings in this study. Primary fieldwork engaged maintenance directors at Southeast distribution centers, plant engineers at automotive manufacturing facilities, and rental contract administrators at third-party logistics providers. Secondary validation drew from EPA enforcement action databases, OSHA inspection citation records, and port authority cargo volume disclosures. Bottom-up fleet size estimates triangulate against top-down equipment shipment data from customs and trade sources.
Rate-of-change decomposition separates volume growth from mix-shift effects across powertrain technologies, contract duration categories, and end-use applications. Segmentation modeling incorporates powertrain type, service tier, facility type, and regional regulatory cluster dimensions. CAGRs derive from fitted trend lines applied to base-year calibration points, with cross-checks against equipment replacement cycle assumptions and warehouse construction permit flows. Lithium-ion battery cost curves and steel price index trajectories inform fleet investment sensitivity scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA emissions enforcement or semiconductor supply disruptions. Forecasts reflect documented assumptions regarding regulatory phase-in schedules, battery chemistry improvement rates, and nearshoring manufacturing relocation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Car Modification Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
RV Battery Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
EGR Valve Market