
 Collapsible Jerry Can Market | 2026-2036
Collapsible Jerry Can Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Jerry Can Market Analysis
Multi-source procurement for military-grade collapsible containers is rebalancing toward qualified domestic suppliers in North America and Europe. Scepter Corporation leverages its defense contracting heritage to sustain long-term institutional relationships with armed forces buyers. Reliance Products anchors the consumer outdoor segment through mass retail channel control across Canada and the United States. Vapur, Inc. differentiates via flexible-film technology leadership in ultralight recreational hydration systems.
A collapsible jerry can is a foldable liquid storage vessel engineered from food-grade polyethylene, laminated nylon, or thermoplastic elastomer films, typically incorporating welded seams, integrated handles, and self-sealing spouts rated for potable water, fuel, or chemical containment. The device collapses to a fraction of filled volume for transport efficiency in remote logistics, disaster response, and recreational overlanding. Plastic variants dominate unit volume due to cost-efficient rotational molding and compliance with FDA Title 21 food-contact standards, while composite constructions command margin pools in military specifications requiring ballistic resilience and extended UV stability. The 20-liter capacity segment leads commercial procurement for humanitarian aid operations, whereas 5-liter formats are the fastest-growing category in consumer outdoor retail through online channels.
FDA material safety regulations, EU REACH substance restrictions, and ISO 9001 quality management frameworks collectively govern polymer sourcing, migration testing protocols, and supplier qualification for collapsible liquid storage devices. Military end users additionally require NATO STANAG certification for interoperability with allied logistics systems. Stakeholders must monitor evolving PFAS restrictions under state-level legislation in California and Maine, as these compounds appear in legacy fluoropolymer barrier coatings.
Market Dynamics
Military procurement consolidation around NATO STANAG interoperability standards is compressing supplier qualification timelines while elevating technical performance thresholds for field-deployable liquid storage systems.
Growth Catalysts
- Bundeswehr Modernization:German defense procurement is driving specialized collapsible container adoption through accelerated field equipment replacement programs.
- REACH Polymer Compliance:EU substance restrictions are filtering out legacy PVC formulations, creating certified-supplier preference pools for compliant polyethylene alternatives.
- Rotational Molding Cost Efficiency:Food-grade polyethylene processing advances are lowering unit economics for humanitarian aid procurement at 20-liter capacity points.
Market Restraints
- Petrochemical Feedstock Volatility:Crude-linked polyethylene resin costs create margin compression for rotational molders without long-term supply contracts.
- Fluoropolymer Barrier Phaseout:California and Maine PFAS restrictions are forcing reformulation of legacy chemical-resistant coatings before certified alternatives reach scale.
- Rigid Container Substitution:Standardized NATO metal jerry cans retain institutional preference for high-threat logistics corridors where puncture resistance outweighs weight savings.
Strategic Opportunities
- India Disaster Response Modernization:National Disaster Response Force procurement is opening to ISO-certified collapsible water storage for monsoon relief operations.
- Overlanding Channel Expansion:Direct-to-consumer outdoor retail platforms are capturing margin pools previously held by mass-market distributors.
- Thermoplastic Elastomer Convergence:Welded TPU-nylon laminates are penetrating military specifications previously reserved for rotomolded construction.
Industry Challenges
- NATO STANAG Certification Timelines:Interoperability testing protocols extend product development cycles by 18-24 months for new entrants.
- Multi-jurisdictional Migration Testing:FDA Title 21, EU 10/2011, and national food-contact regimes require redundant laboratory validation for portable water applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Jerry Can Market |
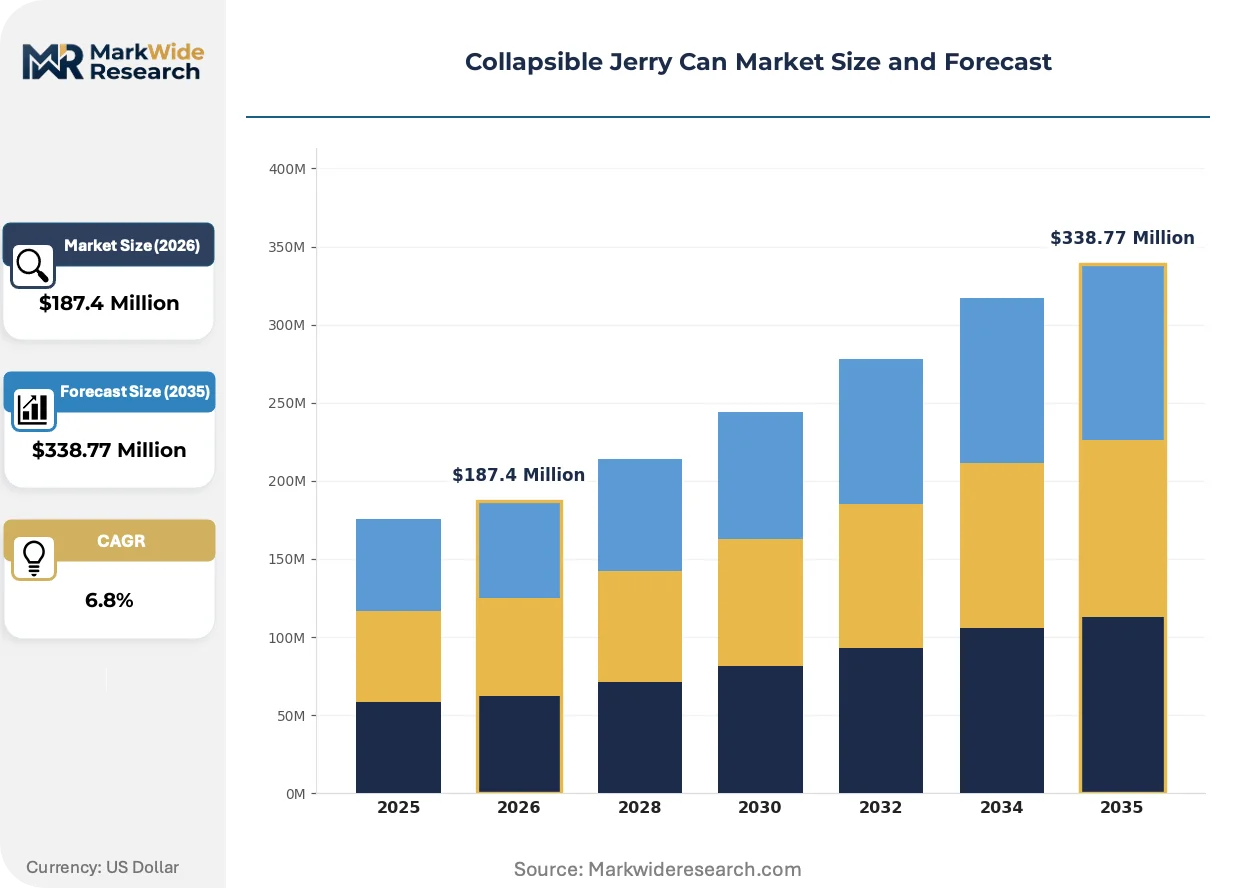
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Flexi-tank End User: Household, Industrial, Military, Emergency Services Distribution Channel: Online Retail, Offline Retail, B2B Sales, Direct Sales Capacity: 5 Liters, 10 Liters, 20 Liters, 30 Liters |
| Companies Covered | Scepter Corporation, Butyl Products Ltd., Reliance Products, Liquid Containment, Vapur, Inc., Fu Deng Plastic Co., Ltd., Polyene General Industries Private Limited, WaterStorageCube, Coghlan's Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Jerry Can Market Emerging Trajectories
Welded flexible-film construction is displacing rotational molding in weight-critical applications while regulatory chemistry restrictions are accelerating material substitution cycles across military and civilian procurement channels.
Thermoplastic polyurethane-nylon laminate technology is expanding into ultralight field hydration systems. Special forces procurement units in NATO member states are adopting welded-seam construction for load-bearing water transport. This film-based approach is expanding into segments previously dominated by rigid polyethylene, compressing the addressable market for conventional rotomolded formats below 10-liter capacities.
EU REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of flexible PVC barrier layers in chemical-resistant variants. Industrial consequence includes accelerated supplier consolidation around compliant TPU and EPDM alternatives. Military chemical, biological, radiological, and nuclear defense procurement in Germany and France is most affected, with specifications now requiring third-party migration testing documentation.
Direct institutional contracting is displacing distributor-mediated procurement for defense and humanitarian end uses. United Nations Development Programme and International Committee of the Red Cross buyers are consolidating vendor lists around pre-qualified manufacturers with integrated quality management systems. This concentration is most visible in German and Swiss procurement clusters, where ISO 9001 certification has become a minimum threshold for tender participation rather than a differentiating factor.
Collapsible Jerry Can Market Segmentation
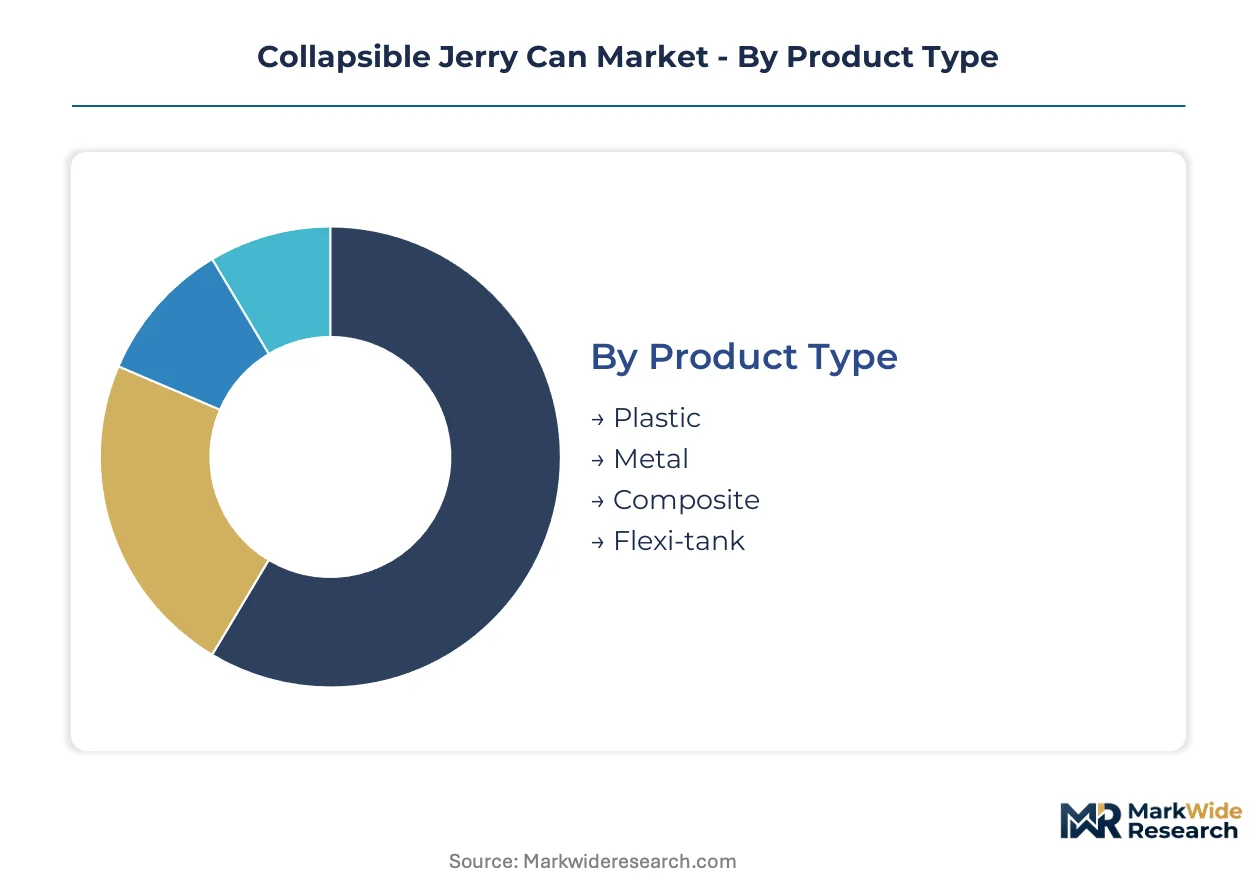
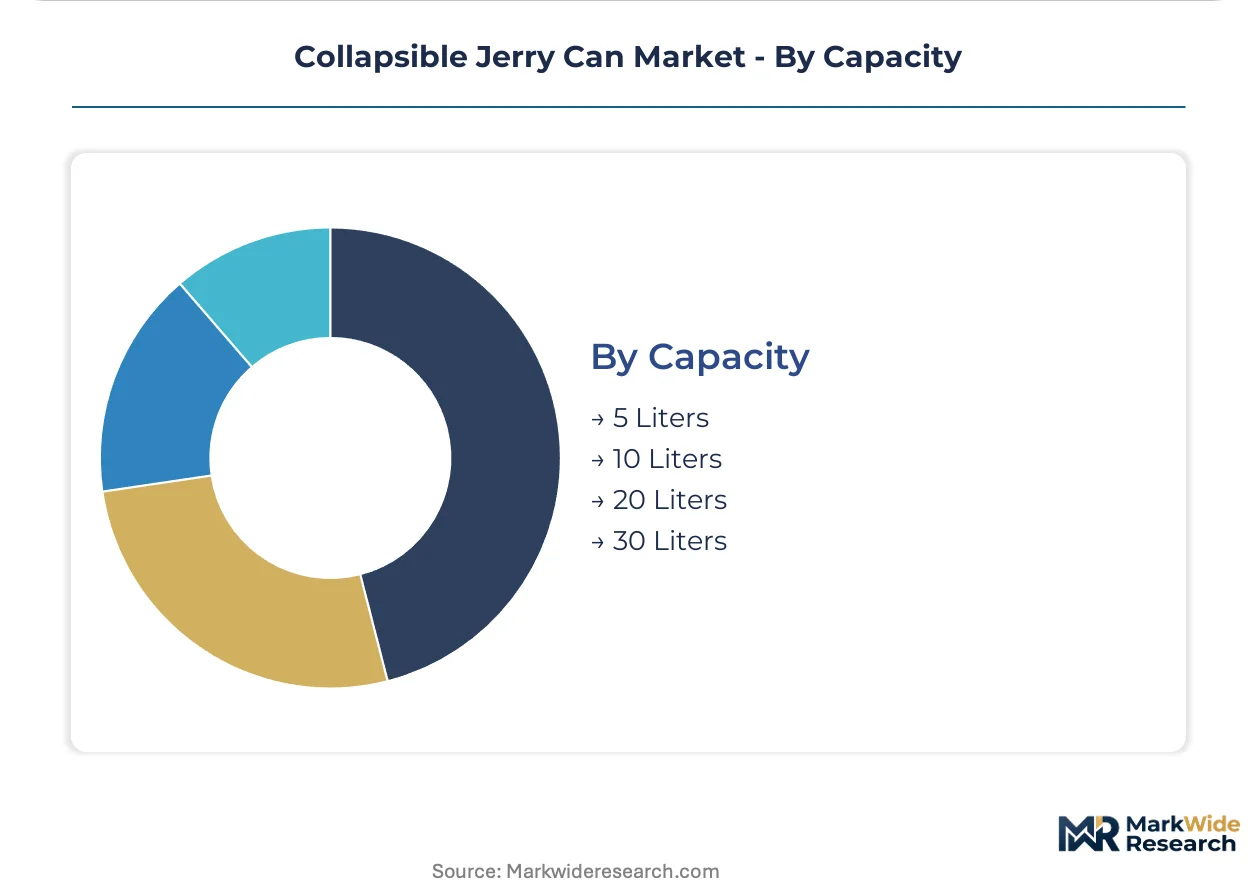
Material selection and capacity configuration determine procurement economics across military, humanitarian, and consumer applications. Each segment carries distinct certification burdens and supply chain requirements that reshape vendor positioning.
Product Type:
Buyers prioritize weight-to-strength ratios against specific regulatory compliance thresholds when selecting construction materials.
- Plastic:Rotomolded food-grade polyethylene dominates unit economics through FDA Title 21 compliance and REACH-certified polymer sourcing. Bundeswehr field water programs and UN humanitarian tenders concentrate procurement around German and Swiss rotational molders with integrated quality systems.
- Composite:Ballistic-resistant laminates incorporating aramid or glass fiber reinforcement command military specification premiums. NATO STANAG interoperability testing in Germany and France filters supplier pools to pre-qualified defense contractors.
- Metal:Standardized NATO aluminum jerry cans retain institutional preference for high-threat logistics corridors requiring puncture resistance.
- Flexi-tank:Welded TPU-nylon laminates penetrate ultralight special forces hydration systems through thermoplastic elastomer welding advances.
Plastic leads on scale; Flexi-tank leads on momentum.
End User:
Application-specific performance requirements create divergent procurement channels with distinct margin structures.
- Military:STANAG-certified containers require 18-24 month qualification cycles with NATO interoperability testing. German and French CBRN defense specifications now mandate third-party migration documentation for barrier coatings.
- Emergency Services:National Disaster Response Force procurement in India and Red Cross tenders in Switzerland consolidate around ISO 9001-certified manufacturers with direct institutional contracting relationships.
- Industrial:Chemical-resistant variants face PFAS reformulation pressure under California and Maine state restrictions.
- Household:Consumer outdoor retail through Canadian and United States mass channels anchors volume for sub-10-liter recreational formats.
Military leads on scale; Emergency Services leads on momentum.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth across institutional and consumer segments.
- B2B Sales:Defense and humanitarian procurement concentrates around pre-qualified vendor lists with integrated quality management systems.
- Direct Sales:United Nations Development Programme and International Committee of the Red Cross buyers in German and Swiss clusters bypass distributor intermediaries.
- Online Retail:Direct-to-consumer platforms capture margin pools in North American recreational overlanding segments.
- Offline Retail:Mass-market distributors retain position in Canadian and United States consumer outdoor channels.
B2B Sales leads on scale; Online Retail leads on momentum.
Capacity:
Volume requirements align with logistics constraints and end-use mobility demands across deployment scenarios.
- 20 Liters:Humanitarian aid operations standardize on this capacity for water distribution efficiency in monsoon relief and refugee camp logistics.
- 5 Liters:Recreational overlanding and special forces load-bearing applications drive welded flexible-film adoption for weight-critical transport.
- 10 Liters:Intermediate formats serve mixed civilian-military procurement with rotational molding cost advantages.
- 30 Liters:Bulk stationary storage applications in industrial chemical containment favor rigid construction.
20 Liters leads on scale; 5 Liters leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German defense procurement clusters in Lower Saxony and Bavaria anchor military-grade collapsible container demand through Bundeswehr modernization programs. Rotational molding centers in Switzerland and polymer fabrication hubs in North America supply complementary capacity for NATO interoperability requirements.
Germany
Bundeswehr field equipment replacement programs drive specialized collapsible container procurement in 20-liter and 5-liter formats. ECHA REACH Annex XVII restrictions on phthalate plasticizers filter supplier pools toward compliant polyethylene alternatives. Manufacturing concentrates in Lower Saxony around rotomolders with integrated ISO 9001 quality systems serving defense tenders.
United States
Special forces procurement units and recreational overlanding segments sustain dual demand tracks for ultralight welded-film and rotomolded formats. FDA Title 21 food-contact standards govern polymer selection for potable water applications. Production gravity sits in Midwest rotational molding corridors supplying mass retail channels across North America.
Switzerland
International Committee of the Red Cross procurement headquarters consolidates vendor lists around pre-qualified collapsible water storage manufacturers. Swissmedic-aligned quality documentation supports humanitarian aid tenders requiring third-party migration testing. Industrial clusters in Basel-Land and Zurich cantons host defense contractors with NATO STANAG certification.
India
National Disaster Response Force modernization opens ISO-certified collapsible water storage procurement for monsoon relief operations. BIS standards for food-contact materials increasingly govern polymer selection in domestic manufacturing. Gujarat and Maharashtra rotational molding hubs scale capacity for 20-liter humanitarian aid formats.
Canada
Consumer outdoor retail channels anchor volume demand for sub-10-liter recreational collapsible containers. Health Canada food-contact regulations align with FDA standards for cross-border polymer sourcing. Ontario-based mass retail distributors control shelf access for household segment penetration.
Collapsible Jerry Can Market Vendor Landscape
Global majors compete with regional champions across defense contracting and consumer retail channels. The supplier base stratifies into three tiers: NATO-certified defense contractors with 18-24 month qualification cycles, ISO-certified humanitarian aid specialists, and mass-market recreational fabricators. Dominant competitive moves include direct institutional contracting displacement of distributor intermediaries and thermoplastic elastomer welding technology licensing for weight-critical military specifications.
Within the defense-contractor archetype, Scepter Corporation and Butyl Products Ltd. occupy positions sustained by long-term institutional relationships with armed forces buyers. Reliance Products anchors the consumer outdoor segment through mass retail channel control. Vapur, Inc. exemplifies the flexible-film technology specialist tier penetrating ultralight recreational and special forces hydration applications.
| Leading Market Players |
|---|
| Scepter Corporation |
| Butyl Products Ltd. |
| Reliance Products |
| Liquid Containment |
| Vapur, Inc. |
| Fu Deng Plastic Co., Ltd. |
| Polyene General Industries Private Limited |
| WaterStorageCube |
| Coghlan's Ltd. |
| Others |
Supply Flow & Price Mechanics
Polyethylene resin costs cascade from Gulf Coast petrochemical complexes through rotational molding centers in Lower Saxony and the American Midwest, compressing margins for humanitarian aid suppliers while NATO-certified defense contractors pass through material premiums via long-term institutional contracts.
Pricing Analysis
Input-cost pass-through from crude-linked polyethylene resin feeds three-tier pricing stratification across premium military-grade, standard humanitarian, and economy consumer tiers. Price differentiation hinges on NATO STANAG certification level and FDA Title 21 migration testing documentation. Cost compression in standard-tier humanitarian procurement is intensifying as UN tenders consolidate around pre-qualified vendor pools. Consumer outdoor segments exhibit highest price sensitivity, while German defense procurement shows lowest elasticity due to specification-locked replacement cycles.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns serving NATO logistics corridors and Red Cross procurement clusters. Manufacturing concentrates in Germany, Switzerland, and the United States, with polymer fabrication drawing from Belgian and Dutch petrochemical feedstock. Single-source vulnerability concentrates in FDA-certified rotational molding capacity for 20-liter humanitarian formats. Distribution runs through direct institutional contracting for defense and aid sectors, with mass retail channels handling consumer recreational volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsible jerry can market compounds steadily as recurring defense modernization cycles and disaster response institutionalization create predictable replacement demand across NATO and humanitarian procurement channels.
For Market Incumbents: Hedge against thermoplastic elastomer substitution by securing welded-film technology licensing from TPU-nylon laminate specialists before special forces procurement fully transitions away from rotomolded formats. Deepen backward integration into food-grade polyethylene resin sourcing through long-term offtake agreements with Rotterdam petrochemical suppliers to defend margin position against feedstock volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer online retail platforms targeting North American overlanding enthusiasts with ultralight 5-liter welded-film formats, bypassing mass-market distributor gatekeepers that incumbent consumer players control. Target India's National Disaster Response Force modernization as the most penetrable institutional segment, where ISO 9001 certification requirements remain less stringent than NATO STANAG barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented consumer outdoor fabricators lack the quality management systems required for defense and humanitarian tender participation. The market supports a 5-10 year compounder thesis anchored by institutional procurement formalization. Acquisition candidates include Swiss and German rotational molders with integrated ISO 9001 systems and existing Red Cross relationships. Watch for PFAS regulatory enforcement acceleration as the inflection signal that forces legacy coating reformulation and triggers supplier shakeout.| Strategic Initiative | Industry Significance |
|---|---|
| NATO STANAG Certification Investment | Unlocks German and French defense procurement with 18-24 month qualification timelines. |
| Welded TPU-Nylon Laminate Scale-Up | Captures special forces ultralight hydration demand displacing rotomolded construction. |
| Direct Institutional Contracting | Bypasses distributor intermediaries in UNDP and Red Cross procurement clusters. |
| REACH-Compliant Polymer Sourcing | Filters supplier pools as ECHA Annex XVII phthalate restrictions eliminate legacy PVC. |
| India Manufacturing Footprint | Positions for National Disaster Response Force monsoon relief tenders with BIS alignment. |
Methodological Framework
Coverage spans Germany, the United States, Switzerland, India, and Canada, with primary inputs from each market triangulated against secondary validation. Defense procurement officers, rotational molding plant managers, humanitarian aid logistics coordinators, and mass retail category buyers provided operational perspective. Secondary sources included FDA Title 21 food-contact standards documentation, ECHA REACH substance restriction filings, NATO STANAG interoperability specifications, UN Development Programme tender records, and customs data on polyethylene resin trade flows. Bottom-up unit economics from manufacturing cost structures were cross-checked against top-down procurement budget allocations.
Rate-of-change decomposition across material substitution cycles, regulatory compliance timelines, and procurement channel shifts anchored the analytical framework. Segmentation dimensions modeled encompass construction material, end-user application, distribution channel, and capacity configuration. CAGRs derived from fitted growth curves reflecting defense budget trajectories and humanitarian aid funding patterns. Industry-specific inputs included Bundeswehr equipment replacement schedules and Indian monsoon relief operational requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price volatility and accelerated PFAS regulatory enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Truck Axle Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Railway Air Filter Market