
 Micromobility Platform Market | 2026-2036
Micromobility Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Micromobility Platform Market Foresight
Subscription bundling of hardware, insurance, and maintenance is recalibrating how fleet operators evaluate total cost of ownership. Lime leverages its manufacturing scale to control unit economics across multiple continents. Vulog anchors its competitive position through white-label software specialization for transit agencies. Bird competes by sustaining direct-to-consumer sales channels alongside shared fleet deployments.
A micromobility platform integrates connected vehicle hardware, fleet management software, and user-facing applications to coordinate short-distance electric vehicle access, typically spanning trips under five kilometers with real-time GPS telemetry and automated payment settlement. The primary commercial purpose is optimizing asset utilization rates while reducing urban congestion and last-mile logistics costs. Shared business models currently absorb the majority of capital deployment, though subscription services for fleet operators represent the fastest-expanding margin pool as operators seek predictable operating expenditure structures. E-scooter vehicle types retain volume leadership across temperate-climate deployments, while e-bike configurations command premium positioning in hilly or longer-distance corridors.
France's ANSM and Germany's KBA enforce divergent battery safety certification pathways that fragment hardware compliance costs for platform providers entering European markets. The US DOT and EPA coordinate on emissions credits that indirectly subsidize electric fleet conversions in metropolitan transit districts. Stakeholders must monitor how municipal procurement standards consolidate around interoperable charging protocols versus proprietary dockless formats.
Market Dynamics
Battery-swappable architectures are compressing asset downtime and rewriting procurement specifications for municipal fleet contracts across temperate-climate cities. Transit agencies now embed hardware-software integration requirements directly into tender documents, favoring vendors with captive manufacturing over pure software plays.
Growth Catalysts
- EU Green Deal implementation:Metropolitan transit districts in France, Germany, and the Netherlands face binding decarbonization timelines that mandate electric fleet conversions by specific regulatory deadlines.
- Last-mile logistics densification:E-commerce fulfillment networks in Singapore, Seoul, and London are contracting micromobility platforms to reduce delivery vehicle congestion in urban cores.
- Cellular IoT module cost curves:Real-time GPS telemetry hardware now deploys at unit economics that support profitable shared-fleet operations in secondary cities previously considered margin-negative.
Market Restraints
- Lithium-ion cell price volatility:Battery pack costs represent 35-40% of vehicle bill-of-materials, exposing fleet operators to commodity swings without long-term offtake agreements.
- Proprietary charging protocol fragmentation:Dockless formats from competing vendors create stranded asset risk for cities that standardize on single-supplier deployments.
- ANSM-KBA regulatory divergence:France and Germany enforce non-harmonized battery safety certification pathways that multiply compliance costs for hardware providers entering both markets.
Strategic Opportunities
- Subscription bundling penetration:Fleet operators in Spain and Italy are migrating from per-ride revenue to fixed-fee structures covering hardware, insurance, and predictive maintenance.
- Interoperable charging infrastructure:Municipal procurement in Copenhagen and Vienna is consolidating around open-protocol dockless standards that reduce vendor lock-in.
- E-bike corridor expansion:Hilly topography in Lisbon, Rome, and San Francisco is driving premium positioning for pedal-assist configurations in longer-distance deployments.
Industry Challenges
- Battery thermal runaway certification timelines:UN 38.3 and IEC 62133 testing protocols extend hardware validation cycles by 8-14 months, delaying fleet scaling.
- Telematics integration complexity:Legacy transit agency IT systems require custom API development to ingest real-time vehicle telemetry, inflating deployment costs.
- Field technician scarcity:Specialized skills for swappable battery diagnostics and brake-regeneration calibration outpace vocational training pipeline output in multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micromobility Platform Market |
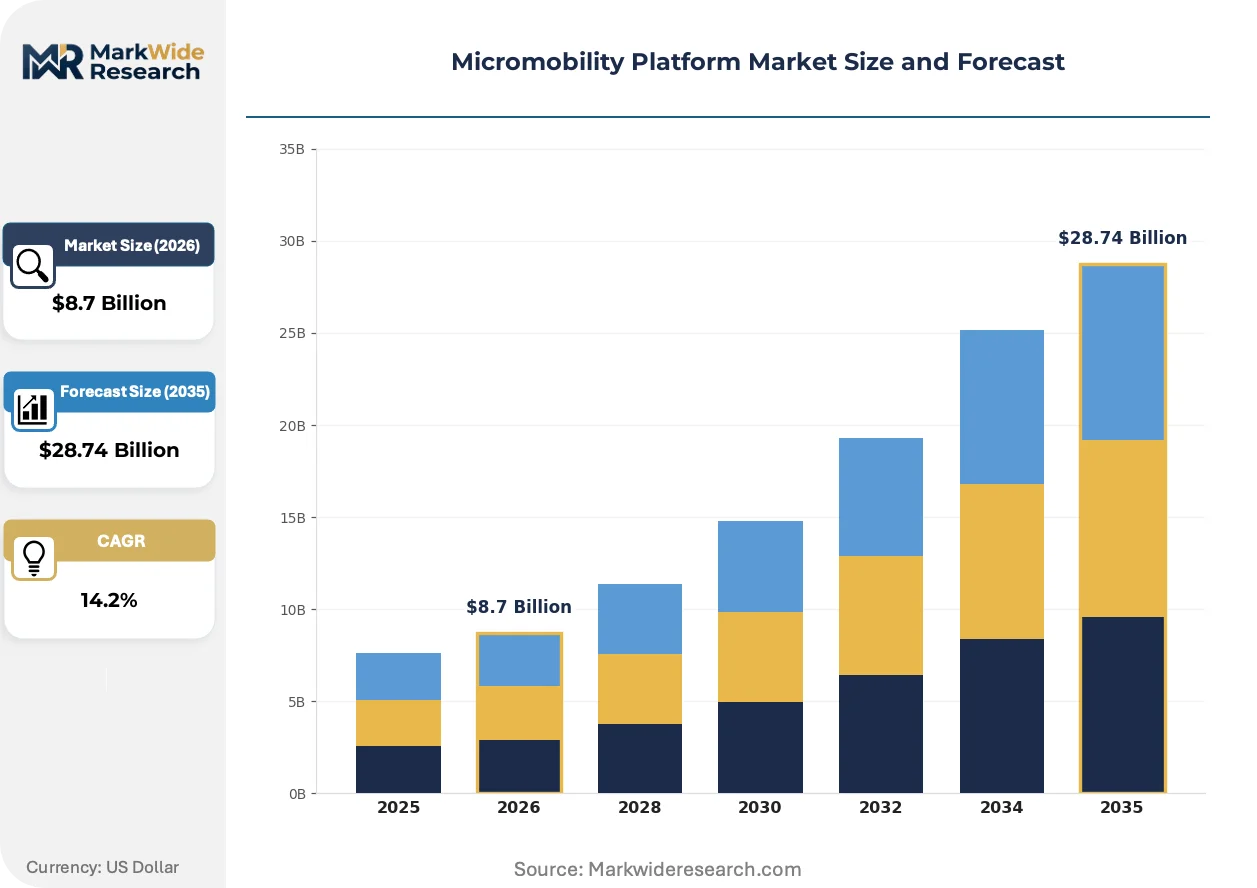
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Business Model: Owned, Shared, Subscription, On-Demand Vehicle Type: E-Scooter, E-Bike, E-Moped, Unicycle Technology: GPS Tracking, Mobile App, IoT Connectivity, Charging Solutions Customer Segment: Commuters, Tourists, Students, Fleet Operators |
| Companies Covered | Lime, Bird, Vulog, Wunder Mobility, Motivate (Lyft), Bolt, Voi Technology, Ridecell, Helbiz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micromobility Platform Market Shifts & Advancements
Hardware-software convergence is compressing vendor margins while creating new monetization layers around fleet data and predictive maintenance services.
Modular battery architectures are rewriting competitive dynamics in shared micromobility. These systems enable sub-60-second swap operations that maximize vehicle utilization rates. Transit agencies in Paris and Berlin now specify hot-swappable packs as mandatory tender requirements. The technology is rewriting total cost of ownership calculations by eliminating depot-based charging infrastructure capex.
REACH battery substance restrictions are tightening material compliance burdens for platform providers selling into European markets. The regulation mandates disclosure and phase-out of hazardous chemistries in lithium-ion cells. Manufacturers are accelerating solid-state electrolyte research to preempt 2027 substance restriction deadlines. German and French regulators are coordinating enforcement mechanisms that will reshape supplier qualification criteria.
Outcome-based service contracts are displacing traditional hardware purchase models in municipal procurement. Fleet operators now demand guaranteed uptime percentages rather than per-vehicle warranties. This shift transfers operational risk to platform vendors while locking in recurring revenue streams. The model is most visible in Scandinavian cities where public-private partnership frameworks dominate transit infrastructure development.
Micromobility Platform Market Segmentation
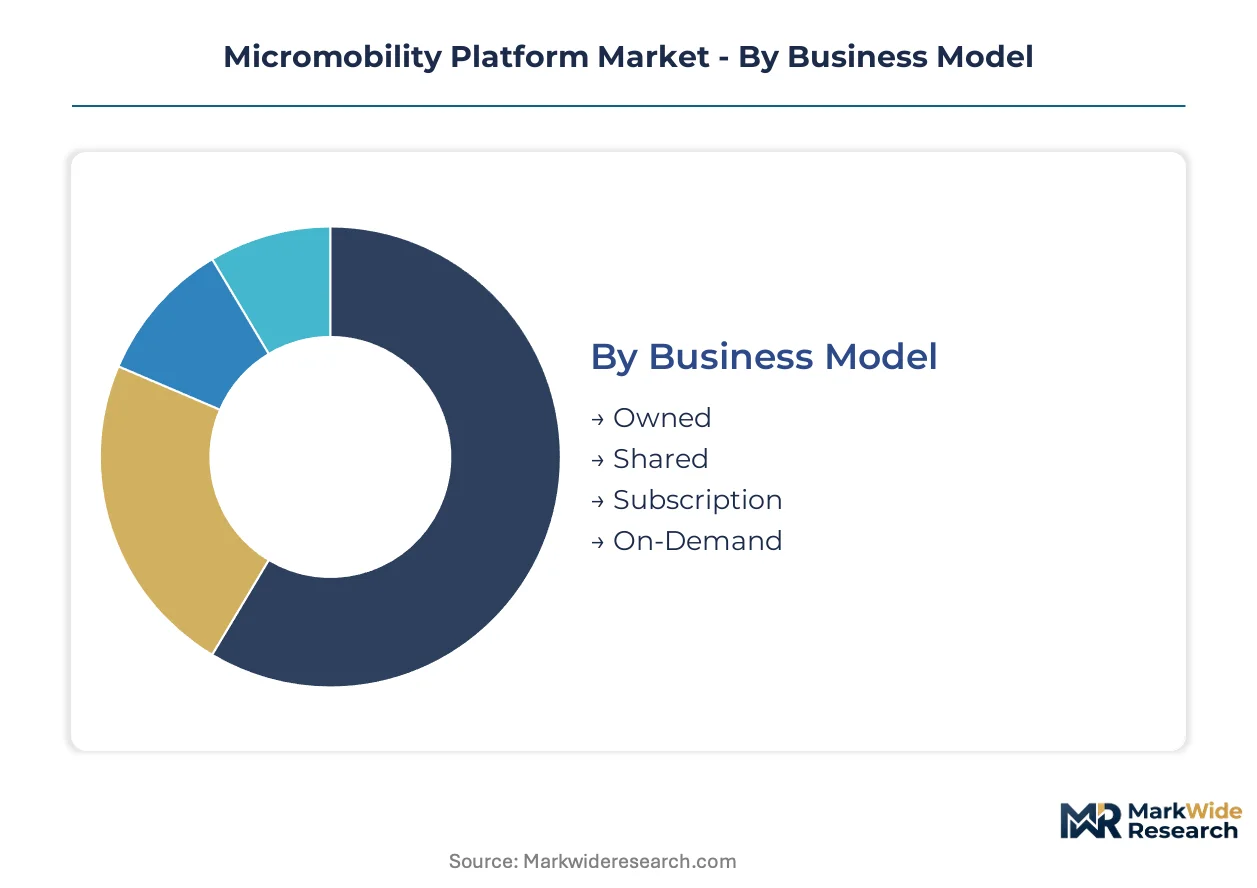
Micromobility platforms serve divergent operational logics across ownership structures, vehicle architectures, and end-user profiles. Segmentation reveals where hardware-software integration requirements concentrate procurement power and how battery-swappable architectures rewrite competitive positioning.
Business Model:
Customization intensity varies from fully standardized shared fleets to bespoke subscription bundles negotiated by large fleet operators.
- Owned:Direct consumer purchase of connected vehicles with embedded fleet management software for personal use. Demand clusters in German and French urban cores where commuters seek predictable last-mile solutions without per-ride pricing volatility.
- Shared:Dockless or station-based vehicle pools accessed through mobile applications with automated payment settlement. Municipal tenders in Paris, Berlin, and Singapore now mandate battery-swappable architectures, concentrating procurement around vendors with captive manufacturing.
- Subscription:Fixed-fee bundling of hardware, insurance, and predictive maintenance services. Fleet operators in Spain and Italy are migrating from per-ride revenue to this structure for predictable operating expenditure.
- On-Demand:Dynamic vehicle deployment triggered by real-time demand signals rather than fixed station networks. Logistics networks in Seoul and London contract these arrangements for e-commerce fulfillment density.
Most installed capacity flows through Shared. Expansion is steepest in Subscription.
Vehicle Type:
Cost tier separation runs from premium pedal-assist configurations to economy-grade standing scooters with minimal telemetry.
- E-Scooter:Standing electric kick scooters with integrated GPS modules and brake-regeneration systems. Volume leadership persists across temperate-climate deployments, though hilly corridors in Lisbon and San Francisco are shifting procurement specifications.
- E-Bike:Pedal-assist bicycles with torque sensors and extended-range battery packs. Premium positioning commands municipal fleet contracts in Rome and hilly North American metros where trip distances exceed five kilometers.
- E-Moped:Seated electric two-wheelers with higher speed classifications requiring helmet compliance. Southeast Asian logistics networks favor these for parcel density in Jakarta and Bangkok congestion zones.
- Unicycle:Self-balancing single-wheel devices with gyroscopic stabilization. Niche adoption concentrates among tech-forward commuters in Shenzhen and Seoul seeking minimal parking footprints.
E-Scooter retains the broadest installed base. E-Bike climbs the fastest in premium corridor tenders.
Technology:
Margin concentration tracks hardware-software integration depth, with pure software plays facing compression against vertically integrated stacks.
- GPS Tracking:Real-time telemetry modules enabling geofencing, theft recovery, and demand prediction algorithms. Cellular IoT cost curves now support profitable deployment in secondary cities previously considered margin-negative.
- Mobile App:User-facing interfaces for vehicle unlocking, route planning, and payment settlement. White-label specialization dominates transit agency procurement in Scandinavia where public-private partnerships require branded citizen experiences.
- IoT Connectivity:Cellular and Bluetooth protocols linking vehicle controllers to cloud-based fleet management systems. UN 38.3 and IEC 62133 certification timelines extend hardware validation cycles, delaying scaling for non-integrated vendors.
- Charging Solutions:Depot infrastructure and battery swap station networks. Hot-swappable pack specifications in Paris and Berlin tenders are eliminating depot-based capex from total cost of ownership calculations.
Most procurement specifications embed GPS Tracking as baseline. Charging Solutions is gaining share fastest as swap architectures displace plug-in models.
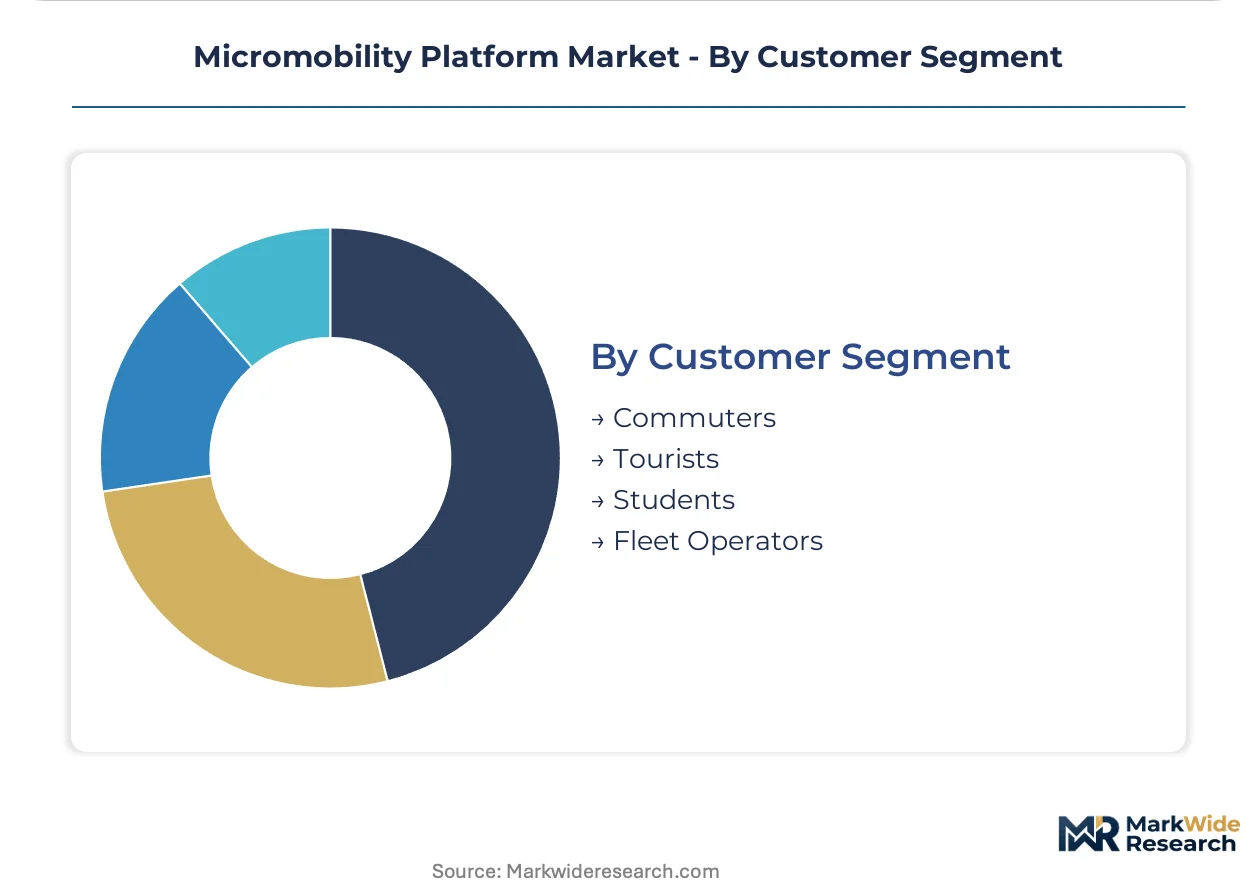
Customer Segment:
Application context determines hardware durability requirements and software feature prioritization across consumer and commercial endpoints.
- Commuters:Daily work-trip users requiring reliability guarantees and subscription pricing. Copenhagen and Vienna municipal standards favor open-protocol interoperability for this segment to reduce vendor lock-in.
- Tourists:Short-duration recreational users with lower frequency but higher per-trip willingness to pay. Seasonal demand spikes in Mediterranean coastal cities drive fleet rebalancing algorithms.
- Students:Price-sensitive campus-based users concentrated in university towns with closed-loop service territories. Institutional procurement in Dutch university clusters specifies durability standards above consumer-grade hardware.
- Fleet Operators:Commercial entities managing vehicle pools for logistics or shared mobility services. Outcome-based contracts with guaranteed uptime percentages are displacing per-vehicle warranties in this segment.
Commuters represent the largest addressable base. Fleet Operators are expanding most quickly as logistics densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Micromobility platforms trace their commercial scaling to dockless e-scooter deployments that began in Santa Monica and San Francisco during 2017. Those California pilots established the hardware-software integration model now replicated across temperate-climate cities worldwide.
United States
Municipal procurement in Austin, Denver, and Chicago now mandates battery-swappable architectures for shared fleet contracts. The US DOT coordinates with EPA on emissions credits that subsidize electric fleet conversions in metropolitan transit districts. Lime anchors its manufacturing scale across multiple continents from its San Francisco operational base.
Germany
Berlin and Munich transit agencies embed hardware-software integration requirements directly into tender documents. The KBA enforces non-harmonized battery safety certification pathways that multiply compliance costs for hardware providers entering European markets. Voi Technology exemplifies vendors with captive manufacturing favored by German municipal specifications.
France
Parisian tenders now specify hot-swappable battery packs as mandatory requirements, eliminating depot-based charging infrastructure capex. The ANSM enforces divergent certification pathways from German regulators that fragment hardware compliance costs. Lime and Dott compete for contracts in the Île-de-France region where subscription bundling is gaining traction.
Singapore
E-commerce fulfillment networks contract micromobility platforms to reduce delivery vehicle congestion in urban cores. The Land Transport Authority mandates interoperable charging protocols that reduce vendor lock-in for fleet operators. Battery-swappable e-scooter architectures dominate procurement specifications in this Southeast Asian logistics hub.
United Kingdom
London's transit authority consolidates procurement around open-protocol dockless standards that reduce single-supplier stranded asset risk. The Department for Transport coordinates micromobility trials with binding safety specifications for vehicle telemetry. Wunder Mobility and Vulog compete for white-label software contracts with Transport for London.
Micromobility Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hardware-software integration depth. Vertically integrated vendors with captive manufacturing control unit economics while pure software plays face margin compression against integrated stacks. Three archetypes dominate: manufacturing-scale operators, white-label software specialists, and hybrid hardware-software platforms. Consolidation pressures favor M&A activity among regional fleet operators and strategic partnerships between vehicle manufacturers and transit agencies.
Within the manufacturing-scale tier, Lime and Bird exemplify vendors leveraging production volume across multiple continents. Vulog occupies a distinct position as a white-label software specialist for transit agencies requiring branded citizen experiences. These three anchors represent divergent strategic bets on where margin pools concentrate as municipal procurement tightens around integrated capabilities.
| Leading Market Players |
|---|
| Lime |
| Bird |
| Vulog |
| Wunder Mobility |
| Motivate (Lyft) |
| Bolt |
| Voi Technology |
| Ridecell |
| Helbiz |
| Others |
Supply & Pricing Matrix
Municipal battery-swappable mandates in Paris and Berlin are forcing hardware vendors to requalify manufacturing lines for hot-swap compatibility, compressing margins on legacy plug-in architectures while rewarding integrated producers with captive battery assembly.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vendors with full hardware-software integration from modular assemblers and white-label software providers. Price differentiation hinges on UN 38.3 certification status and guaranteed uptime percentages in outcome-based contracts. Cost compression in the economy tier is intensifying because cellular IoT module commoditization erodes telemetry hardware premiums. Fleet operators prove least price-sensitive when negotiating subscription bundles covering predictive maintenance, while municipal procurement teams drive hardest bargain on per-vehicle hardware costs.
Supply Chain Analysis
Dual-sourcing requirements in German and French tenders mandate that fleet operators qualify at least two battery cell suppliers, fragmenting procurement power away from single-source lithium-ion producers. Manufacturing concentrates in China for cellular IoT modules, South Korea for high-nickel cathode chemistries, and Taiwan for vehicle controller semiconductors. The supply chain draws from lithium carbonate spot markets, rare-earth magnet processors, and ABS polymer compounders. Single-source vulnerability sits with solid-state electrolyte precursor materials. Distribution runs through OEM direct contracts with transit agencies, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as municipal decarbonization deadlines in the EU Green Deal lock in replacement demand cycles across temperate-climate cities.
For Market Incumbents: Hedge against proprietary charging protocol fragmentation by accelerating interoperability certifications in Copenhagen and Vienna procurement pipelines. Deepen backward integration into swappable battery pack assembly to defend margin position against pure software entrants winning white-label municipal contracts. For New Entrants and Emerging Players: Launch via subscription bundling models targeting Spanish and Italian fleet operators migrating from per-ride revenue structures. Penetrate the e-bike corridor expansion segment in Lisbon and San Francisco where hilly topography commands premium hardware specifications and less saturated vendor competition. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated hardware-software platforms possessing captive manufacturing and ANSM-KBA dual certification. Five-to-ten year viability favors vendors locking recurring revenue through outcome-based uptime guarantees rather than transactional hardware sales. Watch for solid-state electrolyte breakthrough signals as inflection indicator for next-generation battery chemistry winners.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swap Infrastructure Deployment | Paris and Berlin tenders now mandate hot-swappable architectures, eliminating depot capex from operator calculations. |
| White-Label Software Specialization | Scandinavian transit agencies demand branded citizen experiences, favoring Vulog-type vendors over integrated platforms. |
| Interoperable Charging Protocol Adoption | Singapore Land Transport Authority standards reduce vendor lock-in and stranded asset risk for municipal fleets. |
| Subscription Bundling Migration | Spanish and Italian operators shift from per-ride to fixed-fee structures covering hardware, insurance, and predictive maintenance. |
| Solid-State Battery R&D Acceleration | REACH substance restrictions drive manufacturers toward electrolyte research ahead of 2027 compliance deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, municipal procurement officers, battery cell supplier account managers, and cellular IoT module vendors against secondary validation through EU tender databases, UN 38.3 certification registries, and SEC filings from listed micromobility operators. Bottom-up vehicle deployment counts triangulated against top-down market value estimates.
Comparable-period anchoring tied projection assumptions to historical fleet scaling patterns across temperate-climate deployments, modeling segmentation dimensions spanning business model archetypes, vehicle architecture types, integration technology depth, and customer application contexts. CAGRs derived from logistic diffusion curves fitted to municipal adoption timelines, with forecast inputs incorporating lithium-ion cell cost curves and cellular data plan economics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery thermal runaway regulatory acceleration or lithium carbonate supply disruption scenarios. Deviation in EU Green Deal implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Smart Car Tracking Systems Market