
 CV Brake Controls Market | 2026-2036
CV Brake Controls Market Size, Share, and Industry Trends Forecast 2026-2036
CV Brake Controls Market Insights
Modular bundling of brake control hardware with telematics-ready electronics is hardening as the dominant procurement pattern for fleet operators. Bosch leverages captive semiconductor sourcing to anchor integrated module production across European truck platforms. ZF competes through R&D intensity in electromechanical brake architectures. Knorr-Bremse dominates pneumatic brake control supply for heavy-duty applications in Asia-Pacific manufacturing corridors.
CV brake controls encompass hydraulic, pneumatic, electric, and electromechanical actuation systems that modulate braking force through electronic control units processing wheel-speed sensor inputs and vehicle dynamics data, typically operating at pressure thresholds exceeding 12 bar in commercial configurations. These systems serve the primary industrial purpose of preventing wheel lock-up, maintaining directional stability, and reducing stopping distances under variable load conditions. Pneumatic brakes retain the largest installed base among heavy-duty trucks and buses due to decades of platform standardization, while electromechanical brakes represent the fastest-growing technology segment as OEMs pursue weight reduction and maintenance interval extension. The aftermarket provider channel captures concentrated margin pools in brake control refurbishment and remanufacturing, particularly for ABS modules approaching end-of-design-life in aging North American and European fleets.
NHTSA, the EU's F-Gas Regulation, and China's MIIT shape demand through divergent compliance pathways—NHTSA mandates electronic stability control fitment, the F-Gas Regulation constrains pneumatic system refrigerant-linked components, and MIIT accelerates domestic electromechanical brake certification timelines. These regulatory frameworks fragment product homologation requirements and elevate engineering overhead for suppliers serving multiple manufacturing jurisdictions. Stakeholders must monitor divergence between brake-by-wire technical standards under development in ISO committees and national implementation schedules to calibrate platform investment sequencing.
Market Dynamics
Electromechanical brake architectures are displacing pneumatic systems as OEMs pursue weight reduction targets and extended maintenance intervals, compressing platform refresh cycles and forcing suppliers to reconfigure module production lines.
Growth Catalysts
- NHTSA electronic stability control mandates:Mandates for heavy-duty commercial vehicles are accelerating module replacement demand across North American fleets. Retrofit requirements for aging trucks sustain aftermarket volume.
- Telematics integration:Fleet operators now specify brake control hardware bundled with data-ready electronics. This procurement pattern elevates module ASPs and locks in multi-year supplier contracts.
- China MIIT electromechanical certification acceleration:Domestic OEMs are fast-tracking brake-by-wire platforms to meet dual carbon goals. Local content requirements channel procurement toward certified indigenous suppliers.
Market Restraints
- Semiconductor input volatility:ECU production depends on automotive-grade chip supply concentrated in Taiwan and South Korea foundries. Price swings and allocation constraints disrupt module delivery schedules.
- Pneumatic installed base inertia:Decades of heavy-duty platform standardization around compressed air systems create technical and training barriers to electromechanical conversion in established fleets.
- F-Gas Regulation compliance friction:EU constraints on refrigerant-linked pneumatic components force dual-track engineering for European versus export market configurations.
Strategic Opportunities
- Indian heavy-duty fleet expansion:Domestic truck production growth under PLI scheme incentives creates demand for ABS and stability control modules. Local assembly partnerships bypass import duty exposure.
- ISO brake-by-wire standard convergence:Pending technical harmonization across ISO committees offers first-mover advantage for suppliers with pre-certified electromechanical architectures.
- Remanufacturing channel development:End-of-design-life ABS modules in aging North American and European fleets represent concentrated margin pools for aftermarket providers with refurbishment capabilities.
Industry Challenges
- Mechatronics engineering scarcity:Electromechanical brake development requires rare combinations of mechanical design, embedded software, and functional safety expertise. Competition with automotive and aerospace sectors intensifies recruitment.
- Multi-jurisdiction homologation timelines:Divergent NHTSA, EU type-approval, and MIIT certification pathways extend product launch cycles. Engineering overhead multiplies for suppliers serving multiple manufacturing bases.
- Legacy pneumatic integration complexity:Electromechanical retrofits must interface with existing air reservoir and line infrastructure. Custom adaptation for mixed fleet environments strains technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CV Brake Controls Market |
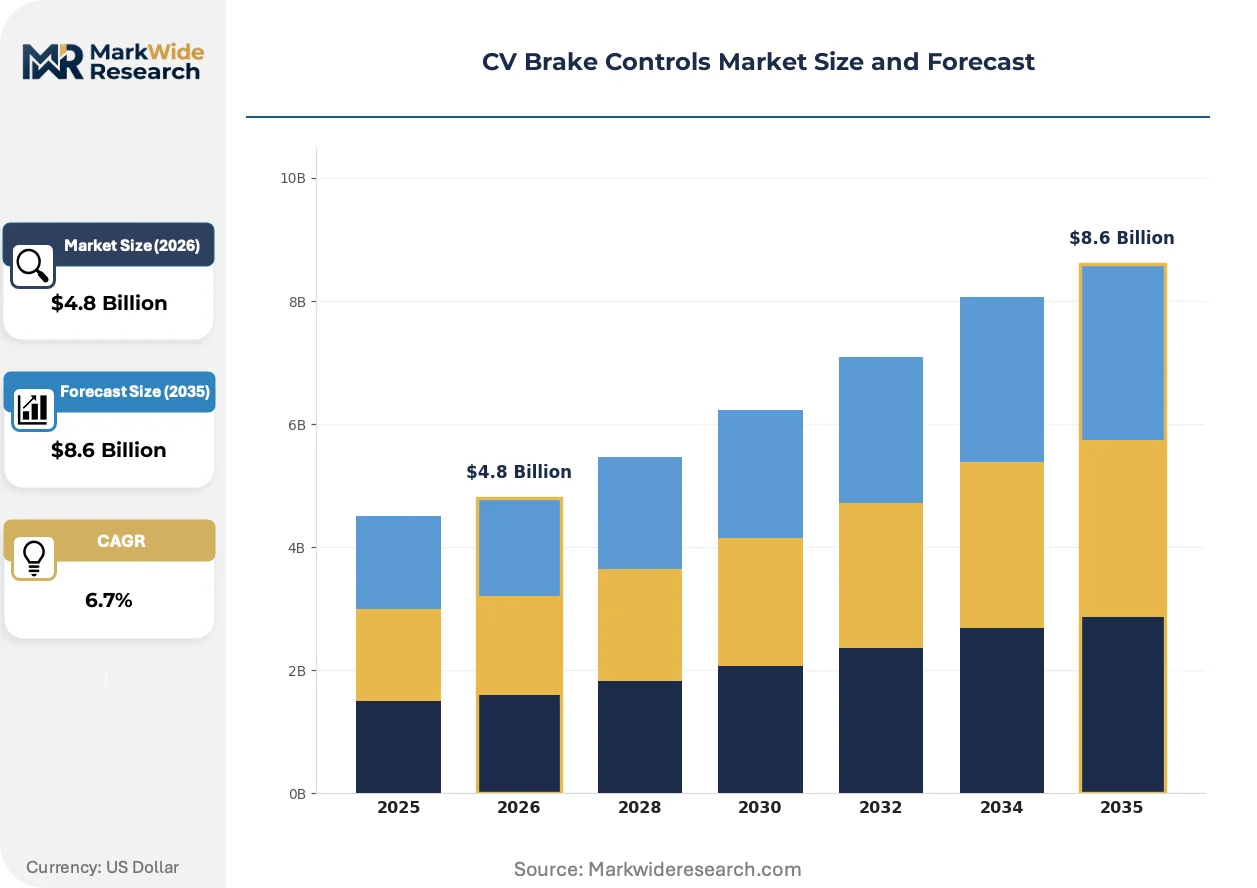
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Brakes, Pneumatic Brakes, Electric Brakes, Electromechanical Brakes End User: OEMs, Aftermarket Providers, Fleet Operators, Third-Party Repair Shops Technology: Anti-lock Braking System, Traction Control System, Electronic Stability Control, Brake by Wire Application: Heavy-Duty Trucks, Buses, Trailers, Construction Vehicles |
| Companies Covered | Bosch, ZF, Wabco, Continental, Hyundai Mobis, ADVICS, Knorr-Bremse, Hitachi, Mando, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CV Brake Controls Market Trends and Innovations
Brake control technology is converging with vehicle electrification architectures and connected fleet infrastructure, compressing the boundary between safety-critical hardware and data-generating electronics.
Electromechanical brake actuation is absorbing engineering investment across European and Chinese truck platforms. These systems eliminate pneumatic compressors and air lines, cutting vehicle weight by substantial margins. ZF and continental Tier 1s are scaling production for 2027-2028 platform launches. The technology is absorbing service revenue from traditional pneumatic maintenance intervals, redirecting fleet spend toward predictive analytics subscriptions.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent pneumatic component redesigns. Suppliers must reformulate seal materials and lubricant specifications to maintain compliance. Heavy-duty applications serving intra-EU freight corridors face the tightest retrofit deadlines, compressing procurement decisions for fleet renewal programs.
Fleet procurement patterns are fragmenting across ownership models. Large for-hire carriers with in-house maintenance capabilities specify integrated telematics-ready modules direct from Tier 1s. Smaller owner-operator segments remain captive to dealer channel distribution with bundled service contracts. This bifurcation is most pronounced in Germany and the United States, where fleet concentration varies sharply by trucking segment.
CV Brake Controls Market Segmentation
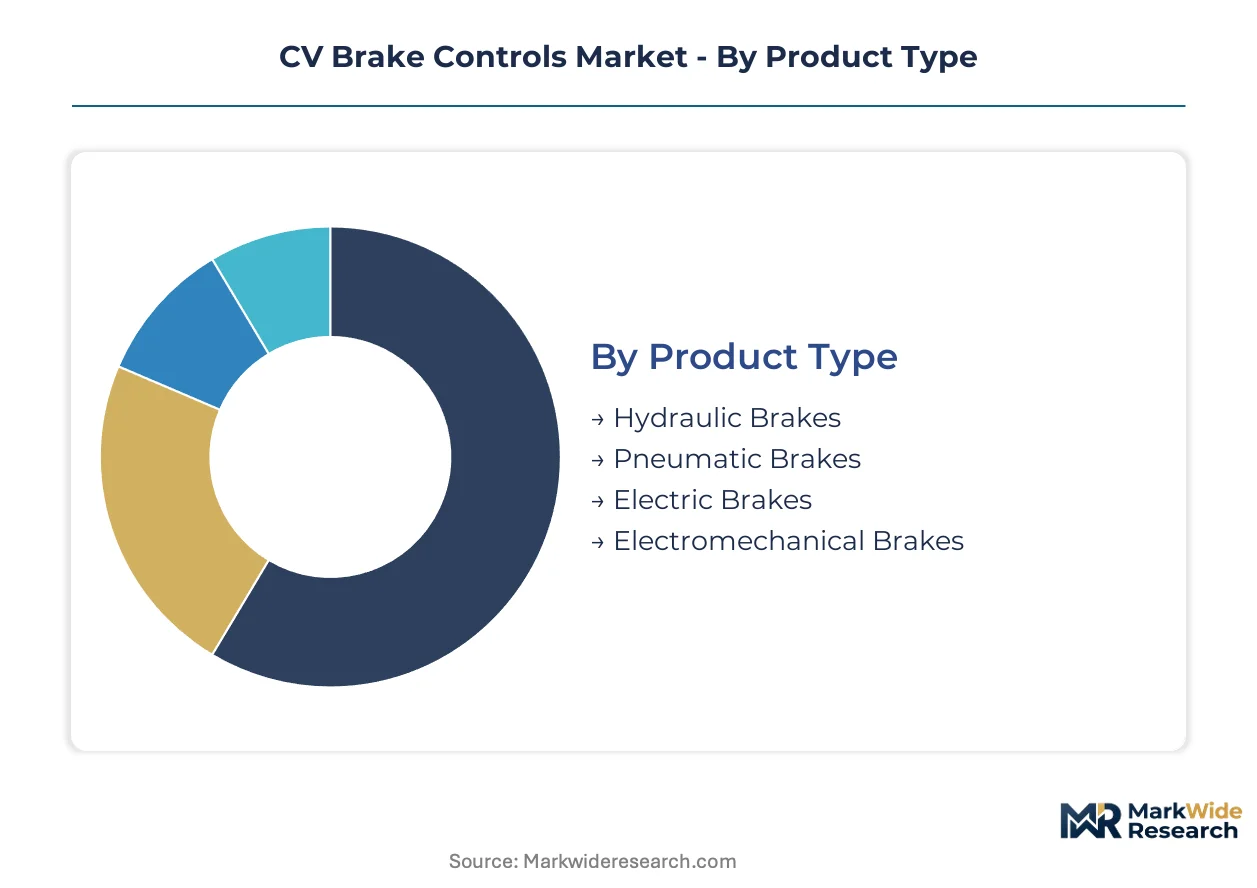
CV brake control suppliers must align production assets with divergent capital requirements across actuation technologies. Procurement patterns fragment between OEM direct sourcing and aftermarket refurbishment channels. Technology choices determine semiconductor content, software validation cycles, and regulatory homologation pathways.
Product Type:
Pneumatic systems demand the heaviest upfront investment in compressor manufacturing and air handling infrastructure. Electromechanical architectures concentrate R&D spend on motor control electronics and functional safety certification.
- Hydraulic Brakes:Fluid-based actuation dominates medium-duty commercial configurations below 12 bar operating pressure. Demand concentrates in German urban delivery fleets where compact packaging and rapid response times outweigh pneumatic reliability advantages. NHTSA stability control mandates accelerate module replacement in aging North American hydraulic installations.
- Pneumatic Brakes:Compressed air systems retain the largest installed base among heavy-duty trucks and buses through decades of platform standardization. China and the United States host the densest manufacturing corridors for pneumatic control modules. EU F-Gas Regulation constraints on refrigerant-linked components force dual-track engineering for European versus export market configurations.
- Electric Brakes:Motor-driven actuation serves specialized low-speed applications in yard tractors and terminal equipment. Integration complexity limits penetration in over-the-road freight segments.
- Electromechanical Brakes:Brake-by-wire architectures eliminate pneumatic infrastructure, cutting vehicle weight and extending maintenance intervals. ZF and Continental are scaling production for European and Chinese truck platform launches.
Most installed capacity flows through Pneumatic Brakes. Expansion is steepest in Electromechanical Brakes.
End User:
Fleet operators concentrate procurement volume through multi-year supplier contracts with embedded telematics requirements. Aftermarket providers capture margin pools in module refurbishment and remanufacturing.
- OEMs:Vehicle manufacturers specify integrated brake control modules bundled with warranty and service agreements. Bosch anchors European truck platform supply through captive semiconductor sourcing. Platform refresh cycles compress as electromechanical architectures displace pneumatic standards.
- Aftermarket Providers:Independent distributors and remanufacturers serve end-of-design-life ABS modules in aging North American and European fleets. Margin concentration in refurbishment capabilities offsets lower ASPs versus new module sales.
- Fleet Operators:Large for-hire carriers with in-house maintenance capabilities procure telematics-ready modules direct from Tier 1 suppliers. Specifications emphasize predictive analytics integration and multi-year service contracts.
- Third-Party Repair Shops:Dealer-affiliated and independent service channels serve owner-operator segments with bundled parts and labor offerings. Technical training gaps slow electromechanical retrofit adoption in mixed fleet environments.
Volume leadership sits with OEMs. Growth intensity clusters in Fleet Operators.
Technology:
Electronic Stability Control and Brake by Wire architectures absorb the steepest validation engineering for functional safety compliance. Anti-lock Braking Systems face margin compression from commoditization and remanufacturing competition.
- Anti-lock Braking System:Wheel-speed sensor-based modulation prevents lock-up under variable load conditions. Aftermarket refurbishment concentrates in modules approaching end-of-design-life in aging United States and German fleets.
- Traction Control System:Engine torque and brake intervention maintain drive wheel grip on low-friction surfaces. Standard fitment on premium heavy-duty configurations in China and the United States.
- Electronic Stability Control:Yaw rate and lateral acceleration sensors enable directional stability intervention. NHTSA mandates for heavy-duty commercial vehicles accelerate module replacement demand across North American fleets. Retrofit requirements sustain aftermarket volume in aging truck populations.
- Brake by Wire:Fully electromechanical actuation eliminates hydraulic and pneumatic lines, enabling integration with autonomous braking algorithms. China MIIT certification acceleration channels procurement toward indigenous suppliers meeting dual carbon goals.
Deployment breadth favors Electronic Stability Control. Engineering investment intensity peaks in Brake by Wire.
Application:
Heavy-duty trucks concentrate module ASPs through integrated telematics specifications. Construction vehicles impose the harshest environmental sealing and vibration durability requirements.
- Heavy-Duty Trucks:Class 8 freight configurations specify brake control modules with embedded fleet connectivity. United States for-hire carriers drive procurement of stability control and telematics-bundled systems. Electromechanical retrofits face technical barriers from existing air reservoir infrastructure in mixed fleet environments.
- Buses:Urban transit and coach applications prioritize passenger safety and regulatory compliance. EU F-Gas Regulation deadlines compress procurement decisions for intra-European corridor fleets.
- Trailers:Semitrailer ABS modules face cost pressure from commoditization while NHTSA mandates sustain replacement demand. Telematics integration lags tractor specifications due to power and connectivity constraints.
- Construction Vehicles:Off-highway braking systems endure extreme duty cycles, contamination exposure, and temperature swings. Specialized pneumatic and hydraulic architectures dominate versus electromechanical alternatives.
Module revenue concentrates in Heavy-Duty Trucks. Specification complexity peaks in Construction Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pneumatic brake systems originated in German heavy-duty engineering traditions during the early twentieth century. The technology diffused through North American long-haul corridors and Chinese manufacturing zones. Contemporary demand concentrates in three manufacturing jurisdictions with distinct regulatory pathways.
United States
Class 8 freight carriers drive module procurement through integrated telematics specifications. NHTSA electronic stability control mandates accelerate replacement cycles across aging truck populations. Detroit and Dallas-Fort Worth anchor dense clusters of brake control module assembly serving domestic OEM platforms.
Germany
Urban delivery fleets prioritize compact hydraulic configurations for medium-duty applications below 12 bar pressure thresholds. EU F-Gas Regulation constraints force dual-track engineering for refrigerant-linked pneumatic components. Stuttgart and Munich host engineering centers scaling electromechanical brake architectures for 2027 platform launches.
China
Domestic OEMs fast-track brake-by-wire certification to align with MIIT dual carbon timelines. Local content requirements channel procurement toward certified indigenous suppliers. Shanghai and Beijing manufacturing corridors concentrate electromechanical module production for export and domestic heavy-duty platforms.
India
Heavy-duty fleet expansion under PLI scheme incentives creates demand for ABS and stability control modules. Domestic truck production growth accelerates module procurement from local assembly partnerships. Tamil Nadu and Maharashtra industrial belts concentrate brake control manufacturing to bypass import duty exposure.
Japan
Premium heavy-duty configurations specify traction control systems as standard fitment for export-oriented truck platforms. METI technical standards influence electromechanical brake validation protocols across Asian supply chains. Nagoya and Tokyo metropolitan areas anchor R&D investment in motor control electronics for next-generation actuation systems.
CV Brake Controls Market Competitive Landscape
The competitive structure tilts toward integrated module suppliers with captive semiconductor sourcing and multi-jurisdiction homologation capabilities. Three archetypes dominate: diversified automotive conglomerates with brake control divisions, pneumatic system specialists defending installed base positions, and electromechanical pure-plays pursuing brake-by-wire certification. Consolidation pressure intensifies as platform refresh cycles compress and OEMs reduce supplier panels. Strategic moves center on backward integration into ECU semiconductor supply and pre-certification of electromechanical architectures ahead of ISO standard convergence.
Among diversified conglomerates, Bosch, ZF, and Continental exemplify the integrated module supplier archetype. These Germany-based entities occupy positions spanning hydraulic, pneumatic, and electromechanical actuation technologies. Their scale enables multi-year fleet contracts bundling brake hardware with predictive analytics subscriptions. Knorr-Bremse represents the pneumatic specialist archetype with concentrated presence in Asia-Pacific heavy-duty corridors. Hyundai Mobis and Mando anchor the Korea-based supplier tier serving domestic OEM platforms and export markets. Each archetype faces divergent investment imperatives: conglomerates balance legacy pneumatic service revenue against electromechanical R&D intensity, while specialists defend maintenance interval economics against brake-by-wire displacement.
| Leading Market Players |
|---|
| Bosch |
| ZF |
| Wabco |
| Continental |
| Hyundai Mobis |
| ADVICS |
| Knorr-Bremse |
| Hitachi |
| Mando |
| Others |
Pricing and Supply Chain Analysis
Fleet operator procurement consolidation around telematics-ready brake control modules is forcing suppliers to absorb semiconductor cost volatility while defending module ASPs through multi-year service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service depth. Premium tiers command substantial markups for NHTSA-certified electronic stability control with embedded predictive analytics, while economy modules face severe price erosion from remanufacturing competition in aging North American fleets. OEM direct procurement exhibits lowest price sensitivity; third-party repair shops serving owner-operators demonstrate highest elasticity.
Supply Chain Analysis
Automotive-grade semiconductor supply rests on Taiwan and South Korea foundries, with ECU production further tethered to German and Chinese PCB assembly corridors. Rare earth magnet dependencies for electromechanical motor control concentrate in Chinese processing facilities. Single-source vulnerability in 28nm automotive microcontroller supply creates delivery disruption risk. Distribution runs through OEM direct channels for new platforms and independent remanufacturers for aftermarket refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical brake platform standardization is compressing supplier margins on legacy pneumatic systems while opening premium-tier expansion through predictive maintenance subscriptions.
For Market Incumbents: Lock in captive semiconductor sourcing through backward integration into ECU chip supply or multi-year foundry offtake agreements. Accelerate pre-certification of brake-by-wire architectures ahead of ISO standard convergence to defend against emerging electromechanical pure-plays. Prioritize channel control in North American fleet operator direct procurement to offset margin compression from pneumatic maintenance interval erosion. For New Entrants and Emerging Players: Enter via remanufacturing channel partnerships serving end-of-design-life ABS modules in aging United States and German fleets, where technical refurbishment capabilities create defensible margin pools. Target Indian heavy-duty fleet expansion under PLI scheme incentives through local assembly joint ventures that bypass import duty exposure. Pursue telematics integration as the primary go-to-market wedge against incumbent hardware-only positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical brake pure-plays holding pre-certified architectures and MIIT qualification in China. Long-term viability hinges on 5-10 year platform refresh cycle compression toward brake-by-wire standardization. Monitor ISO committee technical harmonization timelines as the critical inflection signal for first-mover certification advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Captive ECU chip sourcing insulates Bosch and ZF from Taiwan foundry allocation constraints. |
| Brake-by-Wire Pre-Certification Investment | Early ISO compliance positioning enables ZF and Continental to lock 2027-2028 European platform launches. |
| Local Assembly Partnership in India | Tamil Nadu manufacturing presence allows suppliers to capture PLI scheme fleet expansion without duty exposure. |
| Remanufacturing Channel Development | Refurbishment capabilities in aftermarket providers capture concentrated margin from aging North American ABS modules. |
| Telematics-Ready Module Bundling | Fleet operator contracts embedding predictive analytics elevate ASPs and extend supplier lock-in duration. |
Research Methodology
Bottom-up fleet operator demand modeling reconciled against top-down Tier 1 supplier production tracking forms the analytical core. Primary interviews with brake control procurement managers at heavy-duty OEMs, aftermarket distribution channel heads, and fleet maintenance directors were validated against secondary sources including NHTSA regulatory filings, MIIT certification databases, and vehicle production registration data. Cross-referencing pneumatic and electromechanical platform announcements against semiconductor supply disclosures enabled triangulation of module volume assumptions.
Input-output matrix framing connects actuation technology segmentation with end-user procurement patterns across the projection horizon. Modeled dimensions span product type, technology architecture, application class, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted fleet replacement cycles and technology substitution curves. Forecast inputs incorporated NHTSA mandate compliance timelines, MIIT dual carbon certification acceleration, and EU F-Gas Regulation phase-down schedules.
Inputs from OEM platform engineering disclosures and Tier 1 supplier capacity announcements were available through the study window; gaps in proprietary fleet telematics adoption rates introduce uncertainty bands around connected module penetration assumptions. Forecasts reflect documented assumptions regarding semiconductor supply normalization and regulatory harmonization progress. Material deviation in ISO brake-by-wire standard convergence timelines or foundry allocation constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Snowplows Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Transmission Components Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Vehicle Trailer Hitch Market