
 Headlight Market | 2026-2036
Headlight Market Size, Share, and Industry Trends Forecast 2026-2036
Headlight Market Outlook
East Asian LED chip foundries is restructuring supply availability for tier-one automotive lighting suppliers. Koito Manufacturing leverages captive semiconductor sourcing to sustain high-volume contracts with Japanese and North American OEMs. HELLA GmbH & Co. KGaA anchors European premium adaptive lighting through specialized matrix-beam engineering. Valeo SA competes on cost-optimized LED platforms for mass-market passenger car programs.
A headlight is a forward-illumination assembly integrating a light source, reflector or projector optic, housing, and lens, engineered to deliver regulated beam patterns measured in candela and lux at specified distances. Its primary purpose is to ensure safe nighttime and adverse-weather visibility while minimizing glare for oncoming traffic. LED product types now dominate value generation due to thermal efficiency and design flexibility, though laser technology occupies the premium performance tier with extended throw distances. Adaptive lighting technology is maturing fastest among technology segments as OEMs integrate camera-fed beam shaping. The OEM market channel retains the deepest margin pools through long-term platform contracts and co-development agreements.
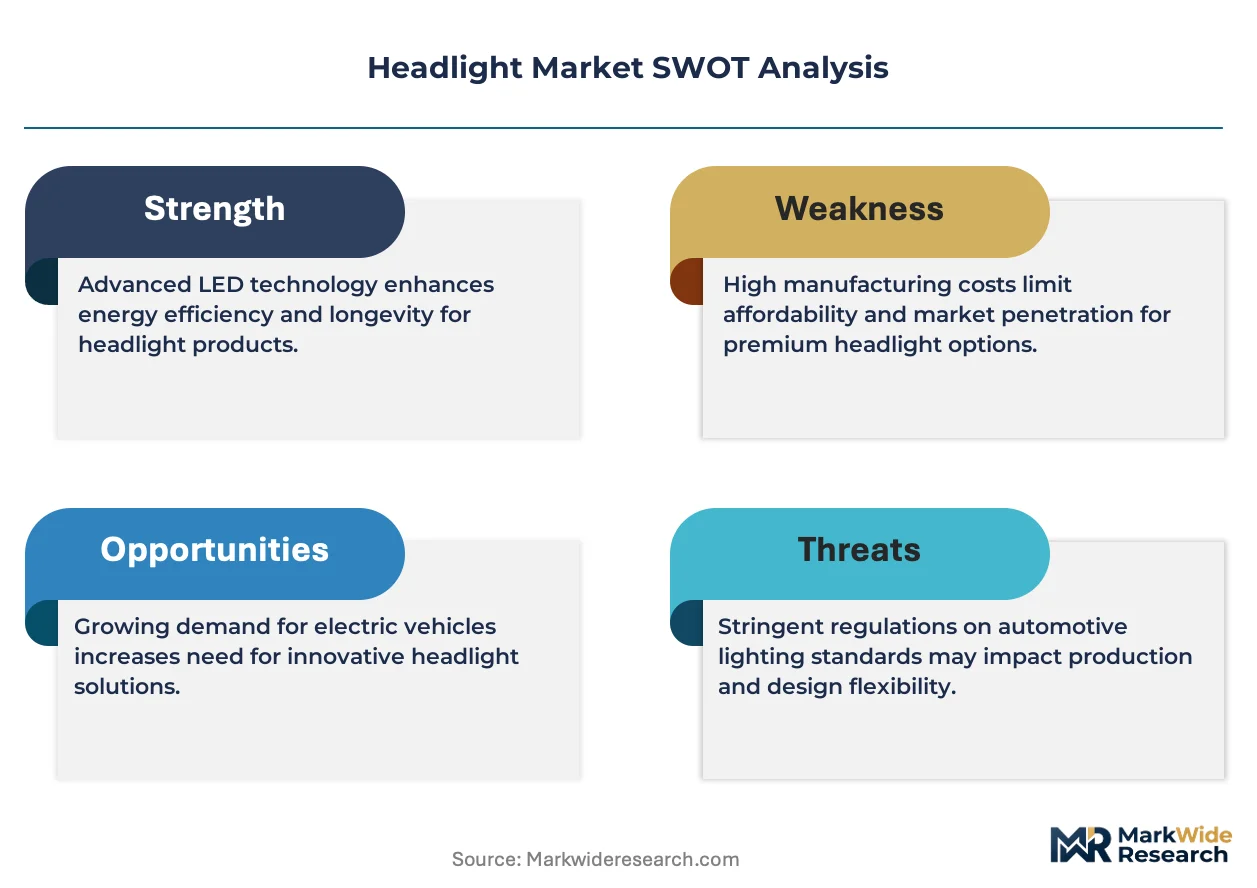
The US NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and replacement-equipment compliance, while the EU's UNECE R48 and R123 regulations mandate automatic leveling and adaptive front-lighting system certification for new vehicle types. Japan's MLIT enforces comparable beam standards through Safety Regulations for Road Vehicles, creating a triad of technical barriers that filter market access. Stakeholders must monitor divergence between US self-certification and EU type-approval processes when planning platform-common lighting architectures.
Market Dynamics
Adaptive front-lighting system mandates from China's MIIT and Germany's KBA are compressing development cycles for tier-one suppliers, forcing simultaneous compliance with divergent photometric standards across export markets.
Growth Catalysts
- MIIT Beam-Pattern Mandates:China's tightened safety regulations now require automatic leveling for new passenger car platforms, pulling adaptive LED volumes into domestic OEM supply chains.
- Camera-Fed Beam Shaping:Machine vision integration enables real-time glare-free high beams, creating upgrade pull from premium vehicle segments.
- East Asian Foundry Capacity:Semiconductor supply restructuring near Japanese and Korean automotive clusters reduces lead times for LED driver IC procurement.
Market Restraints
- Thermal Management Costs:High-brightness LED arrays require active cooling subsystems, adding material cost pressure at mass-market price points.
- Single-Source Laser Diodes:Premium laser headlight modules depend on concentrated specialty chip supply from limited qualified vendors.
- UNECE R48/R123 Compliance Friction:EU type-approval timelines for adaptive systems extend platform launch schedules versus US self-certification pathways.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for automotive component manufacturing attract adaptive lighting assembly to Pune and Chennai supplier parks.
- Software-Defined Lighting:Over-the-air beam-pattern updates enable recurring revenue models from feature unlocking post-vehicle sale.
- Commercial Vehicle Retrofit:Heavy truck fleets in Germany and Japan face nighttime visibility liability exposure, creating aftermarket demand for LED conversion kits.
Industry Challenges
- Optomechanical Design Talent:Shortage of engineers combining photonics simulation with automotive thermal and vibration engineering compresses R&D throughput.
- Dual-Certification Burden:Simultaneous NHTSA FMVSS 108 and UNECE R123 homologation requires parallel test fleets, doubling validation capex per platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Headlight Market |
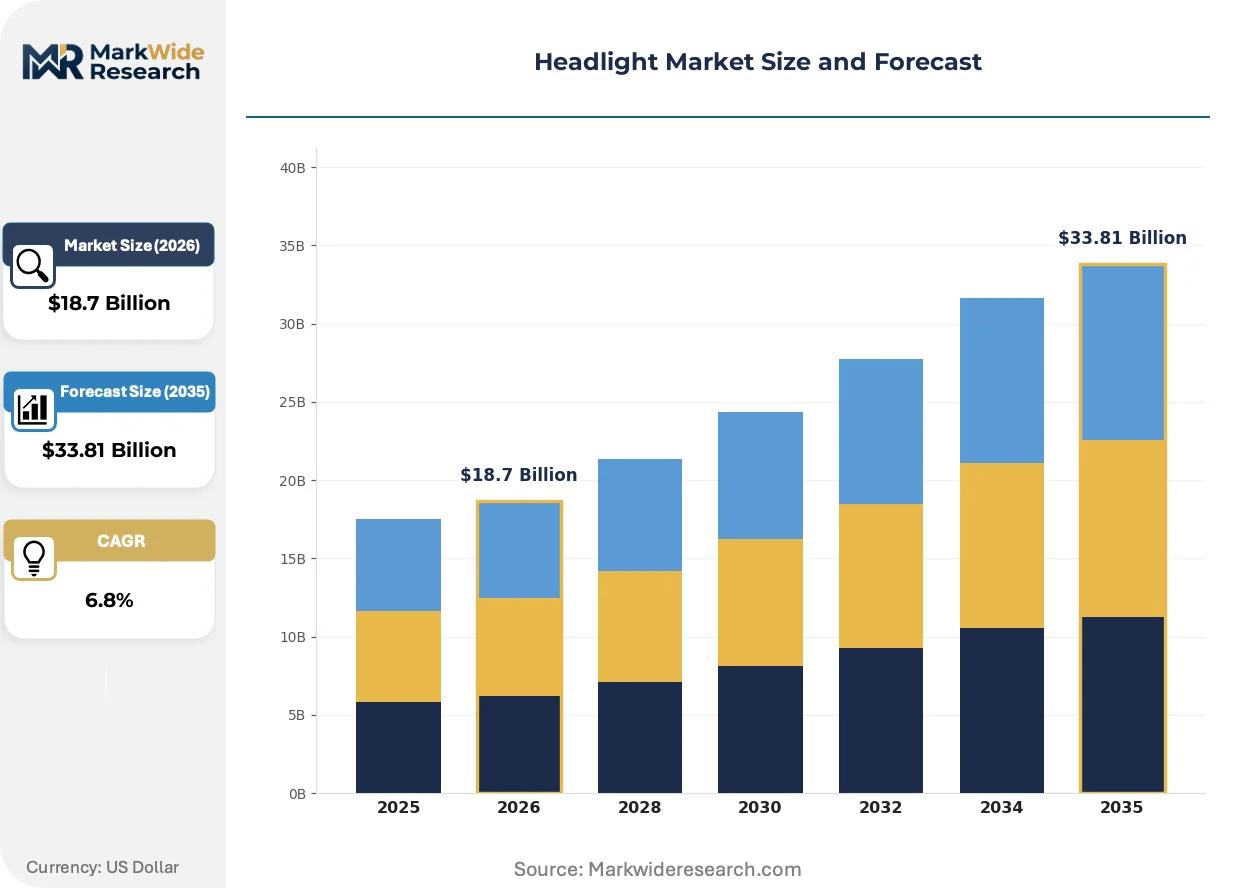
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, LED, Xenon, Laser Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Trucks Market Channel: OEM, Aftermarket, Retail, E-commerce Technology: Adaptive Lighting, Smart Headlights, Matrix Technology, High Beam Assistance |
| Companies Covered | Koito Manufacturing Co., Ltd., HELLA GmbH & Co. KGaA, Valeo SA, Robert Bosch GmbH, DENSO Corporation, Continental AG, Hyundai Mobis, Stanley Electric Co., Ltd., Marelli Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Headlight Market Strategic Shifts
Digital light processing is replacing analog reflector designs across price tiers, while regulatory divergence between US and EU certification pathways forces modular platform architectures that accommodate both standards.
Matrix LED technology is consolidating high-beam functionality into pixelated arrays that selectively mask oncoming traffic without mechanical shutters. German premium OEMs now specify 84-pixel and 1024-pixel variants as standard equipment. This shift is consolidating supplier margins toward software-controlled optic design and away from stamped metal reflector tooling.
UNECE R123 revisions are tightening adaptive front-lighting system certification requirements for pedestrian detection response times. European type-approval authorities now mandate documented camera-to-beam latency below 250 milliseconds. Test house capacity bottlenecks in Germany and the Netherlands are extending homologation queues for new entrants.
Fleet procurement of lighting systems is fragmenting as commercial vehicle operators unbundle headlamp supply from full-truck contracts. Logistics operators in Japan and Germany now source LED modules directly through automotive lighting distributors rather than OEM captive parts organizations. This channel shift is visible most acutely in refrigerated transport segments where downtime costs accelerate component replacement cycles.
Headlight Market Segmentation
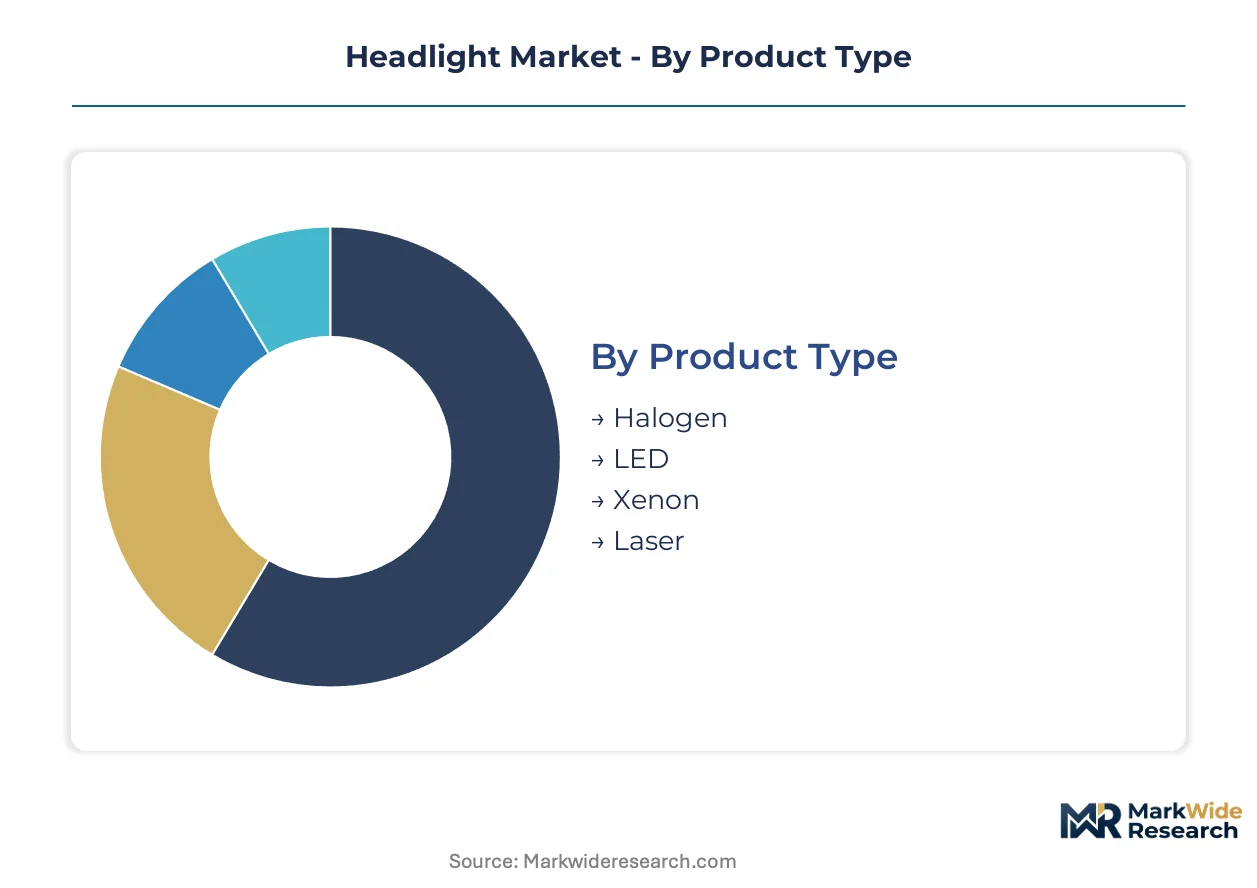
Headlight procurement patterns diverge sharply between mass-market volume programs and premium adaptive platforms. Technology selection cascades through thermal budgets, regulatory certification pathways, and long-term platform contracts with distinct margin profiles.
Product Type:
LED modules command the premium tier on thermal efficiency and design flexibility, while halogen retains volume dominance in emerging-market vehicle programs.
- LED:Solid-state semiconductor arrays deliver 130+ lumens per watt with active thermal management. Demand concentrates in German premium OEM platforms and Chinese MIIT-compliant passenger car lines where automatic leveling is now mandatory. Adaptive beam-shaping firmware locks suppliers into multi-year co-development agreements.
- Halogen:Tungsten-halogen filament technology dominates entry-level vehicle segments across India and Southeast Asian manufacturing clusters. Cost engineering limits adoption of active cooling subsystems, constraining brightness upgrades without housing redesign.
- Xenon:High-intensity discharge arc lamps retain niche presence in commercial vehicle retrofit channels where operators prioritize throw distance over energy efficiency.
- Laser:Phosphor-converted laser diodes extend high-beam range beyond 600 meters for German luxury OEMs, though concentrated chip supply from qualified vendors constrains volume scaling.
Mature deployment sits with halogen architectures across emerging-market vehicle platforms. Newer deployment is concentrated in laser-augmented LED systems for European premium segments.
Vehicle Type:
Passenger car OEMs drive adaptive lighting adoption through camera-fed beam shaping, while commercial vehicle operators prioritize durability and field-serviceability over intelligent features.
- Passenger Cars:Matrix LED and pixelated high-beam systems are standard equipment on German premium platforms. Chinese domestic OEMs are pulling adaptive LED volumes into supply chains under tightened MIIT safety mandates.
- Commercial Vehicles:Heavy truck fleets in Germany and Japan face nighttime visibility liability exposure, creating aftermarket demand for LED conversion kits with simplified thermal architectures.
- Motorcycles:Compact LED modules with passive cooling dominate two-wheeler applications across Indian and Southeast Asian manufacturing hubs where housing space constraints limit adaptive feature integration.
- Trucks:Long-haul operators in refrigerated transport segments source replacement modules directly through automotive lighting distributors rather than OEM captive parts organizations, accelerating replacement cycles.
Volume concentration rests with passenger car platform contracts. Margin expansion is climbing the fastest in commercial vehicle retrofit channels where fleet operators unbundle lighting supply from full-vehicle procurement.
Market Channel:
OEM co-development agreements capture the deepest margin pools through multi-year platform lock-ins, while aftermarket channels fragment across distributor networks and direct fleet procurement.
- OEM:Tier-one suppliers sustain high-volume contracts through captive semiconductor sourcing and specialized matrix-beam engineering. Long-term agreements with Japanese and North American OEMs embed software-controlled optic design as a core differentiator.
- Aftermarket:LED conversion kits for heavy truck fleets bypass traditional OEM parts organizations. German and Japanese logistics operators now source modules directly to minimize downtime costs in refrigerated transport segments.
- Retail:Consumer-facing replacement lamps concentrate in markets with aging vehicle parc and less stringent adaptive lighting mandates.
- E-commerce:Direct-to-fleet procurement platforms are emerging for commercial vehicle operators seeking rapid component turnaround.
Established revenue capture sits with OEM channel contracts. Emerging volume is concentrating in aftermarket direct procurement as fleet operators seek supply chain disintermediation.
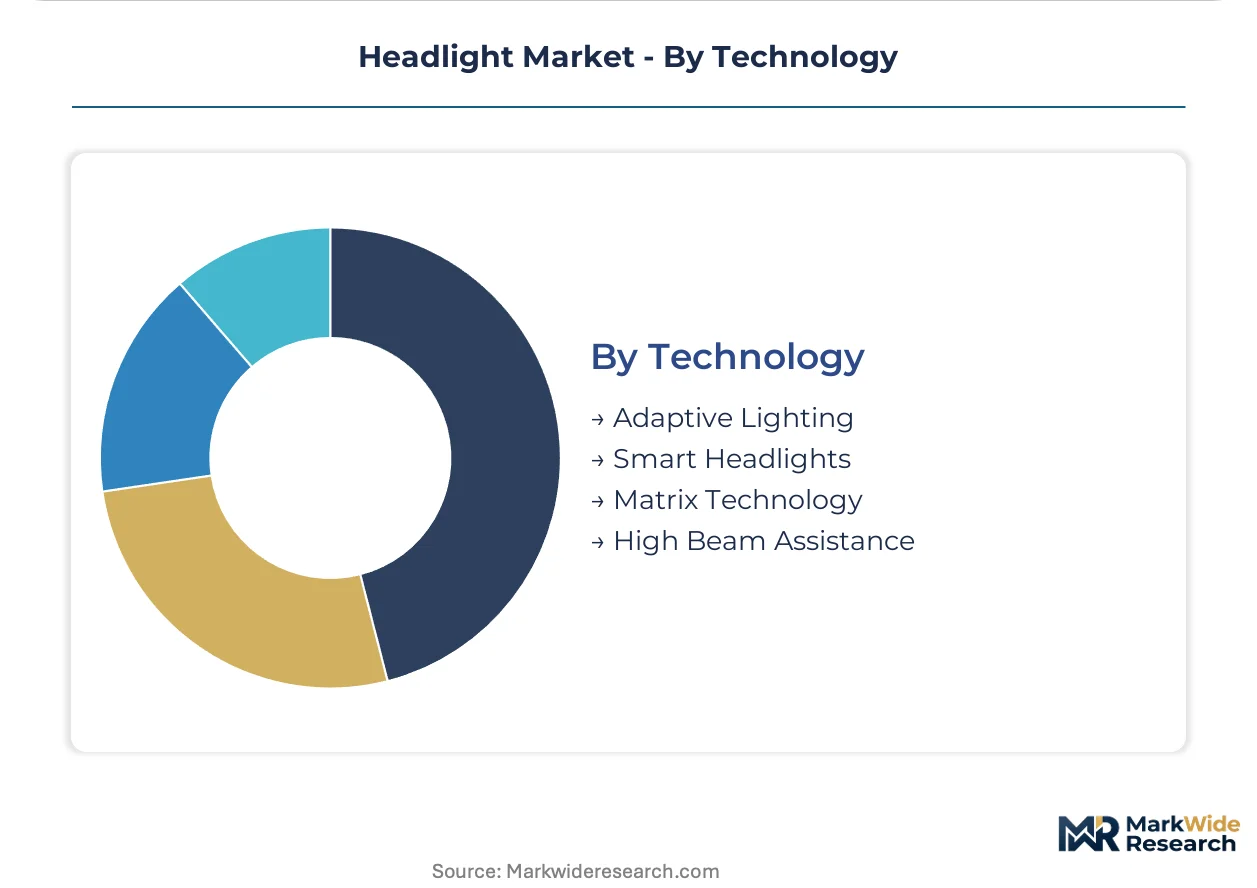
Technology:
Adaptive front-lighting systems are maturing fastest as camera-to-beam latency requirements tighten under revised UNECE R123 certification protocols.
- Adaptive Lighting:Camera-fed systems with sub-250 millisecond response times are now mandatory for new European vehicle type approvals. Test house capacity bottlenecks in Germany and the Netherlands extend homologation queues.
- Smart Headlights:Sensor fusion integrating radar and lidar inputs enables predictive beam adjustment for pedestrian detection scenarios.
- Matrix Technology:Pixelated LED arrays with 84-pixel and 1024-pixel variants selectively mask oncoming traffic without mechanical shutters, consolidating supplier margins toward software-controlled design.
- High Beam Assistance:Semi-automated systems bridge the gap between static halogen architectures and full adaptive platforms in mid-market vehicle segments.
Regulatory pressure is reshaping competitive positioning toward adaptive lighting certification. Feature unlocking through over-the-air updates is creating recurring revenue models from software-defined lighting architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity aluminum substrate foundries in Shandong Province anchor East Asian LED chip supply chains for automotive lighting modules. German automotive supplier networks concentrate matrix-beam engineering talent around Stuttgart and Ingolstadt. Japanese semiconductor packaging clusters in Aichi Prefecture sustain captive sourcing advantages for tier-one headlamp manufacturers.
China
MIIT automatic leveling mandates for new passenger car platforms are pulling adaptive LED volumes into domestic OEM supply chains. GB standards for automotive lighting safety tighten beam-pattern uniformity requirements annually. Yangtze River Delta manufacturing clusters near Shanghai host the densest concentration of LED driver IC packaging facilities serving global tier-one suppliers.
Germany
KBA homologation protocols for adaptive front-lighting systems compress development cycles for matrix-beam platform launches. UNECE R123 certification mandates sub-250 millisecond camera-to-beam latency for pedestrian detection response. Stuttgart and Ingolstadt supplier parks concentrate specialized optic engineering talent for premium OEM pixelated array specifications.
Japan
MLIT Safety Regulations for Road Vehicles enforce candela and lux performance standards comparable to EU type-approval requirements. METI industrial policy supports domestic semiconductor foundry capacity for automotive-grade LED substrates. Aichi Prefecture packaging clusters enable Koito Manufacturing's captive sourcing model for North American and Japanese OEM contracts.
United States
NHTSA FMVSS 108 self-certification pathways allow faster platform launches than EU type-approval timelines for adaptive lighting systems. Michigan and Ohio automotive corridors concentrate headlamp assembly operations for Detroit Three OEM programs. LED conversion kit demand from commercial vehicle fleets bypasses traditional OEM parts organizations through direct distributor procurement.
India
PLI scheme production-linked incentives for automotive component manufacturing attract adaptive lighting assembly to Pune and Chennai supplier parks. BIS certification requirements for replacement headlamps create technical barriers for unorganized aftermarket suppliers. Tamil Nadu automotive clusters near Chennai host emerging LED module testing facilities for export-oriented tier-two suppliers.
Headlight Market Competitive Environment
Global majors compete with regional champions across certification expertise and captive semiconductor sourcing. The vendor base structures around three tiers: integrated lighting system suppliers with captive LED packaging, specialized optic engineering houses focused on matrix-beam firmware, and scale-driven assembly operators serving mass-market platforms. Strategic moves concentrate on backward integration into LED driver IC supply and multi-year co-development agreements locking in OEM platform contracts.
Within the integrated lighting tier, Koito Manufacturing Co., Ltd. exemplifies the captive sourcing archetype through Aichi Prefecture semiconductor packaging control. HELLA GmbH & Co. KGaA anchors European premium adaptive lighting positioning through specialized matrix-beam engineering capabilities. Valeo SA occupies the cost-optimized platform tier, competing on LED module standardization for mass-market passenger car programs. These three represent distinct competitive vectors: vertical semiconductor control, optic firmware specialization, and manufacturing scale efficiency.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| Robert Bosch GmbH |
| DENSO Corporation |
| Continental AG |
| Hyundai Mobis |
| Stanley Electric Co., Ltd. |
| Marelli Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Matrix-beam firmware commoditization is simultaneously collapsing engineering premiums and concentrating procurement leverage among OEMs with multi-year platform lock-ins, forcing tier-one suppliers to unbundle hardware from software licensing to defend margin pools.
Pricing Analysis
Warranty and calibration-service bundling separates premium adaptive LED contracts from mass-market unbundled transactions. Three-tier pricing structure across adaptive matrix, standard LED, and halogen replacement levels reflects certification grade divergence under UNECE R123 versus FMVSS 108 pathways. Pricing pressure stems from thermal management cost inflation at volume price points. Fleet procurement teams in refrigerated transport segments exhibit highest price sensitivity; German premium OEM platform engineers show lowest.
Supply Chain Analysis
Reverse-logistics flows for LED driver IC returns and remanufactured projector housings concentrate refurbishment capacity in Guangdong Province and Bavaria. High-purity aluminum substrate supply draws from Shandong Province, Aichi Prefecture, and Michigan. German and Japanese automotive clusters face single-source vulnerability for qualified laser diode phosphors. Distribution runs through captive OEM parts organizations for passenger car platforms and direct distributor procurement for commercial vehicle retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around semiconductor-captive tier-one suppliers as dual-certification validation costs force sub-scale competitors toward exit.
For Market Incumbents: Anchor platform retention through captive LED packaging investments in Aichi Prefecture or Yangtze River Delta clusters. Deepen software-controlled optic design capabilities to offset hardware margin compression from matrix-beam standardization. Defend against emerging Chinese domestic OEM vertical integration by accelerating co-development agreement renewals before MIIT mandate compliance deadlines tighten. For New Entrants and Emerging Players: Capture commercial vehicle retrofit channel fragmentation in Germany and Japan where fleet operators bypass OEM parts organizations. Target refrigerated transport segments with simplified thermal architectures and rapid distributor turnaround. Pursue direct-to-fleet e-commerce platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated lighting system suppliers seeking semiconductor packaging control. Long-term viability favors tier-one suppliers with locked OEM platform contracts and adaptive lighting certification expertise. Monitor test house capacity bottlenecks in Germany and the Netherlands as inflection indicators for homologation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver IC Supply | Captive semiconductor sourcing secures high-volume contracts with Japanese and North American OEMs. |
| Matrix-Beam Firmware Platform Standardization | Software-controlled optic design consolidates margins away from stamped metal reflector tooling. |
| Dual-Certification Test Fleet Investment | Parallel NHTSA and UNECE validation accelerates platform launch schedules versus competitors. |
| Commercial Vehicle Retrofit Channel Expansion | Direct distributor procurement bypasses OEM captive parts organizations in refrigerated transport. |
| Adaptive Lighting Homologation Partnership | Collaboration with German KBA and Dutch test houses reduces certification queue exposure. |
Study Parameters
Independent corroboration across tier-one supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and test house certification managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS 108 compliance filings, and UNECE type-approval registries. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Rate-of-change decomposition across the analysis window separated volume growth from value expansion drivers. Segmentation dimensions modeled include light source technology, vehicle class, market channel, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to platform contract renewal cycles and mandate implementation timelines. Forecast inputs incorporated MIIT automatic leveling phase-in schedules and UNECE R123 revision adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity allocation and divergent US-EU regulatory harmonization progress. Practitioners should monitor LED driver IC lead time fluctuations and KBA test house queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Child Seats Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Engine Components Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Rear Axle Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Limited Slip Differential (LSD) Market