
 E-Bike Lights Market | 2026-2036
E-Bike Lights Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Lights Market Foresight
EU General Product Safety Regulation is recalibrating compliance costs for aftermarket suppliers. Lupine Lighting Systems leverages German engineering credibility to sustain premium positioning in high-lumen performance segments. Cateye Co., Ltd. anchors its competitive stance through manufacturing scale across Asian supply nodes. Garmin differentiates by integrating lighting with GPS and radar ecosystems, extending its wearable technology dominance into cycling accessories.
E-bike lights are electroluminescent safety devices engineered to deliver specified luminous intensity, beam pattern conformity, and ingress protection ratings for powered two-wheel operation in variable visibility conditions. LED technology dominates the technology segment due to thermal efficiency, lumen-per-watt performance, and compatibility with low-voltage e-bike electrical architectures. Front lights command the largest product type share as regulatory minimums for forward illumination exceed rear visibility requirements in most jurisdictions. Integrated systems represent the fastest-expanding product type as OEMs bundle lighting with drive-system electronics to reduce wiring complexity and warranty exposure.
Germany's KBA enforces StVZO compliance for all road-legal e-bike lighting, creating a de facto quality floor that filters non-conforming imports from lower-cost manufacturing regions. The EU Machinery Directive and CE marking framework mandate electromagnetic compatibility and failure-mode testing, shaping R&D allocation across European-headquartered suppliers. Stakeholders must monitor divergence between EU harmonized standards and emerging national requirements in Asia-Pacific cycling markets, as regulatory fragmentation threatens economies of scale for unified product platforms.
Market Dynamics
Regulatory convergence around photometric compliance and electromagnetic compatibility is compressing product development cycles while elevating R&D thresholds for aftermarket suppliers competing against OEM-integrated lighting architectures.
Growth Catalysts
- EU Machinery Directive:Mandatory failure-mode testing and CE marking requirements are filtering non-conforming imports, creating protected market space for engineering-capable suppliers.
- Urban last-mile delivery:German commercial fleet operators are expanding e-bike procurement, generating sustained replacement demand for StVZO-compliant lighting systems.
- LED thermal efficiency:Advances in lumen-per-watt performance are enabling compact high-output designs that satisfy stringent forward-illumination minimums without bulky heat-sinking.
Market Restraints
- Asian supply concentration:Manufacturing scale advantages in Chinese and Taiwanese electronics clusters limit European aftermarket pricing flexibility against integrated OEM bundles.
- StVZO compliance costs:Germany's KBA enforcement creates a de facto quality floor that elevates certification expenses for entry-tier suppliers.
- Integrated system substitution:OEM bundling of lighting with drive-system electronics is compressing standalone aftermarket volume in premium e-bike segments.
Strategic Opportunities
- Netherlands cycling infrastructure:Dense urban bike networks and mandatory lighting enforcement create sustained upgrade cycles for high-durability products.
- GPS-radar convergence:Integration of lighting with navigation and rear-facing detection systems opens premium positioning for electronics-capable suppliers.
- EU Green Deal procurement incentives:Public-sector fleet electrification mandates are channeling subsidy flows toward safety-compliant e-bike accessories.
Industry Challenges
- Photometric engineering talent:Specialized expertise in beam-pattern optimization and thermal management remains concentrated among German and Japanese component specialists.
- Electromagnetic compatibility testing:CE marking requirements for EMI/EMC validation extend certification timelines and capex intensity for multi-market product platforms.
- Regulatory fragmentation:Divergence between EU harmonized standards and emerging Asia-Pacific national requirements threatens economies of scale for unified lighting architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Lights Market |
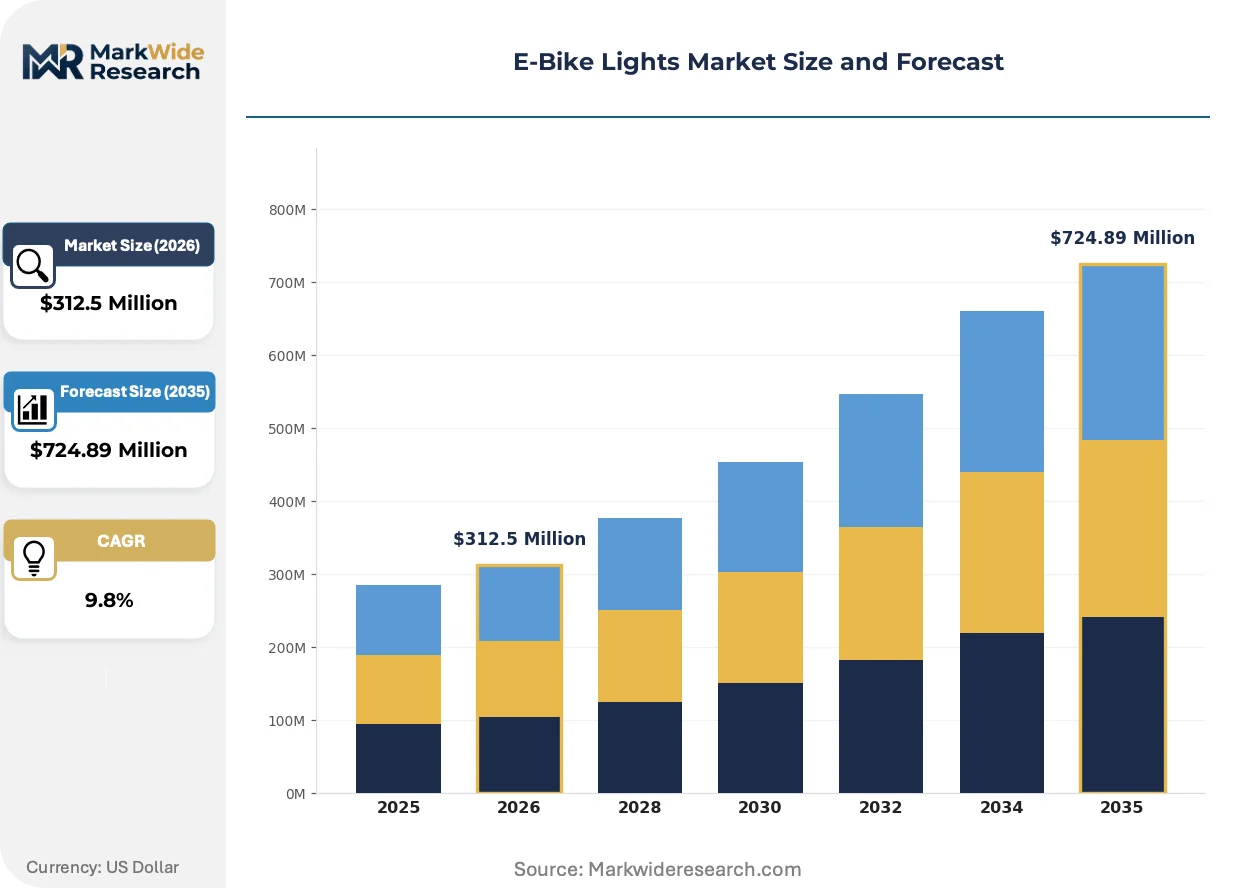
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $724.89 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Lights, Rear Lights, Integrated Systems, Reflectors Technology: LED, OLED, Halogen, Xenon Power Source: Battery-Powered, Dynamo, Solar, Capacitor Mounting Type: Handlebar Mount, Seat Post Mount, Frame Mount, Helmet Mount |
| Companies Covered | D-Light (Chance Good Ent. Co., Ltd.), LEZYNE, Supernova Design GmbH, Herrmans OY AB, Spanninga Metaal BV, Cateye Co., Ltd., Lupine Lighting Systems, Knog, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Lights Market Shifts & Advancements
Active beam shaping and connectivity integration are displacing passive illumination as the primary axis of supplier differentiation, while regulatory pressure accelerates consolidation around engineering-capable manufacturers.
Adaptive matrix LED front lighting is rewriting competitive requirements in the premium segment. German commercial fleet operators are adopting these systems fastest, drawn by automatic high-beam masking that maintains StVZO compliance across variable urban lighting conditions. The technology is compressing market share for fixed-pattern halogen and basic LED alternatives that cannot dynamically adjust beam boundaries.
The EU's updated General Product Safety Regulation is tightening traceability and failure-documentation obligations for all road-legal e-bike accessories. Suppliers must now maintain technical files demonstrating electromagnetic compatibility under Machinery Directive annexes, extending product development cycles by six to nine months. Aftermarket specialists serving Netherlands and German markets are responding by consolidating certification resources and abandoning marginal SKU variations.
Fleet procurement managers are consolidating vendor relationships around full-system suppliers capable of warranty-aligned lighting-drive integration. Direct-to-installer channels are displacing traditional retail distribution for urban delivery operators, who prioritize technical support responsiveness over point-of-sale availability. This concentration is most visible in German metropolitan clusters where last-mile logistics electrification is furthest advanced.
E-Bike Lights Market Segmentation
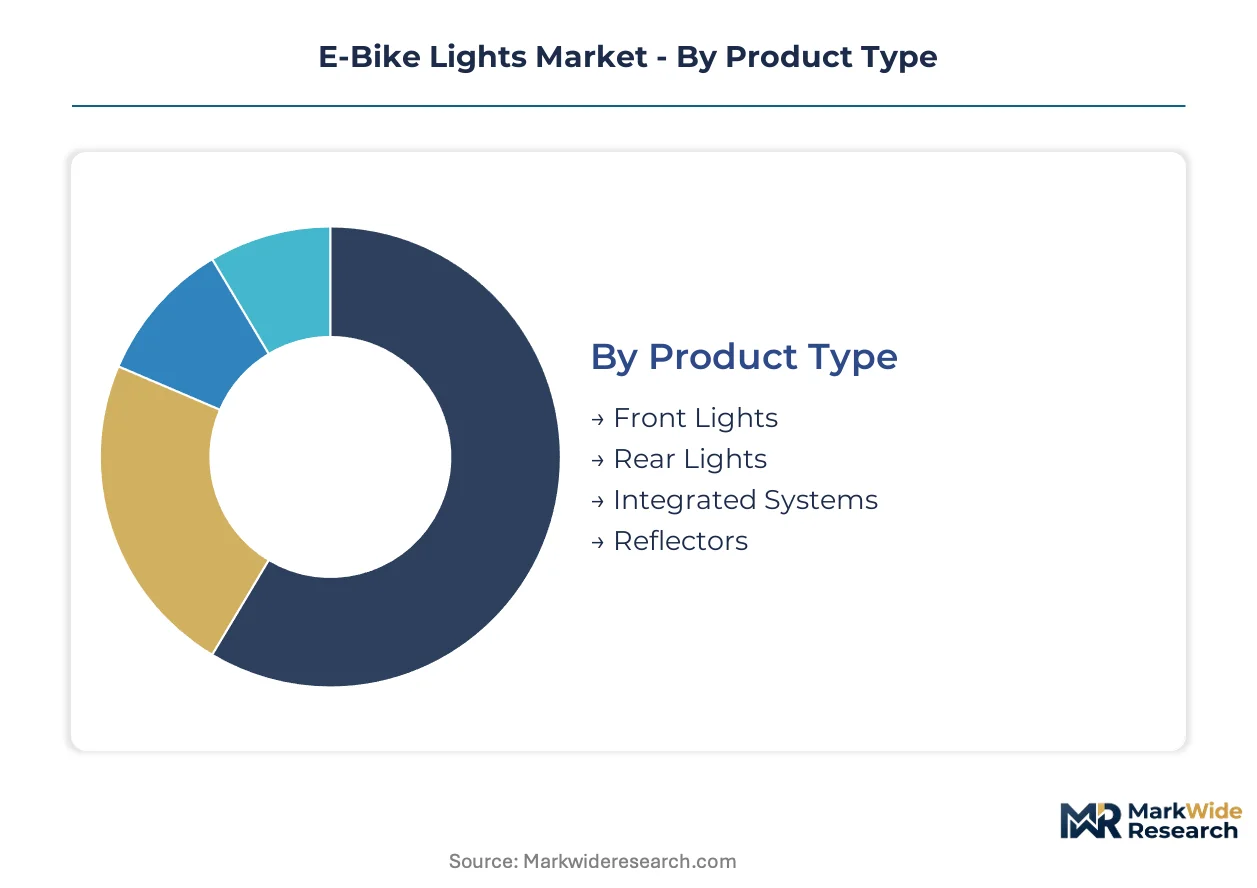
E-bike lighting architectures fragment across four technical dimensions, each carrying distinct certification obligations under EU Machinery Directive annexes. Suppliers must align R&D allocation with the compliance burden specific to each segment combination.
Product Type:
Front lights and integrated systems demand StVZO type-approval from Germany's KBA, while rear lights and reflectors face lighter conformity assessment routes.
- Front Lights:High-output LED arrays with precision beam cutoffs dominate this segment. German commercial fleet operators in Berlin and Hamburg are driving replacement demand for adaptive matrix designs that maintain compliance across variable urban lighting conditions. StVZO certification costs filter out entry-tier competitors.
- Integrated Systems:Drive-system electronics bundle illumination, power management, and diagnostics into unified architectures. OEMs in the Netherlands specify these configurations to reduce wiring complexity and warranty exposure across dense cycling infrastructure networks.
- Rear Lights:Compact red-emitting modules with wide-angle visibility patterns.
- Reflectors:Passive retroreflective elements without active power requirements.
Front lights sit at the top of the volume ranking, with integrated systems climbing the fastest.
Technology:
LED and OLED platforms command premium positioning through thermal efficiency metrics, while halogen and xenon alternatives serve cost-constrained replacement cycles.
- LED:Solid-state emitters delivering 100+ lumens per watt with minimal heat-sinking requirements. Japanese component specialists in Osaka and Nagoya control phosphor deposition expertise that determines color rendering consistency for premium European OEMs.
- OLED:Organic electroluminescent panels enabling uniform surface illumination without optic complexity. German engineering houses leverage this technology for signature lighting designs in high-end urban mobility products.
- Halogen:Tungsten-filament technology with established supply chains but declining share.
- Xenon:Gas-discharge arc sources with high initial output but complex ballast requirements.
LED holds the dominant volume position, while OLED gains share fastest in premium positioning.
Power Source:
Battery architectures and dynamo systems diverge sharply in total cost of ownership calculations for fleet procurement managers.
- Battery-Powered:Rechargeable lithium-ion cells with USB-C charging interfaces. Last-mile delivery operators in Munich and Frankfurt prioritize swappable battery designs that minimize vehicle downtime during multi-shift operations.
- Dynamo:Hub- or tire-driven generators eliminating charging dependency. Dutch cycling infrastructure density supports this segment through consistent ridership volumes that justify higher upfront hardware investment.
- Solar:Photovoltaic integration with limited output in northern European latitudes.
- Capacitor:Rapid-charge storage for auxiliary lighting without battery chemistry.
Battery-powered configurations lead volume rankings, with dynamo systems expanding most quickly in fleet applications.
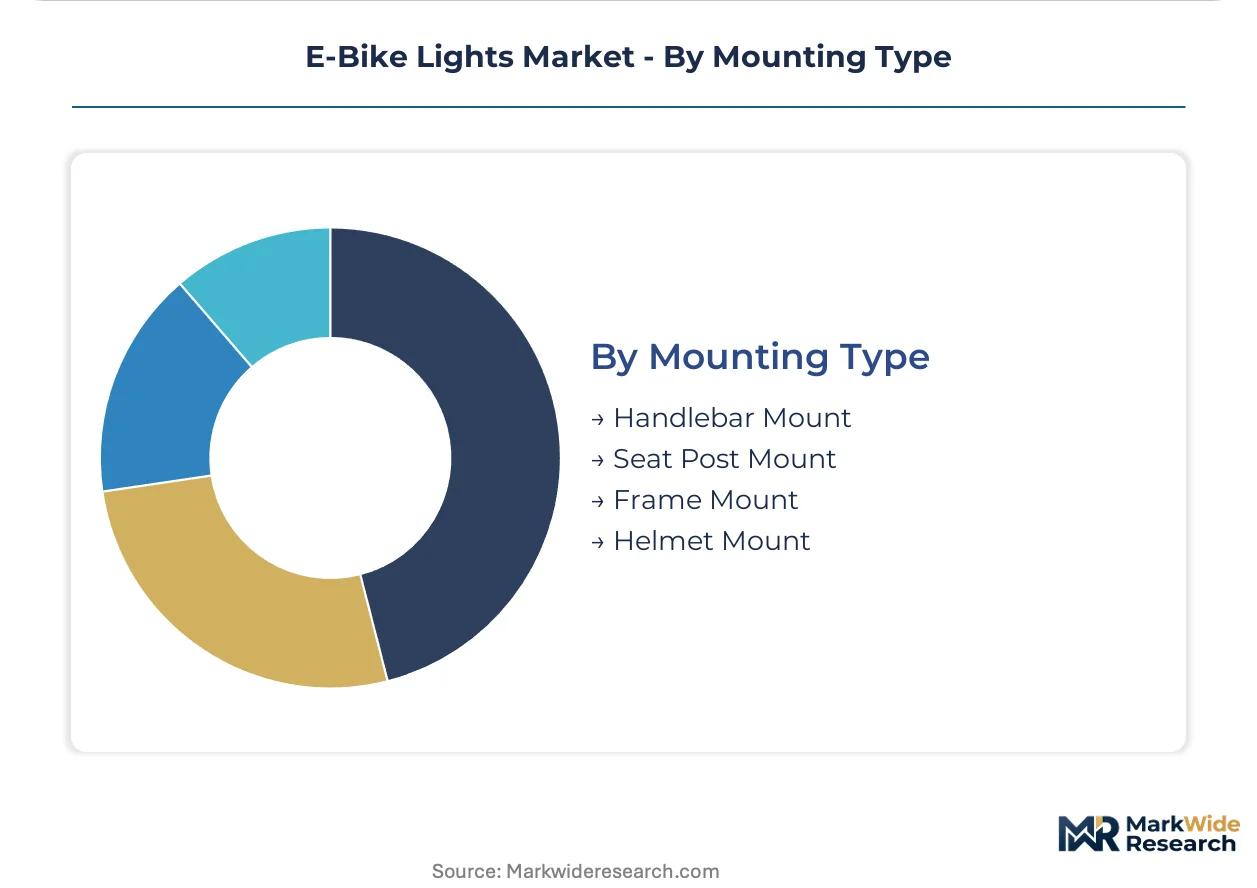
Mounting Type:
Handlebar and seat post configurations dominate aftermarket replacement, while frame and helmet mounts serve specialized performance segments.
- Handlebar Mount:Clamp-based attachment systems accommodating 22.2mm to 31.8mm diameter tubes. German StVZO compliance mandates automatic high-beam masking for forward-mounted units, accelerating adoption of electronically controlled pivot mechanisms.
- Seat Post Mount:Rear-facing visibility systems with tool-free quick-release features. Netherlands enforcement of mandatory lighting during daylight hours sustains replacement demand for high-durability polymer housings.
- Frame Mount:Integrated fork or down tube attachment points for OEM specification.
- Helmet Mount:Rider-positioned illumination following head movement trajectory.
Handlebar mounts command the volume lead, with frame mounts showing steepest expansion through OEM bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photometric engineering talent clusters in German and Japanese component hubs anchor regional competitive positioning across the e-bike lights landscape.
Germany
KBA enforcement of StVZO type-approval elevates certification barriers for forward-illumination systems. The Machinery Directive mandates electromagnetic compatibility documentation that extends product development timelines. Berlin and Hamburg commercial fleet operators drive replacement demand for adaptive matrix LED designs.
Netherlands
Mandatory lighting enforcement during daylight hours sustains upgrade cycles for high-durability rear visibility systems. The EU Green Deal channels public procurement subsidies toward safety-compliant fleet accessories. Randstad urban density supports dynamo-powered configurations through consistent ridership volumes.
Japan
Osaka and Nagoya phosphor deposition expertise determines color rendering consistency for premium European OEM supply relationships. METI industrial standards shape thermal management R&D allocation. Component specialists leverage JIS certification credibility to defend position in high-lumen performance segments.
United States
Last-mile logistics electrification in Seattle and Portland generates demand for GPS-integrated lighting ecosystems. NHTSA regulatory frameworks remain less prescriptive than EU equivalents, permitting faster product iteration cycles. Pacific Northwest cycling infrastructure investment concentrates procurement manager attention on connectivity-enabled accessories.
China
Shenzhen and Dongguan electronics manufacturing scale limits European aftermarket pricing flexibility against integrated OEM bundles. GB standards divergence from EU harmonized requirements threatens economies of scale for unified product platforms. Domestic e-bike OEMs bundle lighting with drive-system electronics to reduce wiring complexity.
E-Bike Lights Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into engineering-capable European houses, Asian manufacturing-scale operators, and electronics-integrated technology platforms. Three strategic archetypes dominate: StVZO-certified premium specialists, volume-driven Asian fabricators, and GPS-radar convergence players. Competitive moves concentrate on certification resource consolidation and direct-to-installer channel development for fleet procurement managers.
Among German engineering houses, Supernova Design GmbH and Lupine Lighting Systems exemplify the StVZO-compliant premium tier through precision beam-pattern optimization. Garmin anchors the electronics-convergence archetype by integrating lighting with navigation and detection ecosystems. Cateye Co., Ltd. occupies a position within the Asian manufacturing-scale tier, leveraging supply node density across Japanese and Taiwanese production clusters.
| Leading Market Players |
|---|
| D-Light (Chance Good Ent. Co., Ltd.) |
| LEZYNE |
| Supernova Design GmbH |
| Herrmans OY AB |
| Spanninga Metaal BV |
| Cateye Co., Ltd. |
| Lupine Lighting Systems |
| Knog |
| Garmin |
| Others |
Supply & Pricing Matrix
StVZO-certified premium tiers and uncertified commodity imports operate on divergent cost structures that reshape both margin architecture and sourcing geography. German KBA enforcement elevates certification expenses for forward-illumination systems, compressing aftermarket pricing flexibility against Asian-manufactured OEM bundles while concentrating procurement manager attention on warranty-aligned supplier relationships.
Pricing Analysis
Bundled drive-system lighting and standalone aftermarket units split pricing models across the landscape. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal management performance, with German commercial fleet operators showing lowest price sensitivity due to StVZO compliance mandates. Pricing pressure stems from integrated OEM substitution in premium e-bike segments, eroding standalone volume. Asian manufacturing-scale operators compete most aggressively on unit economics, while European engineering houses defend position through after-sales service bundling.
Supply Chain Analysis
EU local-content thresholds under the Machinery Directive and Green Deal procurement frameworks reshape sourcing decisions for public-sector fleet operators. Manufacturing concentrates in China, Taiwan, and Japan, with Shenzhen and Dongguan electronics clusters feeding component inputs while Osaka and Nagoya specialists control phosphor deposition expertise. LED emitters, lithium-ion cells, and precision optics constitute critical input dependencies. Single-source vulnerability runs through Taiwanese semiconductor packaging for driver electronics. Distribution runs through direct-to-installer channels for fleet procurement managers and traditional retail for consumer replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-bike lighting functions as a stable compounder anchored by mandatory regulatory compliance that sustains replacement demand regardless of macroeconomic cycling. Fleet electrification mandates and StVZO enforcement create predictable revenue visibility for engineering-capable suppliers.
For Market Incumbents: Deepen certification resource consolidation to compress development timelines against integrated OEM bundles. Invest in backward integration into LED phosphor deposition or thermal management subsystems to defend margin position from Asian manufacturing-scale competitors. Prioritize direct-to-installer channel control in German metropolitan clusters where last-mile logistics electrification concentrates procurement volume.
For New Entrants and Emerging Players: Enter via GPS-radar convergence segments where electronics integration capabilities create differentiation headroom against pure-play lighting specialists. Target Netherlands daylight-mandatory enforcement zones with high-durability rear visibility systems, as dense cycling infrastructure sustains upgrade cycles. Pursue fleet procurement manager relationships through technical support responsiveness rather than point-of-sale availability.
For Investors and Strategic Acquirers: Consolidation pressure builds where photometric engineering talent scarcity meets fragmented aftermarket supplier bases. Frame long-term viability around suppliers capable of navigating EU Machinery Directive electromagnetic compatibility documentation while maintaining Asian supply node relationships. Monitor divergence between EU harmonized standards and emerging Asia-Pacific national requirements as the primary inflection signal for unified product platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| StVZO Certification Investment | KBA type-approval creates protected market space against non-conforming imports. |
| LED Thermal Management R&D | Phosphor deposition expertise from Osaka specialists determines premium OEM relationships. |
| Direct-to-Installer Channel Development | Fleet procurement managers prioritize technical support over retail availability. |
| GPS-Radar Integration Partnership | Navigation ecosystem convergence opens premium positioning for electronics-capable suppliers. |
| Asian Supply Node Diversification | Taiwanese semiconductor packaging concentration creates single-source vulnerability. |
Research Methodology
Bottom-up fleet procurement modeling reconciled against top-down OEM supply tracking forms the analytical core of this study. Primary interviews with commercial fleet operators, aftermarket distributors, OEM platform engineers, and KBA certification specialists combined with secondary validation from EU Machinery Directive filings, StVZO type-approval databases, customs trade records, and LED component import manifests. Triangulation across these sources calibrated volume estimates for replacement cycles and integrated system penetration.
Historical trendline analysis of certification timelines and fleet electrification procurement patterns informed projection assumptions across the analysis window. Segmentation dimensions modeled include product type, technology platform, power source architecture, mounting configuration, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for compliance-driven replacement elasticity and OEM bundling substitution effects. Forecast inputs incorporated LED lumen-per-watt improvement trajectories and dynamo system adoption rates in Dutch cycling infrastructure.
Inputs from EU regulatory filings and Asian component trade data were available through the study window; gaps in proprietary OEM bundling contract terms introduce uncertainty bands around integrated system share projections. Forecasts reflect documented assumptions regarding StVZO enforcement continuity and Machinery Directive annex interpretations. Regulatory fragmentation between EU harmonized standards and emerging Asia-Pacific requirements represents the primary revision risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
TPMS Battery Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market