
 Car Seat and Accessories Market | 2026-2036
Car Seat and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Car Seat and Accessories Market Outlook
Chinese seat component manufacturing is decoupling from legacy Western supply chains as domestic capacity scales for both OEM and aftermarket channels. Lear Corporation leverages vertical integration across foam-in-place seating technology to sustain pricing power in premium vehicle programs. Adient Plc anchors its position through modular seat architecture that spans convertible and booster configurations. Graco Inc specializes in direct-to-consumer distribution, controlling channel margins through proprietary online retail infrastructure.
Car seats and accessories comprise engineered restraint systems constructed from energy-absorbing foam cores, injection-molded polypropylene shells, and woven textile covers designed to limit occupant excursion during frontal and side-impact collisions. Manufacturing employs blow-molding for shell formation and robotic sewing for harness assembly, with finished units tested to dynamic sled criteria measuring chest acceleration and head injury criteria. Convertible seats occupy the largest revenue pool due to extended usable life spanning rear-facing and forward-facing modes, while ISOFIX-compatible accessories represent the fastest-expanding segment as latch-based installation displaces belt-routing methods in both European and Asian markets. Fabric materials dominate unit economics through supplier fragmentation, though metal reinforcement components capture disproportionate margin in premium safety-certified tiers.
Federal Motor Vehicle Safety Standard 213 governs structural integrity and labeling in the United States, while ECE R44/04 and successor i-Size regulations in Europe mandate side-impact testing and height-based classification. China's GB 27887 standard, enforced by the country's national automotive safety regulator, now requires child restraint provisions in passenger vehicle type approvals. Stakeholders must monitor divergence between regional testing protocols, as compliance with multiple certification regimes determines factory gate access rather than product performance alone.
Market Dynamics
ISOFIX anchor standardization across mass-market vehicle platforms is compressing installation error rates and redirecting aftermarket demand toward compatible accessories. This mechanical latch system eliminates belt-routing variability, creating a hard interface between vehicle structure and child restraint that favors purpose-engineered components over universal designs.
Growth Catalysts
- ECE R44/04 and i-Size mandates:European height-based classification and side-impact testing protocols are accelerating replacement cycles as older belt-routing seats face compliance gaps.
- Injection-molded polypropylene shells:Advances in blow-molding tolerances are reducing shell weight while maintaining structural integrity, enabling rear-facing designs with extended weight limits.
- China's GB 27887 enforcement:Mandatory child restraint provisions in passenger vehicle type approvals are standardizing ISOFIX anchor density across domestic OEM platforms.
Market Restraints
- Energy-absorbing foam core volatility:Expanded polypropylene bead pricing fluctuates with propylene feedstock costs, compressing margin on mid-tier convertible seats.
- Woven textile supplier fragmentation:Fabric cover manufacturing disperses across low-capacity regional mills, creating lot-to-lot color and durability inconsistency.
- Dynamic sled testing capacity:Certified crash simulation facilities concentrate in Germany, Japan, and the United States, extending certification timelines for new market entrants.
Strategic Opportunities
- Booster-to-backless transition segments:Height-adjustable high-back boosters with removable back panels address the 40-65 pound demographic with single-SKU flexibility.
- Direct-to-consumer online retail:Proprietary digital storefronts bypass distributor markups and capture first-party installation data for product refinement.
- FMVSS 213 label harmonization:Unified United States federal labeling standards reduce SKU complexity for cross-border North American distribution.
Industry Challenges
- Robotic harness assembly programming:Five-point harness routing automation requires vision-guided sewing cells that demand specialized mechatronics expertise.
- Multi-regional certification concurrency:Simultaneous ECE R44/04, FMVSS 213, and GB 27887 testing creates documentation bottlenecks during product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Seat and Accessories Market |
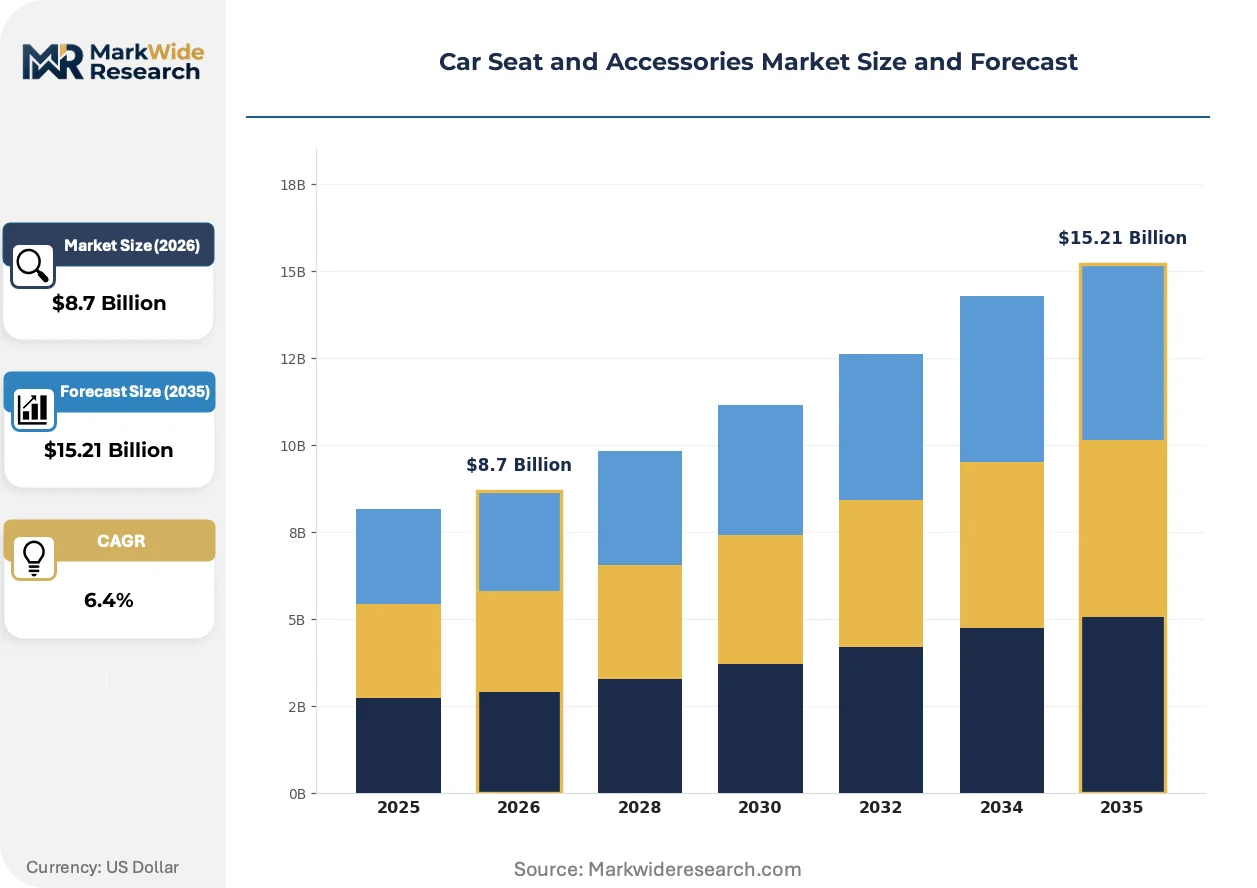
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Seats, Booster Seats, Convertible Seats, Accessories Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores Safety Standard: ISOFIX, FMVSS, ECE R44/04, Safety Seat Certified Material: Fabric, Plastic, Foam, Metal |
| Companies Covered | Lear Corporation, Adient Plc, Toyota Boshoku Corporation, Magna International Inc, Faurecia SE, Graco Inc, Britax, Diono, Maxi-Cosi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Seat and Accessories Market Strategic Shifts
Sensor-integrated restraint systems are migrating from premium vehicle programs into aftermarket accessories, embedding load-cell technology that communicates installation integrity to caregiver smartphones.
Energy-absorbing foam cores with tunable density gradients are absorbing impact forces across broader weight ranges, eliminating the need for separate infant and toddler shell architectures. Premium vehicle OEMs are specifying these materials for integrated child restraint programs, while aftermarket manufacturers adopt them to extend rear-facing limits. The technology is absorbing market share from traditional single-density EPS constructions by reducing SKUs and simplifying inventory.
China's GB 27887 standard, enforced by the national automotive safety regulator, now mandates child restraint provisions in passenger vehicle type approvals. Domestic automakers are engineering ISOFIX anchor systems into mass-market platforms previously lacking standardized mounting points. Compact and mid-size vehicle segments are most affected, with OEMs redesigning seat pan structures to accommodate rigid latch bars.
Subscription-based accessory replacement programs are emerging as an alternative to outright purchase, with caregivers receiving age-appropriate inserts and harness configurations on a scheduled cadence. Direct-to-consumer channels are displacing big-box retail for initial seat acquisition, particularly among first-time parents seeking installation guidance. This pattern concentrates in United States coastal metropolitan markets where digital-native purchasing behavior intersects with higher vehicle turnover rates.
Car Seat and Accessories Market Segmentation
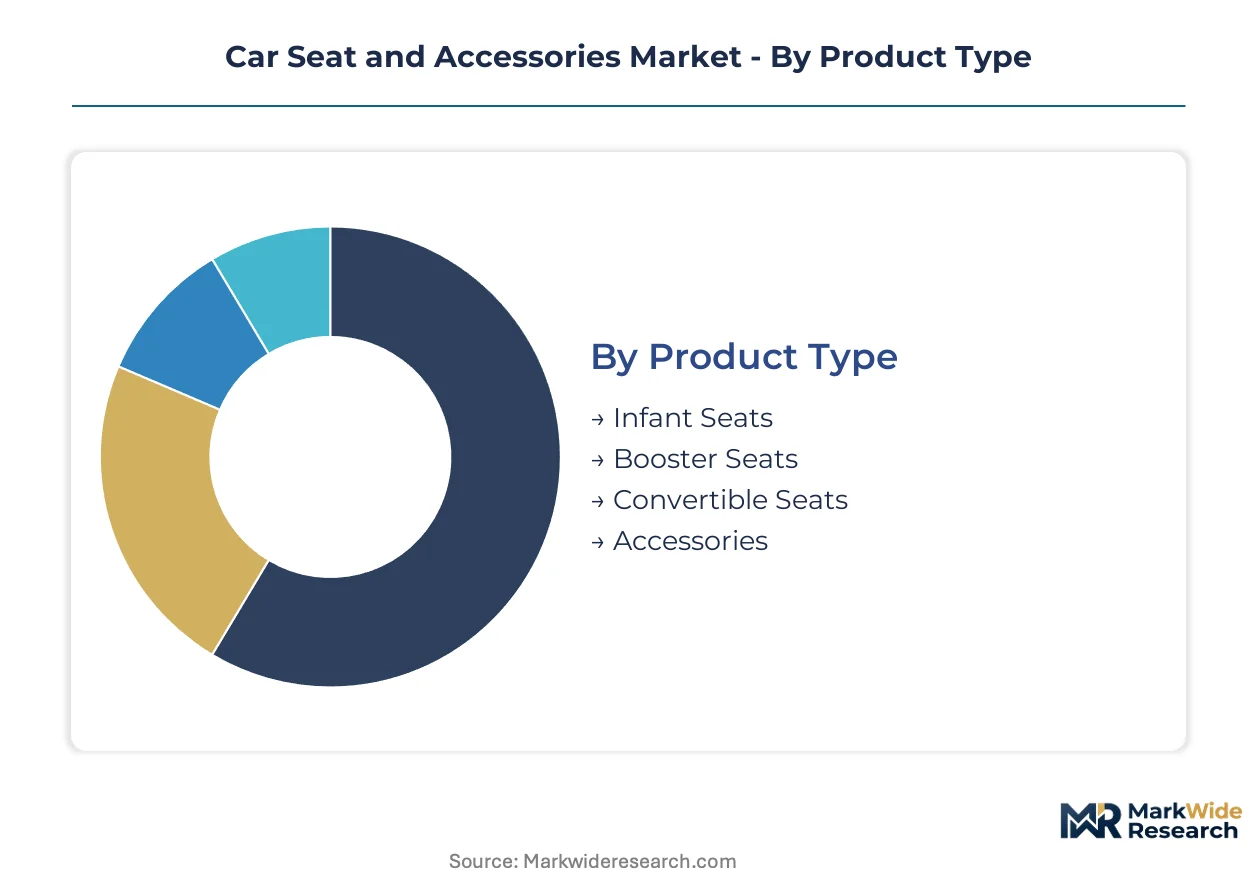
Segmentation in the car seat market reflects divergent capital requirements across manufacturing technologies and certification regimes. Product architecture and material selection determine tooling investment intensity, while distribution channel strategy shapes working capital needs and margin capture.
Product Type:
Capital intensity varies sharply across product categories, with convertible seats demanding the most sophisticated blow-molding and dynamic testing infrastructure.
- Convertible Seats:Dual-mode architectures accommodate rear-facing and forward-facing configurations through adjustable base angles and extended harness systems. Energy-absorbing foam cores with tunable density gradients concentrate demand among first-time parents seeking extended usable life. Manufacturing requires multi-cavity injection molds and robotic harness assembly cells that elevate fixed costs above infant-only designs.
- Infant Seats:Rear-facing-only shells with detachable carrier bases serve the 0-12 month demographic through lightweight polypropylene construction. Demand clusters in urban China where compact vehicle footprints favor portable designs. Capital requirements center on single-cavity tooling and manual harness routing, keeping entry barriers accessible to regional assemblers.
- Booster Seats:High-back and backless configurations elevate children to adult belt geometry without integrated harness systems. Metal reinforcement components capture disproportionate margin in premium safety-certified tiers.
- Accessories:ISOFIX-compatible bases, seat protectors, and travel bags extend product ecosystems. Fabric materials dominate unit economics through supplier fragmentation.
Most installed capacity flows through Convertible Seats. Expansion is steepest in Accessories as ISOFIX standardization redirects aftermarket demand toward purpose-engineered components.
Distribution Channel:
Channel selection determines margin structure and customer acquisition costs, with digital-native entrants disrupting legacy retail economics.
- Online Retail:Proprietary storefronts and marketplace listings capture first-party installation data while bypassing distributor markups. Direct-to-consumer concentration runs highest in United States coastal metropolitan markets where digital purchasing intersects with higher vehicle turnover. Logistics infrastructure demands warehouse networks and returns processing capabilities that favor scaled operators.
- Specialty Stores:Dedicated juvenile product retailers provide hands-on installation guidance and fitting services. Physical footprint requirements elevate real estate costs relative to online channels.
- Supermarkets:Mass-market grocery chains stock entry-level SKUs with simplified packaging for self-service selection. Volume throughput justifies slotting fees.
- Department Stores:Full-line retailers curate mid-tier assortments alongside broader baby gear categories. Seasonal promotional calendars compress margin.
Volume concentrates in Specialty Stores. Digital channels are climbing the fastest as caregiver purchasing behavior shifts toward subscription-based accessory replacement programs.
Safety Standard:
Certification regime selection dictates testing facility access and documentation burden, with multi-standard compliance multiplying development timelines.
- ISOFIX:Rigid latch-based installation eliminates belt-routing variability through standardized anchor points. China's GB 27887 enforcement is standardizing anchor density across domestic OEM platforms. Dynamic sled testing at certified facilities concentrates in Germany, Japan, and the United States.
- ECE R44/04:European height-based classification and side-impact testing protocols accelerate replacement cycles. Compliance documentation bottlenecks new market entrants.
- FMVSS:United States federal labeling standards govern structural integrity and installation instructions. Harmonization efforts reduce SKU complexity for cross-border North American distribution.
- Safety Seat Certified:Third-party verification programs supplement regulatory minimums with consumer-facing quality marks. Testing costs fall between mandatory regimes and uncertified alternatives.
Regulatory volume flows through ECE R44/04. ISOFIX is gaining share fastest as mechanical latch systems displace belt-routing methods in European and Asian markets.
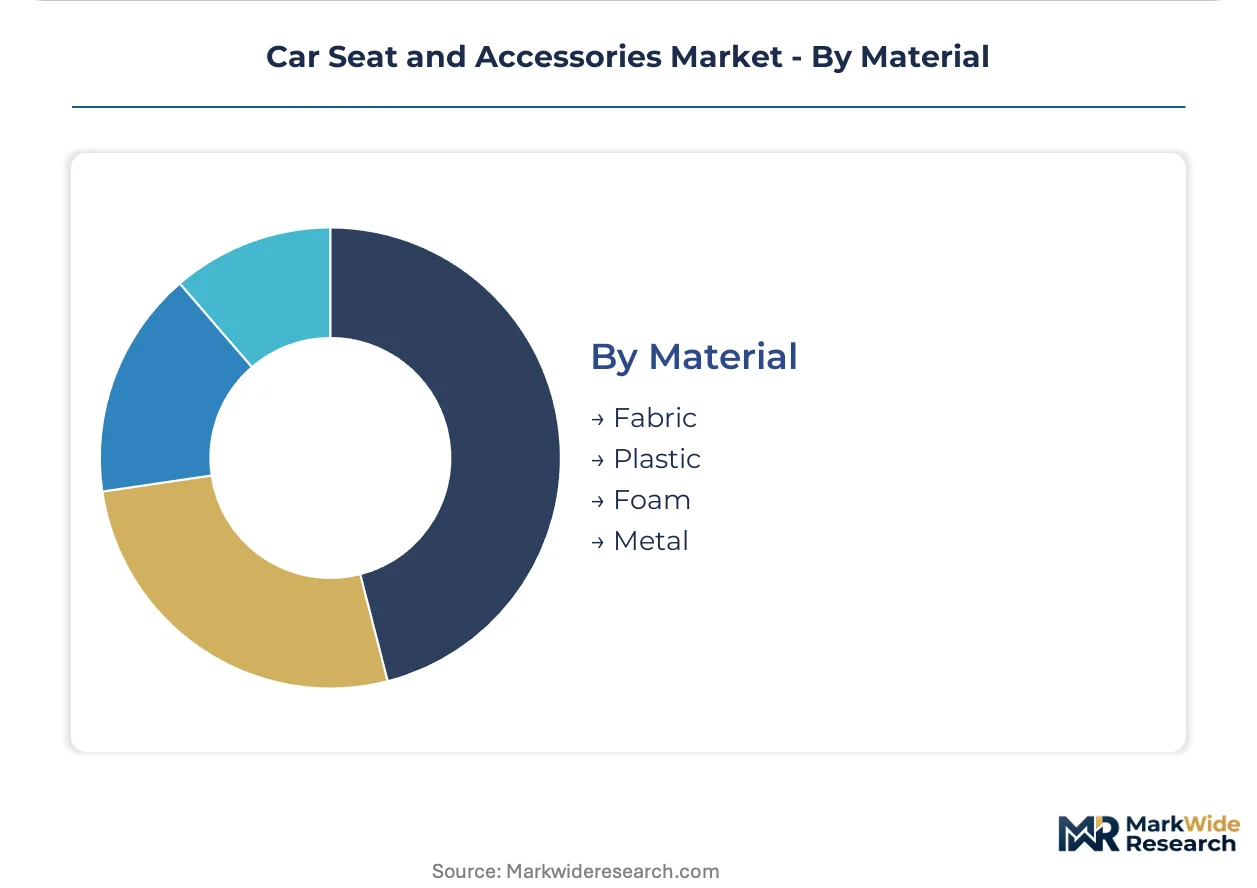
Material:
Input cost volatility and supplier concentration shape material selection economics across tiered product positioning.
- Foam:Expanded polypropylene bead cores absorb impact forces through crushable cellular structures. Propylene feedstock pricing fluctuates with energy markets, compressing margin on mid-tier convertible seats.
- Plastic:Injection-molded polypropylene shells form structural exoskeletons through blow-molding processes. Advances in tolerance control reduce weight while maintaining integrity.
- Fabric:Woven textile covers provide aesthetic differentiation and comfort layers. Regional mill fragmentation creates lot-to-lot color and durability inconsistency.
- Metal:Steel reinforcement bars and aluminum anchor hardware capture premium positioning in safety-certified tiers. Commodity pricing transparency limits differentiation.
Component volume flows through Fabric. Foam is expanding most quickly as tunable density gradients absorb market share from traditional single-density EPS constructions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting manufacturing footprints as cost-of-compliance gaps between certification regimes widen. Producers seek testing economies where facility concentration and regulatory reciprocity reduce duplicate validation burdens.
United States
NHTSA's FMVSS 213 enforcement maintains rigorous dynamic sled testing requirements that sustain domestic manufacturing of premium-certified units. The standard governs structural integrity and federal labeling for all child restraint systems sold interstate. Michigan and Ohio host concentrated engineering clusters where Tier 1 automotive suppliers co-locate crash simulation facilities with seat assembly operations.
Germany
ECE R44/04 and successor i-Size regulations accelerate replacement cycles through height-based classification mandates. KBA oversight ensures side-impact testing compliance across all distributed products. Stuttgart and Munich anchor development centers where OEM-integrated child restraint programs undergo concurrent ECE and FMVSS validation.
China
Domestic automaker standardization of ISOFIX anchor systems creates captive demand for compatible accessories across mass-market vehicle platforms. GB 27887 enforcement by the national automotive safety regulator mandates child restraint provisions in passenger vehicle type approvals. Yangtze River Delta manufacturing hubs scale blow-molding capacity for both export and domestic aftermarket channels.
Japan
METI-aligned JIS standards maintain distinct certification pathways that preserve domestic testing infrastructure for premium export positioning. Aging demographics compress birth-rate-driven demand, shifting strategic focus toward high-margin integrated vehicle programs. Nagoya and Tokyo metropolitan areas concentrate robotic harness assembly expertise serving regional OEM supply chains.
South Korea
MFDS-equivalent automotive safety oversight harmonizes with ECE frameworks, enabling streamlined export certification to European markets. Domestic OEM anchor system proliferation matches Chinese ISOFIX density trajectories. Seoul Capital Area facilities specialize in tunable-density foam core production for convertible seat architectures.
Car Seat and Accessories Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and subscription-based service models. The structure fragments across three operational layers: Tier 1 automotive suppliers with captive OEM relationships, specialized juvenile product manufacturers with direct-to-consumer channels, and regional assemblers serving price-sensitive segments. Strategic archetypes include vertical integrators controlling foam-in-place technology, modular architecture specialists spanning multiple configuration types, and digital-native distributors capturing first-party data. Competitive moves concentrate on M&A for testing facility access and backward integration into polypropylene shell manufacturing.
Among North American-based fabricators, Lear Corporation and Graco Inc exemplify divergent strategic positions. Lear Corporation anchors the Tier 1 supplier archetype through in-house production of foam-in-place seating technology for integrated vehicle programs. Graco Inc occupies the direct-to-consumer distribution tier, representing digital channel concentration that bypasses traditional retail markups. European specialists including Adient Plc sit within the modular architecture tier, exemplifying convertible-to-booster configuration flexibility that reduces SKU complexity across regulatory regimes.
| Leading Market Players |
|---|
| Lear Corporation |
| Adient Plc |
| Toyota Boshoku Corporation |
| Magna International Inc |
| Faurecia SE |
| Graco Inc |
| Britax |
| Diono |
| Maxi-Cosi |
| Others |
Value Chain & Pricing Dynamics
Propylene feedstock pricing volatility cascades through expanded polypropylene bead costs into three distinct finished-product tiers, with mid-market convertible seats absorbing the most margin compression as foam core inputs constitute disproportionate bill-of-materials weight.
Pricing Analysis
Distributor markups compress as direct-to-consumer channels capture first-party installation data and bypass traditional retail economics. Three-tier pricing structure across premium, standard, and economy levels separates ISOFIX-certified units with tunable-density foam from belt-routing alternatives with single-density EPS construction. Cost compression in mid-tier convertible seats is intensifying because propylene feedstock fluctuations transmit directly into energy-absorbing foam core pricing. Fleet buyers and mass-market OEM procurement teams exhibit highest price sensitivity, while premium vehicle integrated programs show lowest elasticity due to safety certification requirements.
Supply Chain Analysis
Blow-molding equipment and certified dynamic sled testing capacity rest on German, Japanese, and United States facility concentrations, creating geographic bottlenecks for new market entrants seeking multi-regional certification. Raw material flows draw from Saudi Arabian and Chinese propylene derivatives, South Korean and Japanese injection-molding machinery, and regional textile mills across Bangladesh and Vietnam for woven cover production. Single-source vulnerability concentrates in certified crash simulation facilities where ECE R44/04, FMVSS 213, and GB 27887 testing queues extend development timelines. Distribution runs through Tier 1 automotive supplier networks for integrated OEM programs, while aftermarket channels fragment across proprietary digital storefronts and specialty juvenile product retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where testing facility concentration in Germany and Japan creates cost-of-compliance premiums against China's scaling domestic certification infrastructure under GB 27887 enforcement.
For Market Incumbents: Lock in captive foam-in-place technology supply through backward integration into polypropylene shell manufacturing, defending against emerging sensor-integrated restraint entrants. Prioritize certification investment at KBA-aligned facilities to maintain European market access as i-Size protocols tighten side-impact testing requirements. Channel control through proprietary installation data platforms reinforces switching costs against digital-native distributors. For New Entrants and Emerging Players: Capture the subscription-based accessory replacement white space in United States coastal metropolitan markets where digital-native purchasing behavior intersects with higher vehicle turnover rates. Target China's domestic aftermarket as ISOFIX anchor standardization across mass-market vehicle platforms creates purpose-engineered component demand. Deploy direct-to-consumer online retail with first-party installation guidance as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with modular architecture specialists spanning convertible-to-booster configuration flexibility that reduces SKU complexity across regulatory regimes. Long-term viability over the coming decade hinges on testing facility access and multi-regional certification concurrency capabilities. Watch ISOFIX penetration rates in China's compact and mid-size vehicle segments as the signal indicating manufacturing footprint reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Testing Facility Acquisition | Certified crash simulation access in Germany, Japan, or the United States compresses ECE R44/04 and FMVSS 213 validation timelines for product launches. |
| Foam Core Manufacturing Integration | In-house production of tunable-density expanded polypropylene cores insulates margin from propylene feedstock volatility in mid-tier convertible seats. |
| ISOFIX-Compatible Accessory Expansion | Purpose-engineered bases and seat protectors capture aftermarket demand as China's GB 27887 standardizes anchor density across domestic OEM platforms. |
| Direct-to-Consumer Platform Launch | Proprietary digital storefronts bypass distributor markups and generate first-party installation data for product refinement in United States coastal markets. |
| Sensor-Integrated Restraint Development | Load-cell technology communicating installation integrity to caregiver smartphones differentiates premium positioning against traditional passive restraint systems. |
Study Parameters
Multiple input streams — executive interviews with Tier 1 automotive supplier procurement teams, OEM platform engineers, and aftermarket distribution heads; secondary validation through NHTSA FMVSS 213 filings, KBA type-approval databases, and vehicle production registries; plus customs records tracking polypropylene shell and foam core trade flows — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory parameters.
Historical shipment data cross-referenced against panel input from product development directors and regulatory affairs specialists anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, distribution channel, safety certification regime, and material composition, with CAGRs derived from regression analysis against vehicle birth-rate trends and regulatory mandate implementation schedules. Forecast inputs incorporated ISOFIX anchor penetration trajectories in China and replacement cycle acceleration under European i-Size height-based classification protocols.
Propylene feedstock price shocks, regulatory divergence between ECE R44/04 and GB 27887 testing protocols, and sensor-integrated restraint technology adoption curves are the dominant revision risks that could alter volume and value trajectories. Forecasts reflect documented assumptions about certification timeline standardization and anchor system proliferation rates. A concentrated set of triggers around Chinese domestic automaker ISOFIX implementation pace and European side-impact testing facility capacity warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Navigation Light Market