
 Biomedical Refrigerators and Freezers Market | 2026-2036
Biomedical Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Biomedical Refrigerators and Freezers Market Analysis
China is narrowing its import dependency in biomedical cold chain equipment through domestic manufacturing expansion in Suzhou and Shenzhen. Thermo Fisher Scientific sustains technology leadership in ultra-low temperature cascade systems for pharmaceutical distribution. Haier Biomedical anchors volume production across Asia with integrated compressor manufacturing. PHC Holdings Corporation specializes in precision vapor compression platforms for hospital pharmacy segments.
Biomedical refrigerators and freezers are engineered thermal storage systems maintaining precise temperature bands from standard refrigeration through cryogenic ranges, utilizing insulated enclosures with vapor compression, cascade, or thermoelectric cooling circuits to preserve biological specimens, vaccines, blood components, and research materials. Ultra-low temperature freezers command premium positioning due to compressor redundancy requirements and specialized insulation protocols for biologics storage. Laboratory refrigerators and upright freezers represent mature volume categories with stable replacement cycles, while blood bank end users drive specification intensity through regulatory validation demands for temperature monitoring and alarm systems.
FDA 21 CFR Part 11 and EU MDR traceability requirements shape validation protocols for clinical storage equipment, compelling manufacturers to embed continuous temperature logging and electronic signature compatibility. EPA refrigerant phase-down rules under the AIM Act and EU F-Gas Regulation are accelerating hydrocarbon and natural refrigerant adoption in new unit designs. Stakeholders must weigh capital investment in compliant cold chain infrastructure against operational risks of legacy equipment obsolescence in regulated environments.
Market Dynamics
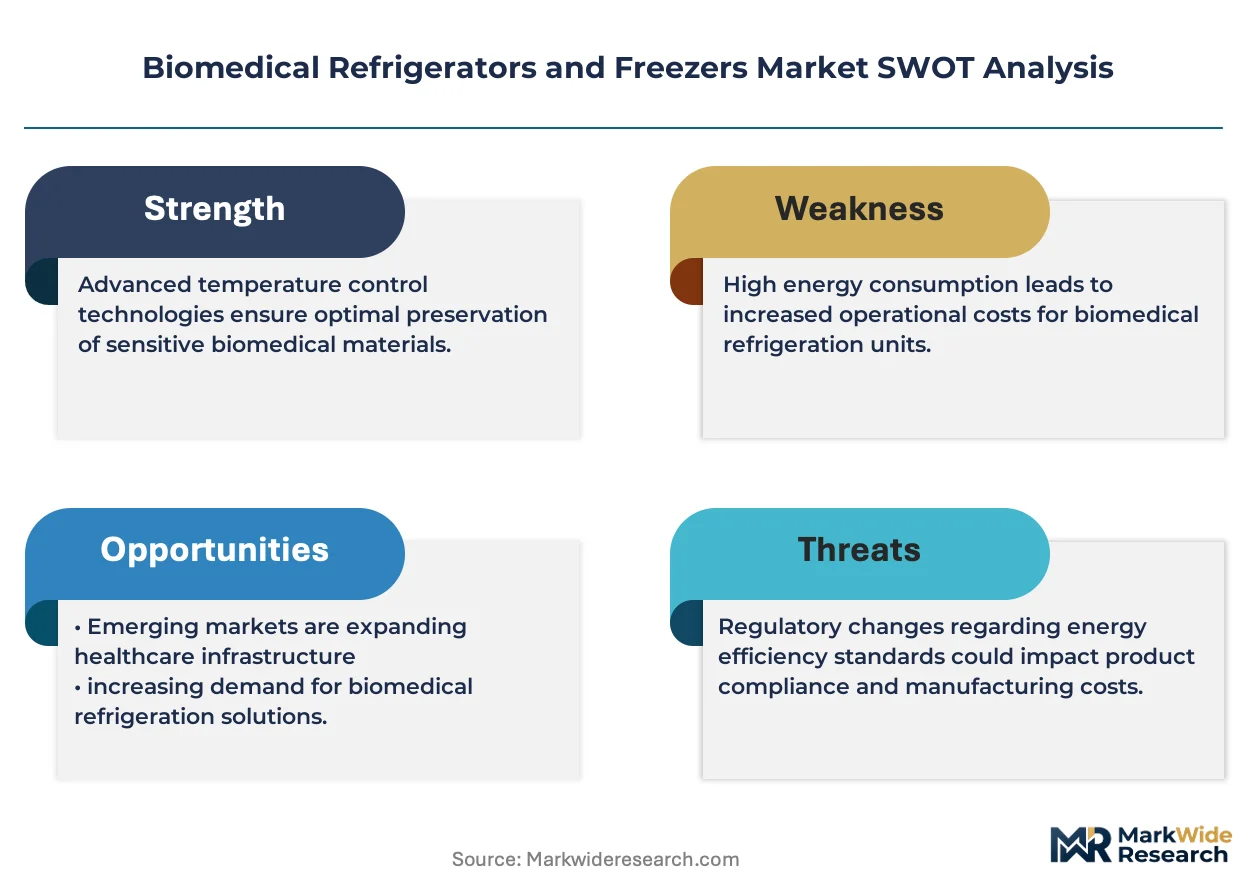
Refrigerant phase-down mandates under the EPA AIM Act and EU F-Gas Regulation are forcing manufacturers to redesign compressor architectures and insulation systems, compressing development cycles while elevating compliance costs across production networks.
Growth Catalysts
- CDSCO cold chain mandates:Blood bank expansion across India under national vaccine storage protocols is accelerating specification-grade unit procurement with integrated temperature logging systems.
- Hydrocarbon refrigerant transition:Propane and isobutane adoption in new cascade systems is opening design pathways for energy efficiency gains in ultra-low temperature categories.
- Heidelberg-Munich research corridor:Concentrated biologics research activity across Germany's laboratory cluster is sustaining premium demand for redundant compressor configurations.
Market Restraints
- Copper and aluminum input volatility:Compressor coil and heat exchanger materials face commodity price swings that compress margin structures for mid-tier manufacturers.
- Supply concentration in compressor motors:Precision motor winding capabilities concentrate in East Asian manufacturing bases, creating single-source exposure for European and North American assembly plants.
- EU MDR validation timelines:Extended conformity assessment procedures for clinical storage equipment are stretching product launch windows and freezing R&D budget allocation.
Strategic Opportunities
- Domestic manufacturing in Suzhou:China's import substitution push creates captive demand for locally assembled ultra-low temperature platforms serving pharmaceutical distribution networks.
- Natural refrigerant regulatory tailwinds:EPA hydrocarbon approval pathways and EU F-Gas quota reductions are incentivizing early mover positioning in sustainable cold chain infrastructure.
- Remote monitoring convergence:Integration of IoT sensor networks with electronic signature protocols is opening subscription revenue streams adjacent to hardware sales.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in cascade system design and vacuum panel insulation remains concentrated among aging technical workforces in Japan and Germany.
- Legacy equipment integration friction:Hospital pharmacy customers face protocol mismatches when connecting FDA 21 CFR Part 11-compliant monitoring systems to installed base units lacking digital output capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomedical Refrigerators and Freezers Market |
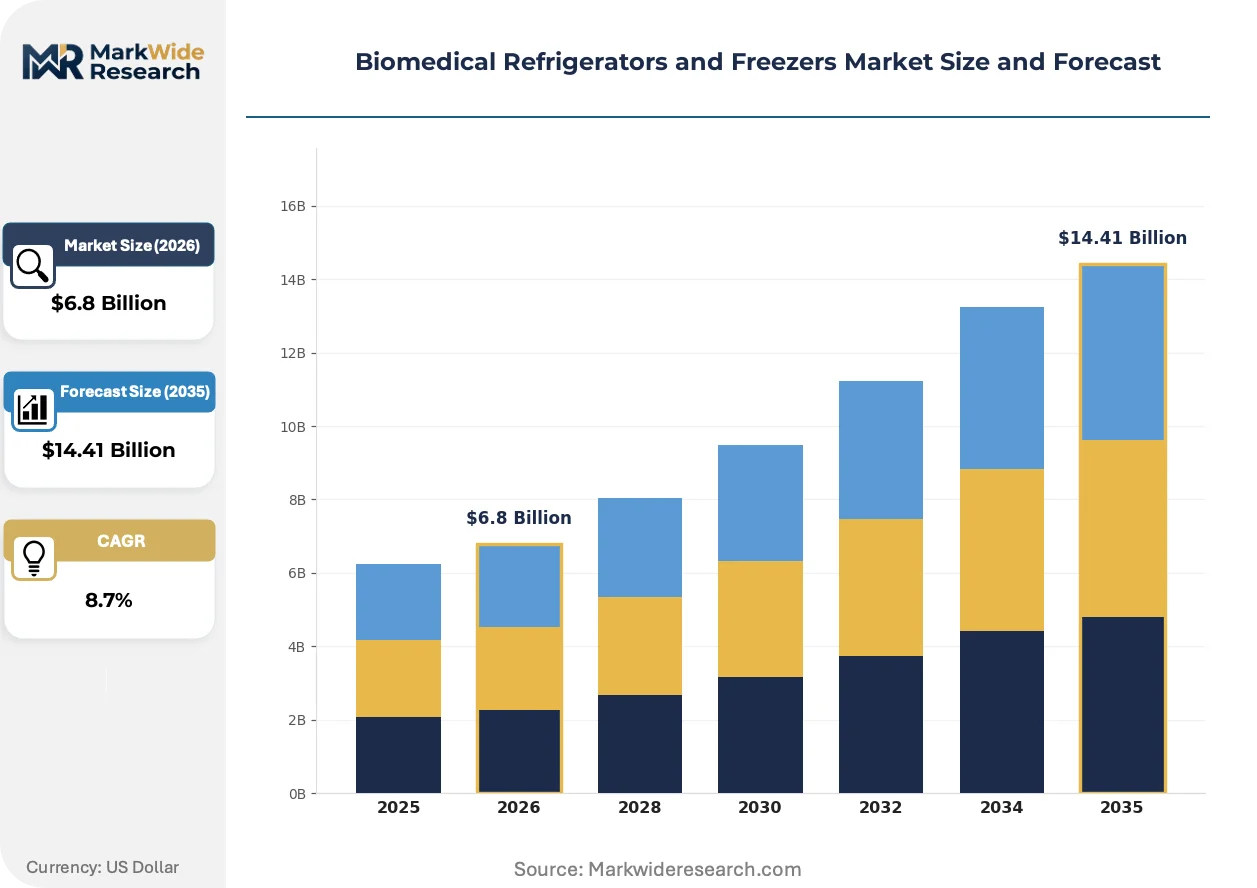
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Under-counter Refrigerators, Chest Freezers, Upright Freezers, Laboratory Refrigerators End User: Pharmacies, Hospitals, Research Laboratories, Blood Banks Temperature Range: Ultra-Low Temperature, Freezing, Refrigeration, Cryogenic Technology: Direct Cooling, Vapor Compression, Thermoelectric, Cascade |
| Companies Covered | Helmer Scientific, Panasonic Healthcare Corporation, Thermo Fisher Scientific Inc., Terumo Corporation, Philipp Kirsch GmbH, PHC Holdings Corporation, Eppendorf AG, B Medical Systems, Haier Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomedical Refrigerators and Freezers Market Emerging Trajectories
Active technology migration across cooling architectures, refrigerant chemistries, and validation protocols is compressing product lifecycles while elevating specification intensity for temperature uniformity and energy performance.
Cascade refrigeration systems using hydrocarbon working fluids are migrating from laboratory research settings into pharmaceutical distribution networks. Cold chain operators in Germany and Switzerland are piloting propane-based ultra-low temperature platforms for mRNA vaccine storage. This technology shift is compressing demand for legacy HFC-dependent systems and forcing compressor suppliers to retool production lines.
EU F-Gas Regulation quota reductions and EPA SNAP approvals for hydrocarbon alternatives are accelerating refrigerant transition roadmaps across original equipment manufacturers. Industrial consequence includes accelerated R&D spend on flammable refrigerant safety systems and pressure-rated enclosures. Blood bank and hospital pharmacy segments in Europe are responding by extending replacement cycles on existing HFC equipment while negotiating future-proofing clauses in procurement contracts.
Service contract unbundling is disrupting traditional equipment-plus-maintenance bundling in North American hospital procurement. Independent service organizations are capturing calibration and validation work previously captive to manufacturers. This pattern is most visible in tertiary care networks across the United States seeking to reduce capital commitment and shift temperature monitoring compliance to operational expenditure budgets.
Biomedical Refrigerators and Freezers Market Segmentation
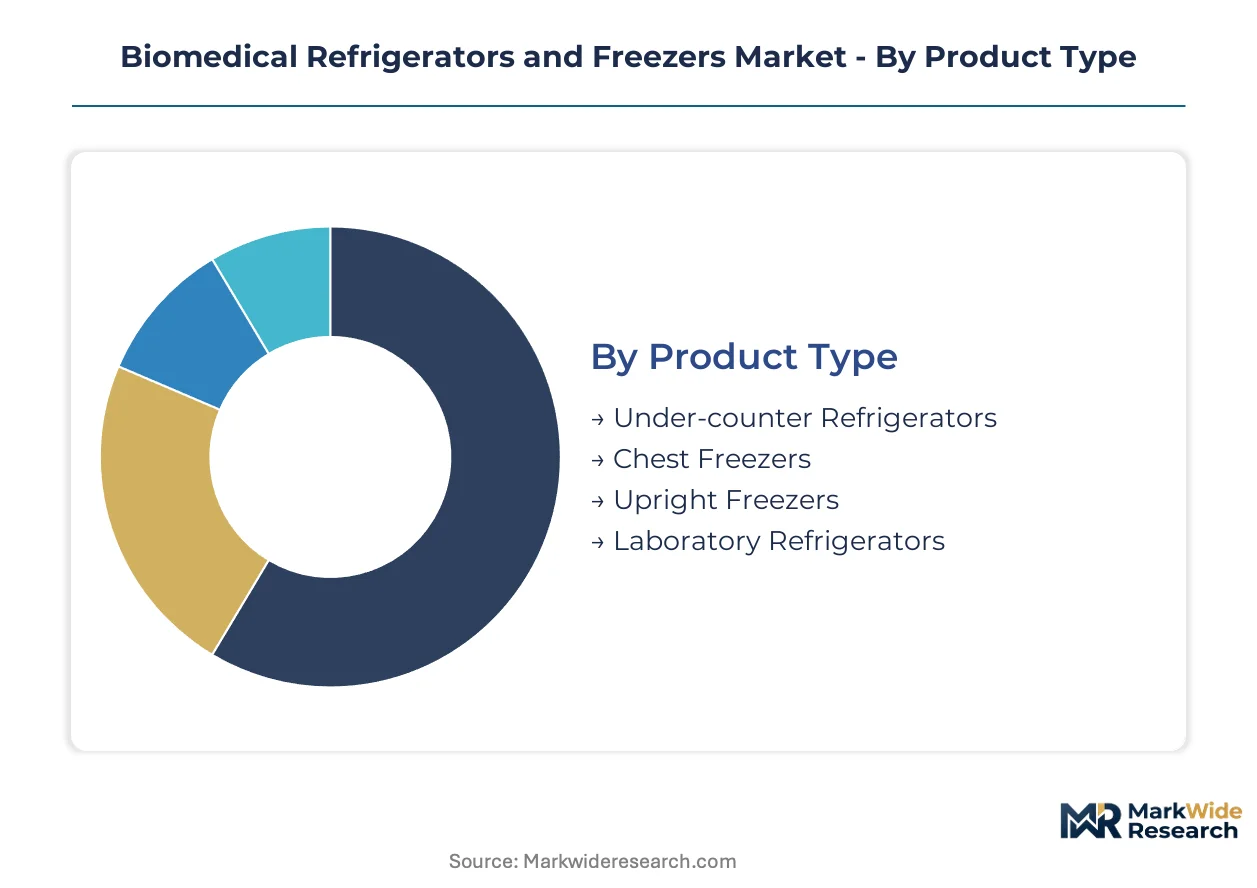
Equipment specification intensity varies sharply across biomedical cold chain segments, with validation protocols and service contract structures creating divergent margin profiles. Temperature uniformity requirements and regulatory traceability demands fragment procurement patterns across end-use categories.
Product Type:
After-sales service intensity escalates with compressor redundancy complexity and insulation system sophistication across product configurations.
- Upright Freezers:Vertical cabinet designs optimize floor space utilization in constrained hospital pharmacy environments. Blood banks across India under CDSCO protocols specify these units with integrated temperature logging for plasma inventory management.
- Laboratory Refrigerators:Precision vapor compression platforms maintain tight temperature bands for reagent and specimen preservation. Research laboratories in Germany's Heidelberg-Munich corridor sustain premium procurement for redundant cooling configurations.
- Under-counter Refrigerators:Compact footprint units serve point-of-care medication storage in clinical settings with space constraints.
- Chest Freezers:Top-opening designs prioritize thermal retention efficiency for bulk vaccine and biological sample archiving.
Upright Freezers holds the largest share; momentum sits with Laboratory Refrigerators.
End User:
Capital deployment cycles and compliance burden intensity diverge sharply across institutional buyer categories.
- Blood Banks:Regulatory validation demands under FDA 21 CFR Part 11 and EU MDR protocols drive specification-grade procurement with continuous monitoring systems. CDSCO cold chain mandates across India accelerate unit replacement with temperature alarm integration.
- Research Laboratories:Ultra-low temperature requirements for biologics storage command cascade system configurations with hydrocarbon refrigerant transitions. Germany's laboratory cluster sustains concentrated demand for redundant compressor architectures.
- Hospitals:Pharmacy and clinical storage applications span standard refrigeration through cryogenic ranges with service contract unbundling trends.
- Pharmacies:Vaccine storage protocols and medication cold chain requirements shape mid-tier procurement with validation documentation needs.
Blood Banks holds the largest share; Research Laboratories are climbing the fastest.
Temperature Range:
Energy consumption profiles and insulation system costs escalate non-linearly as temperature setpoints descend below standard refrigeration thresholds.
- Ultra-Low Temperature:Cascade and Stirling cooling architectures maintain minus 80 degree Celsius setpoints for long-term biologics preservation. mRNA vaccine storage requirements in Germany and Switzerland pilot propane-based platforms.
- Cryogenic:Liquid nitrogen vapor phase systems serve cell therapy and regenerative medicine applications with specialized handling protocols.
- Freezing:Minus 20 to minus 40 degree Celsius bands accommodate plasma, enzymes, and diagnostic reagent storage with vapor compression efficiency.
- Refrigeration:Standard 2 to 8 degree Celsius ranges dominate unit volume with mature replacement cycles across hospital and pharmacy segments.
Refrigeration holds the largest share; Ultra-Low Temperature shows the steepest expansion trajectory.
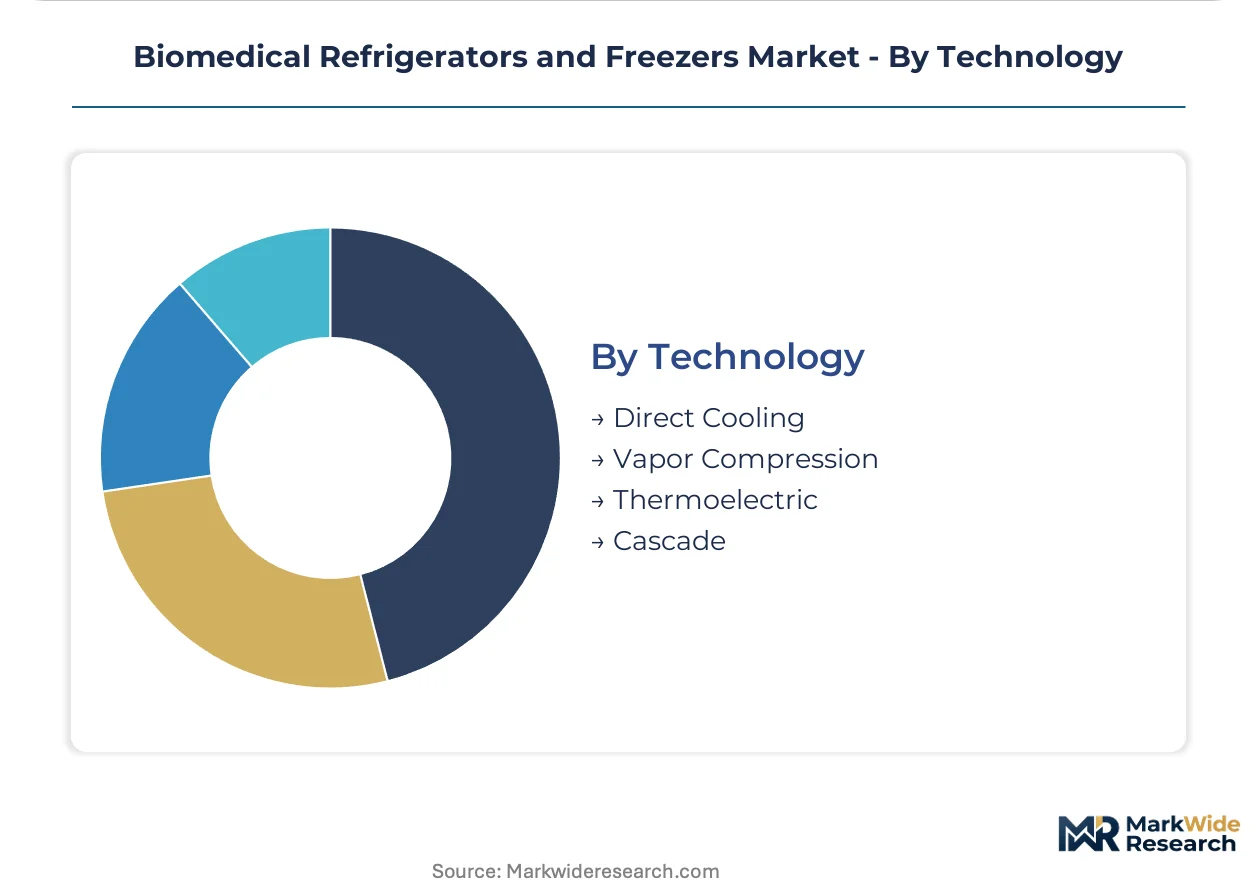
Technology:
Refrigerant chemistry transitions under EPA AIM Act and EU F-Gas Regulation are compressing development cycles across cooling architecture categories.
- Vapor Compression:Dominant cooling platform utilizing hydrocarbon and natural refrigerant alternatives with redesigned safety enclosures. EPA SNAP approvals accelerate propane and isobutane adoption in new unit designs.
- Cascade:Stacked refrigeration circuits achieve ultra-low temperatures with specialized vacuum panel insulation. EU F-Gas quota reductions force compressor supplier retooling for flammable refrigerant compatibility.
- Thermoelectric:Solid-state cooling eliminates compressor maintenance for small-volume portable applications with limited temperature pull-down capability.
- Direct Cooling:Simplified heat exchange architectures serve economy-tier segments with baseline temperature maintenance requirements.
Vapor Compression holds the largest share; Cascade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing clusters in East Asia supply precision motor windings to assembly plants worldwide, while regulatory divergence across FDA, EMA, and CDSCO jurisdictions fragments validation protocols for cold chain equipment.
United States
Hospital pharmacy networks and blood bank operators drive specification-grade procurement with integrated temperature logging systems. FDA 21 CFR Part 11 mandates electronic signature compatibility and continuous monitoring documentation. Tertiary care facilities in the Northeast Corridor and California are unbundling service contracts to shift compliance costs toward operational expenditure budgets.
Germany
The Heidelberg-Munich research corridor sustains concentrated demand for redundant compressor configurations in ultra-low temperature categories. EU F-Gas Regulation quota reductions accelerate hydrocarbon refrigerant transitions in cascade system designs. Bavarian laboratory clusters pilot propane-based platforms for mRNA vaccine storage protocols.
China
Domestic manufacturing expansion in Suzhou and Shenzhen narrows import dependency for pharmaceutical distribution networks. NMPA alignment with international cold chain standards elevates validation requirements for locally assembled units. Yangtze River Delta production bases now capture captive demand from state-owned vaccine logistics operators.
India
Blood bank expansion under CDSCO cold chain mandates accelerates unit replacement with temperature alarm integration. National vaccine storage protocols drive specification-grade procurement across public health infrastructure. Maharashtra and Gujarat host the fastest-growing clusters of cold chain equipment distributors serving regional plasma inventory networks.
Japan
Precision vapor compression engineering expertise concentrates among established technical workforces serving hospital pharmacy segments. METI efficiency standards and PMDA validation protocols shape domestic procurement specifications. Osaka-based manufacturing maintains specialized capabilities in vacuum panel insulation for cryogenic applications.
Biomedical Refrigerators and Freezers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling compressor motors, heat exchangers, and precision insulation materials. The vendor base spans multinational conglomerates with diversified life science portfolios, mid-cap regional fabricators, and niche specialists in cryogenic engineering. Three archetypes dominate: diversified laboratory equipment conglomerates, dedicated cold chain system builders, and precision component suppliers. Competitive moves concentrate on hydrocarbon refrigerant platform launches and geographic expansion through distribution partnerships in emerging pharmaceutical markets.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Eppendorf AG exemplify platform integrators with broad portfolio breadth. Haier Biomedical anchors volume production capabilities across Asia-Pacific markets. PHC Holdings Corporation occupies a specialized position in precision vapor compression systems for clinical storage applications. Philipp Kirsch GmbH represents German engineering-focused fabrication serving European research laboratory demand.
| Leading Market Players |
|---|
| Helmer Scientific |
| Panasonic Healthcare Corporation |
| Thermo Fisher Scientific Inc. |
| Terumo Corporation |
| Philipp Kirsch GmbH |
| PHC Holdings Corporation |
| Eppendorf AG |
| B Medical Systems |
| Haier Biomedical |
| Others |
Supply Flow & Price Mechanics
Suzhou's precision motor winding capacity anchors compressor supply for biomedical cold chain equipment, concentrating upstream pricing power among East Asian suppliers while downstream buyers in Europe and North America face cost pass-through pressure on cascade system assemblies.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across biomedical refrigeration equipment, with quota-driven hydrocarbon transitions compressing margins on legacy HFC-dependent platforms. Pricing stratifies across premium redundant compressor configurations, standard vapor compression units, and economy-tier direct cooling systems based on certification grade and after-sales bundling intensity. Cost compression in mid-tier segments is intensifying because copper and aluminum commodity volatility feeds directly into heat exchanger production economics. Hospital pharmacy networks exhibit the highest price sensitivity due to unbundled service contract migration, while research laboratories in Germany's Heidelberg-Munich corridor show lowest sensitivity given specification-grade demands for biologics preservation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for biomedical cold chain equipment manufacturers sourcing precision compressor motors. Production gravity centers on China, Japan, and Germany, with East Asian facilities supplying motor windings and vacuum panel insulation while German engineering houses specialize in cascade system integration. Raw material dependencies rest on copper coil stock, aluminum heat exchanger extrusions, and hydrocarbon refrigerant feedstocks. Single-source vulnerability concentrates in precision motor winding capabilities concentrated in Suzhou and Shenzhen production bases. Distribution runs through pharmaceutical logistics operators and hospital GPO procurement networks with validation documentation requirements extending fulfillment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biomedical refrigerators and freezers market functions as a regulatory-moat defensive story where FDA 21 CFR Part 11 and EU MDR validation entrenchment creates switching costs that freeze out unqualified competitors and protect incumbent margin structures.
For Market Incumbents: Harden compliance infrastructure against emerging hydrocarbon refrigerant safety certification requirements while embedding IoT monitoring capabilities to capture subscription revenue streams adjacent to hardware sales. Backward integration into compressor motor production in Suzhou or Shenzhen reduces single-source exposure from East Asian suppliers. Capacity addition in India serves CDSCO-mandated blood bank expansion with locally assembled units to deflect import duty pressure. For New Entrants and Emerging Players: Mid-tier hospital pharmacy networks in Southeast Asia represent the most penetrable entry point given specification intensity gaps versus European and North American procurement standards. Independent service organization partnerships offer a channel to capture calibration and validation work previously captive to manufacturer bundling. Target blood bank distributors in Maharashtra and Gujarat with temperature alarm-integrated units priced below Thermo Fisher and PHC Holdings premium positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because validation protocol complexity and refrigerant transition R&D cycles extend competitive moats beyond typical industrial equipment horizons. Acquisition targets should prioritize cryogenic engineering talent pools in Japan and Germany where aging technical workforces concentrate irreplaceable cascade system design expertise. Monitor EPA SNAP approval velocity for hydrocarbon refrigerant pathways as the signal indicating margin expansion timing for early-mover platform investments.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | EPA SNAP approvals for propane-based cascade systems open energy efficiency positioning in ultra-low temperature categories. |
| Domestic Manufacturing Expansion | Suzhou and Shenzhen production bases capture captive demand from China's state-owned vaccine logistics operators under NMPA alignment. |
| IoT Monitoring Integration | FDA 21 CFR Part 11-compliant sensor networks enable subscription revenue streams adjacent to hardware sales in hospital pharmacy segments. |
| Service Contract Unbundling | Independent calibration and validation work shifts compliance costs to operational expenditure budgets in tertiary care networks. |
| Cryogenic Engineering Acquisition | Specialized cascade system design expertise in Japan and Germany addresses talent scarcity constraining vacuum panel insulation advancement. |
Methodological Framework
The analysis maps ultra-low temperature cascade systems, vapor compression platforms, and thermoelectric cooling architectures, each validated through hospital pharmacy procurement managers, blood bank operations directors, and biomedical engineering specialists. Primary interviews with GPO contracts managers and regulatory affairs leads at cold chain equipment manufacturers combined with secondary validation from FDA 510(k) filings, EMA technical documentation, and CDSCO cold chain guidelines. Bottom-up unit shipment modeling triangulates against top-down pharmaceutical distribution infrastructure spending estimates.
Assumptions held fixed include refrigerant phase-down timelines under EPA AIM Act and EU F-Gas Regulation, while variables tested encompass hydrocarbon adoption velocity and blood bank expansion rates across India. Segmentation dimensions span product type, end-user category, temperature range, and cooling technology architecture across the analysis window. CAGRs derive from fitted growth curves applied to validated base-year estimates with cross-reference to compressor motor production capacity disclosures and hospital capital expenditure survey data.
Practitioners should monitor refrigerant safety standard revisions and copper commodity price volatility for early signals demanding forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Centrifuge Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Patient Lifting Equipment Market