
 US Radiotherapy Market | 2026-2036
US Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
US Radiotherapy Market Insights
Multi-source equipment procurement is hardening among large health systems seeking resilience against single-vendor service dependencies. Varian Medical Systems leverages its installed base of linear accelerators to sustain recurring service revenue across academic medical centers. Elekta competes through specialized stereotactic platforms that anchor Nordic-design workflows in US radiation oncology departments.
US radiotherapy encompasses external beam and internal radiation systems that generate ionizing energy to destroy malignant cells, typically operating at 6-18 MV photon energies with sub-millimeter targeting precision. Linear accelerators command the dominant share of capital expenditure as health systems prioritize vault-ready, image-guided platforms. Intensity-modulated radiation therapy represents the fastest-growing delivery mode, with margin pools shifting toward adaptive planning software that integrates real-time imaging feedback.
FDA clearance pathways for novel beam modalities and NRC oversight of radioactive source security jointly elevate compliance costs for market entrants. CMS national coverage determinations directly shape provider reimbursement and therefore equipment purchasing timelines. Stakeholders must monitor emerging artificial intelligence-based contouring tools and their parallel regulatory classification pathways to anticipate workflow disruption and competitive repositioning.
Market Dynamics
Hypofractionated treatment regimens are compressing reimbursement timelines and forcing accelerated capital replacement cycles across US cancer centers, fundamentally altering equipment procurement cadences.
Growth Catalysts
- CMS Reimbursement Pathways:National coverage determinations for condensed treatment schedules incentivize health systems to upgrade aging linear accelerator fleets.
- Proton Center Construction:Texas, California, and Florida anchor capital deployment for particle therapy facilities with dedicated vault infrastructure.
- Image-Guided Platforms:Real-time imaging integration during beam delivery is elevating clinical precision thresholds and equipment specifications.
Market Restraints
- Vault Construction Costs:Radiation shielding requirements for megavoltage systems impose fixed infrastructure burdens that constrain site expansion.
- Radioactive Source Security:NRC oversight of cobalt-60 and cesium-137 inventory elevates compliance overhead and insurance liabilities.
- Single-Vendor Service Dependencies:Proprietary maintenance contracts with dominant equipment suppliers limit operational flexibility for mid-sized oncology networks.
Strategic Opportunities
- Adaptive Planning Software:AI-driven contouring tools that integrate real-time imaging feedback represent uncaptured margin pools beyond hardware sales.
- Stereotactic Platforms:Nordic-designed workflow systems are penetrating academic medical centers seeking differentiated radiosurgery capabilities.
- Multi-Source Procurement:Large health systems are diversifying vendor relationships to mitigate service disruption risks and strengthen negotiating leverage.
Industry Challenges
- Medical Physics Talent Scarcity:Board-certified dosimetrists and radiation physicists command premium compensation, constraining treatment capacity expansion.
- Legacy System Integration:PACS and EMR interoperability with new beam delivery platforms requires costly middleware development and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Radiotherapy Market |
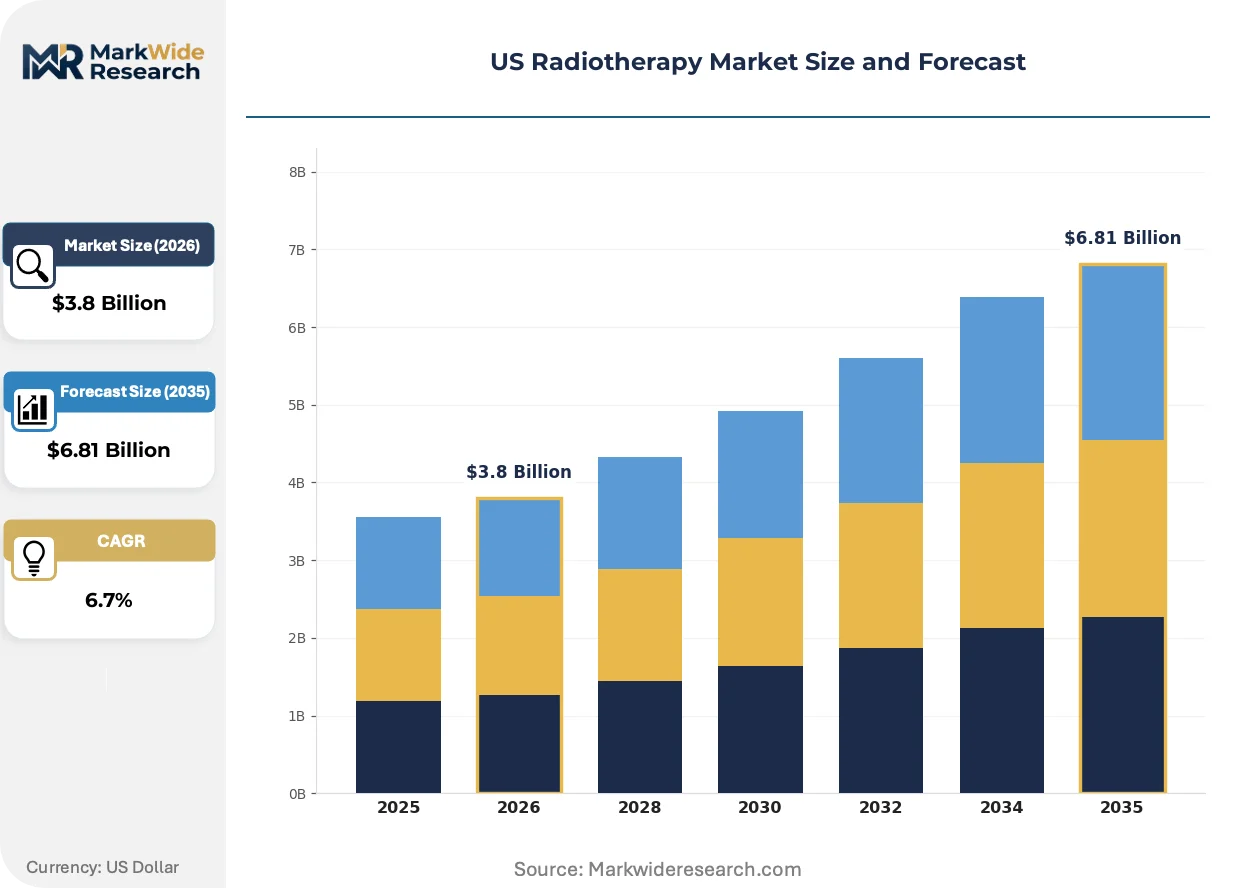
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy Devices, Radiation Therapy Planning Systems, Imaging Systems Delivery Mode: External Beam Radiation Therapy, Internal Radiation Therapy, Stereotactic Radiosurgery, Intensity-Modulated Radiation Therapy End User: Hospitals, Cancer Treatment Centers, Outpatient Clinics, Academic Research Institutions Application: Oncology Treatments, Palliative Care, Radiosurgery, Preoperative Treatment |
| Companies Covered | Varian Medical Systems, Accuray Incorporated, Elekta, Mevion Medical Systems, ViewRay Technologies, GE Healthcare, RefleXion Medical, Brainlab, Canon Medical Systems Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Radiotherapy Market Trends and Innovations
Beam modality diversification and software-defined treatment planning are compressing the traditional hardware-centric business model, shifting value capture toward algorithmic and service layers.
Magnetic resonance-guided radiation therapy is electrifying real-time tumor tracking capabilities. Academic medical centers in the Northeast and Midwest are piloting these hybrid systems for abdominal and thoracic malignancies. The technology is electrifying adaptive replanning workflows that previously required fraction-to-fraction imaging gaps.
FDA clearance pathways for artificial intelligence-based contouring tools are creating parallel regulatory classification frameworks. Device manufacturers must now navigate software-as-medical-device submissions alongside traditional 510(k) hardware approvals. Radiation oncology departments are responding by establishing dedicated AI validation committees and vendor qualification protocols.
After-sales service unbundling is fragmenting the traditional equipment-vendor relationship. Large health systems are insourcing preventive maintenance for linear accelerator subsystems while retaining specialized vendor contracts for beam calibration and regulatory dosimetry. This pattern is most visible in Texas and California where consolidated delivery networks command sufficient scale to justify captive technical staff.
US Radiotherapy Market Segmentation
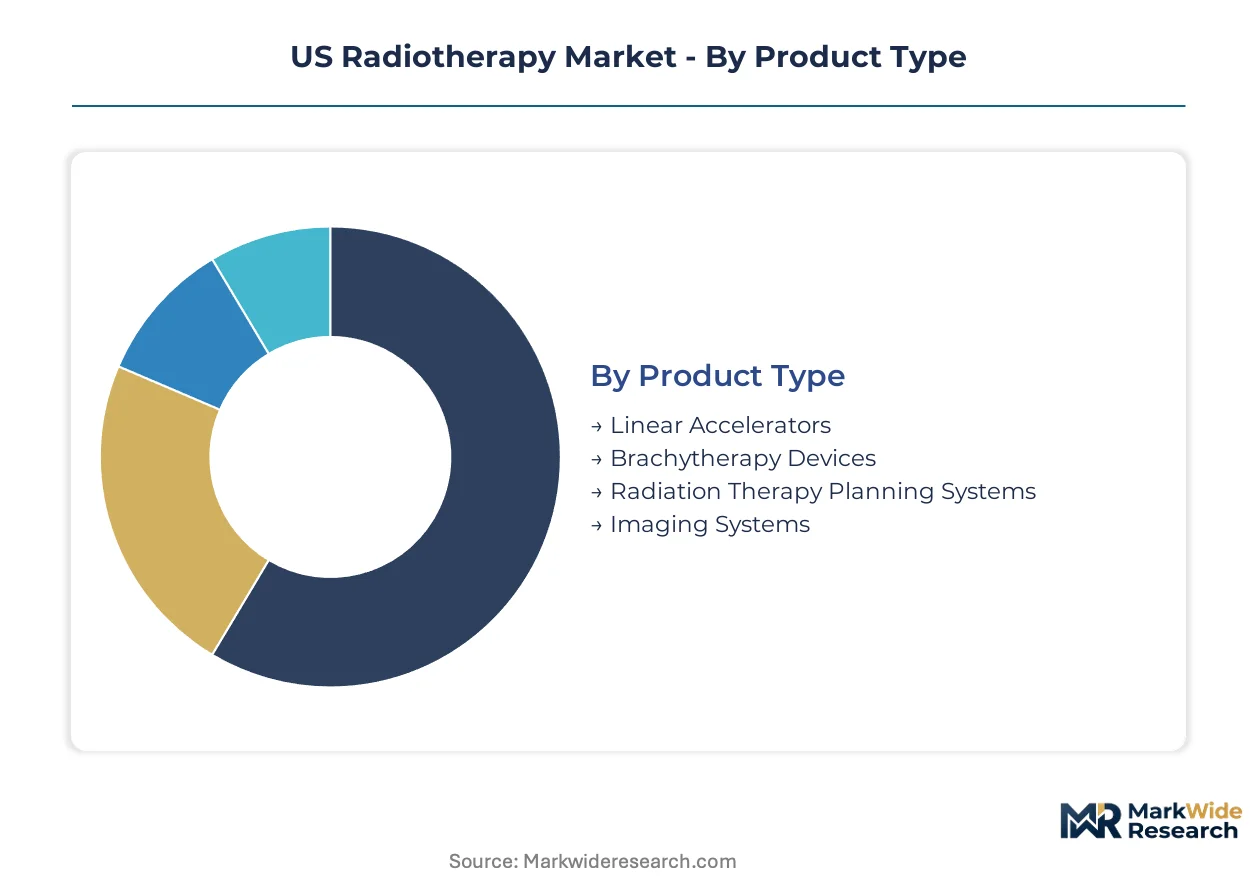
Equipment procurement patterns across US cancer centers diverge sharply by clinical workflow, reimbursement structure, and vault infrastructure requirements. Understanding these segment boundaries clarifies why capital allocation concentrates in specific delivery modes and end-user settings rather than distributing evenly across product categories.
Product Type:
Capital intensity and service contract structures dominate buyer decisions, with health systems weighing upfront vault costs against recurring software licensing and maintenance obligations.
- Linear Accelerators:These megavoltage systems generate 6-18 MV photon beams for external treatment delivery. Demand clusters in Texas, California, and Florida where proton center construction and vault-ready upgrades anchor capital planning cycles.
- Brachytherapy Devices:Internal radiation systems deploy sealed radioactive sources directly within tumor cavities or body cavities. NRC oversight of cobalt-60 and cesium-137 inventory elevates compliance overhead, constraining adoption in mid-sized oncology networks lacking dedicated radiation safety officers.
- Radiation Therapy Planning Systems:Software platforms for dose calculation and beam optimization.
- Imaging Systems:CT and MR-compatible hardware for treatment simulation and verification.
Linear accelerators lead on scale; radiation therapy planning systems lead on momentum.
Delivery Mode:
Reimbursement compression from hypofractionated regimens is accelerating replacement cycles, with providers prioritizing modalities that compress treatment timelines without sacrificing precision.
- Intensity-Modulated Radiation Therapy:Computer-controlled beam modulation sculpts dose distributions to conform precisely to irregular tumor geometries. CMS national coverage determinations for condensed schedules incentivize upgrades from conventional conformal systems.
- Stereotactic Radiosurgery:High-dose, single-fraction or limited-fraction delivery demands sub-millimeter targeting precision. Academic medical centers in the Northeast and Midwest pilot these capabilities for cranial and spinal lesions, anchoring Nordic-designed workflow adoption.
- External Beam Radiation Therapy:Conventional fractionated delivery remains the volume backbone.
- Internal Radiation Therapy:Brachytherapy-based approaches for gynecologic and prostate malignancies.
External beam radiation therapy leads on scale; intensity-modulated radiation therapy leads on momentum.
End User:
Scale economics and physics talent availability determine site selection, with board-certified dosimetrist scarcity constraining expansion outside consolidated metropolitan markets.
- Cancer Treatment Centers:Dedicated oncology facilities command the highest equipment utilization rates and justify premium linear accelerator specifications. These centers concentrate in Florida and California where patient volume density supports dedicated vault infrastructure.
- Hospitals:Integrated health systems leverage multi-source procurement strategies to mitigate single-vendor service dependencies. Texas-based delivery networks particularly favor insourced preventive maintenance for accelerator subsystems.
- Outpatient Clinics:Limited-service settings focused on routine fractionation.
- Academic Research Institutions:Sites piloting magnetic resonance-guided and AI-adaptive platforms.
Hospitals lead on scale; cancer treatment centers lead on momentum.
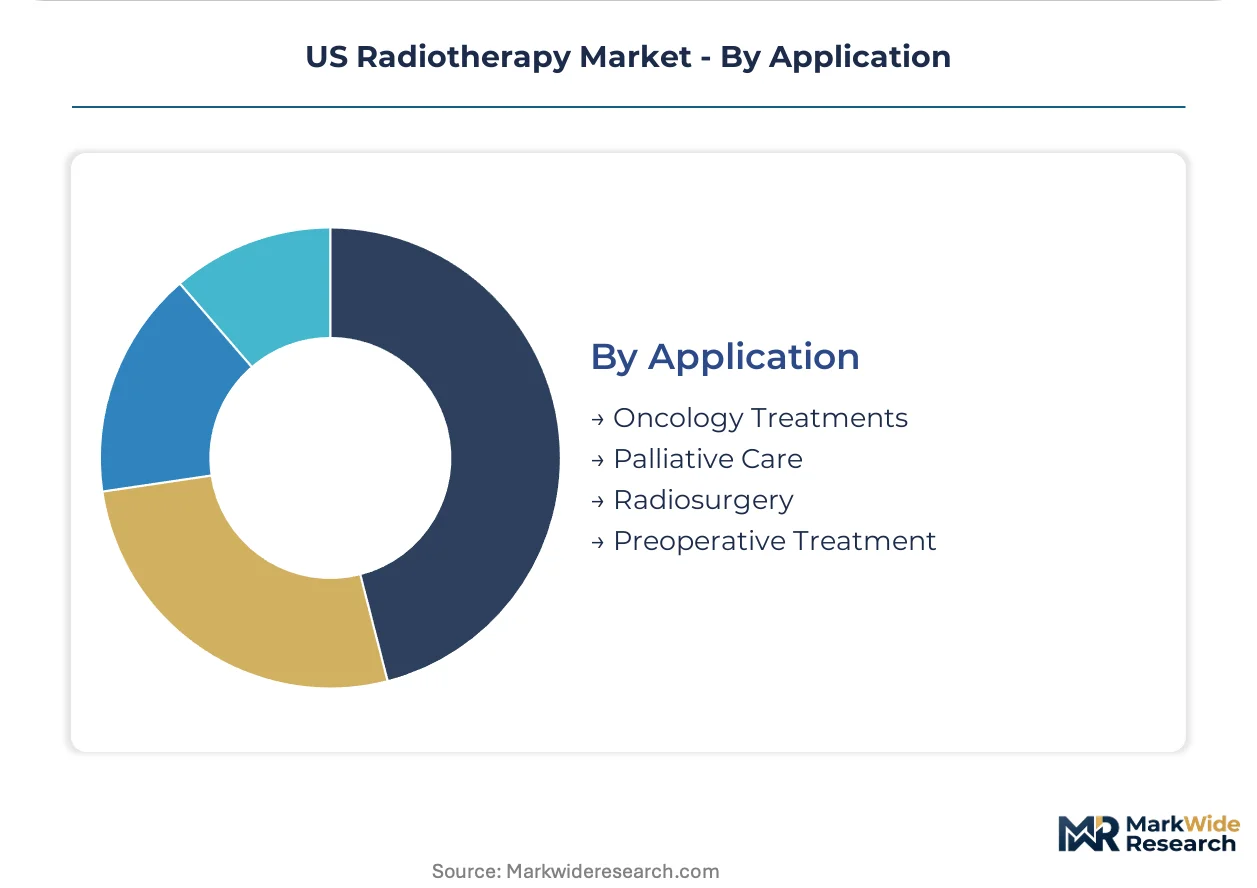
Application:
Clinical outcome requirements and reimbursement coding specificity shape modality selection, with curative intent treatments justifying higher capital specifications than palliative protocols.
- Oncology Treatments:Curative-intent protocols for solid tumors and hematologic malignancies dominate procedure volume. Real-time imaging integration during beam delivery elevates equipment specifications across Texas and California treatment networks.
- Radiosurgery:Single-session ablative delivery for cranial, spinal, and pulmonary lesions demands specialized stereotactic platforms. Academic medical centers anchor adoption where physics talent density supports complex treatment planning.
- Palliative Care:Symptom-directed fractionation for metastatic disease.
- Preoperative Treatment:Neoadjuvant protocols to downstage tumors prior to surgical resection.
Oncology treatments lead on scale; radiosurgery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Medical Center anchors proton therapy capital deployment, with MD Anderson Cancer Center and Baylor College of Medicine driving vault construction timelines that compress equipment procurement cycles across the state.
Texas
MD Anderson Cancer Center and Baylor St. Luke's Medical Center anchor proton center construction pipelines that demand specialized vault infrastructure. Texas Department of State Health Services radiation control regulations mandate shielding specifications that elevate compliance costs for linear accelerator installations. Houston and Dallas-Fort Worth metropolitan clusters concentrate capital planning for image-guided platform upgrades.
California
Stanford Health Care and UCLA Health drive demand for magnetic resonance-guided radiation therapy systems with adaptive replanning capabilities. California Department of Public Health Radiologic Health Branch enforces radioactive source security protocols that constrain brachytherapy device adoption. Los Angeles and San Francisco Bay Area academic medical centers pilot AI-based contouring tools under FDA software-as-medical-device pathways.
Florida
Moffitt Cancer Center and Baptist Health South Florida prioritize stereotactic radiosurgery platforms for cranial and spinal lesion protocols. Florida Bureau of Radiation Control oversees cobalt-60 inventory tracking that elevates operational overhead for mid-sized oncology networks. Tampa and Miami metropolitan treatment centers concentrate hypofractionated regimen adoption accelerated by CMS reimbursement determinations.
New York
Memorial Sloan Kettering Cancer Center and NYU Langone Health deploy Elekta stereotactic workflow systems for Nordic-design radiosurgery capabilities. New York State Department of Health Bureau of Environmental Radiation Protection mandates medical physics staffing ratios that constrain treatment capacity expansion. Manhattan and Long Island cancer treatment clusters drive multi-source procurement strategies to mitigate single-vendor service dependencies.
Illinois
Northwestern Medicine and University of Chicago Medicine integrate adaptive planning software with real-time imaging feedback for abdominal malignancies. Illinois Emergency Management Agency Radiation Safety Division regulates linear accelerator commissioning timelines that extend validation periods. Chicago metropolitan academic medical centers concentrate board-certified dosimetrist recruitment efforts amid national physics talent scarcity.
US Radiotherapy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue magnetic resonance-guided and AI-adaptive niches that demand specialized regulatory pathways. The vendor base stratifies across linear accelerator incumbents, proton therapy specialists, and software-defined planning platforms. Three archetypes dominate: integrated equipment-service providers, Nordic-design workflow specialists, and hybrid imaging-beam modality innovators. Consolidation pressure manifests through service contract unbundling and insourced preventive maintenance adoption.
Among integrated equipment-service providers, Varian Medical Systems and Elekta exemplify archetypes that leverage installed base density to sustain recurring revenue streams. Accuray Incorporated occupies a position within the stereotactic precision tier, anchoring specialized radiosurgery capabilities in academic medical center workflows. These three entities represent distinct competitive vectors: comprehensive platform breadth, Nordic-design workflow differentiation, and focused ablative delivery specialization.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Accuray Incorporated |
| Elekta |
| Mevion Medical Systems |
| ViewRay Technologies |
| GE Healthcare |
| RefleXion Medical |
| Brainlab |
| Canon Medical Systems Corporation |
| Others |
Pricing and Supply Chain Analysis
High-grade tungsten and cobalt price indices cascade through linear accelerator manufacturing tiers, compressing margins for vault-ready systems while elevating premium specifications for proton therapy infrastructure. Equipment vendors pass alloy cost volatility through to cancer treatment centers via escalator clauses in multi-year service contracts.
Pricing Analysis
Input-cost pass-through from rare earth magnet and radiation-grade steel suppliers stratifies equipment procurement across premium, standard, and economy tiers. FDA 510(k) clearance tier and NRC radioactive source certification grade differentiate price bands, with academic medical centers showing lowest price sensitivity for adaptive planning modules. Pricing pressure stems from CMS reimbursement compression for hypofractionated regimens, forcing mid-sized oncology networks toward standard-tier specifications. Community hospitals exhibit highest price sensitivity, deferring linear accelerator upgrades until warranty expiration triggers forced replacement.
Supply Chain Analysis
FDA quality system regulation and NRC material license qualification gates constrain supplier pools for megavoltage beam generation subsystems. Manufacturing concentrates in Germany, Sweden, and the United States for precision-machined gantry components. Supply chains draw from Chilean copper concentrate, Chinese rare earth processing, and domestic steel forging for vault-grade shielding. Single-source vulnerability persists for superconducting cyclotron magnets in proton therapy systems. Distribution runs through authorized dealer networks with embedded field service engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US radiotherapy market functions as a geographic-arbitrage play where Texas and Florida proton center construction timelines outpace California's regulatory commissioning delays, compressing capital deployment windows for equipment vendors.
For Market Incumbents: Anchor recurring revenue streams through unbundled service contracts that retain beam calibration and regulatory dosimetry while ceding preventive maintenance to insourced hospital technical staff. Defend against Nordic-design workflow specialists by embedding AI contouring tools within existing linear accelerator software ecosystems. Prioritize multi-source procurement resilience through certified third-party spare parts networks. For New Entrants and Emerging Players: Direct-to-clinic software licensing routes bypass capital-intensive hardware manufacturing barriers for AI-adaptive planning platforms. Target mid-sized oncology networks in Illinois and New York where medical physics talent scarcity constrains treatment capacity expansion. Pursue hospital system partnerships that bundle contouring software with existing Elekta or Varian installed bases. For Investors and Strategic Acquirers: Asymmetric upside sits with magnetic resonance-guided radiation therapy specialists holding FDA breakthrough device designation. Long-term viability hinges on reimbursement pathway expansion for real-time adaptive replanning. Acquisition focus should center on software-defined planning platforms with validated AI algorithms. Watch CMS national coverage determinations for hypofractionated regimens as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS national coverage determinations for condensed schedules accelerate equipment replacement cycles. |
| Hospital System Partnership | Multi-source procurement agreements with Texas delivery networks mitigate single-vendor service dependencies. |
| Software Companion Development | AI-driven contouring tools integrate real-time imaging feedback beyond hardware sales margins. |
| FDA Submission | Software-as-medical-device pathways for adaptive planning require parallel regulatory navigation. |
| CE Marking Pathway | European validation accelerates Nordic-design stereotactic platform penetration in US academic centers. |
Research Methodology
Multiple input streams — radiation oncology department heads, biomedical engineering directors, GPO contracts managers, and proton center project developers — were reconciled against CMS reimbursement databases, FDA 510(k) clearance records, and NRC material license filings. Secondary validation drew from hospital procurement databases, academic medical center capital expenditure disclosures, and state radiation control regulatory filings. Bottom-up equipment shipment tallies and top-down cancer incidence projections were triangulated to anchor market sizing.
Data-stream reconciliation across product type, delivery mode, end user, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle compression and proton center construction pipeline analysis. Modeled inputs included hypofractionated regimen adoption curves, vault construction cost trajectories, and medical physics staffing ratio constraints.
Regulatory pathway delays, reimbursement determination reversals, and radioactive source supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding CMS coverage expansion and NRC oversight continuity. A model refresh is warranted upon material change in national coverage determination timelines for adaptive radiation therapy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Microtome Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Medical Filter Market
Medical Equipment
MRI Transport Market