
 Global Countertop Platelet Incubator Market | 2026-2036
Global Countertop Platelet Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Countertop Platelet Incubator Market Foresight
Blood bank procurement is rebalancing toward multi-chamber automated systems as hospital networks consolidate platelet storage operations. Helmer Scientific leverages its North American installed base to sustain service revenue streams alongside hardware sales. Thermo Fisher Scientific anchors its position through diagnostic laboratory relationships that extend into adjacent blood management workflows. SARSTEDT AG & Co. KG competes on European regulatory alignment, while Labcold Ltd. specializes in compact footprint designs for space-constrained hematology labs.
A countertop platelet incubator is a temperature-controlled benchtop device that maintains platelet concentrates at 20-24°C with continuous gentle agitation to preserve viability before transfusion. These units integrate precise thermal management with orbital or linear agitation mechanisms to prevent platelet aggregation and maintain pH within acceptable ranges. Multi-chamber configurations command premium positioning by enabling simultaneous storage of multiple platelet units with independent environmental monitoring, while portable units serve satellite clinics and emergency response settings where fixed infrastructure is unavailable. Automated technology segments attract investment as blood banks seek to reduce manual intervention and documentation burden.
The FDA enforces platelet storage requirements under 21 CFR 606, while the EU Medical Device Regulation (MDR) imposes conformity assessment burdens on incubator manufacturers seeking CE marking. ISO 13485 quality management standards govern production processes, and the WHO's blood safety guidelines influence procurement specifications in developing health systems. Stakeholders must monitor evolving platelet additive solution approvals and agitation protocol standards that could render existing incubator inventories non-compliant or obsolete.
Market Dynamics
Hospital network consolidation is compressing platelet storage operations into centralized regional hubs, forcing blood banks to retire single-chamber units in favor of multi-chamber automated systems that reduce labor overhead and documentation burden.
Growth Catalysts
- FDA's updated 21 CFR 606 platelet storage guidelines:Tighter temperature and agitation requirements are accelerating replacement cycles for non-compliant incubator inventories across US blood centers.
- Japan's aging transfusion-dependent population:Rising demand for platelet concentrates in hematology and oncology protocols is expanding cold chain infrastructure in Tokyo and Osaka hospital networks.
- Multi-chamber automation technology:Independent environmental monitoring per chamber is reducing cross-contamination risk and enabling simultaneous storage of additive-solution variants.
Market Restraints
- Precision thermoelectric component supply:Concentrated sourcing of solid-state cooling modules from East Asian semiconductor fabs creates input volatility for incubator manufacturers.
- EU MDR conformity assessment burden:Extended CE marking timelines for Class IIa medical devices are delaying product launches and freezing R&D budgets.
- Room-temperature platelet alternatives:Lyophilized and cold-stored platelet formulations under clinical investigation threaten incumbent incubator demand if approved for routine transfusion.
Strategic Opportunities
- India's expanding blood bank network:WHO-influenced procurement specifications in tier-2 and tier-3 cities are opening demand for compact footprint units that fit space-constrained hematology labs.
- Portable battery-powered configurations:Satellite clinics and emergency response settings without fixed infrastructure represent underserved demand for mobile platelet preservation.
- ISO 13485 quality management convergence:Harmonized production standards are reducing certification duplication costs for manufacturers serving multiple export markets simultaneously.
Industry Challenges
- Biomedical equipment technician scarcity:Specialized calibration and maintenance skills for orbital agitation mechanisms are concentrating service capacity in major metropolitan hospital clusters.
- Legacy LIS integration complexity:Blood bank information system interoperability gaps are forcing costly middleware development for automated documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Countertop Platelet Incubator Market |
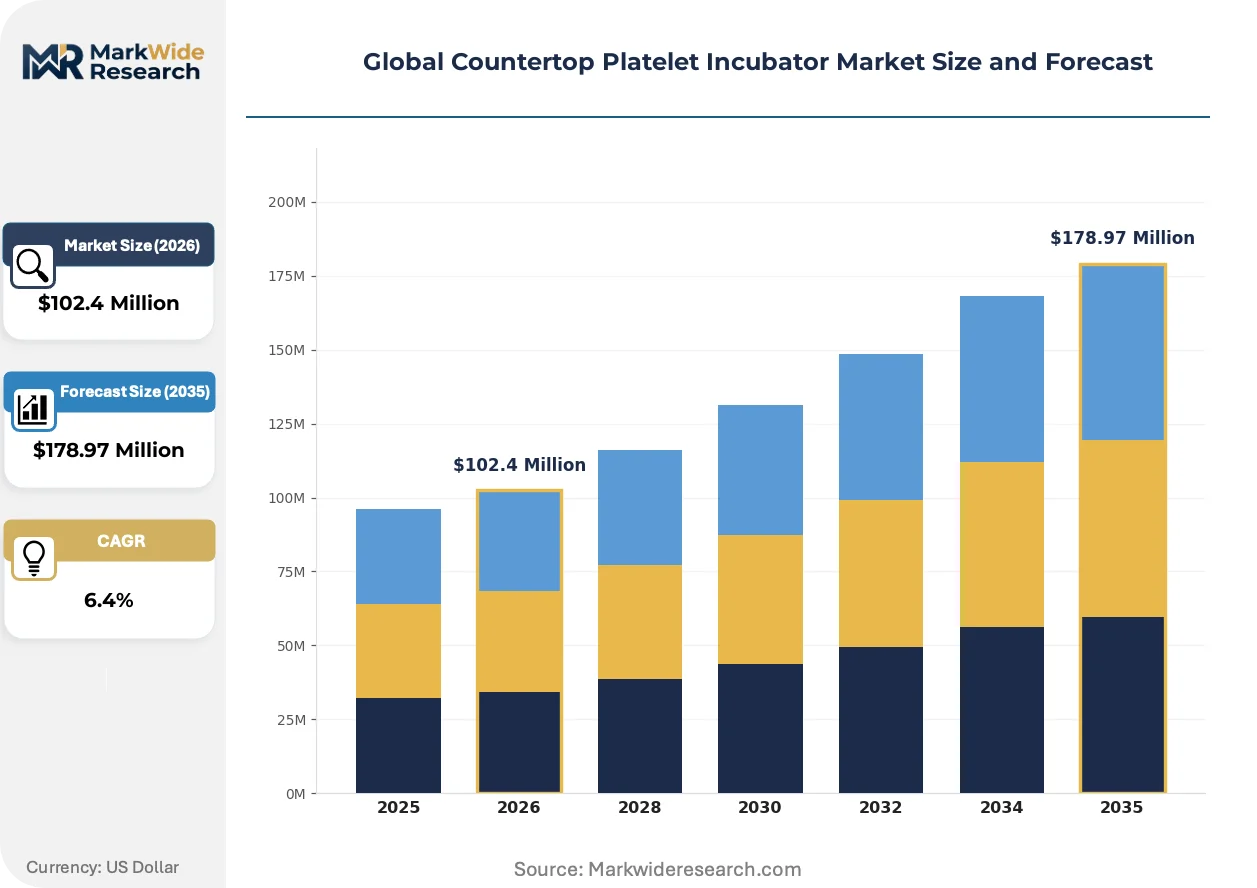
| Market Size in 2026 | $102.4 Million |
| Market Size in 2035 | $178.97 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber, Multi-Chamber, Portable, Automated, Semi-Automated Technology: Temperature Control, Agitation System, CO2 Incubation, Humidity Control, Sterilization Feature Application: Blood Banks, Hematology Labs, Pharmaceutical R&D, Clinical Research, Veterinary Diagnostics End User: Diagnostic Laboratories, Research Institutes, Biotechnology Companies, Academic Centers |
| Companies Covered | Helmer Scientific, Thermo Fisher Scientific, Boekel Scientific, SARSTEDT AG & Co. KG, Labcold Ltd., LMB Technologie GmbH, EMSAS Electrical Equipment Industry and Trading Inc., Terumo Corporation, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Countertop Platelet Incubator Market Shifts & Advancements
Automation is penetrating platelet storage workflows at the chamber level, with sensor networks and algorithmic environmental control displacing manual monitoring protocols that dominated the past decade.
Multi-chamber incubator platforms with independent microprocessor-controlled thermal zones are automating agitation speed and temperature adjustments based on real-time pH telemetry. Large hospital networks in Germany and the United States are deploying these systems to consolidate platelet inventory from multiple satellite collection sites. This automation is compressing staffing ratios in blood bank operations while raising the technical bar for equipment procurement specifications.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are forcing manufacturers to implement systematic vigilance reporting for thermal excursion events. Incubator producers must now maintain electronic records of field performance data across their installed base. Blood banks in France and the Netherlands are prioritizing vendors with established EU notified body relationships to minimize compliance transition risk.
Centralized procurement through group purchasing organizations is consolidating vendor relationships and unbundling after-sales service contracts from hardware transactions. Hospital networks in Japan and the United States are negotiating multi-site maintenance agreements separately from capital equipment purchases. This unbundling is most visible in North American integrated delivery networks where procurement officers now benchmark service response times independently of unit acquisition costs.
Global Countertop Platelet Incubator Market Segmentation
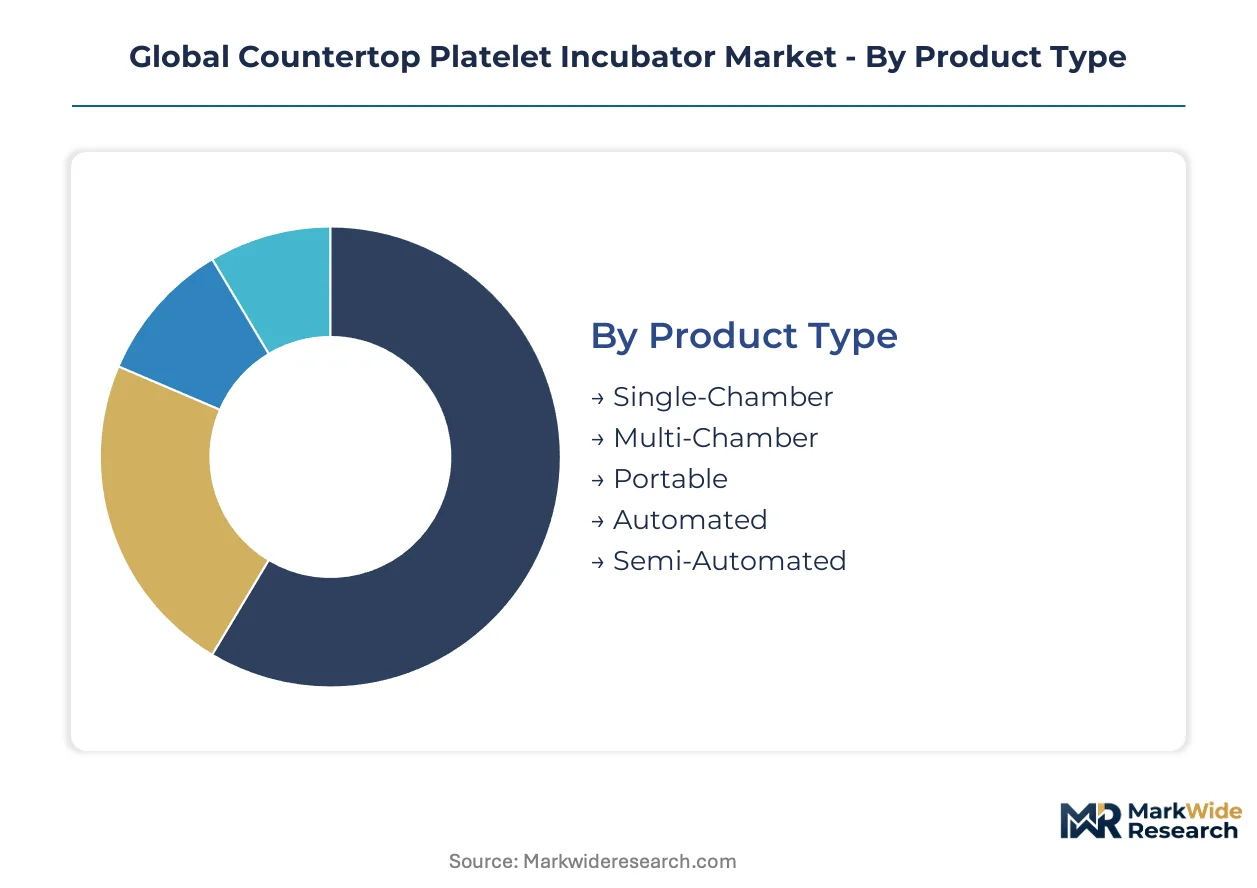
Segmentation in the countertop platelet incubator market tracks divergent upgrade cycles across blood bank infrastructure tiers. Procurement specifications vary sharply between centralized hospital networks replacing legacy single-chamber units and satellite clinics acquiring first-time portable systems.
Product Type:
Replacement cycles for aging incubator inventories are compressing as FDA storage guideline enforcement tightens temperature and agitation compliance windows.
- Multi-Chamber:These units deploy independent microprocessor-controlled thermal zones with per-chamber environmental monitoring. Blood banks in Germany and the United States are consolidating satellite inventory into these platforms to reduce staffing ratios and cross-contamination risk.
- Automated:Algorithmic agitation speed adjustment based on real-time pH telemetry eliminates manual intervention. Hospital networks in Japan are prioritizing these systems for documentation workflow integration with blood bank information systems.
- Single-Chamber:Legacy units dominate retirement schedules across US blood centers facing 21 CFR 606 compliance deadlines.
- Portable:Battery-powered configurations serve emergency response settings and rural clinics lacking fixed infrastructure in India's tier-2 cities.
- Semi-Automated:Hybrid units retain manual override capabilities for facilities with limited biomedical technician coverage.
Multi-Chamber sits at the top of the volume ranking, with Portable climbing the fastest.
Technology:
Cost tiers separate precision thermoelectric cooling from conventional compressor-based systems, with solid-state modules commanding premium positioning.
- Temperature Control:Thermoelectric modules maintain 20-24°C setpoints within ±0.5°C tolerance. Supply concentration in East Asian semiconductor fabs creates input volatility for manufacturers sourcing solid-state cooling components.
- Agitation System:Orbital and linear mechanisms prevent platelet aggregation while preserving pH. Calibration complexity is concentrating service capacity in major metropolitan hospital clusters in the United States and Japan.
- CO2 Incubation:pH buffering systems for specific platelet additive formulations.
- Humidity Control:Evaporation prevention for extended storage protocols in research settings.
- Sterilization Feature:UV or heat-based chamber decontamination for multi-user laboratory environments.
Temperature Control captures the largest installed base, though Agitation System is expanding most quickly as FDA agitation protocol standards tighten.
Application:
Customer type stratification separates high-throughput transfusion centers from low-volume research environments with divergent automation requirements.
- Blood Banks:Centralized regional hubs in hospital networks are retiring single-chamber inventories for multi-chamber automated platforms. Procurement runs through group purchasing organizations unbundling service contracts from hardware.
- Hematology Labs:Space-constrained facilities in Tokyo and Osaka are prioritizing compact footprint designs with independent chamber monitoring for simultaneous storage of additive-solution variants.
- Pharmaceutical R&D:Platelet function studies and additive solution development drive demand for precision environmental telemetry.
- Clinical Research:Academic medical centers require documentation-grade environmental logging for regulatory submission support.
- Veterinary Diagnostics:Emerging demand from specialty animal hospitals with transfusion capabilities.
Blood Banks anchor absolute volume, with Hematology Labs gaining share fastest through hospital consolidation in Japan and Germany.
End User:
Volume scale separates diagnostic laboratories running continuous platelet inventory from research institutes with intermittent batch processing needs.
- Diagnostic Laboratories:High-throughput transfusion services in integrated delivery networks are negotiating multi-site maintenance agreements separately from capital purchases. FDA post-market surveillance requirements are forcing systematic vigilance reporting for thermal excursion events.
- Research Institutes:Platelet biology and storage science studies require flexible chamber configurations for protocol variation. EU MDR conformity assessment burdens are delaying product launches and freezing R&D procurement budgets in France and the Netherlands.
- Biotechnology Companies:Cell therapy developers need platelet concentrates for culture media supplementation.
- Academic Centers:Training programs and translational research drive demand for entry-level semi-automated units.
Diagnostic Laboratories dominate current procurement volume, with Biotechnology Companies showing the steepest expansion trajectory as cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as CE marking costs under the EU MDR push production toward jurisdictions with streamlined medical device approval pathways. Manufacturers are relocating final assembly to markets where notified body backlogs are shorter and quality management certification timelines compress go-to-market schedules.
United States
Blood center consolidation across integrated delivery networks is driving centralized procurement of multi-chamber automated systems. The FDA enforces 21 CFR 606 platelet storage guidelines with tightened temperature and agitation compliance windows that accelerate replacement cycles for aging incubator inventories. Major hospital clusters in Boston and the Research Triangle are retiring single-chamber units in favor of platforms with independent environmental monitoring.
Germany
Hospital network mergers in North Rhine-Westphalia and Bavaria are compressing platelet storage into regional hubs requiring high-throughput automation. The EU MDR conformity assessment burden extends CE marking timelines for Class IIa medical devices, freezing some procurement budgets while favoring vendors with established notified body relationships. The Frankfurt-Rhine-Main medical technology corridor hosts concentrated service capacity for orbital agitation mechanism calibration.
Japan
Tokyo and Osaka hematology labs are expanding cold chain infrastructure to serve an aging transfusion-dependent population with rising platelet concentrate demand. METI industrial standards and PMDA medical device regulations govern local manufacturing and import approval pathways. The Kanto region's hospital networks are prioritizing automated systems with blood bank information system integration to reduce documentation burden.
India
WHO-influenced procurement specifications are opening demand for compact footprint incubators in tier-2 and tier-3 city blood banks with space-constrained hematology labs. CDSCO medical device regulations and BIS quality standards create a dual compliance framework for domestic and imported equipment. Maharashtra and Karnataka are seeing fastest network expansion as state health programs build transfusion capacity outside major metros.
United Kingdom
NHS blood and transplant services are unbundling after-sales service contracts from hardware purchases through centralized procurement frameworks. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit device regulations that diverge from EU MDR timelines in specific conformity assessment areas. London and Southeast England's consolidated hospital networks are benchmarking multi-site maintenance agreements independently of capital equipment costs.
Global Countertop Platelet Incubator Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent manufacturers extend service revenue streams beyond hardware transactions. The vendor base clusters around three strategic tiers: diversified laboratory equipment conglomerates with diagnostic workflow integration, specialized thermal management fabricators with regional regulatory alignment, and compact-footprint specialists targeting space-constrained installations. Consolidation pressures are intensifying as group purchasing organizations centralize multi-site procurement and unbundle maintenance agreements from capital sales. Technology licensing and backward integration into precision thermoelectric component sourcing represent the two dominant competitive moves.
Among North American laboratory equipment conglomerates, Thermo Fisher Scientific and Helmer Scientific exemplify contrasting archetypes: the former anchors its position through diagnostic laboratory relationships extending into adjacent blood management workflows, while the latter leverages installed base density to sustain service revenue streams alongside hardware sales. European specialists SARSTEDT AG & Co. KG and Labcold Ltd. occupy positions defined by regulatory geography—SARSTEDT exemplifies EU MDR alignment strategies, while Labcold represents compact-footprint specialization for constrained laboratory environments.
| Leading Market Players |
|---|
| Helmer Scientific |
| Thermo Fisher Scientific |
| Boekel Scientific |
| SARSTEDT AG & Co. KG |
| Labcold Ltd. |
| LMB Technologie GmbH |
| EMSAS Electrical Equipment Industry and Trading Inc. |
| Terumo Corporation |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap thermal equipment specialists in Germany and Japan anchor production capacity, creating pricing discipline through captive service networks and long-term blood bank relationships that resist commoditization pressure from distributor-heavy competitors.
Pricing Analysis
Distributor margins compress pricing power at the channel layer, with group purchasing organizations extracting 15-25 point spreads between manufacturer list and hospital net pricing. Three-tier pricing structure across premium automated, standard multi-chamber, and economy portable levels separates FDA-validated systems from CE-marked alternatives and basic single-chamber units. Cost compression in the portable tier intensifies because Indian and Southeast Asian procurement offices prioritize acquisition cost over total cost of ownership. Blood banks in integrated delivery networks show lowest price sensitivity, while tier-2 city hospitals in developing markets drive hardest bargain on per-chamber economics.
Supply Chain Analysis
Regional distribution centers in Chicago, Frankfurt, and Singapore orchestrate hub-and-spoke patterns that position finished incubators within 48-hour service response zones of major hospital clusters. Manufacturing concentrates in Germany, Japan, and the United States, with precision thermoelectric modules sourcing exclusively from South Korean and Taiwanese semiconductor fabs. Solid-state cooling components, orbital agitation motors, and pH sensor arrays create multi-point input dependencies. Single-source vulnerability in thermoelectric supply creates exposure to East Asian trade policy shifts. Distribution runs through manufacturer-direct field service organizations for premium tiers and medical equipment distributors for economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automation premium capture and service contract unbundling, with multi-chamber systems commanding pricing power through FDA compliance validation that legacy inventories cannot match.
For Market Incumbents: Extend service revenue streams through predictive maintenance telemetry and multi-site maintenance agreements that lock out third-party service competition. Incumbent manufacturers should deepen backward integration into precision thermoelectric component sourcing to reduce exposure to East Asian supply volatility. Lyophilized platelet alternatives and room-temperature storage formulations represent substitution threats that demand accelerated R&D in environmental monitoring differentiation. For New Entrants and Emerging Players: Begin with portable battery-powered configurations for India's tier-2 and tier-3 city blood banks, where space constraints and unreliable grid infrastructure create penetrable demand. Compact footprint specialization serves hematology labs in Tokyo and Osaka that incumbent conglomerates underserve with oversized multi-chamber platforms. Direct-to-hospital digital sales channels bypass GPO procurement friction for first-time buyers lacking established vendor relationships. For Investors and Strategic Acquirers: Laboratory equipment conglomerates are the most active acquirer in this space, seeking thermal management capabilities to extend diagnostic workflow portfolios. Long-term viability hinges on regulatory compliance automation rather than hardware commoditization, favoring targets with established FDA and EU MDR submission track records. Watch for lyophilized platelet clinical trial readouts as inflection indicators that could compress incumbent valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Investment | CE marking acceleration unlocks procurement budgets frozen in French and Dutch blood banks. |
| Backward Integration into Thermoelectrics | Captive solid-state cooling supply insulates margins from East Asian semiconductor fab volatility. |
| Portable Product Line Launch | Battery-powered units address underserved emergency response and rural clinic demand in India. |
| Hospital System Partnership | Direct relationships with integrated delivery networks in Boston and Research Triangle bypass distributor capture. |
| Software Companion Development | Blood bank information system integration reduces documentation burden driving Japanese procurement decisions. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Blood bank operations directors, biomedical equipment technicians, GPO contracts managers, and regulatory affairs leads at incubator manufacturers contributed structured interviews. Secondary sources include FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and WHO blood safety guideline repositories. Bottom-up unit demand modeling triangulates against top-down market sizing from manufacturer revenue disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, automation level, end-user category, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, blood center consolidation trajectories, and additive solution approval timelines. Forecast inputs incorporate FDA enforcement intensity assumptions for 21 CFR 606 compliance and EU MDR transition pace for CE marking backlogs.
Several conditions sit outside the modeled scope, including lyophilized platelet regulatory approvals and breakthrough cold-storage formulations that could eliminate room-temperature incubation demand. Forecasts reflect documented assumptions about hospital network consolidation velocity and biomedical technician labor availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
MRI Transport Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Operating Table Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Ultrasound Equipment Market