
 Medical Equipment Maintenance Market | 2026-2036
Medical Equipment Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Equipment Maintenance Market Intelligence
A transition from reliance on in-house biomedical engineering departments to outsourced contracts with specialized service providers is pivoting the market structure. This shift favors both original equipment manufacturers (OEMs) and independent service organizations (ISOs). Siemens Healthineers leverages its proprietary diagnostic imaging technology to offer premium service packages. GE HealthCare competes with a comprehensive service portfolio covering a wide range of hospital equipment. Meanwhile, facilities management specialists like Sodexo and Aramark provide integrated, multi-vendor maintenance solutions for entire healthcare systems.
Medical equipment maintenance involves the scheduled inspection, corrective repair, performance testing, and calibration of devices used in healthcare settings. The process ensures equipment operates within manufacturer-defined specifications and meets strict regulatory safety standards, which is critical for patient outcomes and diagnostic accuracy. Imaging devices, including MRI and CT scanners, represent a dominant equipment category due to their high acquisition cost and operational complexity. Within service types, predictive maintenance is gaining prominence over traditional preventive schedules, utilizing sensor data to forecast failures before they occur.
Regulatory frameworks are a primary force shaping service requirements and documentation standards. The US FDA enforces stringent quality system regulations for device servicing, while Europe's Medical Device Regulation (MDR) imposes rigorous post-market surveillance obligations on manufacturers and their service agents. In China, the NMPA mandates specific maintenance protocols for imported and domestic medical equipment. The central decision for healthcare providers is whether to partner with OEMs for proprietary expertise or engage ISOs for potential cost savings and multi-vendor operational flexibility.
Market Dynamics
The market's central dynamic is the tension between healthcare providers' need for cost containment, which favors independent service organizations, and the proprietary control OEMs exert through complex software and specialized parts for high-value imaging and therapeutic systems.
Growth Catalysts
- Stringent Regulations:Europe's Medical Device Regulation (MDR) imposes rigorous post-market surveillance and service documentation requirements, compelling healthcare facilities to formalize maintenance contracts with qualified providers to ensure compliance.
- Infrastructure Expansion:Massive investment in new hospital construction and healthcare facility upgrades, particularly in China, creates a continuously expanding installed base of medical equipment that requires a corresponding service and maintenance infrastructure.
- Technological Complexity:The increasing sophistication of diagnostic imaging equipment like MRI and CT scanners, which incorporate advanced software and digital components, surpasses the capabilities of many in-house biomedical teams, necessitating specialized external support.
Market Restraints
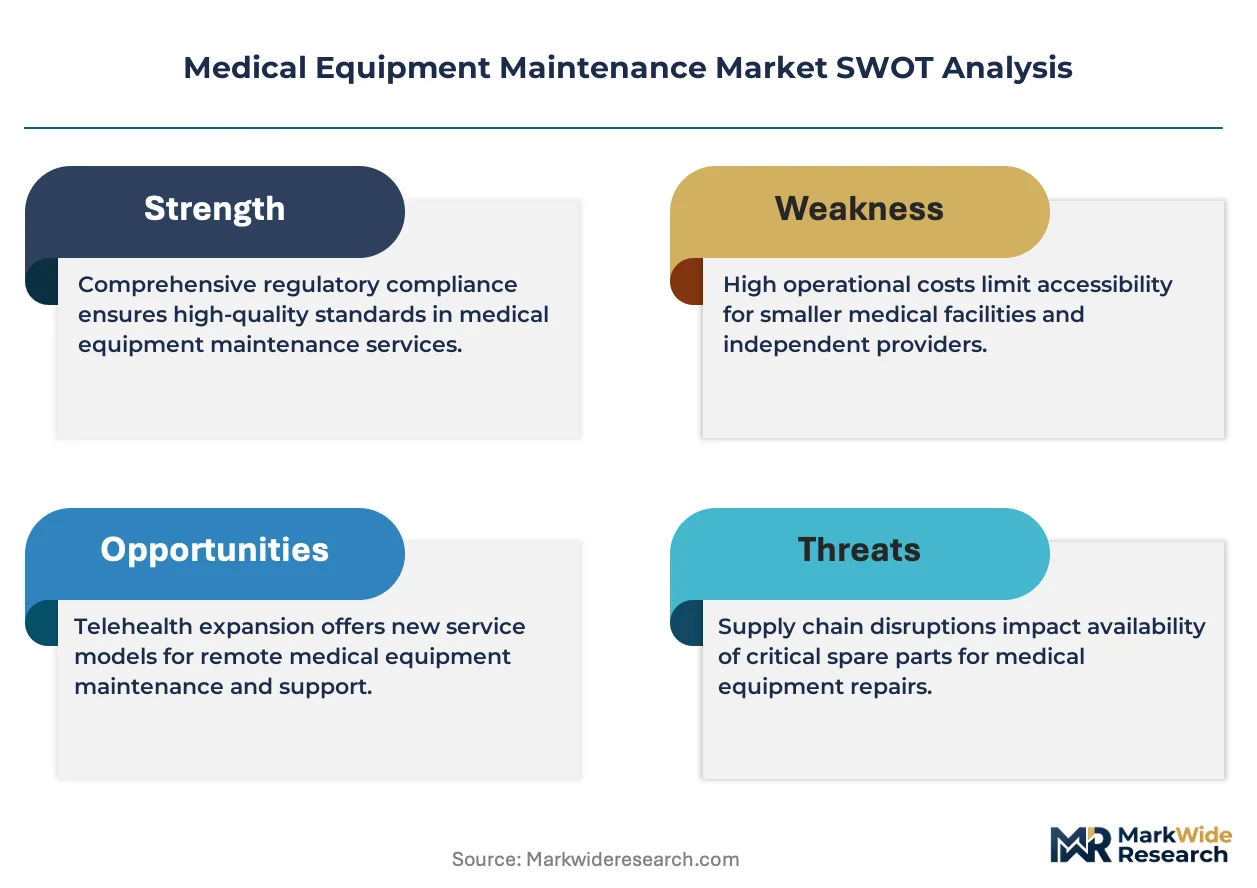
- Proprietary Service Models:Original equipment manufacturers often restrict access to service manuals, diagnostic software codes, and proprietary replacement parts, limiting the ability of hospitals and ISOs to perform comprehensive repairs.
- High Cost of Spares:The elevated cost of OEM-certified spare parts for critical systems, such as detectors for CT scanners or gradient coils for MRI machines, constitutes a significant portion of maintenance budgets and restrains service choices.
- Skilled Labor Scarcity:A persistent shortage of qualified and experienced biomedical equipment technicians (BMETs) capable of servicing a wide array of complex, multi-vendor devices creates a bottleneck for both in-house and third-party service providers.
Strategic Opportunities
- Integrated Service Platforms:An opportunity exists to develop software platforms that integrate equipment maintenance data with a hospital's broader enterprise asset management (EAM) and computerized maintenance management systems (CMMS) for a holistic operational view.
- Multi-Vendor Specialization:Service providers can focus on offering comprehensive, multi-vendor service contracts for entire clinical departments, such as radiology or surgery, simplifying procurement and accountability for hospital administrators.
- Emerging Market Penetration:Expanding service operations into regions like Southeast Asia and Latin America, where healthcare infrastructure is growing rapidly, offers significant first-mover advantages for establishing maintenance networks.
Industry Challenges
- Cybersecurity Vulnerabilities:Securing networked medical devices from cyber threats during remote maintenance and software patching is a critical operational challenge, demanding robust security protocols to protect patient data and device functionality.
- Legacy System Integration:Integrating modern predictive analytics and remote monitoring tools with older, non-networked medical equipment presents a significant technical and financial hurdle for healthcare facilities aiming to standardize maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Equipment Maintenance Market |
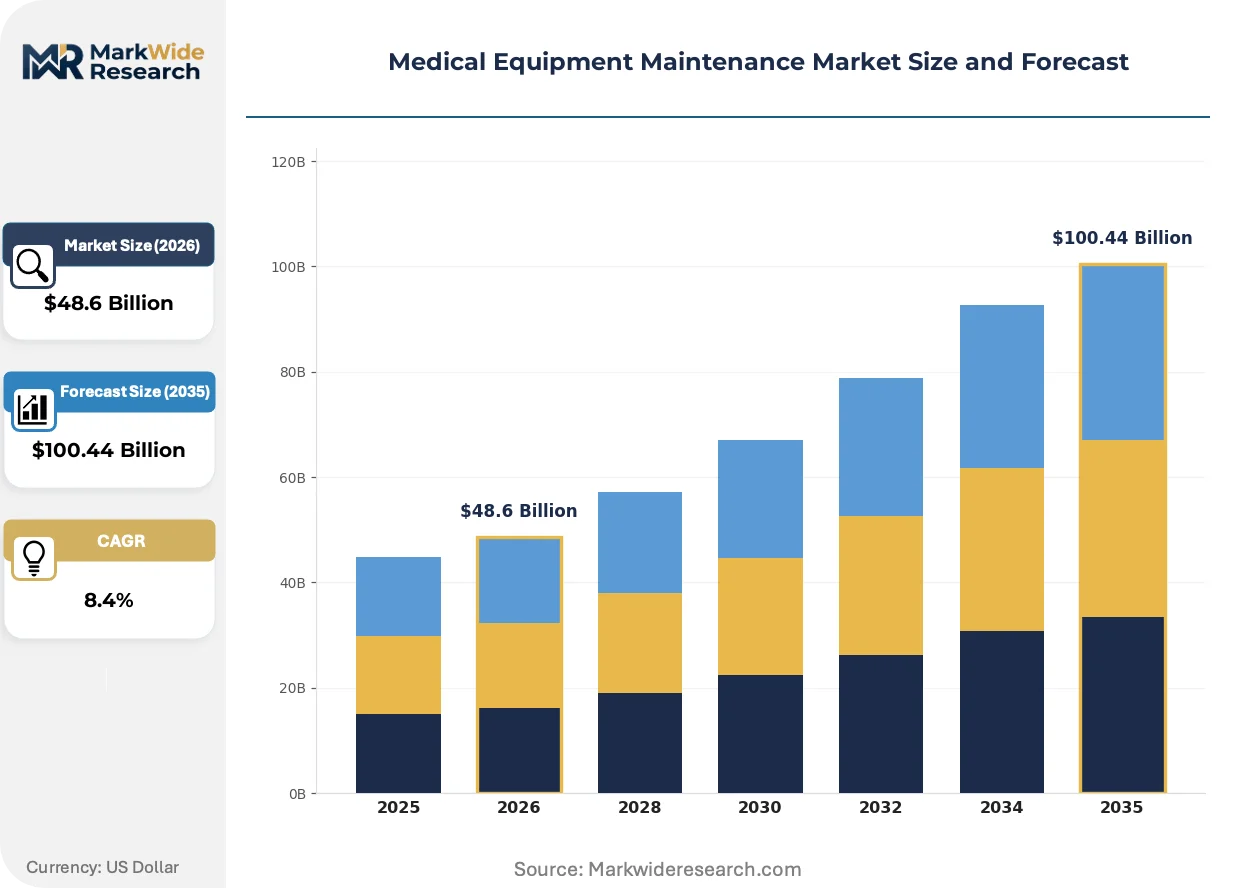
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Corrective Maintenance, Predictive Maintenance, Calibration, Installation Support Equipment Category: Imaging Devices, Surgical Instruments, Patient Monitoring Systems, Diagnostic Analyzers, Sterilization Equipment End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Laboratories, Specialty Clinics Contract Model: Time and Material, Fixed Price, Outcome-Based, Pay Per Use, Subscription-Based |
| Companies Covered | Sodexo, Medtronic, ISS Solutions, Siemens Healthineers, GE HealthCare, VectoRay Medical, Compass Group, Philips, Aramark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Equipment Maintenance Market Strategic Shifts & Innovations
The digitalization of service delivery is transforming medical equipment maintenance from a reactive, break-fix model into a proactive, data-driven discipline. This shift focuses on maximizing equipment uptime and integrating service data with clinical operations for improved asset performance management.
Predictive maintenance technologies utilize embedded IoT sensors to collect real-time operational data, such as temperature, vibration, and usage cycles, directly from medical devices. Large hospital networks and specialized diagnostic centers are the primary adopters, seeking to preempt equipment failures. This data-driven approach is converging with artificial intelligence algorithms to forecast component failure with high accuracy, enabling just-in-time repairs and minimizing unplanned downtime.
The US FDA's stringent enforcement of its Quality System Regulation (QSR) as it applies to the servicing of medical devices is a significant regulatory development. This compels all service entities, including independent organizations and hospital-based teams, to implement and maintain formal quality management systems with rigorous documentation, akin to manufacturing standards. The independent service organization (ISO) segment is most affected, now required to invest heavily in compliance infrastructure to validate their processes.
A notable behavioral shift is occurring in how healthcare systems procure maintenance services, moving from device-specific agreements to consolidated, multi-vendor service contracts. This change disrupts the traditional OEM-dominated service channel, creating an opening for ISOs and facilities management firms that can demonstrate the capability to service a diverse portfolio of equipment under a single agreement. This trend is most pronounced in large, multi-site hospital systems in the United States seeking greater operational efficiency and vendor consolidation.
Medical Equipment Maintenance Market Segmentation
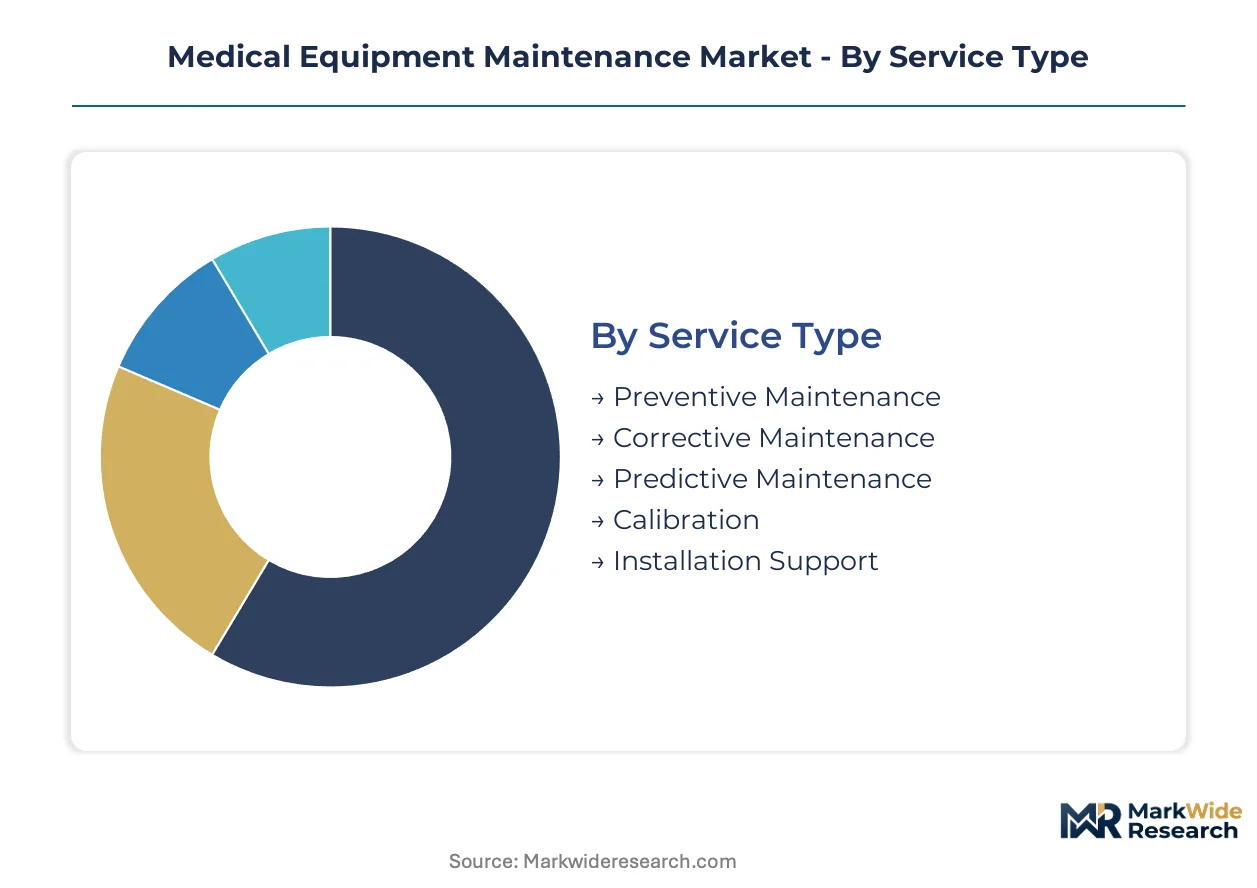
The medical equipment maintenance market is segmented to reflect the diverse operational needs and technological complexities within healthcare. Understanding these segments clarifies how providers procure services and how specialized organizations deliver them. This segmentation highlights the various approaches to ensuring equipment uptime and regulatory compliance.
Service Type:
Healthcare providers differentiate their service procurement based on operational philosophy and desired equipment reliability.
- Predictive Maintenance:This advanced service utilizes real-time sensor data and artificial intelligence to forecast equipment failures before they occur. Demand is concentrating in large hospital networks seeking to maximize uptime for critical diagnostic imaging devices.
- Preventive Maintenance:This traditional service involves scheduled inspections, cleaning, and component replacements to prevent breakdowns. Hospitals widely adopt this approach to comply with regulatory standards and extend the lifespan of essential therapeutic systems.
- Corrective Maintenance:This reactive service addresses equipment malfunctions or failures after they have occurred, restoring functionality.
- Calibration:This specialized service ensures medical devices operate within manufacturer-defined specifications for accuracy and precision.
- Installation Support:This service provides technical assistance and setup for new medical equipment, ensuring proper integration into clinical workflows.
Volume sits with Preventive Maintenance; growth tilts toward Predictive Maintenance.
Equipment Category:
The market differentiates equipment categories by their inherent operational complexity and acquisition cost.
- Imaging Devices:This category includes high-value systems like MRI, CT, and X-ray machines, requiring specialized expertise for calibration and repair. Demand is strong from diagnostic centers due to the critical role these devices play in patient diagnosis.
- Patient Monitoring Systems:These devices continuously track vital signs and physiological parameters, necessitating frequent checks for accuracy and software updates. Hospitals prioritize maintenance for these systems to ensure continuous patient safety across various departments.
- Surgical Instruments:This segment covers a wide array of tools used in operating rooms, requiring meticulous sterilization and functional checks.
- Diagnostic Analyzers:These laboratory instruments process patient samples, demanding precise calibration and regular performance verification.
- Sterilization Equipment:This equipment ensures the decontamination of medical tools, requiring consistent validation to meet infection control standards.
Imaging Devices command the largest service expenditure, while Patient Monitoring Systems exhibit consistent service demand.
End User:
End-user segmentation reflects the institutional scale and scope of medical services provided.
- Hospitals:These large facilities possess a vast and diverse installed base of medical equipment, driving comprehensive maintenance contracts. They often seek multi-vendor solutions to manage a wide range of diagnostic and therapeutic technologies effectively.
- Diagnostic Centers:Specializing in imaging and laboratory tests, these centers rely heavily on high-precision diagnostic equipment, demanding expert calibration and uptime. Their focus on specific modalities necessitates specialized service providers for optimal performance.
- Ambulatory Surgical Centers:These outpatient facilities require maintenance for surgical instruments and anesthesia machines to ensure patient safety during procedures.
- Laboratories:Medical laboratories depend on precise diagnostic analyzers and sample processing equipment for accurate test results.
- Specialty Clinics:These smaller, focused healthcare settings require tailored maintenance for their specific therapeutic or diagnostic devices.
Hospitals represent the dominant end-user segment, with Diagnostic Centers showing significant growth in specialized service needs.
Contract Model:
Healthcare providers select contract models based on their desired financial predictability and risk allocation.
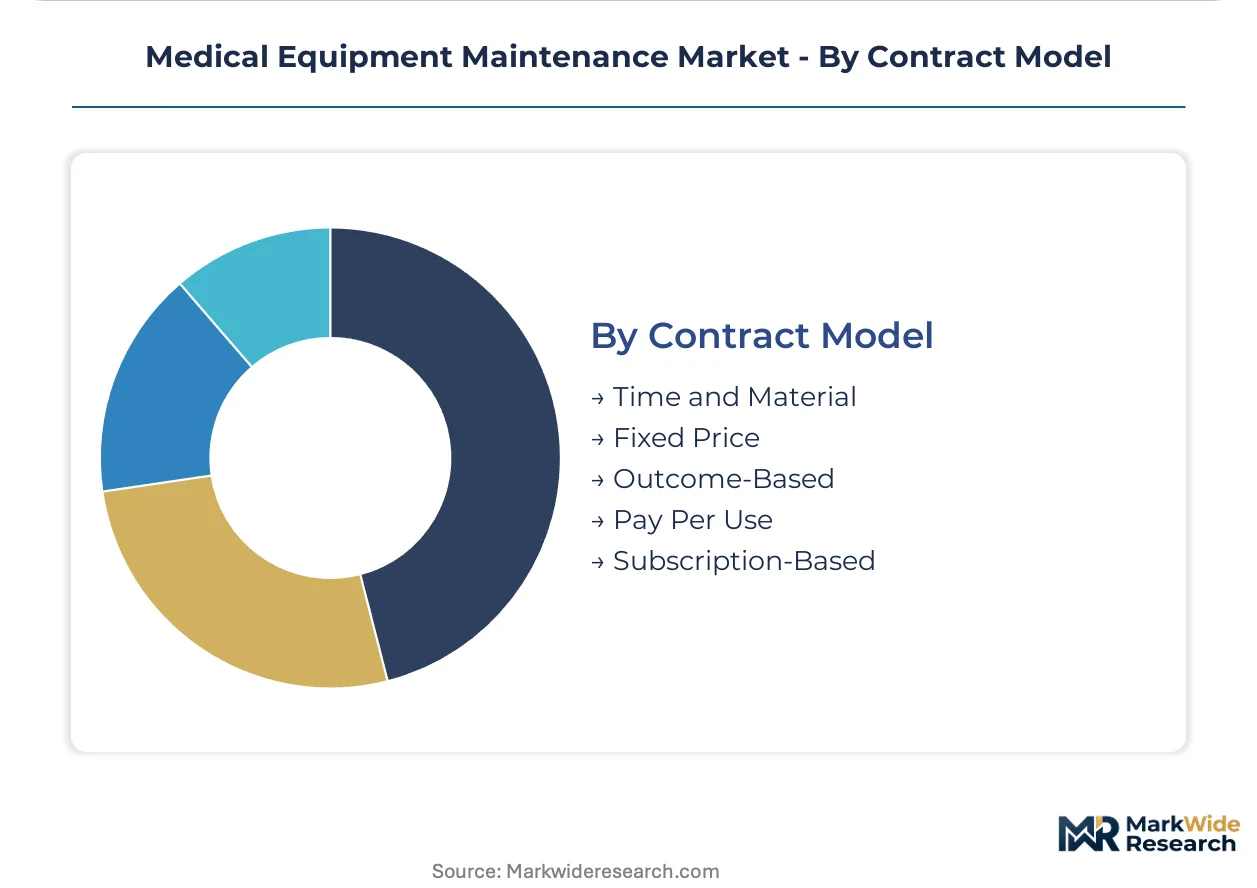
- Fixed Price:This model offers predictable costs for a defined scope of services over a set period, appealing to budget-conscious providers. Many large hospital systems favor fixed-price agreements for long-term budget stability and operational certainty.
- Outcome-Based:This innovative model links service payments to achieved performance metrics, such as equipment uptime or patient safety indicators. Early adopters include technologically advanced diagnostic centers aiming for maximum operational efficiency and clinical excellence.
- Time and Material:This flexible model charges for actual labor hours and parts used, suitable for ad-hoc repairs or less critical equipment.
- Pay Per Use:This model bills based on equipment utilization, reducing upfront costs and aligning expenses with operational activity.
- Subscription-Based:This model offers recurring access to services for a fixed fee, simplifying procurement and ongoing maintenance management.
Fixed Price contracts remain prevalent, while Outcome-Based models are gaining traction for high-value assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive investment in new healthcare facilities anchors significant demand for medical equipment maintenance services. This rapid infrastructure expansion across various regions necessitates robust support systems for a growing installed base of diagnostic and therapeutic devices. Regulatory frameworks across key global markets are also driving formalized maintenance practices.
China
Massive investment in new hospital construction and healthcare facility upgrades drives demand for maintenance services in China. The NMPA mandates specific maintenance protocols for both imported and domestically manufactured medical equipment, ensuring operational safety. Major urban centers like Shanghai and Beijing are witnessing concentrated growth in specialized service providers supporting advanced diagnostic imaging centers.
United States
The United States market sees high demand for maximizing uptime of critical diagnostic and therapeutic equipment in hospitals. The US FDA enforces stringent quality system regulations for device servicing, compelling formal maintenance contracts. Large hospital systems in regions like the Northeast Corridor and California require integrated, multi-vendor maintenance solutions for their extensive equipment portfolios.
Germany
Stringent regulatory frameworks like Europe's Medical Device Regulation (MDR) impose rigorous post-market surveillance obligations, increasing maintenance demand in Germany. Healthcare providers prioritize precision calibration and performance testing for highly complex medical devices. Industrial clusters in Bavaria and North Rhine-Westphalia house numerous specialized service organizations catering to advanced medical technology.
India
Infrastructure expansion and increasing healthcare accessibility are driving the need for medical equipment maintenance across India. The country's national health authorities are developing guidelines to ensure the operational integrity of medical devices. Major metropolitan areas such as Mumbai and Delhi are experiencing a rise in third-party service providers supporting both public and private healthcare facilities.
Japan
Japan's aging population and focus on high-quality patient care necessitate consistent maintenance for advanced medical devices. The PMDA oversees device safety and effectiveness, influencing maintenance standards and documentation requirements. Technology hubs in the Kanto region, particularly Tokyo, are centers for specialized service engineers supporting complex diagnostic imaging systems.
Medical Equipment Maintenance Market Key Industry Players
Global majors compete with regional champions across the spectrum of service delivery models for medical equipment maintenance. The market structure exhibits a tiered approach, with original equipment manufacturers dominating high-value proprietary systems while independent service organizations offer multi-vendor flexibility. Strategic archetypes include specialized OEMs, comprehensive facilities management providers, and agile independent service organizations. Competitive moves center on portfolio diversification to cover more equipment types and geographic expansion into emerging healthcare markets.
Within the OEM-dominated premium tier, Siemens Healthineers and GE HealthCare represent companies leveraging proprietary technology to offer comprehensive service packages. These firms maintain strong positions in servicing high-value imaging and therapeutic systems, often bundling maintenance with equipment sales. Facilities management specialists like Sodexo exemplify providers offering integrated, multi-vendor maintenance solutions across entire healthcare systems, focusing on operational efficiency for large hospital networks.
| Leading Market Players |
|---|
| Sodexo |
| Medtronic |
| ISS Solutions |
| Siemens Healthineers |
| GE HealthCare |
| VectoRay Medical |
| Compass Group |
| Philips |
| Aramark |
| Others |
Cost & Logistics Intelligence
Skilled biomedical equipment technician availability, concentrated in established healthcare hubs, directly influences labor-cost differentials and service pricing across regional markets. This disparity creates distinct pricing tiers between geographies with abundant versus scarce specialized talent.
Pricing Analysis
Warranty and service bundling often define initial contract negotiations, with OEMs leveraging proprietary technology to offer premium packages. Fixed Price contracts remain dominant, offering budget predictability for large hospital systems. Price differentiation stems from equipment complexity and the level of regulatory compliance required, such as FDA QSR adherence. Pricing pressure arises from healthcare providers' persistent need for cost containment, particularly impacting multi-vendor service providers. Hospitals, especially those managing diverse equipment portfolios, exhibit high price sensitivity.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke models characterize the delivery of medical equipment spare parts and consumables. Geographic supply concentration for specialized components largely centers on original equipment manufacturer production facilities in countries like Germany, the United States, and Japan. The supply chain relies heavily on proprietary diagnostic software codes and highly specialized replacement parts, including CT detectors. A structural risk is single-source vulnerability for these critical components, leading to elevated costs. Downstream distribution runs through OEM-controlled service networks and independent service organizations that source from various channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing a consolidation phase, driven by increasing regulatory burdens and the escalating complexity of medical technology, which marginalizes smaller, less specialized providers.
For Market Incumbents:Anticipate the continued shift towards multi-vendor service contracts by expanding capabilities beyond proprietary systems. Invest heavily in predictive maintenance platforms and AI-driven analytics to preempt equipment failures, offering superior uptime guarantees. Address the growing threat of cybersecurity vulnerabilities in networked devices by enhancing remote service security protocols. Leverage established relationships with large hospital networks to offer integrated facility management solutions, reinforcing market position against agile ISOs.
For New Entrants and Emerging Players:Price-point gaps exist between premium OEM services and basic in-house options, creating opportunities for value-focused entrants. Target multi-vendor service contracts for entire clinical departments, such as radiology or cardiology, in mid-sized hospitals. Focus on emerging markets like Southeast Asia and Latin America, where healthcare infrastructure is rapidly expanding. Develop robust compliance frameworks for regulations like Europe's MDR and the US FDA's QSR, positioning as a credible, cost-effective alternative to OEMs.
For Investors and Strategic Acquirers:Re-rating potential sits with independent service organizations demonstrating strong multi-vendor capabilities and robust regulatory compliance infrastructure, given the market's shift towards outsourced models. The long-term viability of medical equipment maintenance services is strong, anchored by an expanding installed base and increasing technological complexity. Acquisition targets should include firms specializing in integrated service platforms or those with established footprints in high-growth emerging markets. Watch for increased adoption of outcome-based contract models as a key inflection indicator for valuing service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Service Platforms | Streamlines maintenance workflows and provides holistic asset management for healthcare systems. |
| Acquire Multi-Vendor Service Providers | Expands service capabilities and reduces reliance on single OEM expertise for diverse equipment portfolios. |
| Expand into Emerging Healthcare Markets | Captures new demand from rapidly growing healthcare infrastructure in underserved regions. |
| Invest in Predictive Maintenance Technology | Enhances equipment uptime and reduces unplanned downtime through data-driven failure forecasting. |
| Strengthen Regulatory Compliance Infrastructure | Ensures adherence to stringent global standards like FDA QSR and Europe's MDR, building trust. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a broad market perspective. Primary research involved in-depth interviews with biomedical engineers, hospital purchasing committees, OEM service managers, and independent service organization technicians. This approach enabled bottom-up validation and top-down triangulation of market size and growth drivers.
Market granularity was modeled across service type, equipment category, end user, contract model, and key regional markets throughout the analysis window. Compound annual growth rates were derived from historical performance trends and projected future demand influenced by healthcare infrastructure expansion. Industry-specific forecast inputs included anticipated regulatory enforcement levels and the pace of medical device technological advancements.
Inputs from published reports, company disclosures, and expert interviews were available through the study window; gaps in granular regional spending data introduce uncertainty bands. Forecasts reflect a comprehensive set of assumptions regarding healthcare investment and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Water Bath Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Nuclear Medicine Equipment Market