
 Autoclaves Market | 2026-2036
Autoclaves Market Size, Share, and Industry Trends Forecast 2026-2036
Autoclaves Market Analysis
Pharmaceutical companies is rotating toward high-throughput sterilization systems as biologics manufacturing expands. STERIS plc leverages its installed base in North American hospital networks to sustain service revenue attachment. Getinge AB anchors European demand through centralized sterile supply department integrations. Tuttnauer competes on mid-capacity laboratory segments with programmable cycle architecture.
An autoclave is a pressure vessel that uses saturated steam at temperatures typically exceeding 121 degrees Celsius to achieve microbial inactivation through protein denaturation. The device maintains precise pressure-temperature-time parameters to ensure sterilization assurance levels for medical devices, laboratory media, and pharmaceutical components. Steam sterilizers dominate hospital procurement due to material compatibility breadth and established validation protocols, while plasma sterilizers capture growing share in temperature-sensitive endoscope reprocessing where oxidizing chemistry replaces thermal load. Automatic control systems command premium positioning through cycle documentation and remote monitoring capabilities that align with FDA 21 CFR Part 11 compliance requirements.
The FDA enforces Quality System Regulation for sterilization equipment design controls, while the EMA's Medical Device Regulation mandates clinical evidence for reusable device reprocessing systems. ISO 17665 provides the principal standard for steam sterilization validation that manufacturers must reference for CE marking and global market access. Stakeholders must monitor evolving EPA regulations on ethylene oxide emissions as environmental scrutiny intensifies for sterilization alternatives.
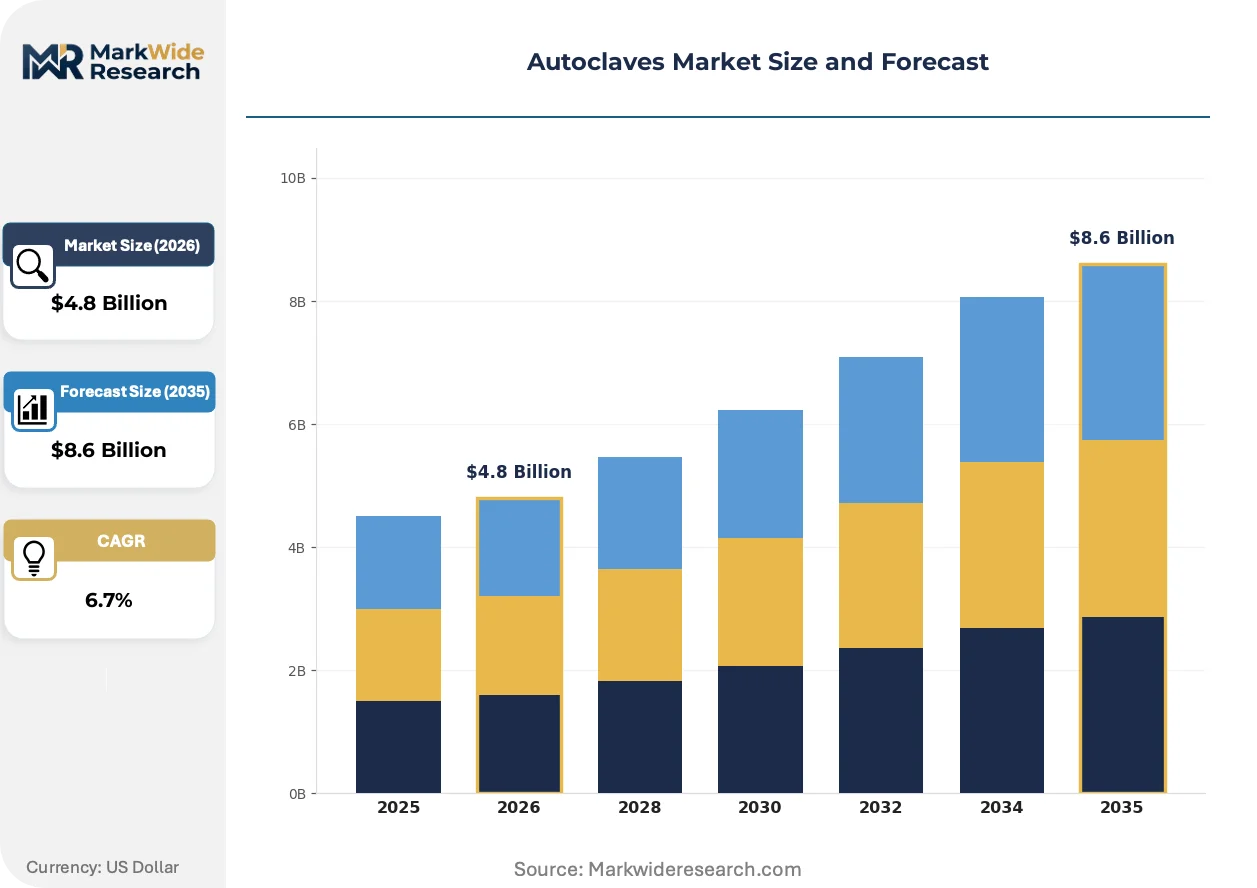
Market Dynamics
Biologics manufacturing expansion is forcing pharmaceutical sterilization infrastructure into high-throughput retooling cycles, compressing equipment replacement timelines from seven-year cycles to four-year refresh mandates. This demand pulse concentrates procurement authority within centralized sterile supply departments that now specify automated documentation systems as non-negotiable.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for sterilization validation documentation accelerate automatic control system upgrades across contract manufacturing organizations.
- Biologics manufacturing:Cell and gene therapy production lines require dedicated sterilization capacity with rapid cycle turnaround protocols.
- German medical device clusters:Precision engineering procurement from Baden-Württemberg and Bavaria sustains demand for validated steam sterilizers with integrated quality management interfaces.
Market Restraints
- Stainless steel input volatility:Grade 316L pressure vessel material costs fluctuate with nickel pricing, compressing margin predictability for equipment fabricators.
- Ethylene oxide emission scrutiny:EPA enforcement actions against sterilization facilities in Illinois and Georgia create regulatory overhang for alternative chemistry adoption.
- Plasma sterilizer throughput limits:Hydrogen peroxide vapor systems face cycle duration constraints that prevent full displacement of steam in high-volume hospital central sterile supply departments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's phased implementation of Schedule M compliance deadlines drives sterilization equipment procurement in Hyderabad and Ahmedabad bulk drug clusters.
- Remote monitoring convergence:Integration of IoT sensor arrays with cloud-based cycle documentation creates service revenue attachment models beyond equipment sale margins.
- EU MDR Article 17:Reprocessing validation requirements for reusable surgical instruments expand addressable market for washer-disinfector and sterilizer integrated systems.
Industry Challenges
- Validation engineering talent scarcity:ISO 17665 sterilization assurance expertise concentrates among aging specialists in Basel and Boston, constraining OEM service expansion.
- Legacy system integration friction:Hospital information systems with proprietary protocols resist seamless data exchange with modern autoclave documentation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoclaves Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Sterilizers, Dry Heat Sterilizers, Ethylene Oxide Sterilizers, Plasma Sterilizers End User: Hospitals, Laboratories, Dental Clinics, Pharmaceutical Companies Technology: Automatic Control, Manual Control, Computerized Control, Hybrid Systems Application: Medical Instruments, Laboratory Supplies, Pharmaceuticals, Cosmetics |
| Companies Covered | STERIS plc, Getinge AB, Tuttnauer, Belimed AG, MELAG Medizintechnik, Astell Scientific, Priorclave Ltd., Systec GmbH, Shinva Medical Instrument Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoclaves Market Emerging Trajectories
Sterilization technology trajectories are diverging between thermal and low-temperature modalities as material science advances expand the range of devices requiring reprocessing without thermal degradation.
Steam sterilizer architecture is bifurcating between compact benchtop units for point-of-care dental and veterinary clinics and high-capacity pass-through systems for pharmaceutical manufacturing suites. Biopharma contract manufacturers in Massachusetts and North Carolina are specifying the latter with redundant steam supply and automated load tracking. This equipment tiering is compressing mid-capacity hospital sterilizer demand while elevating premium positioning for integrated quality management systems.
REACH restrictions on peracetic acid precursors are forcing European sterilization facilities to evaluate hydrogen peroxide plasma alternatives for flexible endoscope reprocessing. The ECHA regulatory trajectory favors oxidizing chemistry with lower environmental persistence profiles. German and Dutch hospital procurement consortia are now mandating life-cycle emission assessments alongside sterility assurance validation in equipment tenders.
Consolidated buying through regional hospital networks is displacing individual facility procurement autonomy in the United States. Integrated delivery networks in Texas and Florida now centralize sterilization equipment specification through corporate supply chain committees. This concentration elevates vendor qualification barriers while compressing pricing negotiation leverage for standalone community hospitals.
Autoclaves Market Segmentation
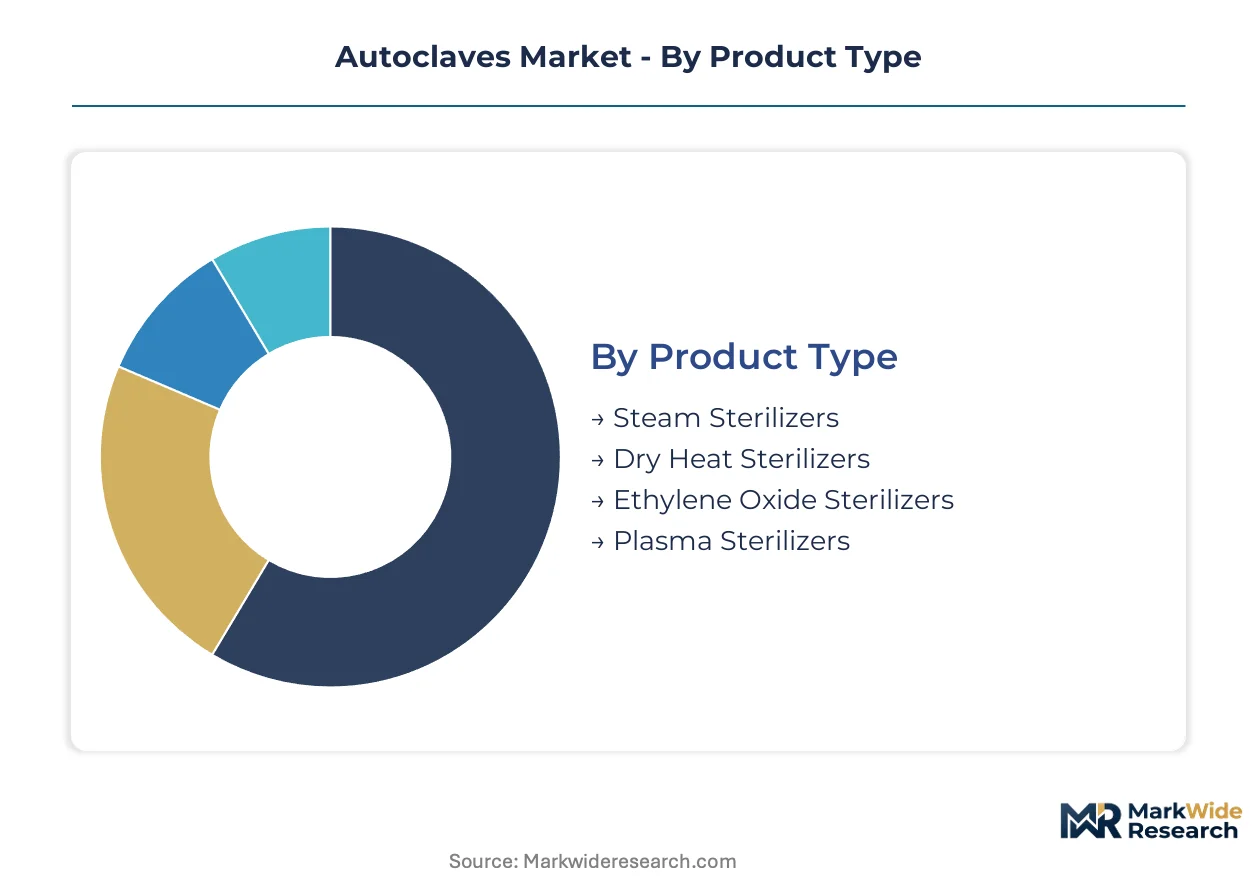
Autoclave procurement patterns diverge sharply across sterilization modalities and end-use environments. Equipment specifications must align with material compatibility constraints, regulatory validation requirements, and throughput demands that vary by clinical versus industrial settings.
Product Type:
Steam sterilizers dominate domestic hospital procurement across Germany and the United States, while plasma and ethylene oxide systems serve export markets with stringent low-temperature requirements.
- Steam Sterilizers:Saturated steam systems operating above 121°C deliver protein denaturation for heat-stable medical devices and surgical instruments. German hospital networks in Baden-Württemberg specify these with integrated quality management interfaces for centralized sterile supply departments.
- Plasma Sterilizers:Hydrogen peroxide vapor systems enable oxidizing chemistry sterilization for temperature-sensitive endoscopes and flexible instruments. Massachusetts biopharma contract manufacturers deploy these alongside steam units for material-differentiated processing workflows.
- Dry Heat Sterilizers:Convection and radiant heat systems address moisture-sensitive powders and oils in pharmaceutical manufacturing.
- Ethylene Oxide Sterilizers:Alkylating gas chemistry serves heat- and moisture-sensitive devices, though EPA enforcement in Illinois and Georgia constrains new capacity deployment.
Steam sterilizers hold the largest share; momentum sits with plasma sterilizers.
End User:
Procurement authority concentrates in centralized supply chain committees for hospital networks, while pharmaceutical manufacturers specify dedicated biologics capacity.
- Hospitals:Central sterile supply departments in integrated delivery networks command high-throughput pass-through systems with automated load tracking and remote monitoring capabilities for FDA 21 CFR Part 11 compliance.
- Pharmaceutical Companies:Cell and gene therapy production lines in North Carolina and Massachusetts require rapid cycle turnaround protocols with redundant steam supply and validated documentation systems.
- Laboratories:Research and quality control facilities specify mid-capacity programmable cycle architecture for media and glassware sterilization.
- Dental Clinics:Compact benchtop units serve point-of-care instrument reprocessing with simplified operational interfaces.
Hospitals command the dominant procurement volume; pharmaceutical companies are expanding capacity fastest.
Technology:
Control system sophistication directly determines pricing tiers and service revenue attachment potential across customer segments.
- Automatic Control:Microprocessor-managed cycle parameters with electronic records and remote monitoring command premium positioning. Contract manufacturing organizations upgrade these systems to satisfy FDA electronic documentation mandates.
- Computerized Control:Network-integrated architectures with cloud-based cycle documentation enable predictive maintenance and service revenue models beyond equipment sale margins.
- Manual Control:Basic timer and pressure gauge interfaces persist in cost-constrained veterinary and dental settings.
- Hybrid Systems:Configurable automation levels bridge manual and fully automatic operation for mid-tier hospital budgets.
Automatic control systems anchor current revenue; computerized control platforms are gaining share fastest.
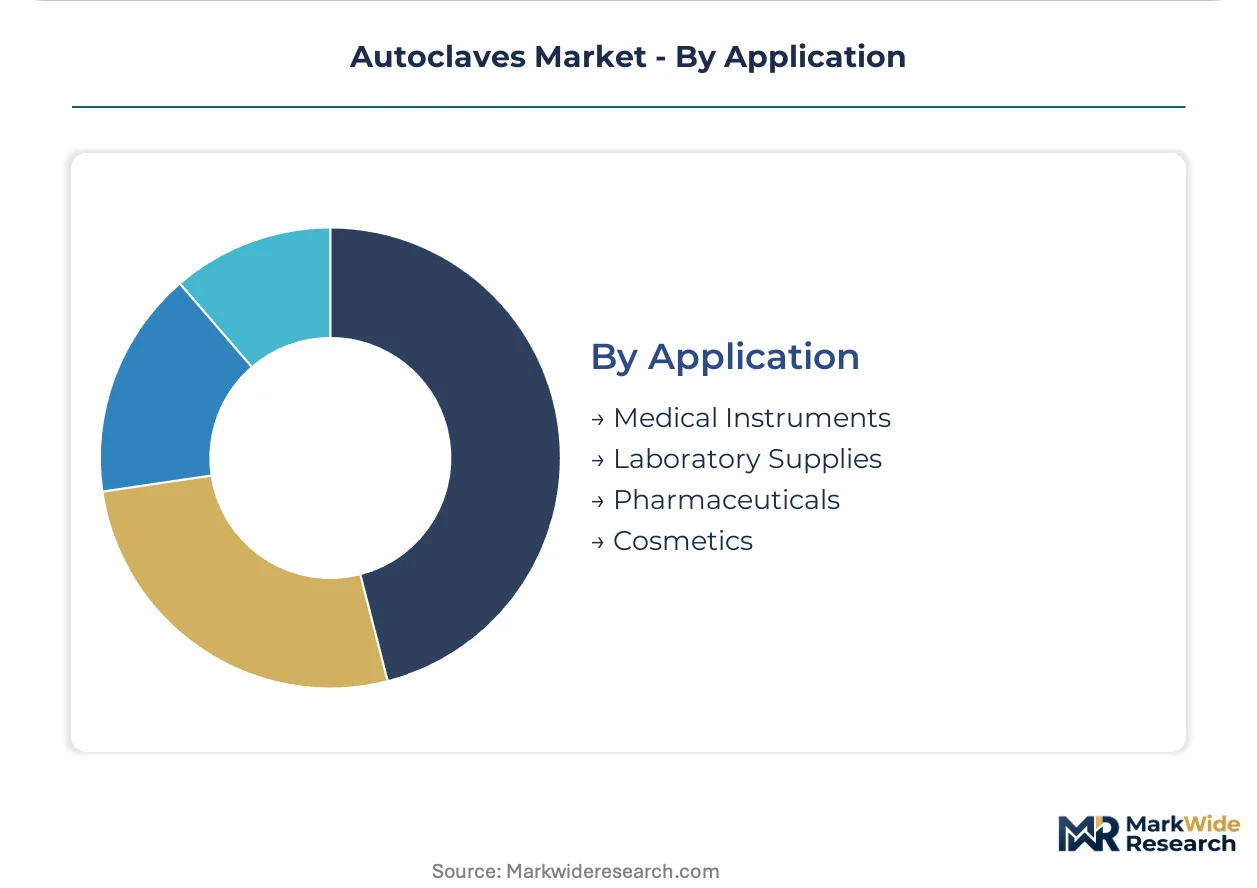
Application:
Material compatibility requirements and sterility assurance levels dictate equipment selection across clinical and industrial processing environments.
- Medical Instruments:Reusable surgical devices and endoscopes demand validated sterilization assurance with ISO 17665-compliant documentation for EU MDR Article 17 reprocessing requirements.
- Pharmaceuticals:Parenteral drug components and biologics containers require dedicated sterilization capacity with rapid turnaround to minimize production line downtime.
- Laboratory Supplies:Culture media, pipettes, and glassware processing prioritizes cycle flexibility over throughput speed in research settings.
- Cosmetics:Packaging materials and formulation equipment sterilization follows pharmaceutical-grade protocols in premium product manufacturing.
Medical instruments represent the largest application segment; pharmaceuticals are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in European sterilization equipment logistics, connecting Baden-Württemberg engineering clusters to Atlantic and Baltic markets.
United States
Massachusetts and North Carolina biopharma contract manufacturers drive high-throughput pass-through system procurement for cell therapy production. FDA 21 CFR Part 11 electronic records mandates accelerate automatic control upgrades across contract manufacturing organizations. Greater Boston's Route 128 corridor concentrates validation engineering expertise for sterilization assurance protocols.
Germany
Baden-Württemberg and Bavaria medical device clusters sustain precision engineering demand for validated steam sterilizers with integrated quality interfaces. EU MDR Article 17 reprocessing requirements expand addressable market for washer-disinfector integrated systems. Stuttgart's industrial automation ecosystem supplies sensor arrays for remote monitoring convergence.
India
Hyderabad and Ahmedabad bulk drug clusters scale sterilization capacity to meet CDSCO Schedule M compliance deadlines. The country's national pharmaceutical regulator enforces phased good manufacturing practice upgrades through 2025. Telangana's Genome Valley biologics parks specify dedicated rapid-cycle sterilization infrastructure.
China
Yangtze River Delta pharmaceutical manufacturers retrofit sterilization lines for NMPA good manufacturing practice alignment with international standards. The national medical products administration tightens validation documentation requirements for sterile processing equipment. Shanghai's Zhangjiang Hi-Tech Park anchors biologics manufacturing expansion driving equipment procurement.
Japan
Kanto region medical device reprocessing facilities upgrade hydrogen peroxide plasma capacity for temperature-sensitive endoscope volumes. PMDA quality system regulation mandates design control documentation for sterilization equipment imports. Tokyo's central sterile supply departments consolidate procurement through metropolitan hospital network alliances.
Autoclaves Market Vendor Landscape
Listed leaders compete with private specialists across capitalization tiers, creating a bifurcated structure where publicly traded entities anchor service revenue models while family-held fabricators dominate mid-capacity laboratory segments. The vendor base concentrates among three strategic archetypes: integrated sterile processing platform providers, precision engineering specialists with regional hospital network relationships, and programmable cycle architects serving research settings. Competitive moves center on backward integration into stainless steel pressure vessel fabrication and predictive maintenance service attachments via IoT sensor deployment.
Within the integrated platform tier, STERIS plc and Getinge AB exemplify scale-driven positioning through installed base leverage and centralized sterile supply department relationships. Tuttnauer occupies a position among mid-capacity specialists with programmable architecture competencies. Shinva Medical Instrument Co., Ltd. represents geography-differentiated fabrication capacity serving domestic pharmaceutical manufacturing expansion.
| Leading Market Players |
|---|
| STERIS plc |
| Getinge AB |
| Tuttnauer |
| Belimed AG |
| MELAG Medizintechnik |
| Astell Scientific |
| Priorclave Ltd. |
| Systec GmbH |
| Shinva Medical Instrument Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 11 compliance requirements gate both vendor qualification and price differentiation simultaneously, as automatic control systems with electronic records capabilities command premium positioning over manual alternatives while contract manufacturing organizations absorb upgrade costs to maintain audit readiness.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement through integrated delivery network contracts, with three-tier pricing separating computerized control platforms from automatic systems and manual units. Price differentiation rests on certification grade and after-sales service bundling, particularly ISO 17665 validation support and remote monitoring subscriptions. Cost compression in mid-capacity segments is intensifying because stainless steel input volatility compresses margin predictability for equipment fabricators. Dental clinics and veterinary settings exhibit highest price sensitivity, while pharmaceutical manufacturers show least sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Inventory lead times for Grade 316L pressure vessels extend when nickel pricing volatility disrupts German and Chinese stainless steel mill schedules. Geographic supply concentration centers on Germany, China, and India for pressure vessel fabrication, with sensor arrays and control systems drawing from Japan and the United States. Raw material dependencies hinge on nickel ore sourcing, precision machining capacity, and microprocessor supply from Taiwan. Single-source vulnerability in specialized validation engineering talent constrains OEM service expansion. Distribution runs through regional hospital procurement consortia and pharmaceutical manufacturing clusters rather than fragmented dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autoclave market fragmentation creates opportunity as biologics manufacturing expansion splinters demand between high-throughput pharmaceutical systems and point-of-care compact units, opening niches for specialized entrants.
For Market Incumbents: Compound installed base leverage through predictive maintenance service attachments and backward integration into stainless steel pressure vessel fabrication. Plasma sterilizer throughput limits threaten steam sterilizer displacement timelines, elevating the priority of rapid-cycle R&D investment. Capacity addition in Indian pharmaceutical manufacturing clusters captures CDSCO compliance-driven demand pulses. For New Entrants and Emerging Players: Differentiate on programmable cycle architecture for mid-capacity laboratory segments where Tuttnauer maintains incumbent position. The most penetrable white space sits in Indian bulk drug clusters facing Schedule M compliance deadlines. A go-to-market angle targeting CDSCO validation documentation services alongside equipment sales bypasses established European vendor relationships. For Investors and Strategic Acquirers: EU MDR Article 17 reprocessing validation requirements reshape the acquisition landscape toward washer-disinfector and sterilizer integrated system specialists. Long-term viability over the next decade favors vendors with service revenue attachment models beyond equipment sale margins. The acquisition target archetype combines IoT sensor deployment capabilities with existing hospital network relationships. The signal to watch is EPA enforcement trajectory on ethylene oxide emissions as regulatory overhang intensifies for alternative chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Vessel Fabrication | Captive supply of Grade 316L components insulates margin from nickel pricing volatility. |
| IoT Sensor Array Deployment | Cloud-based cycle documentation creates recurring service revenue beyond equipment sale margins. |
| CDSCO Validation Documentation Services | Schedule M compliance deadlines in Hyderabad and Ahmedabad drive attach-rate expansion. |
| Plasma Sterilizer Rapid-Cycle R&D | Hydrogen peroxide vapor throughput improvements address central sterile supply department constraints. |
| EU MDR Article 17 Integrated System Development | Washer-disinfector and sterilizer combinations capture reusable surgical instrument reprocessing mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, sterilization validation specialists, and pharmaceutical manufacturing executives and refined through secondary validation against FDA 510(k) filings, EMA medical device registration databases, ISO standard revision records, and hospital procurement contract disclosures. Bottom-up equipment shipment estimates triangulated against top-down pharmaceutical manufacturing capacity expansion data.
Variance decomposition across sterilization modality, end-user environment, control system sophistication, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated biologics manufacturing pipeline data, hospital capital expenditure surveys, and stainless steel pricing indices.
Material uncertainties — EPA enforcement actions on ethylene oxide, nickel price volatility, and validation engineering talent availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory trajectory and input cost stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Water Bath Market
Medical Equipment
Electric Bed Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market