
 Health Intelligent Virtual Assistant Market | 2026-2036
Health Intelligent Virtual Assistant Market Size, Share, and Industry Trends Forecast 2026-2036
Health Intelligent Virtual Assistant Market Analysis
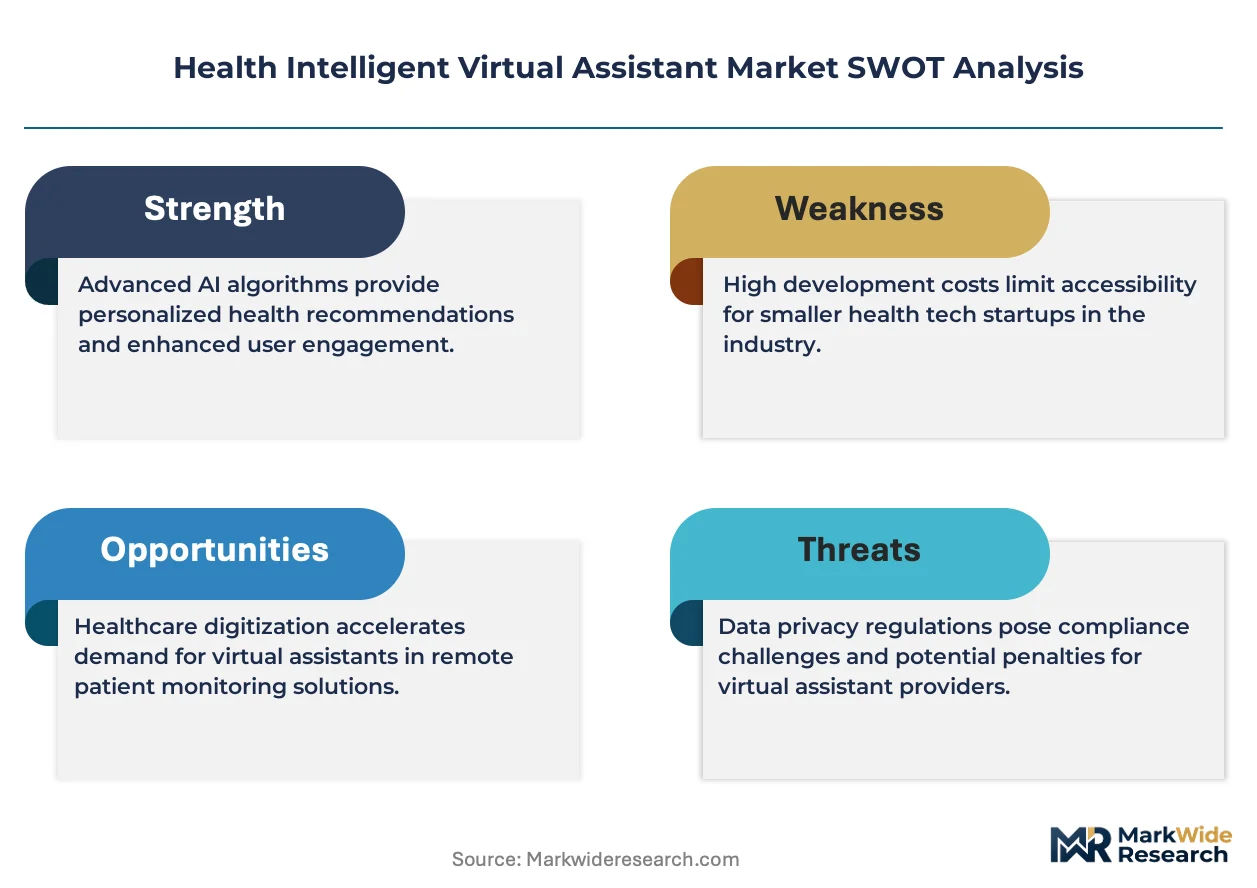
The health intelligent virtual assistant market is consolidating around two distinct performance tiers. Premium offerings integrate with electronic health record systems and support clinical decision workflows, while commodity chatbots handle basic scheduling queries. Microsoft leverages its Azure cloud infrastructure to anchor enterprise deployments across hospital networks. Nuance Communications specializes in voice recognition accuracy for clinical documentation, sustaining differentiation through deep EHR partnerships.
A health intelligent virtual assistant constitutes software that processes natural language inputs through NLP engines and machine learning models to deliver automated health-related interactions, typically operating with response latency under two seconds for real-time patient engagement. These systems serve to reduce administrative burden on clinical staff while extending care access beyond traditional operating hours. Chatbot deployments currently dominate volume as healthcare organizations pilot low-risk automation for appointment scheduling and symptom triage, though voice assistant installations accelerate fastest among provider organizations seeking hands-free clinical workflow integration. AI algorithms represent the concentrated margin pool where vendors differentiate through proprietary training data and regulatory validation depth.
FDA oversight of AI-enabled medical devices directly shapes product development timelines and commercialization pathways for diagnostic-adjacent virtual assistants. HIPAA compliance requirements govern data architecture decisions, pushing vendors toward cloud computing deployments with business associate agreements from major infrastructure providers. Stakeholders must monitor evolving FDA guidance on adaptive algorithms to determine whether continuous learning systems require incremental premarket submissions or qualify for streamlined review pathways.
Market Dynamics
Hospital systems are consolidating vendor relationships around conversational AI platforms that embed directly into clinical workflows, compressing procurement cycles from multi-year evaluations to accelerated pilot-to-production timelines.
Growth Catalysts
- Epic Systems integration:Native EHR connectivity accelerates enterprise deployment across United States hospital networks, reducing implementation friction.
- FDA guidance clarity:Streamlined premarket pathways for AI-enabled medical devices enable faster commercialization of diagnostic-adjacent virtual assistants.
- Cloud infrastructure maturation:Business associate agreements from major providers resolve HIPAA compliance architecture decisions, lowering vendor entry barriers.
Market Restraints
- Specialized NLP training data scarcity:Proprietary clinical conversation datasets remain concentrated among incumbent vendors, constraining new entrant model accuracy.
- Regulatory fragmentation:Divergent validation requirements between FDA premarket submissions and EU MDR conformity assessments extend multi-territory launch timelines.
- Voice recognition latency thresholds:Sub-two-second response requirements demand expensive edge computing deployments, elevating total cost of ownership.
Strategic Opportunities
- Rural health network penetration:Federally qualified health centers in underserved United States counties present automation demand with limited incumbent saturation.
- Multimodal interaction convergence:Integration of voice, text, and visual symptom capture creates differentiation beyond single-modality competitors.
- CMS reimbursement tailwinds:Remote patient monitoring billing codes incentivize virtual assistant deployment for chronic care management workflows.
Industry Challenges
- Clinical workflow integration complexity:Health systems require extensive customization to align automated triage logic with existing physician decision protocols.
- Adaptive algorithm governance:Continuous learning systems trigger regulatory uncertainty regarding incremental premarket submission obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Intelligent Virtual Assistant Market |
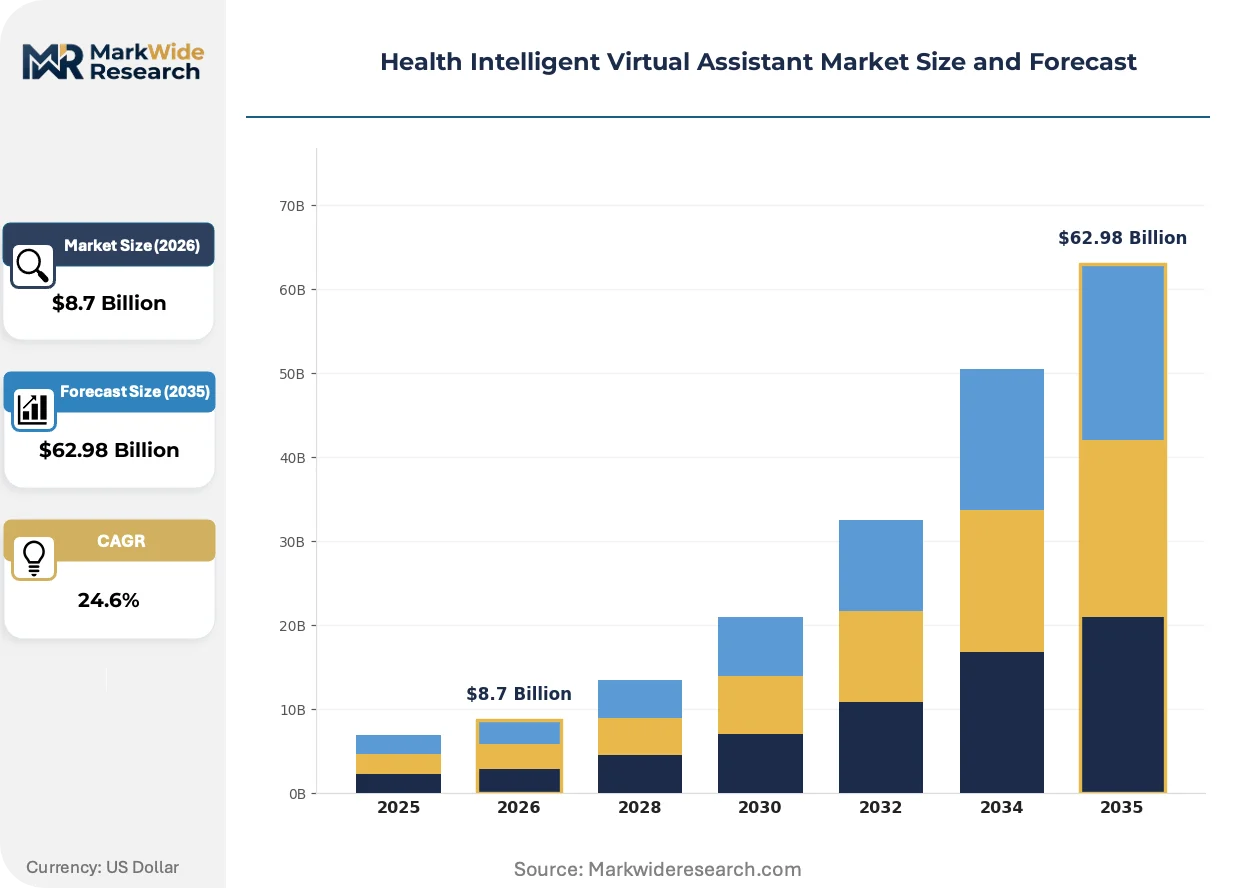
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbot, Voice Assistant, Mobile App, Web Portal Application: Appointment Scheduling, Medication Management, Health Tracking, Symptom Checker End User: Patients, Healthcare Providers, Employers, Insurers Technology: Natural Language Processing, Machine Learning, Cloud Computing, AI Algorithms |
| Companies Covered | Microsoft, Nuance Communications, CSS Corp, eGain Corporation, Kognito, MEDRESPOND, Next IT Solutions, True Image Interactive, CodeBaby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Intelligent Virtual Assistant Market Emerging Trajectories
Natural language processing architectures are shifting from retrieval-based to generative models, enabling more contextually fluid patient conversations while introducing new validation burdens for clinical safety.
Large language model fine-tuning for clinical domains is converging with retrieval-augmented generation techniques to ground outputs in verified medical knowledge bases. Academic medical centers in the United States are piloting these hybrid architectures for complex symptom assessment. This convergence is compressing the gap between consumer-grade conversational fluency and regulatory-demanded clinical accuracy.
The EU AI Act risk classification framework places diagnostic-adjacent virtual assistants in high-risk categories, mandating conformity assessments and post-market monitoring systems. European health technology vendors are restructuring quality management systems to accommodate algorithm change control protocols. Germany and France are emerging as early implementation testbeds where notified body capacity constraints are creating certification bottlenecks.
Health system procurement committees are consolidating vendor evaluations around integrated platform capabilities rather than point solutions. Specialty clinic networks are displacing standalone chatbot contracts with enterprise agreements covering voice, text, and ambient documentation. This pattern is most visible in United States integrated delivery networks where CIOs prioritize EHR-native deployment over best-of-breed fragmentation.
Health Intelligent Virtual Assistant Market Segmentation
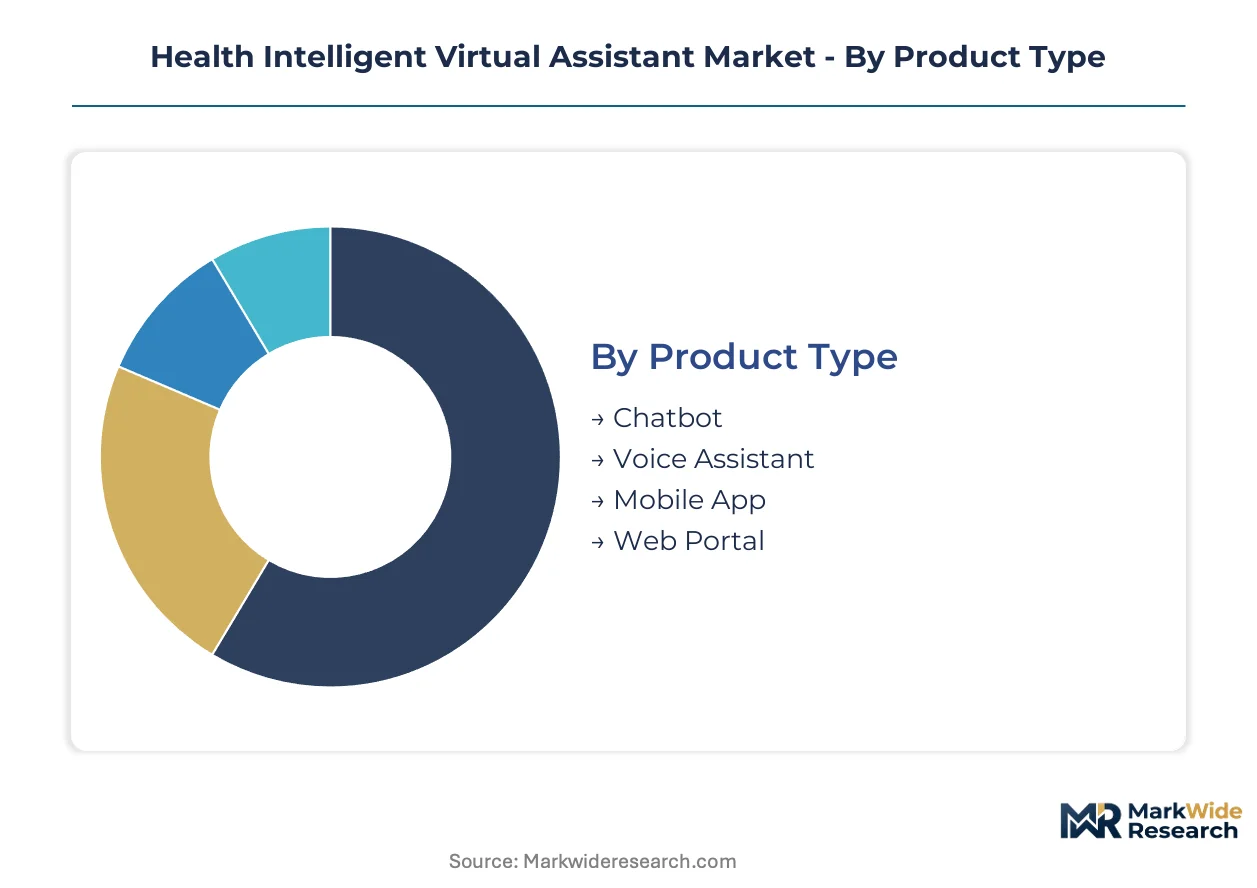
Health intelligent virtual assistants fragment across four distinct dimensions that determine deployment complexity and revenue capture. Product type and application segments reveal the sharpest divergence between high-volume commodity deployments and premium clinical workflow integrations. Technology segmentation exposes where proprietary differentiation concentrates versus standardized infrastructure layers.
Product Type:
Chatbot deployments dominate transaction volume while voice assistant installations command premium pricing through hands-free clinical integration.
- Chatbot:Text-based conversational interfaces deploy through web browsers and messaging platforms with minimal infrastructure requirements. Hospital systems in the United States pilot these for low-risk triage automation, though CMS reimbursement limitations constrain revenue per deployment.
- Voice Assistant:Speech recognition systems process natural language inputs with sub-two-second latency thresholds for real-time clinical documentation. Academic medical centers in Boston and Stanford drive demand for ambient listening capabilities that reduce physician keyboard burden.
- Mobile App:Native smartphone applications extend care access beyond facility walls through push notification engagement.
- Web Portal:Browser-based interfaces integrate with patient-facing EHR portals for appointment self-scheduling.
Today's leader: Chatbot. Tomorrow's challenger: Voice Assistant.
Application:
Symptom assessment commands development investment while medication adherence solutions attract chronic care management billing codes.
- Symptom Checker:Algorithmic triage engines route patient concerns to appropriate care settings based on severity scoring. FDA premarket submission requirements for diagnostic-adjacent functionality extend commercialization timelines.
- Medication Management:Dose reminder systems and drug interaction alerts support polypharmacy patients. Federally qualified health centers in rural United States counties deploy these for CMS-reimbursable chronic care management workflows.
- Appointment Scheduling:Calendar integration and waitlist optimization reduce front-desk staffing requirements.
- Health Tracking:Biometric data aggregation from wearables enables longitudinal wellness monitoring.
Symptom Checker captures current R&D investment. Medication Management holds the steepest expansion trajectory through reimbursement tailwinds.
End User:
Provider organizations concentrate procurement authority while employer-sponsored wellness programs represent underpenetrated demand.
- Healthcare Providers:Hospital systems and physician practices automate clinical documentation and patient communication workflows. Epic Systems integration requirements shape vendor selection criteria across United States integrated delivery networks.
- Patients:Direct-to-consumer deployments bypass institutional procurement cycles but face retention challenges post-onboarding.
- Employers:Self-insured corporations subsidize virtual assistant access to reduce plan utilization costs.
- Insurers:Payers deploy for prior authorization automation and member engagement cost reduction.
Healthcare Providers anchor enterprise revenue. Employers offer the largest addressable expansion surface.
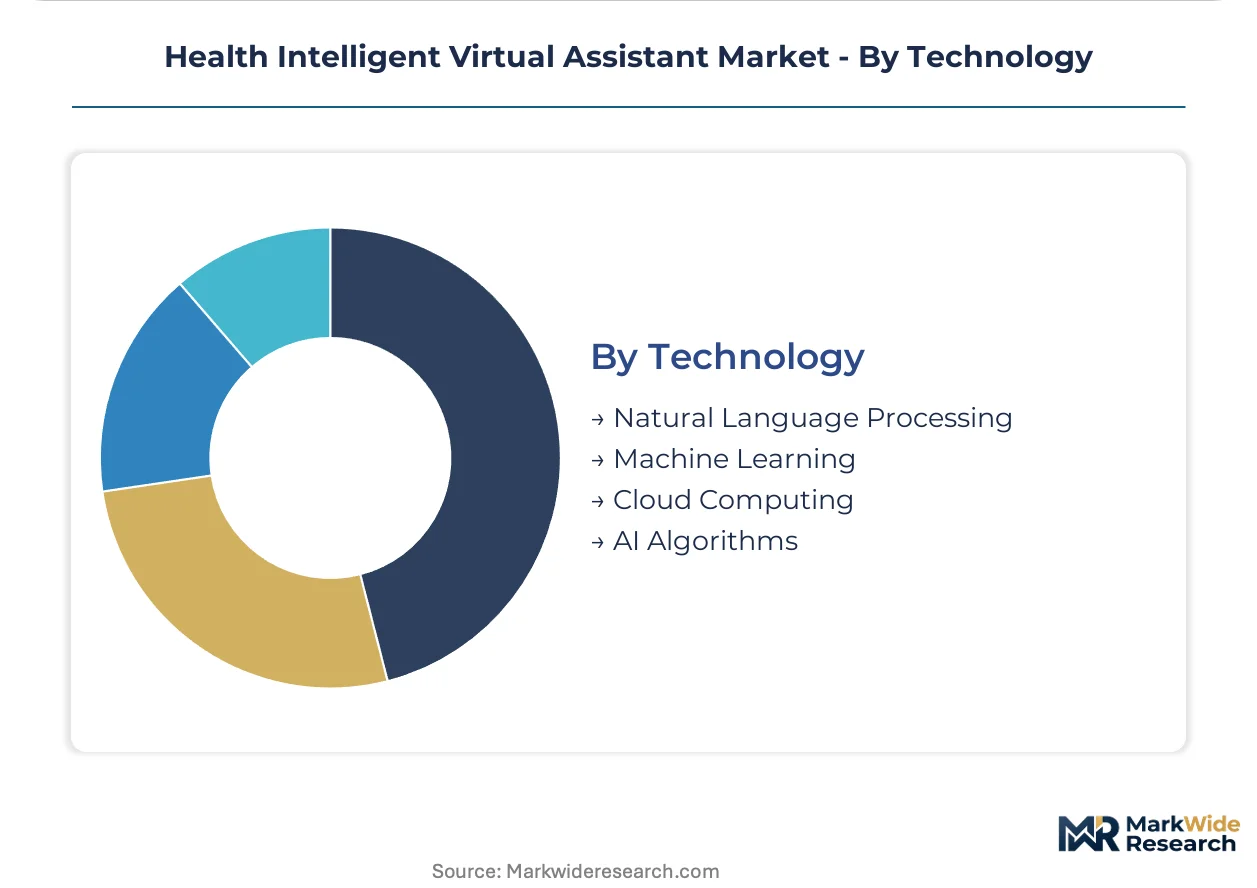
Technology:
AI algorithms concentrate proprietary differentiation while cloud computing resolves HIPAA compliance through standardized business associate agreements.
- AI Algorithms:Diagnostic-adjacent models require continuous learning governance and FDA validation for adaptive system updates. Proprietary clinical conversation datasets from incumbent vendors constrain new entrant accuracy thresholds.
- Natural Language Processing:Generative architectures are displacing retrieval-based systems for contextual fluency, though clinical safety validation burdens expand accordingly.
- Machine Learning:Supervised training pipelines depend on annotated medical dialogue corpora.
- Cloud Computing:Infrastructure-as-a-service deployments from major providers reduce vendor capital requirements.
AI Algorithms define competitive moats. Natural Language Processing is gaining share fastest through large language model convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized health informatics talent concentrates in the United States, Germany, and United Kingdom, anchoring development clusters for clinical NLP systems. These workforce pools shape regional competitive positioning through proximity to academic medical centers and regulatory expertise.
United States
Epic Systems integration requirements drive procurement decisions across integrated delivery networks, with hospital CIOs prioritizing EHR-native deployment. FDA premarket submission pathways for AI-enabled medical devices compress commercialization timelines for diagnostic-adjacent virtual assistants. Academic medical centers in Boston and Stanford pilot ambient documentation systems, reducing physician keyboard burden through voice recognition.
Germany
Notified body capacity constraints under EU MDR create certification bottlenecks for high-risk diagnostic algorithms. The EU AI Act risk classification framework mandates conformity assessments and post-market monitoring systems for clinical virtual assistants. Berlin and Munich health technology vendors restructure quality management systems to accommodate algorithm change control protocols.
United Kingdom
NHS procurement frameworks consolidate vendor evaluations around integrated platform capabilities rather than point solutions. MHRA guidance on software as a medical device shapes development timelines for symptom assessment algorithms. London-based digital health clusters attract venture funding for multimodal interaction convergence projects spanning voice, text, and visual symptom capture.
Canada
Health Canada oversight of AI-enabled medical devices aligns with FDA pathways while maintaining distinct validation requirements for bilingual deployment. Federally qualified health centers in Ontario and Quebec pilot automation for rural network penetration. Toronto health informatics programs supply specialized NLP training talent to domestic vendors.
India
CDSCO medical device regulations govern software classification for diagnostic-adjacent virtual assistants entering commercial distribution. Bengaluru and Hyderabad health technology clusters develop cost-optimized chatbot deployments for appointment scheduling automation. Domestic vendors leverage cloud infrastructure business associate agreements to resolve data localization requirements.
Health Intelligent Virtual Assistant Market Vendor Landscape
Top-tier vendors anchor enterprise EHR integration, while mid-tier specialists compete on voice recognition accuracy and clinical workflow customization. The vendor base stratifies across three performance tiers differentiated by regulatory validation depth and proprietary training data scale. Technology conglomerates with cloud infrastructure assets represent one strategic archetype; voice recognition specialists with deep clinical partnerships represent another. Competitive moves concentrate on strategic partnerships with academic medical centers and portfolio diversification into multimodal interaction capabilities.
Within the technology infrastructure tier, Microsoft leverages Azure cloud assets to anchor hospital network deployments. Nuance Communications exemplifies the voice recognition specialization archetype through clinical documentation focus. eGain Corporation occupies a position among customer engagement platform vendors extending into healthcare verticals. These three anchors represent distinct competitive vectors: cloud-native scale, clinical workflow depth, and cross-industry platform adaptation.
| Leading Market Players |
|---|
| Microsoft |
| Nuance Communications |
| CSS Corp |
| eGain Corporation |
| Kognito |
| MEDRESPOND |
| Next IT Solutions |
| True Image Interactive |
| CodeBaby |
| Others |
Supply Flow & Price Mechanics
Specialized health informatics talent clustering in Boston and the San Francisco Bay Area creates labor-cost differentials that widen pricing-tier spreads between premium clinical workflow integrations and commodity chatbot deployments.
Pricing Analysis
Bundled enterprise EHR-native deployments command substantial premiums over unbundled point solutions lacking native integration. Three-tier pricing structure across premium, standard, and economy levels separates voice assistants with sub-two-second latency from basic scheduling chatbots. Pricing pressure stems from cloud infrastructure commoditization as major providers standardize HIPAA-compliant business associate agreements. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize workflow integration over cost.
Supply Chain Analysis
FDA premarket submission requirements and EU MDR conformity assessments gate vendor participation, filtering supply toward established players with regulatory validation depth. Development concentrates in the United States, Germany, and the United Kingdom, with cloud infrastructure sourcing from domestic hyperscaler regions. Proprietary clinical NLP training datasets represent critical input dependencies concentrated among incumbent vendors. Single-source vulnerability around specialized health informatics talent pools elevates recruitment risk. Distribution runs through direct enterprise sales to hospital systems and GPO-mediated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on voice recognition latency compression reducing edge computing costs and premium-tier ambient documentation systems displacing keyboard-dependent workflows.
For Market Incumbents: Lock in EHR-native deployment advantages through exclusive Epic Systems partnership extensions before generative AI entrants achieve clinical safety validation. Consolidate proprietary training data moats through academic medical center exclusive licensing. Counter emerging voice-first specialists by embedding ambient listening across documentation, triage, and coding workflows.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in rural health network deployments offers white-space entry with cost-optimized chatbot solutions for federally qualified health centers. Target medication adherence applications where CMS reimbursement codes reduce buyer price sensitivity. Pursue channel partnerships with regional health IT distributors lacking national vendor relationships.
For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking clinical workflow depth to anchor healthcare vertical expansion. Five-to-ten year viability favors vendors with FDA diagnostic-adjacent validation and multimodal interaction portfolios. Monitor EU AI Act notified body capacity constraints as inflection indicator for European market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Diagnostic-adjacent virtual assistants require premarket clearance for symptom assessment algorithms. |
| Hospital System Partnership | Epic Systems integration agreements determine procurement eligibility across United States networks. |
| Platform Integration | Voice-text-visual convergence creates differentiation beyond single-modality competitors in enterprise evaluations. |
| Reimbursement Strategy | CMS remote patient monitoring billing codes monetize chronic care management virtual assistant deployments. |
| Acquisition of Specialist Firm | Voice recognition accuracy specialists with clinical documentation focus command strategic premiums. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged hospital CIOs, clinical informatics officers, FDA regulatory consultants, GPO contracts managers, and health technology procurement committees. Secondary sources included FDA 510(k) filings, CMS reimbursement code databases, hospital procurement records, and EHR vendor partnership disclosures. Bottom-up deployment counts triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition anchored the analytical framework, segmenting growth across product type, application, end user, and technology dimensions. Deployment model, organization size, and EHR integration complexity provided additional segmentation granularity. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns. Forecast inputs incorporated FDA guidance evolution timelines and cloud infrastructure capex trajectories from major providers.
Caveats apply where FDA adaptive algorithm guidance revisions or EU AI Act implementation delays could materially shift the outlook. Forecasts reflect assumptions regarding Epic Systems integration prioritization and CMS reimbursement code expansion. A model refresh is warranted upon material change in notified body certification capacity or generative AI clinical safety validation standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
IHE XDS.B Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Global E-Health Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Global Ambulatory EHR Market
Health Informatics
Laboratory Informatics Market