
 Veterinary Endodontics Market | 2026-2036
Veterinary Endodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Endodontics Market Analytics
Specialty veterinary dental distributor networks is reshaping how endodontic instruments and materials reach private practitioners. Midmark Corporation leverages its installed base of anesthesia and dental equipment to cross-sell endodontic consumables through integrated equipment-service contracts. iM3Vet Pty Ltd anchors its position in Australia and expands into Southeast Asian veterinary markets through region-specific product certifications. Henry Schein, Inc. competes by bundling endodontic materials with its broader animal health distribution infrastructure across North American veterinary clinics.
Veterinary endodontics encompasses the diagnosis and treatment of pulp and periapical disease in non-human species, employing specialized files, obturation materials, and apex locators calibrated for carnivore and herbivore dental anatomy. The discipline serves the primary commercial purpose of preserving functional dentition in companion animals, thereby avoiding extraction and maintaining masticatory performance. Instruments and consumables together constitute the dominant product category, with advanced techniques and digital imaging representing the fastest-expanding technology dimension as cone-beam computed tomography migrates from human to veterinary practice. Veterinary hospitals capture the largest end-user share, while private practices represent the most price-sensitive segment with growing interest in portable endodontic systems.
The FDA Center for Veterinary Medicine oversees material biocompatibility for devices used in animal dental procedures, while USDA APHIS regulates interstate movement of biological materials employed in regenerative endodontic research. ISO 10993 biological evaluation standards increasingly influence supplier qualification for veterinary-specific obturation materials and sealers. State veterinary medical boards in the United States and the Royal College of Veterinary Surgeons in the United Kingdom set credentialing requirements that determine which practitioners may perform endodontic procedures, directly shaping addressable demand. Stakeholders must monitor how telemedicine regulations and credentialing reciprocity agreements reshape referral patterns between general practitioners and specialist veterinary dentists.
Market Dynamics
Digital imaging systems are compressing diagnostic timelines for veterinary endodontic procedures, forcing equipment suppliers to bundle cone-beam computed tomography hardware with software subscriptions rather than standalone sales.
Growth Catalysts
- Pet Insurance Coverage:Broadening reimbursement policies in the United States and Germany reduce out-of-pocket costs for complex endodontic procedures, expanding addressable demand among companion animal owners.
- ISO 10993 Standards:Harmonized biocompatibility evaluation protocols for veterinary obturation materials streamline supplier qualification across multiple jurisdictions, reducing regulatory fragmentation.
- University Teaching Hospitals:Referral networks anchored by credentialing pathways at institutions in Australia and the United States channel complex cases toward certified veterinary dentists.
Market Restraints
- Specialist Supply Concentration:The pool of board-certified veterinary dentists remains concentrated in urban clusters across the United States, Germany, and Australia, creating access bottlenecks for rural practitioners.
- Equipment Capex Requirements:Digital radiography and apex locator systems require substantial upfront investment, pricing smaller private practices out of advanced endodontic service provision.
- Credentialing Variability:State veterinary medical boards in the United States maintain inconsistent scope-of-practice definitions, creating regulatory friction for interstate referral networks.
Strategic Opportunities
- Portable System Development:Compact, battery-powered endodontic equipment addresses the unmet need of mobile veterinary dentists serving multi-clinic networks in suburban United States markets.
- Southeast Asian Expansion:Region-specific product certifications enable entry into veterinary markets where companion animal expenditure is accelerating faster than specialist infrastructure.
- Telemedicine Integration:Regulatory clarity on remote consultation and case review is reshaping referral patterns between general practitioners and specialist dentists in Western Europe.
Industry Challenges
- Specialist Training Pipeline:The extended residency requirements for veterinary dental certification create a multi-year lag between market demand and qualified practitioner supply.
- Legacy Equipment Interoperability:Digital imaging systems from different manufacturers often lack standardized data formats, complicating record transfer between referring clinics and specialty hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Endodontics Market |
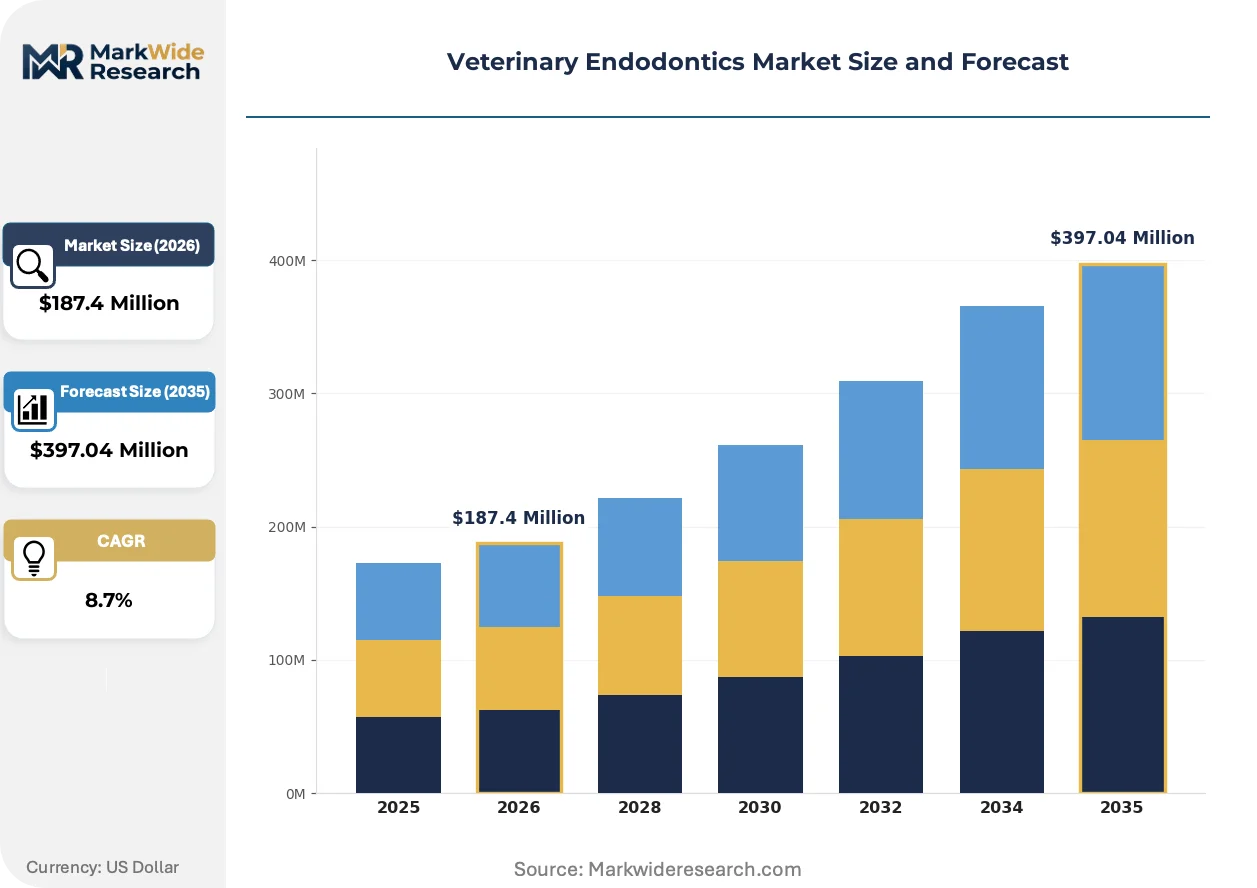
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Materials, Software, Consumables Application: Clinical Procedures, Educational Purposes, Research Activities, Training Programs End User: Veterinary Hospitals, Clinics, Research Institutions, Private Practices Technology: Conventional Techniques, Advanced Techniques, Digital Imaging, Laser Technology |
| Companies Covered | Midmark Corporation, iM3Vet Pty Ltd, Acteon Group Ltd, Dentsply Sirona, Henry Schein, Inc., Dentalaire International, Cislak Manufacturing, Integra LifeSciences, Planmeca OY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Endodontics Market Evolving Landscape
Laser technology is reshaping soft tissue management in veterinary endodontic procedures, displacing conventional mechanical debridement in specialty clinics with the capital to absorb platform costs.
Cone-beam computed tomography is migrating from human dental practice into veterinary applications, delivering three-dimensional periapical visualization that conventional radiography cannot match. University teaching hospitals in the United States and Germany are adopting these systems first, compressing the diagnostic phase of complex endodontic cases. Equipment manufacturers are responding by developing species-specific imaging protocols for carnivore and herbivore dental anatomy.
The FDA Center for Veterinary Medicine is tightening material biocompatibility documentation requirements for obturation sealers used in animal procedures. Suppliers must now submit expanded toxicological data packages, extending product registration timelines by twelve to eighteen months. European manufacturers are leveraging REACH-compliant chemical safety dossiers to accelerate parallel submissions under ISO 10993 frameworks.
Referral network consolidation is altering how general practitioners access specialist endodontic services. Large corporate veterinary groups in the United States are acquiring specialty dentistry practices, internalizing referrals that previously flowed to independent hospitals. This vertical integration compresses case turnaround times but reduces equipment purchasing autonomy at the clinic level.
Veterinary Endodontics Market Segmentation
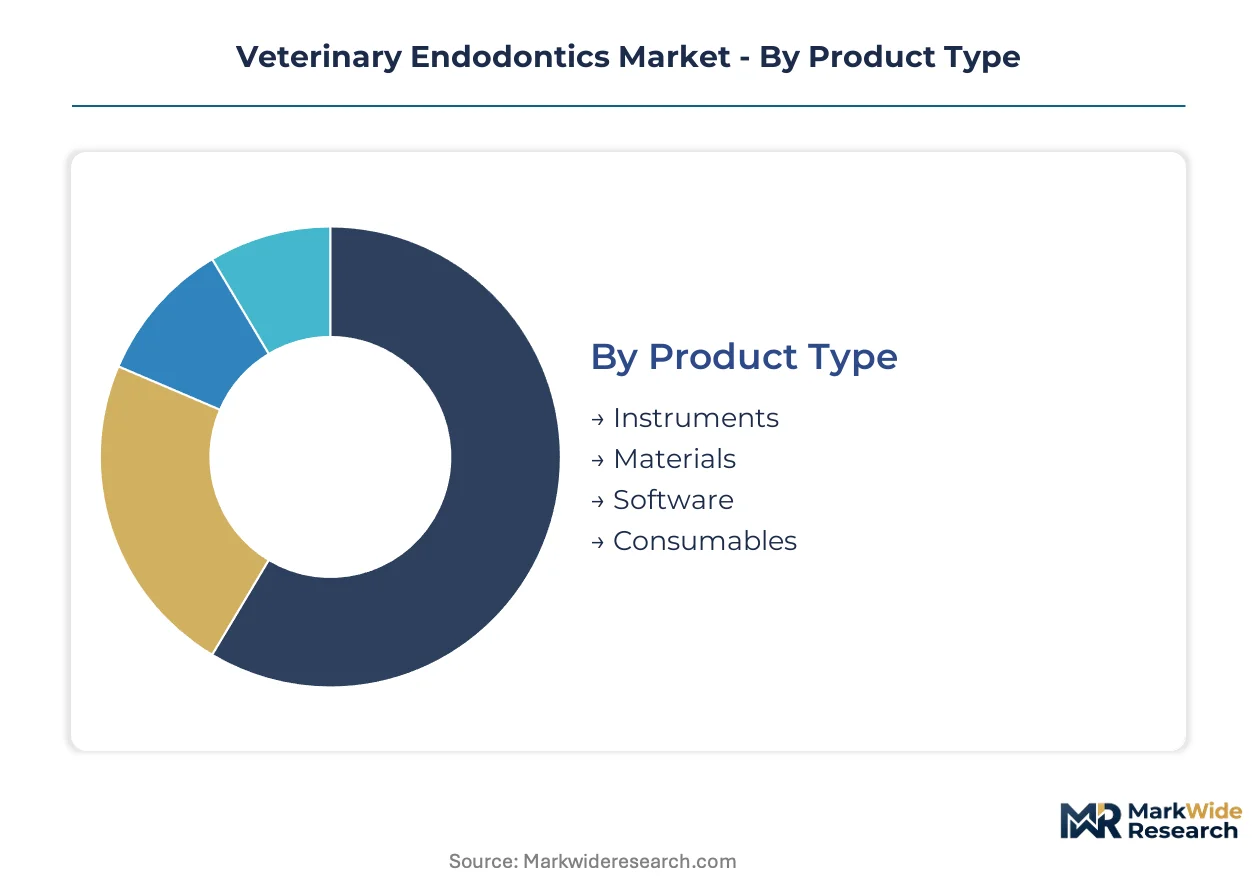
Veterinary endodontics segmentation reveals distinct procurement rhythms across product categories. Instruments and consumables turn over rapidly through distributor networks, while capital equipment cycles stretch across multiple years.
Product Type:
Instruments and consumables rotate through inventory fastest, with materials and software commanding extended replacement cycles.
- Instruments:Specialized files, apex locators, and handpieces engineered for carnivore and herbivore dental anatomy. Demand clusters in United States specialty clinics where state veterinary medical boards tighten credentialing standards for advanced procedures.
- Consumables:Obturation materials, sealers, and irrigants requiring frequent replenishment. German and Australian university teaching hospitals anchor procurement volume as referral networks channel complex cases toward certified practitioners.
- Materials:Bioceramic sealers and gutta-percha variants governed by ISO 10993 biocompatibility protocols.
- Software:Imaging analysis and treatment planning platforms bundled with hardware subscriptions.
Instruments dominate installed base. Consumables represent where expansion concentrates.
Application:
Clinical throughput drives the steepest revenue concentration, while educational and research applications sustain longer contract horizons.
- Clinical Procedures:Therapeutic interventions including root canal therapy, vital pulp therapy, and periapical surgery. United States pet insurance reimbursement policies reduce out-of-pocket costs, expanding addressable demand among companion animal owners.
- Educational Purposes:Curriculum support for veterinary dental residency programs. Royal College of Veterinary Surgeons credentialing requirements in the United Kingdom shape simulator and model procurement.
- Research Activities:Regenerative endodontic studies employing biological materials regulated by USDA APHIS interstate movement protocols.
- Training Programs:Continuing education workshops for general practitioners seeking procedural expansion.
Clinical procedures generate dominant revenue share. Educational purposes anchor long-term supplier relationships.
End User:
Hospital procurement operates on capital budgeting cycles, while private practices favor portable equipment with compressed payback periods.
- Veterinary Hospitals:Multi-specialty institutions with dedicated dental suites and in-house cone-beam computed tomography. United States corporate veterinary groups internalize referrals through acquired specialty dentistry practices.
- Private Practices:Solo and small-group clinics prioritizing mobile-compatible systems. Suburban United States markets show unmet demand for battery-powered portable equipment serving multi-clinic networks.
- Clinics:General practice settings with intermittent endodontic caseload.
- Research Institutions:University laboratories conducting regenerative and materials science studies.
Veterinary hospitals command premium equipment specifications. Private practices represent the fastest volume expansion.
Technology:
Digital and laser platforms displace conventional methods where capital availability permits, while basic techniques retain share in price-sensitive settings.
- Digital Imaging:Cone-beam computed tomography systems migrating from human dental practice with species-specific protocols for carnivore and herbivore anatomy. German university hospitals adopt first, compressing diagnostic timelines for complex cases.
- Laser Technology:Soft tissue management platforms displacing mechanical debridement in specialty clinics with sufficient capital absorption capacity.
- Advanced Techniques:Microsurgical instrumentation and operating microscopes for complex retreatment.
- Conventional Techniques:Hand instrumentation and radiographic methods retaining share in rural and developing markets.
Conventional techniques retain broad installed base. Digital imaging captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance reimbursement policies in the United States and Germany compress out-of-pocket costs for complex endodontic procedures, expanding addressable demand among companion animal owners. University teaching hospitals in Australia and credentialing pathways at American Veterinary Dental College institutions channel referral volumes toward certified practitioners.
United States
Corporate veterinary groups acquire specialty dentistry practices, internalizing referrals that previously flowed to independent hospitals. The FDA Center for Veterinary Medicine tightens material biocompatibility documentation requirements for obturation sealers, extending product registration timelines. Urban clusters in California and the Northeast concentrate board-certified veterinary dentists, creating access bottlenecks for rural practitioners.
Germany
REACH-compliant chemical safety dossiers accelerate parallel submissions under ISO 10993 frameworks for European manufacturers. The country's national veterinary regulator enforces harmonized biocompatibility evaluation protocols for veterinary obturation materials. University teaching hospitals in Bavaria and North Rhine-Westphalia adopt cone-beam computed tomography systems first, compressing diagnostic timelines for complex cases.
Australia
iM3Vet anchors procurement volume through region-specific product certifications enabling Southeast Asian market expansion. The Therapeutic Goods Administration influences material safety standards through alignment with international biocompatibility frameworks. University veterinary teaching hospitals in New South Wales and Victoria anchor referral networks and continuing education pathways for complex endodontic cases.
United Kingdom
The Royal College of Veterinary Surgeons sets credentialing requirements determining which practitioners may perform endodontic procedures, directly shaping addressable demand. Simulator and model procurement for veterinary dental residency programs sustains longer contract horizons with suppliers. Greater London and the Southeast concentrate specialty practices with dedicated dental suites and in-house imaging capacity.
Japan
The Ministry of Agriculture, Forestry and Fisheries oversees animal health standards influencing veterinary dental equipment import protocols. The Pharmaceuticals and Medical Devices Agency provides regulatory reference points for material biocompatibility assessment in companion animal procedures. The Kanto region around Tokyo concentrates specialty veterinary hospitals with capital budgeting cycles supporting cone-beam computed tomography adoption.
Veterinary Endodontics Market Competitive Landscape
On the supply side, the industry is moderately concentrated around integrated equipment-service providers and specialized veterinary dental distributors. Equipment manufacturers with installed bases in anesthesia and dental suites leverage cross-selling opportunities for endodontic consumables. Three strategic archetypes dominate: integrated veterinary equipment conglomerates, specialized dental distributors with regional certification expertise, and human dental multinationals adapting platforms for veterinary anatomy. Competitive moves center on geographic expansion through region-specific certifications and portfolio diversification into portable battery-powered systems.
Among integrated veterinary equipment providers, Midmark Corporation and Henry Schein, Inc. exemplify the equipment-service bundling archetype, leveraging broad animal health distribution infrastructure to cross-sell endodontic consumables. iM3Vet Pty Ltd occupies a position as the specialized regional distributor archetype, anchoring procurement volume in Australia while expanding through Southeast Asian certification pathways. Acteon Group Ltd represents the human-to-veterinary adaptation archetype, applying dental technology platforms to species-specific anatomical requirements.
| Leading Market Players |
|---|
| Midmark Corporation |
| iM3Vet Pty Ltd |
| Acteon Group Ltd |
| Dentsply Sirona |
| Henry Schein, Inc. |
| Dentalaire International |
| Cislak Manufacturing |
| Integra LifeSciences |
| Planmeca OY |
| Others |
Value Network & Pricing Analysis
German and Swiss precision instrument manufacturers anchor upstream supply for veterinary endodontic files and apex locators, concentrating margin capture in the premium equipment tier while distributor networks absorb working capital pressure downstream.
Pricing Analysis
Volume-discount tiering separates institutional procurement by university teaching hospitals from solo private practices purchasing portable systems. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 certification grade and after-sales service bundling. Pricing pressure stems from corporate veterinary groups consolidating specialty practices and internalizing equipment purchasing decisions. Private practices exhibit highest price sensitivity, deferring capital expenditure on cone-beam computed tomography systems, while teaching hospitals demonstrate lowest sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Extended payment terms from sixty to ninety days characterize supplier financing arrangements for distributor networks stocking consumables. Manufacturing concentrates in Germany, Switzerland, and the United States for precision instruments, with bioceramic sealer production drawing from Italian and Japanese chemical suppliers. Single-source vulnerability persists for species-specific imaging software protocols. Distribution runs through integrated veterinary equipment conglomerates and specialized dental distributors with regional certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against extraction-as-alternative, where companion animal owners opt for tooth removal rather than costly endodontic preservation when insurance coverage gaps persist.
For Market Incumbents: Insulate referral relationships by embedding portable equipment financing into multi-clinic service contracts, countering corporate group vertical integration that internalizes specialist access. Deepen backward integration into bioceramic sealer formulation to capture margin pools currently flowing to European chemical suppliers. Fortify position against extraction substitution through outcome-guarantee pricing models that align procedure cost with functional dentition preservation.
For New Entrants and Emerging Players: Build out battery-powered portable system distribution in suburban United States markets where mobile veterinary dentists serve fragmented multi-clinic networks. Target Southeast Asian certification pathways ahead of specialist infrastructure buildout, leveraging region-specific regulatory alignment with Australian Therapeutic Goods Administration standards. Establish go-to-market presence through continuing education workshop sponsorships that channel general practitioners toward procedural expansion.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized regional distributors with established Southeast Asian certification portfolios and university teaching hospital anchoring relationships. Long-term viability hinges on telemedicine regulatory clarity reshaping referral patterns between general practitioners and specialist dentists. Watch for FDA Center for Veterinary Medicine biocompatibility documentation timeline extensions as inflection signal for sealer supplier consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Region-Specific Certification Investment | Australian TGA alignment accelerates Southeast Asian market entry for consumables suppliers. |
| Portable Equipment Development | Battery-powered systems address unmet suburban United States mobile dentistry demand. |
| University Hospital Partnership | Teaching hospital anchoring secures referral network channel control for complex cases. |
| Bioceramic Sealer Backward Integration | In-house formulation captures margin pools from European chemical suppliers. |
| Telemedicine Platform Integration | Remote consultation capability reshapes general practitioner to specialist referral flows. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with veterinary dental specialists, procurement managers at corporate veterinary groups, distributor network heads, and regulatory affairs leads at equipment manufacturers; alongside secondary validation through FDA Center for Veterinary Medicine device filings, ISO 10993 biocompatibility registration databases, state veterinary medical board credentialing records, and university teaching hospital capital expenditure disclosures. Bottom-up procedure volume estimates triangulated against top-down equipment shipment data.
Forecast inputs incorporated product type segmentation across instruments, consumables, materials, and software; application segmentation spanning clinical procedures, educational purposes, research activities, and training programs; end-user segmentation by hospital, private practice, clinic, and research institution; and technology segmentation across digital imaging, laser platforms, advanced techniques, and conventional methods. CAGRs derived from procedure volume elasticity to pet insurance penetration rates and specialist supply pipeline graduation counts. Species-specific imaging protocol development timelines and telemedicine regulatory clarity progression served as veterinary-specific forecast modifiers.
Sensitivities concentrate around pet insurance reimbursement policy shifts, FDA biocompatibility documentation timeline extensions, and specialist training pipeline output fluctuations. Forecasts reflect documented assumptions regarding credentialing pathway expansion and corporate group acquisition velocity. Macroeconomic contraction affecting discretionary companion animal expenditure, regulatory restriction on biological material interstate movement, or disruptive substitution by regenerative dental therapies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Swine Vaccines Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Consumables Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Veterinary Hospitals Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Global Veterinary MRI Market
Veterinary
Global Dog Vaccines Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Milking Salve Market
Veterinary
Companion Animal Vaccines Market
Veterinary
OTC Cat Medicines Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Global Cattle Vaccines Market