
 Mineral Ingredients Market | 2026-2036
Mineral Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Ingredients Market Analysis
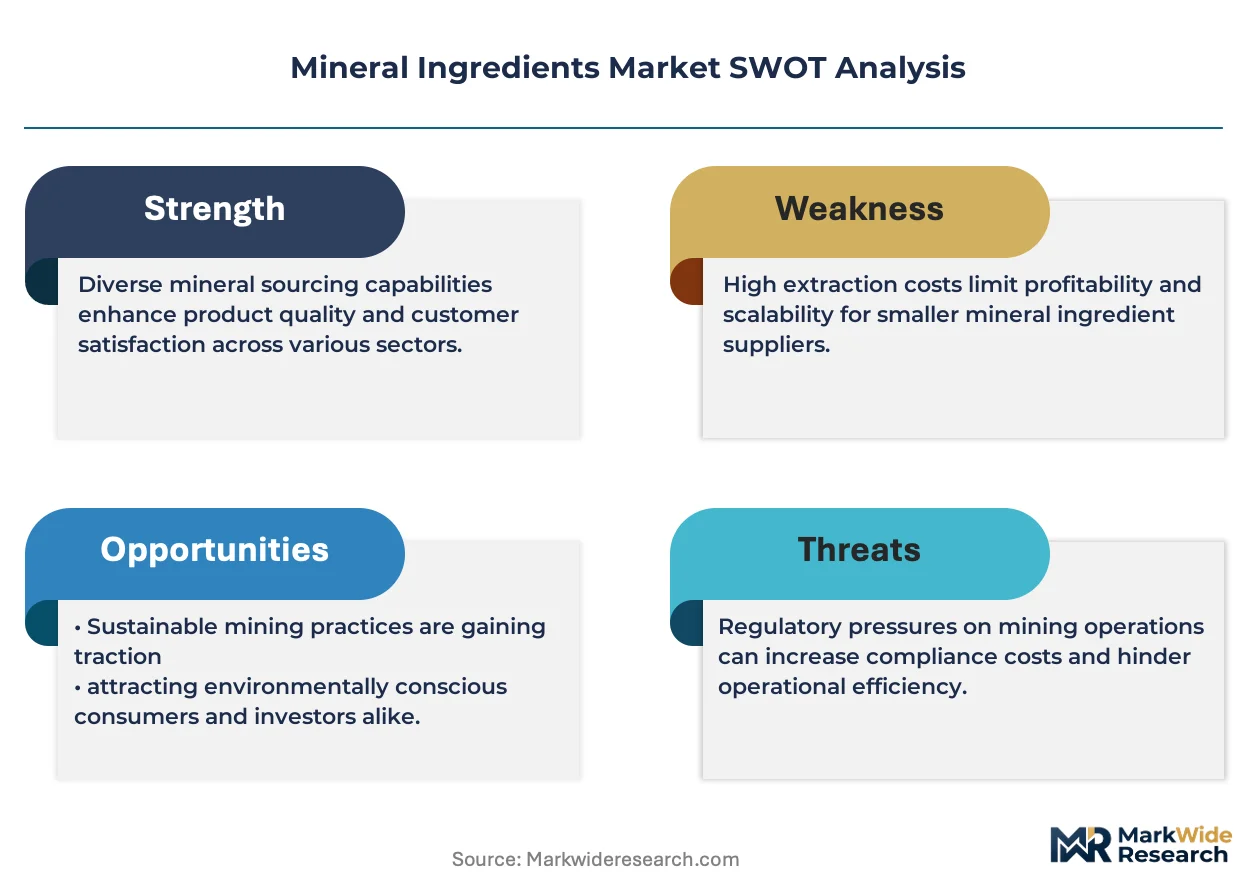
Buyer concentration in the food and beverage sector is broadening as mid-sized functional food startups and private-label manufacturers diversify procurement beyond legacy pharmaceutical offtake. Balchem Corporation leverages its chelated mineral technology to sustain premium positioning in human nutrition. BASF SE anchors European supply through its captive carbonate and phosphate complexes. Yara International ASA dominates agricultural mineral flows, extending its nitrogen-mineral integration into specialty crop nutrition.
Mineral ingredients comprise inorganic compounds and elemental salts refined to specific purity grades, typically exceeding food-grade or pharmaceutical-grade thresholds, serving as essential fortificants, excipients, and nutritional intermediates across industrial formulations. Calcium carbonate leads product type volumes due to its ubiquity in antacid pharmaceuticals and dairy analogs, while potassium chloride grows fastest as sodium-reduction campaigns reshape processed food recipes. Powder form occupies the largest share of mineral ingredient shipments, though liquid suspensions gain share in beverage fortification where dispersion uniformity commands margin premiums.
FDA food additive regulations and GRAS self-affirmation pathways shape U.S. market access timelines for novel mineral chelates, while REACH registration requirements in Europe constrain synthetic sourcing from non-compliant suppliers. FSSAI fortification standards in India mandate iron, zinc, and calcium inclusion in staple commodities, directly lifting carbonate and sulfate demand. Stakeholders must monitor evolving chelation-bioavailability claims and regional purity standards to align R&D portfolios with divergent regulatory thresholds.
Market Dynamics
Clean-label fortification mandates across food and beverage manufacturing are compressing formulation timelines while elevating purity thresholds, forcing mineral suppliers to requalify legacy carbonate and sulfate grades against evolving bioavailability benchmarks.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory iron, zinc, and calcium inclusion in staple commodities directly expands food-grade mineral salt procurement volumes from domestic producers.
- Sodium-reduction campaigns:Reformulated processed food recipes across North America and Europe accelerate potassium chloride substitution for sodium-based salts in savory applications.
- Chelated mineral technology:Enhanced bioavailability claims from amino acid chelates command premium positioning in human nutrition and dietary supplement channels.
Market Restraints
- Phosphate rock concentration:Morocco and Western Sahara control roughly three-quarters of exploitable phosphate reserves, creating geopolitical chokepoints for calcium phosphate supply security.
- REACH registration friction:Synthetic mineral sourcing from non-compliant Asian suppliers faces exclusion from European formulated food and pharmaceutical supply chains.
- Energy-intensive calcination:Natural gas price volatility directly compresses margins for precipitated calcium carbonate producers dependent on thermal processing.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for specialty chemicals attract greenfield investment in food-grade mineral salt manufacturing capacity near Mumbai and Ahmedabad industrial corridors.
- Beverage suspension systems:Liquid mineral fortification for ready-to-drink functional beverages creates demand for nano-dispersed carbonate and citrate formats with extended shelf stability.
- EU F-Gas Regulation:Refrigeration-dependent mineral processing facilities must retrofit cooling systems, favoring suppliers with captive renewable energy and low-carbon thermal infrastructure.
Industry Challenges
- GRAS self-affirmation complexity:Novel mineral chelates face protracted FDA review timelines as toxicological data requirements expand for bioavailability claims in dietary supplements.
- Multi-jurisdictional purity harmonization:Divergent food-grade thresholds between USP, EP, and FSSAI specifications force redundant testing protocols and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Ingredients Market |
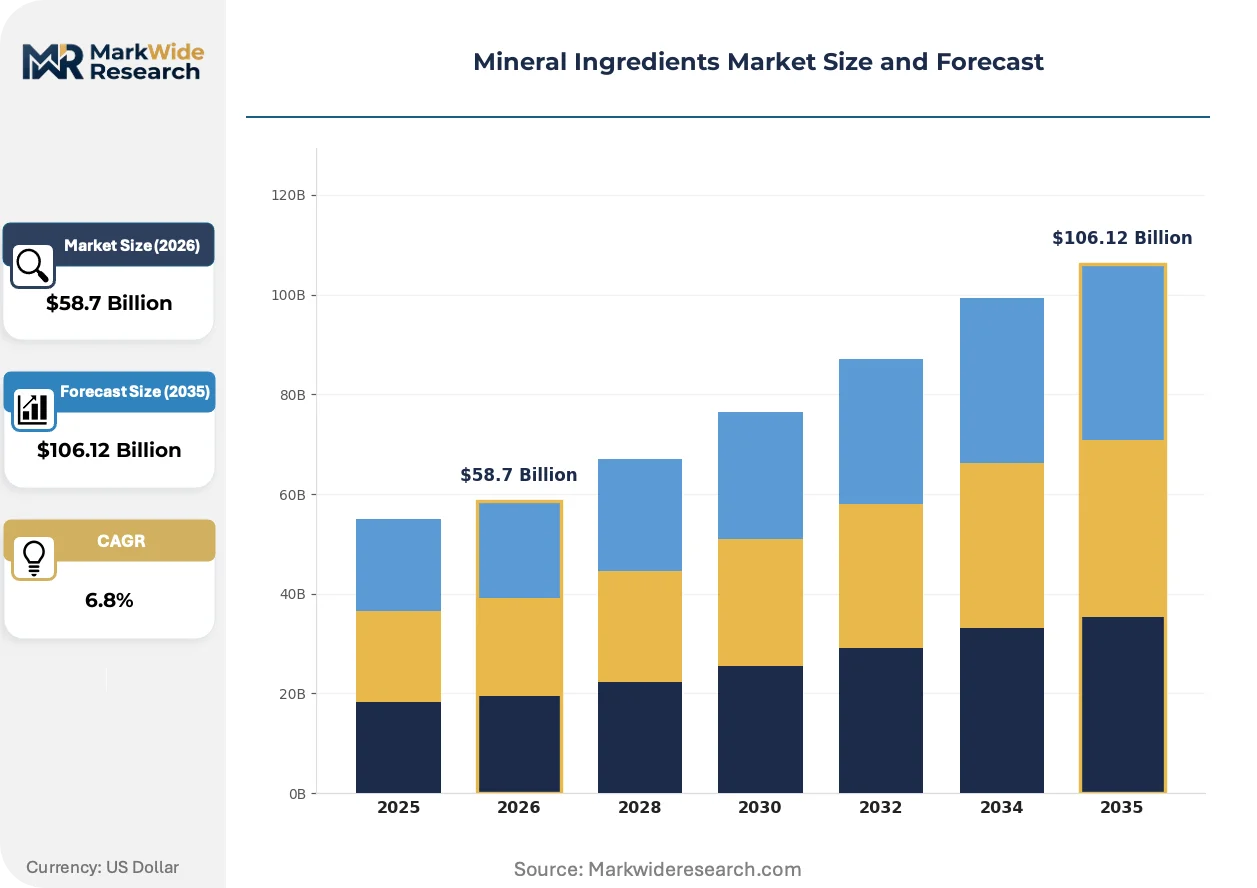
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Magnesium Sulfate, Potassium Chloride, Sodium Bicarbonate End Use Industry: Food & Beverage, Pharmaceuticals, Agriculture, Personal Care Form: Powder, Granules, Crystals, Liquid Source: Natural, Synthetic, Organic, Inorganic |
| Companies Covered | Balchem Corporation, Kemin Industries, Corbion, Zinpro Corporation, Innophos, Koninklijke DSM N.V., BASF SE, Yara International ASA, Gadot Biochemical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Ingredients Market Emerging Trajectories
Mineral ingredient innovation centers on bioavailability enhancement, regulatory pre-certification, and format flexibility for clean-label applications. Formulation science and processing technology are converging to compress development cycles while expanding addressable end-use segments.
Amino acid chelation technology is overtaking inorganic salt formats in premium human nutrition segments. Functional food manufacturers in Germany and Switzerland now specify glycinate and bisglycinate complexes for magnesium and zinc fortification. This shift compresses demand for traditional oxide and sulfate grades in high-margin applications while elevating technical barriers for commodity suppliers.
REACH authorization requirements for synthetic mineral intermediates are tightening sourcing transparency across European supply chains. ECHA substance evaluation protocols now demand full toxicological dossiers for novel chelating agents used in food contact materials. German and Dutch formulators are responding by pre-qualifying captive mineral suppliers against evolving SVHC candidate list criteria.
Direct procurement relationships between mineral refiners and mid-sized functional food startups are fragmenting traditional distributor channels. These emerging manufacturers in California and Massachusetts now negotiate specification-grade contracts bypassing legacy ingredient brokers. The shift is most pronounced in plant-based dairy analogs where rapid formulation iteration demands technical partnership rather than transactional supply.
Mineral Ingredients Market Segmentation
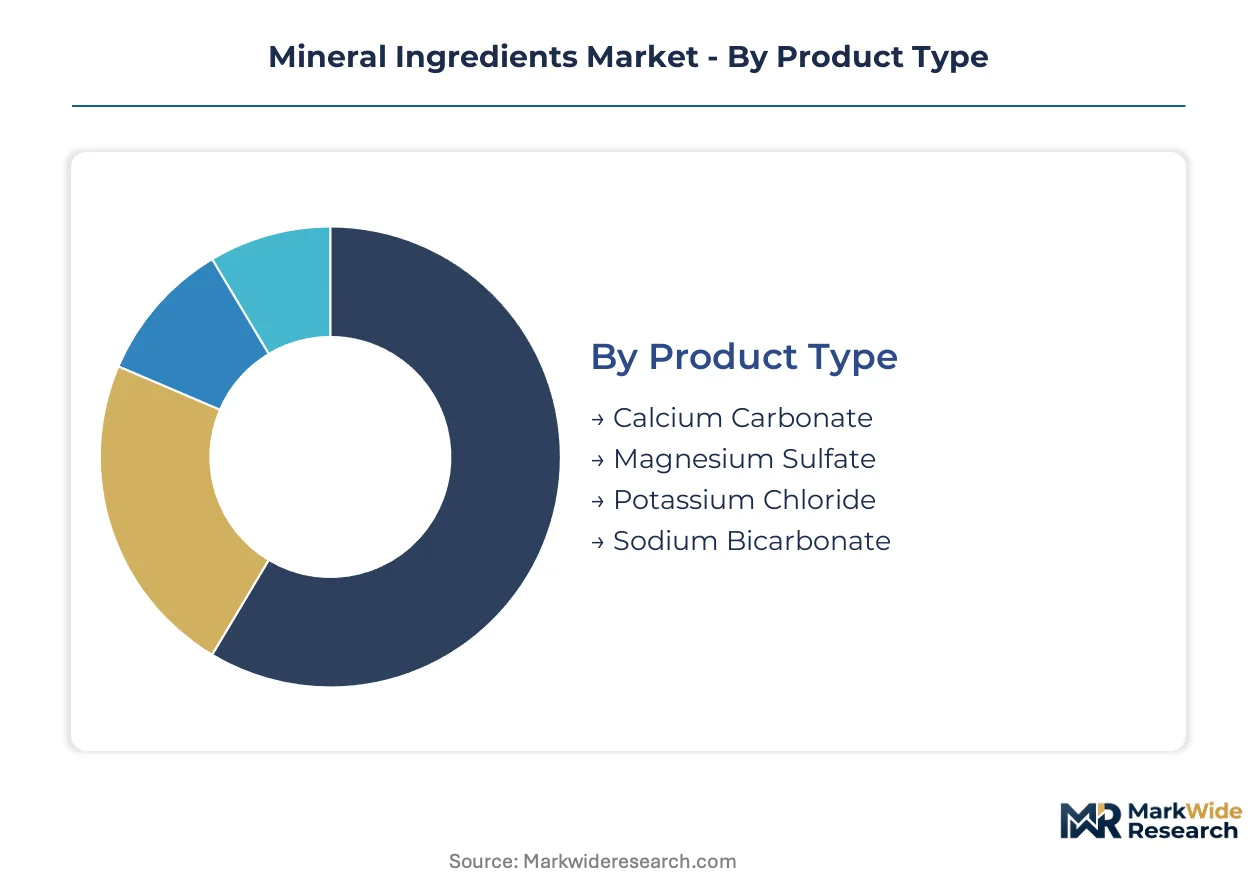
Mineral ingredient procurement decisions hinge on purity thresholds, bioavailability benchmarks, and regulatory alignment across divergent end-use specifications. Formulators select segments based on dissolution kinetics, particle morphology, and compliance with food-grade versus pharmaceutical-grade standards.
Product Type:
Purchasing managers prioritize solubility profiles and cost-per-dose efficiency when selecting mineral compounds for fortification matrices.
- Calcium Carbonate:Precipitated and ground forms serve antacid pharmaceuticals and dairy analogs with high elemental calcium density. USP-grade material from Midwestern limestone deposits supplies North American nutraceutical contract manufacturers under FDA food additive regulations.
- Potassium Chloride:Crystalline salt substitutes sodium chloride in reformulated savory processed foods. Sodium-reduction mandates from Health Canada and FDA guidance documents accelerate procurement volumes for CPG manufacturers in Ontario and California.
- Magnesium Sulfate:Heptahydrate crystals function as osmotic laxatives and magnesium replenishment sources. Pharmaceutical compounders in Maharashtra specify EP-grade material for parenteral formulations under CDSCO oversight.
- Sodium Bicarbonate:Alkaline buffer maintains pH stability in effervescent tablets and baking applications. German chemical distributors stock food-grade and technical-grade variants for divergent industrial channels.
Calcium carbonate leads on scale; potassium chloride leads on momentum.
End Use Industry:
Application-specific purity requirements and formulation complexity determine supplier qualification pathways.
- Food & Beverage:Clean-label fortification mandates from FSSAI, FDA, and EFSA drive carbonate, citrate, and glycinate procurement for staple commodity enrichment. Ready-to-drink beverage manufacturers specify nano-dispersed suspensions for shelf-stable mineral delivery.
- Pharmaceuticals:Excipient-grade minerals require USP-NF or EP certification for tablet compression and capsule filling operations. Mumbai-based generic drug producers audit sulfate and oxide suppliers against ICH Q3D elemental impurity guidelines.
- Agriculture:Micronutrient premixes for fertigation and foliar application demand water-soluble sulfate and chelated forms. Yara International and similar integrated suppliers control nitrogen-mineral blending operations near Rotterdam and Tampa.
- Personal Care:Cosmetic-grade zinc oxide and magnesium derivatives serve dermal protection and sensory modification functions. Formulators in Île-de-France specify non-nano particle sizes under REACH cosmetic ingredient restrictions.
Food and beverage commands procurement volume; pharmaceuticals extract premium pricing through certification overhead.
Form:
Processing equipment compatibility and dissolution rate specifications guide physical format selection.
- Powder:Milled carbonate and sulfate powders dominate bulk shipments for dry blending operations. Fluidized bed coating facilities in Gujarat process micronized material for controlled-release nutraceutical applications.
- Liquid:Suspended citrate and bisglycinate solutions enable homogeneous fortification of UHT beverages and liquid dietary supplements. Nano-dispersion technology from Swiss specialty chemical suppliers extends sedimentation stability beyond 12 months.
- Granules:Agglomerated forms improve flowability for high-speed tablet presses and direct-compression nutraceutical manufacturing.
- Crystals:Pharmaceutical-grade heptahydrate and anhydrous crystals meet USP solubility specifications for parenteral and oral dosage forms.
Powder retains dominant share; liquid formats gain fastest in beverage fortification channels.
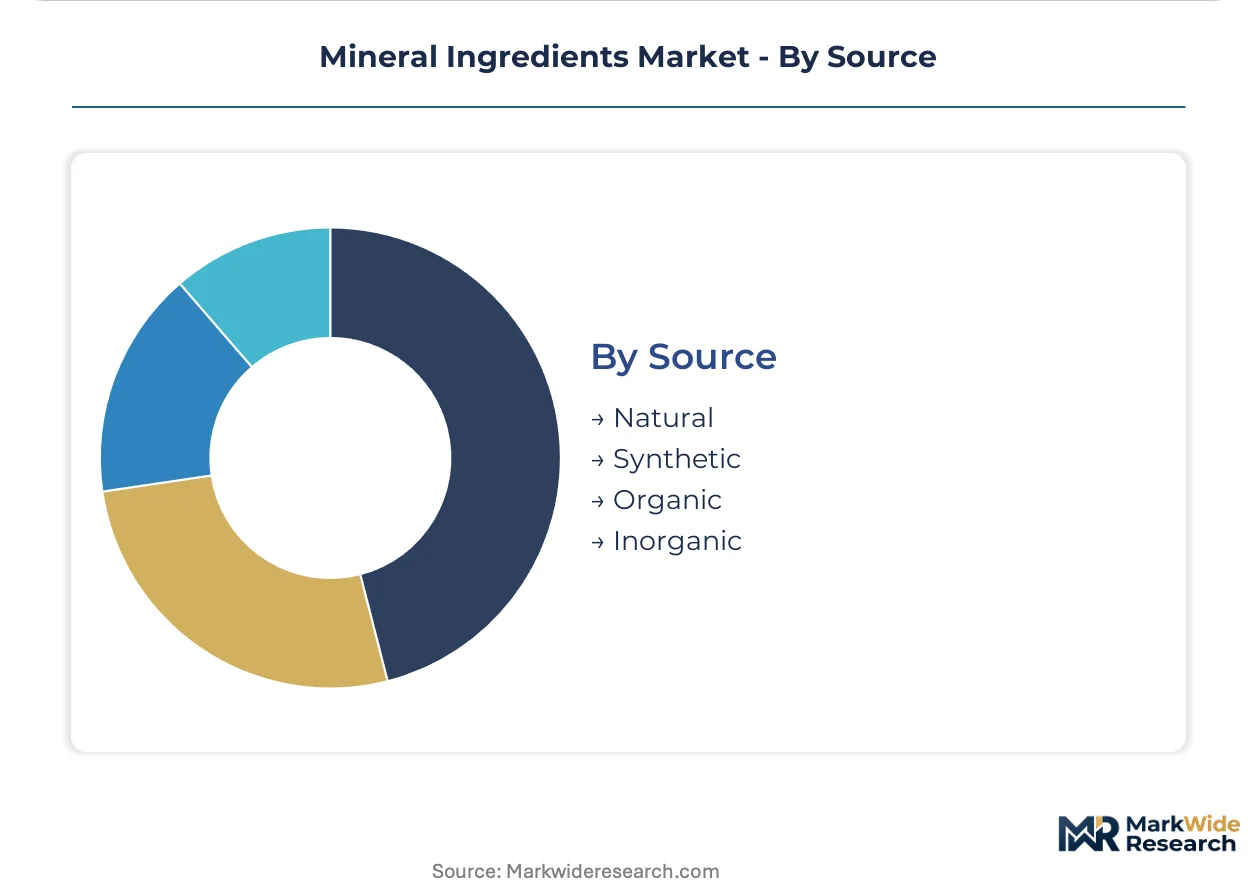
Source:
Clean-label positioning and supply chain traceability requirements increasingly influence origin-based procurement policies.
- Natural:Mined limestone, dolomite, and evaporite deposits supply carbonate and sulfate raw materials. Rajasthan and Madhya Pradesh quarries feed domestic Indian food-grade salt production under FSSAI traceability mandates.
- Synthetic:Precipitated calcium carbonate from carbonation of calcium hydroxide offers controlled particle size distribution. European REACH registration requirements constrain synthetic sourcing to ECHA-compliant production facilities.
- Organic:Plant-derived mineral concentrates from seaweed and botanical extraction serve niche clean-label positioning.
- Inorganic:Elemental and salt-based forms constitute the technical baseline for industrial and pharmaceutical specifications.
Natural sourcing dominates volume; synthetic routes command premium in high-purity pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FSSAI fortification mandates are accelerating domestic mineral salt production faster than Germany's REACH compliance requirements are constraining synthetic carbonate imports. This divergence is reshaping procurement geography across food-grade and pharmaceutical-grade segments.
United States
Fortified beverage startups in California and Massachusetts are bypassing traditional distributors to negotiate direct specification contracts with mineral refiners. FDA GRAS self-affirmation pathways for novel chelates face expanded toxicological data requirements, extending market access timelines. Midwestern limestone deposits around Illinois and Ohio supply precipitated calcium carbonate to nutraceutical contract manufacturers.
Germany
EFSA clean-label mandates are elevating bioavailability benchmarks for carbonate and citrate grades used in functional foods. ECHA REACH authorization requirements now demand full toxicological dossiers for chelating agents in food contact materials. Chemical distributors in North Rhine-Westphalia maintain dual food-grade and technical-grade sodium bicarbonate inventories for divergent industrial channels.
India
PLI scheme incentives are attracting greenfield investment in food-grade mineral salt capacity near Mumbai and Ahmedabad. FSSAI mandates for iron, zinc, and calcium inclusion in staple commodities directly expand procurement from domestic producers. Rajasthan and Madhya Pradesh quarries feed carbonate and sulfate production under national traceability requirements.
Switzerland
Swissmedic pharmaceutical-grade standards are anchoring premium mineral excipient demand for generic drug producers. Specialty chemical suppliers around Basel are commercializing nano-dispersion technology for beverage suspension systems with 12-month sedimentation stability. Glycinate and bisglycinate complex specifications from German and Swiss formulators are displacing traditional oxide grades.
Netherlands
Integrated nitrogen-mineral blending operations near Rotterdam are controlling agricultural micronutrient flows into specialty crop nutrition. ECHA substance evaluation protocols are forcing Dutch formulators to pre-qualify captive suppliers against SVHC candidate list criteria. REACH registration friction is excluding non-compliant Asian synthetic mineral sources from European supply chains.
Mineral Ingredients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base stratifies between multinational chemical conglomerates with captive mineral complexes and mid-sized technology specialists with chelation expertise. Three archetypes dominate: integrated agricultural-nutrition hybrids, pharmaceutical-grade excipient suppliers, and bioavailability-focused human nutrition formulators. Capacity expansion in India and strategic partnerships for beverage suspension technology represent the dominant competitive vectors.
Among the integrated agricultural-nutrition hybrids, Yara International ASA occupies a position exemplifying nitrogen-mineral integration into specialty crop channels. BASF SE anchors the European supply archetype through its captive carbonate and phosphate production infrastructure. Balchem Corporation represents the bioavailability-focused tier, with its positioning sustained by chelated mineral technology in human nutrition applications.
| Leading Market Players |
|---|
| Balchem Corporation |
| Kemin Industries |
| Corbion |
| Zinpro Corporation |
| Innophos |
| Koninklijke DSM N.V. |
| BASF SE |
| Yara International ASA |
| Gadot Biochemical Industries |
| Others |
Supply Flow & Price Mechanics
Natural gas feedstock costs for thermal calcination of precipitated calcium carbonate flow directly from European spot markets through to premium-tier carbonate pricing, compressing margins for producers without captive renewable energy infrastructure while elevating price floors for food-grade mineral salts sourced from Indian PLI-backed facilities.
Pricing Analysis
Capacity additions in India are reshaping price floors for food-grade carbonate and sulfate grades, displacing legacy import dependence from European refiners. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels segments buyers by certification overhead, with FSSAI-mandated procurement from domestic producers showing lowest price sensitivity. Cost compression in technical-grade material is intensifying because of energy-intensive calcination exposure to natural gas volatility. Contract manufacturers in Maharashtra exhibit highest price sensitivity; Swiss nutraceutical formulators least.
Supply Chain Analysis
Phosphate rock supply rests on Moroccan and Western Saharan reserve concentration, creating single-source vulnerability for calcium phosphate downstream. Limestone feedstock draws from Rajasthan and Madhya Pradesh quarries for Indian domestic production, while synthetic carbonate production is anchored in German and Dutch ECHA-registered facilities. Tariff exposure runs through EU REACH compliance costs for Asian synthetic sourcing. Distribution runs through direct procurement relationships between mineral refiners and mid-sized functional food startups, fragmenting legacy distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as FSSAI fortification mandates and EFSA clean-label benchmarks shift procurement toward bioavailability-certified chelated grades over commodity oxide formats.
For Market Incumbents: Anticipate potassium chloride volume displacement as sodium-reduction mandates accelerate across North American and European processed food reformulation. Defensive consolidation moves center on backward integration into Rajasthan limestone quarries under FSSAI traceability mandates, and pre-certification of glycinate complex production for Swiss and German human nutrition channels. Margin pressure from energy-intensive calcination exposure demands renewable energy infrastructure investment. For New Entrants and Emerging Players: Nano-dispersion technology for beverage suspension systems offers a technology-first wedge into ready-to-drink functional beverage fortification, where 12-month sedimentation stability commands specification-grade contracts. White-space targets concentrate on direct procurement relationships with California and Massachusetts plant-based dairy analog startups, and PLI-scheme manufacturing capacity near Ahmedabad for export-oriented food-grade sulfate production. Go-to-market positioning emphasizes technical partnership over transactional supply. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration friction excludes non-compliant Asian synthetic mineral sources from European pharmaceutical and formulated food supply chains. Long-term viability favors acquisition targets with captive chelation technology and ECHA-registered production infrastructure. The signal to watch is FSSAI expansion of mandatory fortification to additional staple commodities beyond current iron, zinc, and calcium mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | FSSAI traceability mandates in Rajasthan secure feedstock provenance for food-grade carbonate production. |
| Chelated Mineral Technology Licensing | Glycinate and bisglycinate complex patents from Swiss specialty suppliers displace traditional oxide grades in premium human nutrition. |
| Renewable Energy Infrastructure Retrofit | EU F-Gas Regulation compliance for refrigeration-dependent calcination facilities favors low-carbon thermal operations near Rotterdam. |
| Direct Procurement Channel Development | Bypassing legacy distributors to California beverage startups accelerates formulation partnership cycles for nano-dispersed suspensions. |
| PLI-Linked Capacity Expansion | Production-linked incentives near Mumbai and Ahmedabad attract greenfield investment in export-oriented food-grade mineral salt manufacturing. |
Methodological Framework
Multiple input streams — technical R&D directors at chelated mineral specialists, procurement leads at functional food manufacturers, distribution channel partners in North Rhine-Westphalia, and plant managers at Gujarat fluidized bed coating facilities — were reconciled against secondary validation from FSSAI fortification circulars, ECHA REACH substance evaluation protocols, SEC 10-K filings of listed mineral ingredient producers, and customs data on carbonate and sulfate trade flows. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Data-stream reconciliation across product type, end-use industry, form specification, and source origin dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro mineral consumption trends. Industry-specific forecast inputs incorporated FSSAI mandate implementation timelines and EFSA bioavailability benchmark evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phosphate rock geopolitical disruption, natural gas price volatility affecting calcination economics, and REACH authorization scope expansion for novel chelating agents. A small set of named triggers — FSSAI commodity expansion, ECHA SVHC candidate list updates, and PLI scheme renewal terms — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Selenium Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Global Fabricated Metal Products Market
Metals & Minerals
Chromite Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Precious Metals E-Waste Recovery Market