
 Natural Industrial Absorbents Market | 2026-2036
Natural Industrial Absorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Industrial Absorbents Market Analytics
Industrial distribution through MRO supply houses is fragmenting as direct-to-factory e-commerce platforms capture specification-driven buyers. Oil-Dri Corporation of America anchors its position through captive mineral reserves in Georgia and Mississippi. Monarch Green differentiates via biodegradable coir formulations targeting food-grade facilities. New Pig Corporation competes through private-label spill kit assembly and same-day fulfillment from its Pennsylvania distribution center.
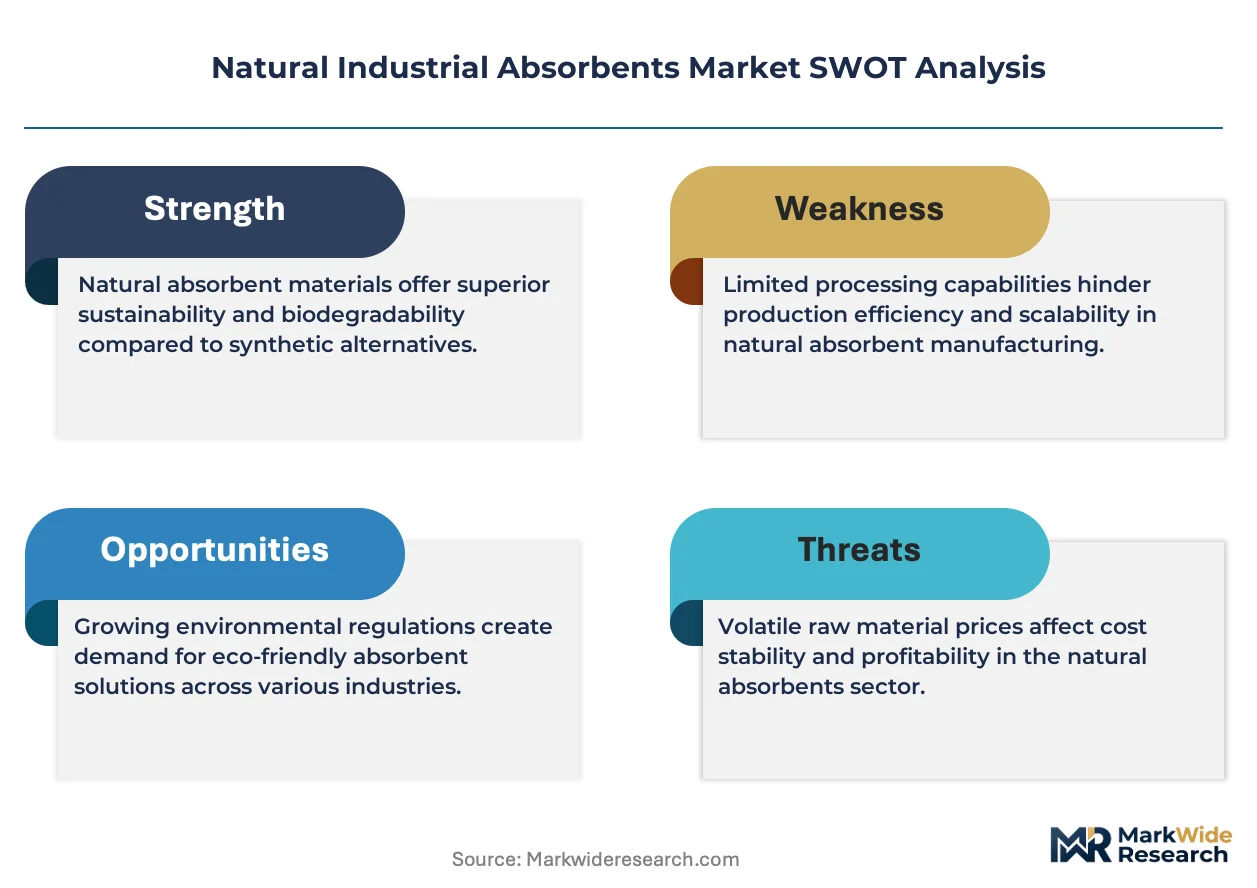
Natural industrial absorbents comprise plant-derived or animal-fiber materials engineered to immobilize hydrocarbons, aqueous solutions, and chemical vapors through capillary action and oleophilic surface chemistry, with bulk densities typically ranging from 0.05 to 0.25 g/cm³ depending on substrate porosity. Cellulose-based pads dominate unit volume in manufacturing maintenance applications where OSHA compliance mandates rapid fluid immobilization. Coir granules represent the fastest-expanding material category as tropical fiber processing achieves cost parity with peat moss alternatives. Oil & Gas end users command premium pricing for offshore-certified absorbents meeting EPA SPCC secondary containment thresholds.
EPA enforces SPCC rules that mandate facility-specific spill prevention plans, while OSHA 1910.1200 governs hazard communication for absorbent deployment in chemical exposure scenarios. REACH restrictions on synthetic polymer microplastics redirect European procurement toward cellulose and wool substrates certified under EU Ecolabel criteria. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could impose post-use recovery obligations on absorbent distributors.
Market Dynamics
EPA SPCC rule enforcement and OSHA 1910.1200 compliance mandates are compressing specification cycles as facilities replace synthetic sorbents with cellulose and coir alternatives to avoid regulatory penalties.
Growth Catalysts
- OSHA Workplace Safety Standards:Chemical processing plants in the United States face intensified inspection protocols for spill response readiness, accelerating absorbent inventory turnover and bulk purchasing volumes.
- EU Ecolabel Certification:Automotive suppliers across Germany's manufacturing corridor now mandate biodegradable absorbent solutions for factory floor maintenance protocols to meet sustainability procurement criteria.
- Coir Fiber Processing Cost Parity:Tropical fiber supply chains in Sri Lanka and India have achieved production economics matching peat moss alternatives, unlocking volume expansion in food-grade facility applications.
Market Restraints
- Coconut Husk Supply Concentration:Coir granule production depends on monsoon-dependent harvests concentrated in Kerala and Tamil Nadu, exposing processors to raw material availability shocks.
- REACH Microplastic Restrictions:Synthetic polymer displacement creates technical performance gaps in high-volume aqueous chemical absorption where cellulose swells inadequately.
- Mineral Reserve Access:Attapulgite and diatomite mining permits in Georgia and Mississippi face environmental review delays, constraining domestic bentonite-based absorbent expansion.
Strategic Opportunities
- Offshore Oil & Gas Certification:EPA SPCC secondary containment thresholds for marine platforms create premium pricing tiers for absorbents meeting Bureau of Safety and Environmental Enforcement standards.
- Direct-to-Factory E-Commerce:Specification-driven buyers bypass MRO distributors through digital platforms offering technical documentation and same-day fulfillment from regional warehouses.
- Extended Producer Responsibility Frameworks:California and Washington state legislation proposes post-use recovery obligations that would favor biodegradable substrates over synthetic alternatives in government procurement.
Industry Challenges
- Absorbent Performance Standardization:ASTM F726 test protocol variations across laboratories create specification mismatches between manufacturers and industrial buyers, elongating qualification timelines.
- Legacy Inventory Integration:Facilities with existing synthetic sorbent contracts face contract termination penalties and disposal costs when transitioning to natural alternatives, slowing adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Industrial Absorbents Market |
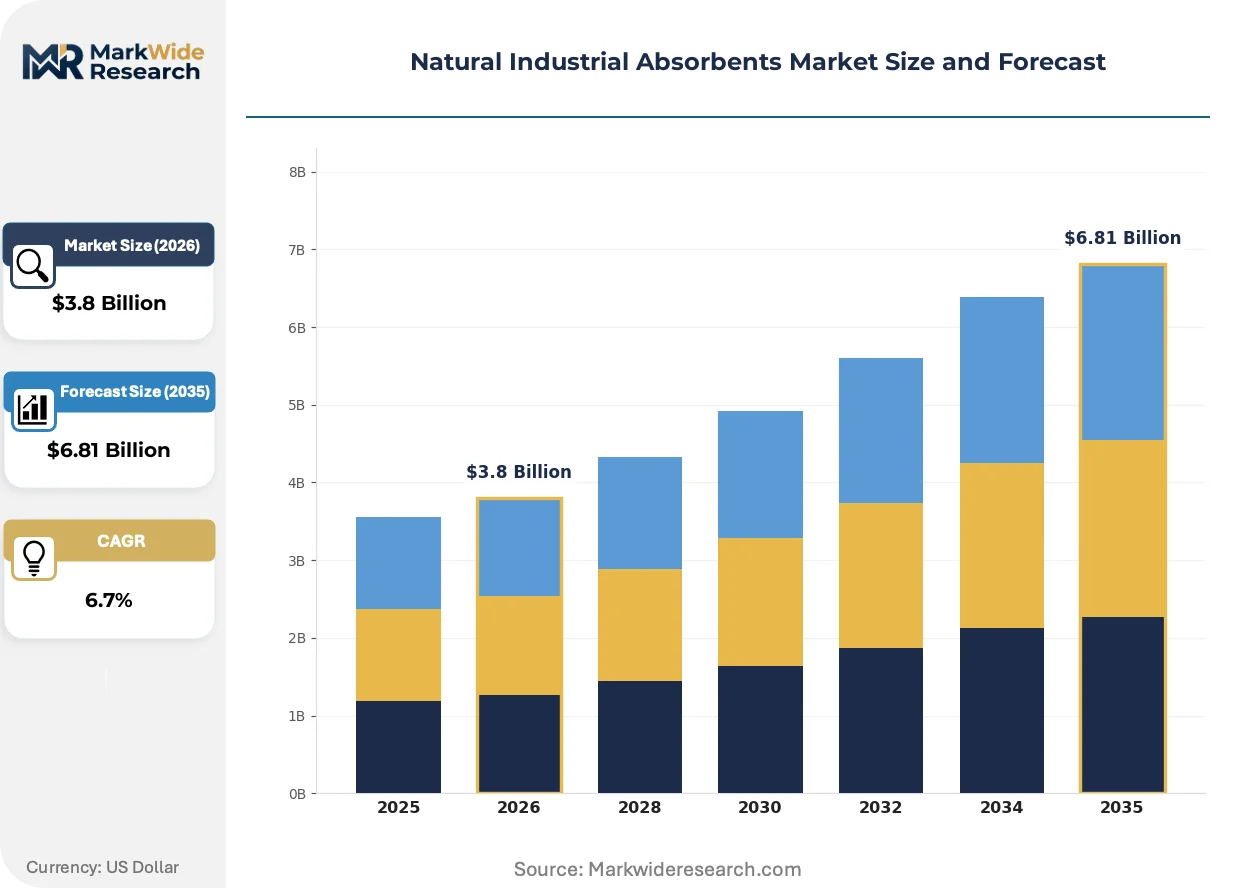
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spill Kits, Absorbent Pads, Absorbent Rolls, Granules Material: Coir, Peat, Cellulose, Wool Application: Oil Spills, Water Leaks, Chemical Cleanup, Industrial Maintenance End User: Manufacturing, Construction, Oil & Gas, Transportation |
| Companies Covered | Monarch Green, New Pig Corporation, Oil-Dri Corporation of America, Kimberly-Clark Professional, Brady Corporation, Tolsa, 3M, Meltblown Technologies Inc., Green Boom Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Industrial Absorbents Market Evolving Landscape
Sensor-integrated spill detection systems are converging with absorbent deployment protocols, compressing response times and reshaping how facilities specify passive containment versus active monitoring solutions.
Capacitive moisture sensing embedded in cellulose pad arrays is digitizing spill response workflows in chemical processing plants. Facilities in Texas and Louisiana are piloting these systems to trigger automated inventory replenishment before saturation thresholds compromise containment. The technology is digitizing maintenance scheduling by replacing visual inspection cycles with real-time saturation telemetry.
REACH restrictions on synthetic polymer microplastics redirect European procurement toward cellulose and wool substrates certified under EU Ecolabel criteria. ECHA enforcement actions against polypropylene sorbent manufacturers have accelerated qualification timelines for natural alternatives in German automotive supplier networks. Food-grade facilities in Bavaria now require biodegradable documentation traceable to fiber harvest origin.
Maintenance managers increasingly specify absorbents through integrated supply platforms rather than traditional MRO distributor relationships. Direct procurement from manufacturers with technical specification databases is displacing catalog-based purchasing in Pennsylvania and Ohio manufacturing clusters. This behavioral shift concentrates in automotive supplier networks where just-in-time floor protocols demand precise delivery synchronization.
Natural Industrial Absorbents Market Segmentation
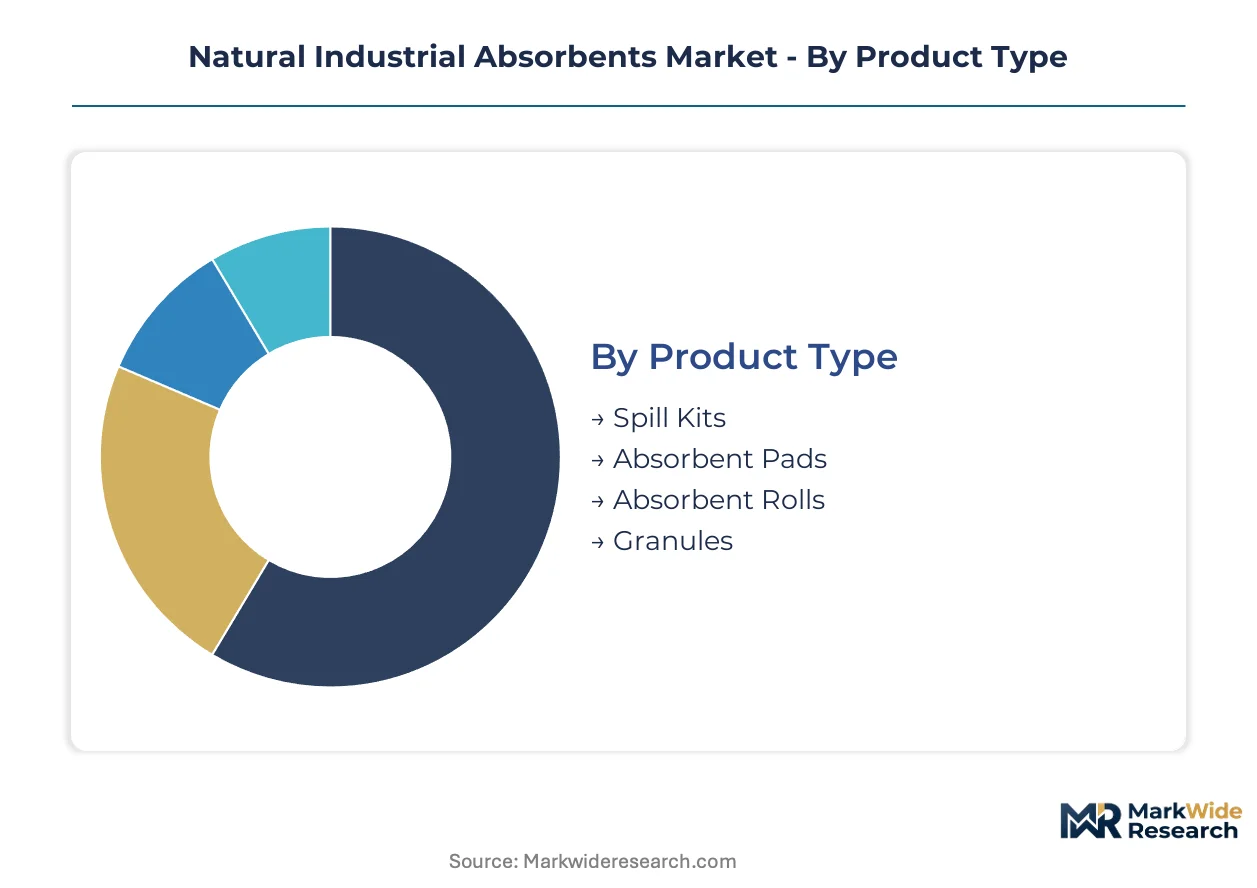
Natural industrial absorbents serve divergent performance requirements across spill response scenarios. Specification buyers prioritize absorption capacity, biodegradability, and regulatory compliance when matching product formats to contamination type. Segmentation reveals where material innovation and procurement concentration are reshaping competitive positioning.
Product Type:
Format selection tracks deployment velocity and containment scale demanded by facility protocols.
- Spill Kits:Pre-configured response packages combine pads, socks, and disposal bags for rapid deployment. Chemical processing plants in Texas and Louisiana mandate kit certification under EPA SPCC secondary containment thresholds, driving specification standardization.
- Absorbent Pads:Cellulose-based sheets engineered for hydrocarbon immobilization through oleophilic surface chemistry dominate manufacturing maintenance applications. OSHA workplace safety standards in the United States compress replacement cycles as facilities stockpile compliant inventory.
- Absorbent Rolls:Continuous-format substrates enable custom-length deployment across conveyor systems and production lines.
- Granules:Loose-particulate formats deliver bulk coverage for large-area containment in outdoor industrial yards.
Absorbent pads command the established base. The steepest expansion runs through spill kits.
Material:
Substrate economics and regional supply availability determine procurement feasibility for specification buyers.
- Coir:Tropical fiber from coconut husk processing achieves cost parity with peat alternatives. German automotive suppliers now mandate biodegradable coir formulations for factory floor protocols under EU Ecolabel procurement criteria.
- Cellulose:Recycled paper pulp substrates deliver high surface-area absorption at lowest unit cost. Manufacturing facilities across Pennsylvania and Ohio specify cellulose pads for high-volume maintenance schedules where rapid turnover dominates cost calculus.
- Peat:Moss-derived granules retain established positioning in legacy industrial applications.
- Wool:Animal-fiber absorbents serve niche food-grade and pharmaceutical containment scenarios.
Cellulose anchors volume leadership. Coir climbs the fastest as tropical supply chains mature.
Application:
Contamination chemistry dictates absorbent selection and disposal protocol complexity.
- Oil Spills:Hydrocarbon-specific absorbents require oleophilic-hydrophobic properties for marine and industrial deployment. Offshore platforms in the Gulf of Mexico command premium pricing for Bureau of Safety and Environmental Enforcement certification.
- Chemical Cleanup:Acid and solvent containment demands substrate compatibility verification. REACH microplastic restrictions redirect European procurement toward cellulose and wool alternatives certified under ECHA enforcement frameworks.
- Water Leaks:Aqueous-fluid absorption prioritizes swell capacity and structural integrity during saturation.
- Industrial Maintenance:General-purpose protocols absorb mixed-fluid contamination in manufacturing environments.
Oil spill response commands the established base. Chemical cleanup gains share fastest as regulatory scrutiny intensifies.
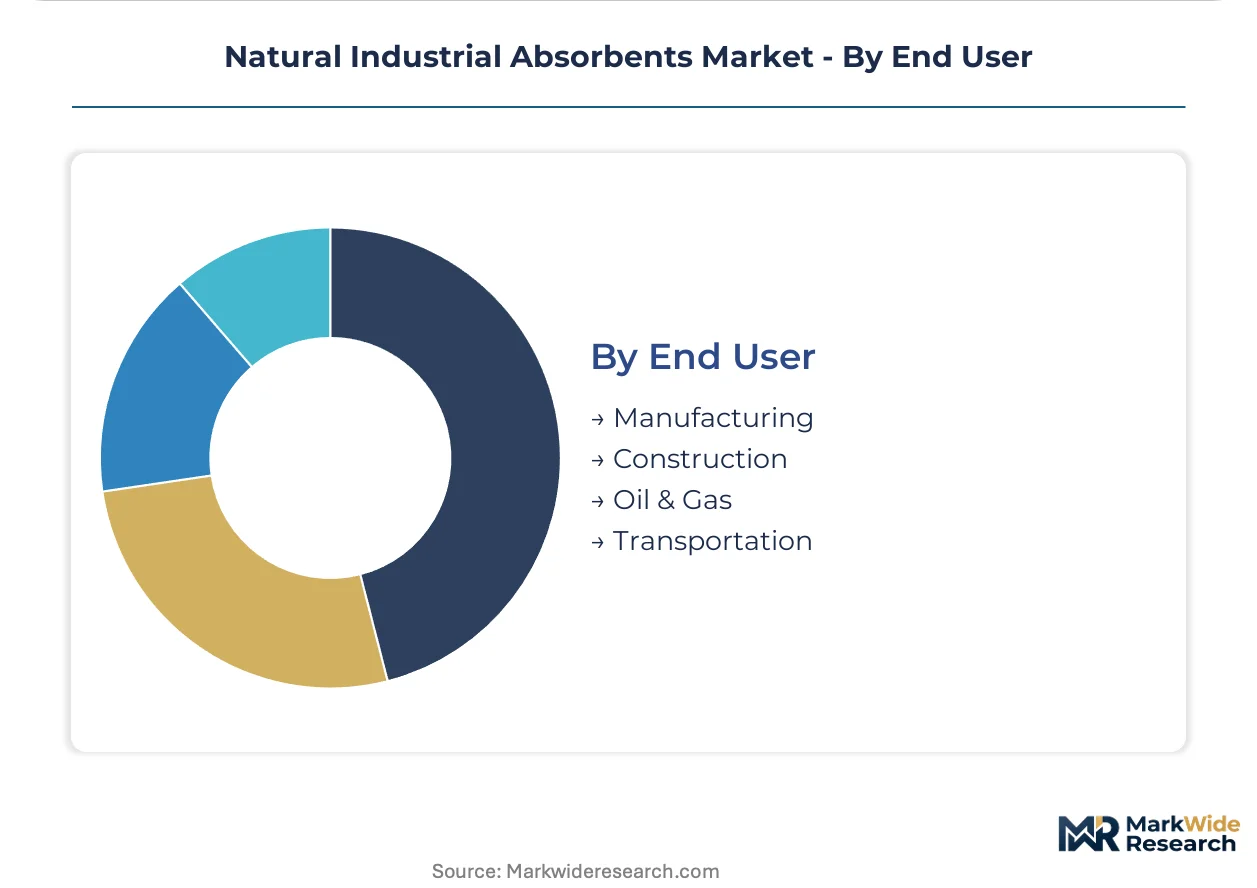
End User:
Industry-specific hazard profiles and compliance mandates drive specification divergence across buyer segments.
- Oil & Gas:Upstream and midstream operations face the most stringent containment requirements. EPA SPCC rule enforcement and BSEE offshore standards create premium pricing tiers for certified absorbents in Texas, Louisiana, and Alaska production zones.
- Manufacturing:Automotive supplier networks across Germany's manufacturing corridor mandate biodegradable solutions. Just-in-time floor protocols in Bavaria require precise delivery synchronization and origin-traceable fiber documentation.
- Construction:Site-based spill response addresses fuel and hydraulic fluid leakage during equipment operation.
- Transportation:Fleet maintenance and terminal operations require portable containment for mobile contamination scenarios.
Manufacturing commands the established base. Oil & Gas delivers the steepest pricing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing for offshore-certified absorbents in the United States runs 40-60% above comparable products in India, where domestic coir processing clusters compress margins. This asymmetry reflects divergent regulatory stringency and end-user specification requirements across major demand centers.
United States
EPA SPCC rule enforcement and BSEE offshore standards drive specification intensity in Texas and Louisiana production zones. OSHA 1910.1200 mandates compress replacement cycles for manufacturing facilities. The Gulf Coast petrochemical corridor commands premium pricing for Bureau of Safety and Environmental Enforcement-certified absorbents deployed on marine platforms.
Germany
Automotive supplier networks across Bavaria mandate biodegradable absorbent solutions under EU Ecolabel procurement criteria. REACH restrictions on synthetic polymer microplastics redirect procurement toward cellulose and wool substrates. The manufacturing corridor stretching from Stuttgart to Munich requires origin-traceable fiber documentation for just-in-time floor protocols.
China
Dual carbon goals and MEE environmental enforcement accelerate displacement of synthetic sorbents in coastal manufacturing zones. Yangtze River Delta chemical processors face intensified spill prevention inspections. Shanghai and Ningbo port authorities are piloting biodegradable containment standards for bulk liquid handling operations.
India
Kerala and Tamil Nadu coir processing clusters achieve production economics matching peat moss alternatives. CDSCO and BIS standards for industrial safety equipment create compliance thresholds for food-grade facility applications. The Kochi-Alappuzha fiber belt supplies German automotive networks with EU Ecolabel-certified granules.
Canada
Health Canada and PMRA environmental standards govern absorbent deployment in Alberta oil sands and British Columbia marine terminals. The country's national spill response framework mandates biodegradable alternatives for federal procurement contracts. Vancouver and Prince Rupert port authorities specify cellulose-based protocols for tanker loading operations.
Natural Industrial Absorbents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and substrate advantages. The vendor base organizes around three strategic archetypes: mineral reserve holders with captive sourcing, biodegradable formulators with tropical fiber supply chains, and private-label assemblers with distribution velocity. Consolidation pressure concentrates among mid-scale processors lacking either raw material control or technical certification depth. Dominant competitive moves include backward integration into fiber harvesting and strategic partnerships with automotive supplier networks.
Among North American mineral reserve holders, Oil-Dri Corporation of America exemplifies the captive-sourcing archetype through its Georgia and Mississippi deposit positions. Monarch Green occupies a position within the biodegradable formulation tier, while New Pig Corporation anchors the private-label assembly and fulfillment segment. These three patterns represent the structural options available to specification buyers navigating compliance mandates.
| Leading Market Players |
|---|
| Monarch Green |
| New Pig Corporation |
| Oil-Dri Corporation of America |
| Kimberly-Clark Professional |
| Brady Corporation |
| Tolsa |
| 3M |
| Meltblown Technologies Inc. |
| Green Boom Corp. |
| Others |
Value Network & Pricing Analysis
Monsoon-dependent coconut husk harvests in Kerala and Tamil Nadu expose coir granule processors to raw material availability shocks that simultaneously widen pricing spreads between certified and uncertified grades and force buyers toward cellulose alternatives with more stable feedstock economics.
Pricing Analysis
The customization-premium spread separates standard cellulose pads from Bureau of Safety and Environmental Enforcement-certified absorbents for offshore platforms. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in standard cellulose grades is intensifying because recycled paper pulp feedstock competition from packaging sectors tightens supply. Chemical processing plants in Texas and Louisiana exhibit the highest price sensitivity due to bulk purchasing volumes, while Oil & Gas offshore operators accept premium pricing for regulatory compliance assurance.
Supply Chain Analysis
Supplier-financing facilities from Sri Lankan coir cooperatives have extended payment terms to 90 days for German automotive buyers qualifying under EU Ecolabel procurement criteria. Geographic supply concentration centers on India, the United States, and Germany for distinct substrate categories. Raw material dependencies draw from Georgia and Mississippi attapulgite deposits, Kerala coconut husk fiber belts, and recycled paper pulp streams anchored in Pennsylvania and Ohio. Single-source vulnerability in tropical fiber harvesting creates exposure to climate-driven supply interruptions. Distribution runs through direct-to-factory e-commerce platforms displacing traditional MRO supply house relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by EPA SPCC enforcement waves that periodically force synthetic-to-natural absorbent replacement cycles.
For Market Incumbents: Pre-empt coir supply chain disruption by securing backward integration into Kerala fiber processing cooperatives before monsoon volatility triggers competitor stockpiling. Anchor capacity addition in Mississippi attapulgite corridors to defend against mineral reserve access delays from environmental review bottlenecks. Certification investment in Bureau of Safety and Environmental Enforcement offshore standards creates switching costs that lock in Oil & Gas procurement relationships.
For New Entrants and Emerging Players: Mid-market food-grade facilities in Bavaria represent the most penetrable entry point given origin-traceable documentation requirements that incumbent mineral reserve holders struggle to satisfy. Direct-to-factory e-commerce platforms with same-day fulfillment from regional warehouses offer a go-to-market angle that bypasses entrenched MRO distributor relationships and captures specification-driven buyers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biodegradable formulators with tropical fiber supply chains over mineral reserve holders facing environmental permit uncertainty. Long-term viability over a 5-10 year window rests on EU Ecolabel certification depth and automotive supplier network integration. The signal to watch is California and Washington state extended producer responsibility legislation that would redirect government procurement toward biodegradable substrates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Harvesting | Captive coir supply from Kerala cooperatives insulates processors from monsoon-driven availability shocks. |
| EU Ecolabel Certification Investment | German automotive supplier networks mandate biodegradable documentation traceable to fiber harvest origin. |
| Direct-to-Factory E-Commerce Platform Launch | Specification-driven buyers in Pennsylvania and Ohio manufacturing clusters bypass traditional MRO distributors. |
| Offshore Oil & Gas Certification Program | Bureau of Safety and Environmental Enforcement standards command premium pricing in Gulf of Mexico platforms. |
| Extended Producer Responsibility Partnership | California and Washington state legislation favors biodegradable substrates in government procurement contracts. |
Research Methodology
A standing panel of plant managers, procurement leads at chemical processing facilities, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA SPCC enforcement records, OSHA compliance inspection databases, EU Ecolabel certification registries, and customs trade data for cellulose and coir substrate flows. Bottom-up facility-level demand estimation triangulated against top-down market sizing from absorbent consumption intensity metrics.
Scenario-bracketing around regulatory enforcement intensity and tropical fiber harvest variability bounded projections across the analysis window. Segmentation dimensions modeled include product format, material substrate, contamination chemistry, and end-user industry vertical. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle compression from compliance mandates. Industry-specific forecast inputs incorporated Bureau of Safety and Environmental Enforcement certification adoption curves and EU REACH microplastic restriction implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, chemical plant capital expenditure cycles, or pulp commodity pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and fiber supply chain maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Injection Molding Market
Industrial Materials
Fly Ash Market
Industrial Materials
Pre-Painted Steel Coil Market