
 Calcined Alumina Market | 2026-2036
Calcined Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Alumina Market Analytics
EU REACH regulation on substance registration and downstream chemical safety is hardening compliance requirements for imported calcined alumina used in European ceramic and refractory applications. Hindalco Industries leverages captive bauxite reserves and integrated refining to sustain cost leadership across Asian supply corridors. Showa Denko specializes in ultra-high-purity grades for semiconductor ceramics, positioning its product line above commodity tiers. Almatis controls a broad geographic manufacturing footprint that anchors its service to European and Middle Eastern refractory producers.
Calcined alumina consists of alpha-aluminum oxide produced by controlled thermal decomposition of aluminum hydroxide at temperatures exceeding 1,000°C, yielding hardness values near 9 on the Mohs scale and purity levels from 99.0% to 99.8% depending on end-use specifications. White fused alumina commands premium positioning in abrasive and precision polishing applications where friability and grain shape determine performance. Reactive alumina represents the fastest-expanding product category as advanced ceramics and electronics substrates require sub-micron particle distributions with controlled sintering behavior. Tabular alumina retains structural dominance in high-temperature refractory linings for steel and cement kilns where thermal shock resistance governs material selection.
EPA emissions standards under the Clean Air Act shape calciner operating permits and flue-gas treatment investments across United States production sites. REACH registration obligations and CE marking requirements for abrasive products govern market access into European downstream channels. China's GB standards and Ministry of Ecology and Environment enforcement direct local calcination efficiency upgrades and particulate discharge limits. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional purity certification protocols to align capacity investments with shifting compliance frontiers.
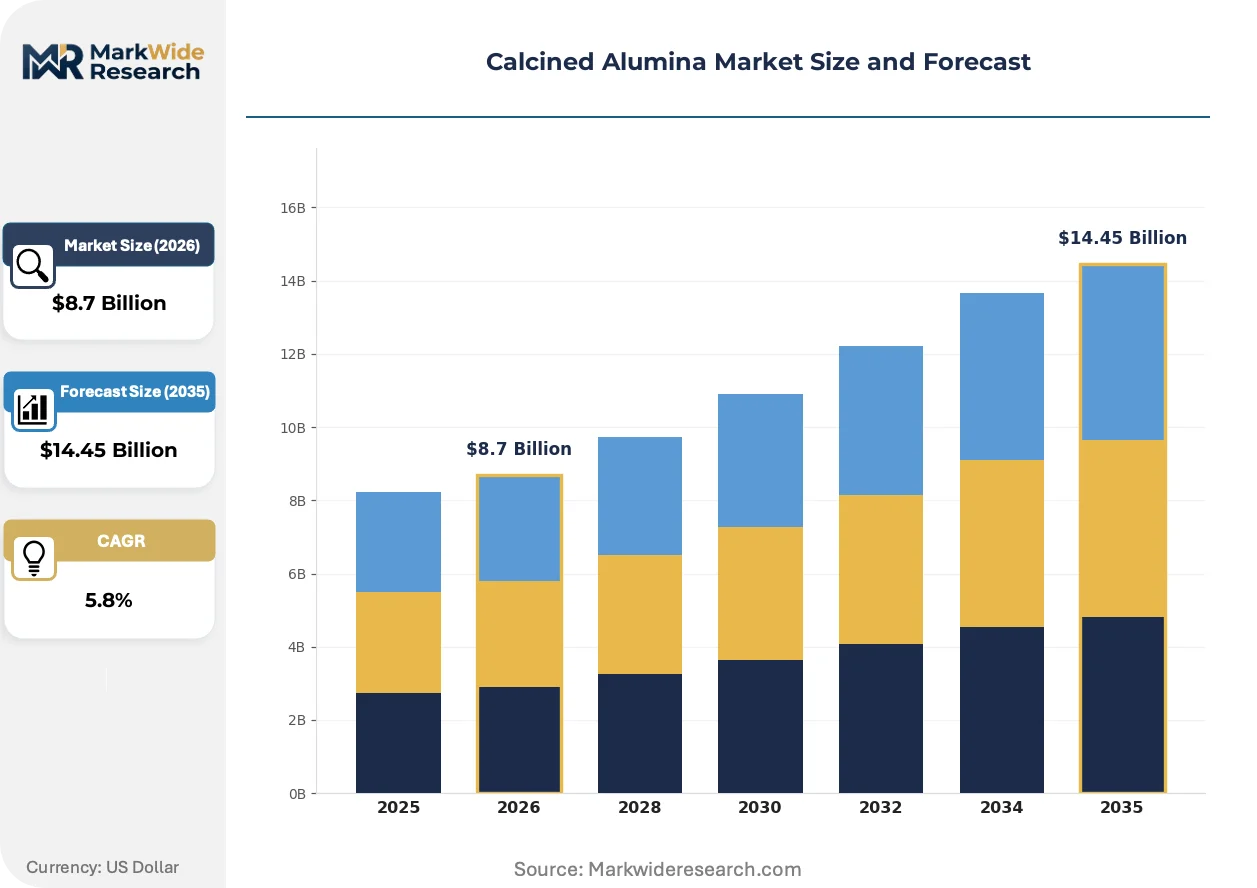
Market Dynamics
Integrated alumina-to-ceramic supply chains in China are compressing procurement timelines for refractory manufacturers while REACH compliance and EPA emissions thresholds force calciner technology upgrades across North America and Europe.
Growth Catalysts
- Semiconductor substrate demand:Advanced ceramics for chip packaging require sub-micron reactive alumina with controlled sintering behavior, pulling high-purity grades into electronics manufacturing.
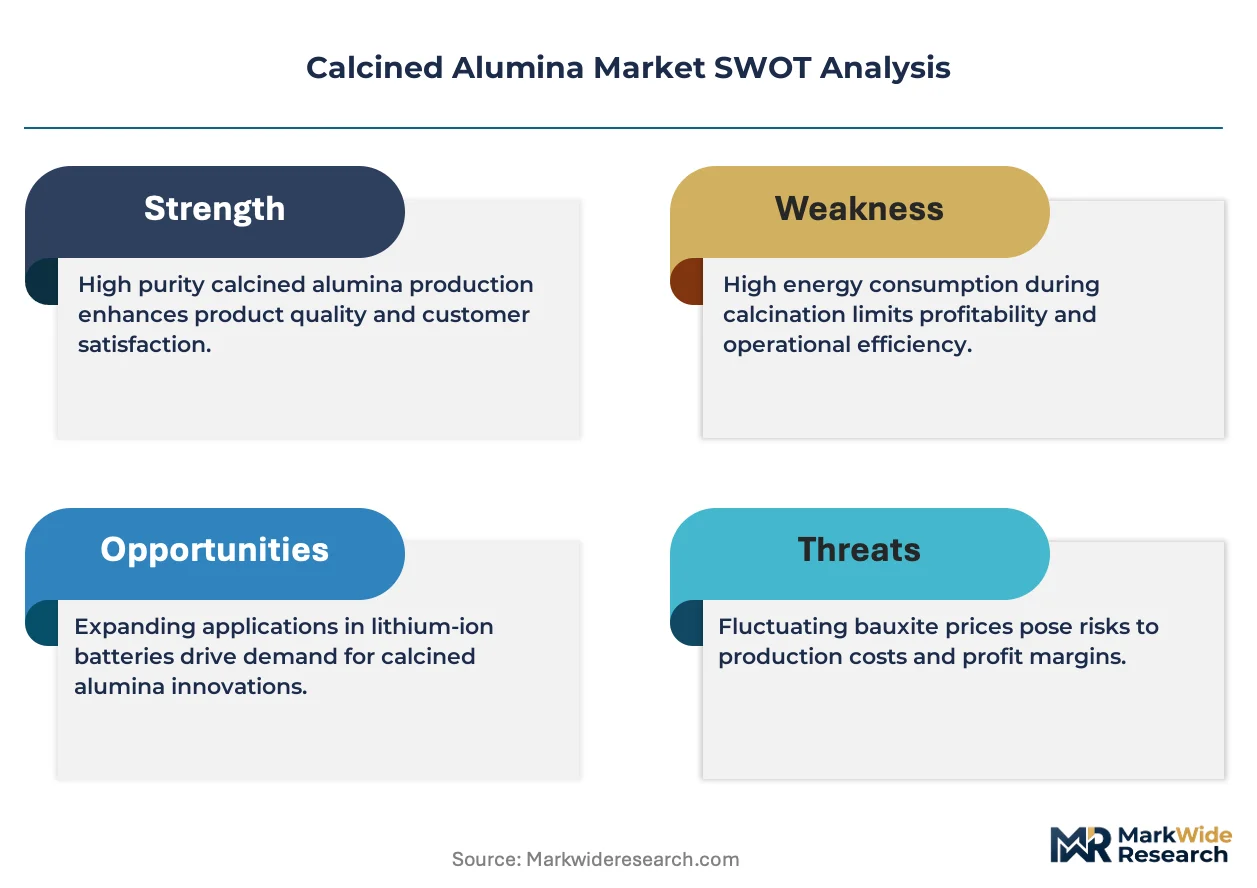
- REACH registration obligations:European downstream chemical safety mandates are hardening compliance requirements for imported calcined alumina used in ceramic and refractory applications.
- Steel industry refractory consumption:Tabular alumina retains structural dominance in high-temperature linings for steel and cement kilns where thermal shock resistance governs material selection.
Market Restraints
- Bauxite supply concentration:Captive bauxite reserves in Guinea, Australia, and Brazil create input cost volatility for non-integrated refiners lacking upstream control.
- Energy intensity of calcination:Thermal decomposition exceeding 1,000°C consumes natural gas and electricity at rates that amplify exposure to regional energy price spikes.
- Fused alumina substitution:White fused alumina commands premium positioning in abrasive applications where friability and grain shape determine performance, limiting calcined alumina penetration.
Strategic Opportunities
- India refractory expansion:Domestic steel capacity growth under PLI scheme incentives creates localized demand for cost-competitive tabular alumina supply.
- Carbon border adjustment mechanisms:EU CBAM implementation rewards low-carbon calcination processes, creating competitive advantage for facilities with renewable energy integration.
- 3D printing ceramic feedstocks:Reactive alumina with controlled particle distributions is modularizing into additive manufacturing workflows for complex component geometries.
Industry Challenges
- Flue-gas treatment capex:EPA Clean Air Act compliance and MEE particulate discharge limits in China require multi-million dollar scrubber and baghouse installations at existing calciners.
- Purity certification timelines:CE marking requirements for abrasive products and semiconductor-grade material qualification cycles extend customer onboarding to 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Alumina Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Fused Alumina, Brown Fused Alumina, Tabular Alumina, Reactive Alumina Application: Abrasives, Ceramics, Refractories, Polishing Compounds End User: Aerospace, Automotive Components, Electronics, Energy Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Hindalco Industries, Showa Denko, Almatis, Zibo Yishengjia Aluminum, CHALCO, Alteo, Nabaltec, National Aluminum Company Limited, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Alumina Market Evolving Landscape
Process intensification and digital quality control are compressing batch-to-batch variation while regulatory carbon accounting is reshaping energy sourcing decisions across calcination facilities.
Flash calcination technology is modularizing traditional rotary kiln workflows by enabling continuous thermal decomposition with residence times under two seconds. Refractory manufacturers in Germany and Japan are adopting these systems to reduce fuel consumption per ton. The structural consequence is compressing capital requirements for new capacity entry while tightening specifications for alpha-alumina crystal phase consistency.
EPA emissions standards under the Clean Air Act are mandating continuous emissions monitoring systems and selective catalytic reduction retrofits at United States production sites. The industrial consequence is elevating operating costs for legacy facilities while advantaging greenfield installations with integrated pollution controls. Steel and cement kiln refractory suppliers in the Midwest and Gulf Coast regions are responding by consolidating procurement around certified low-emission alumina sources.
Direct mill relationships are displacing traditional distributor channels as large ceramic manufacturers seek batch traceability and technical service integration. European advanced ceramics producers are negotiating long-term offtake agreements that bundle material supply with sintering parameter optimization. This pattern is most visible in Germany's industrial ceramics cluster around Cologne and Hoechst.
Calcined Alumina Market Segmentation
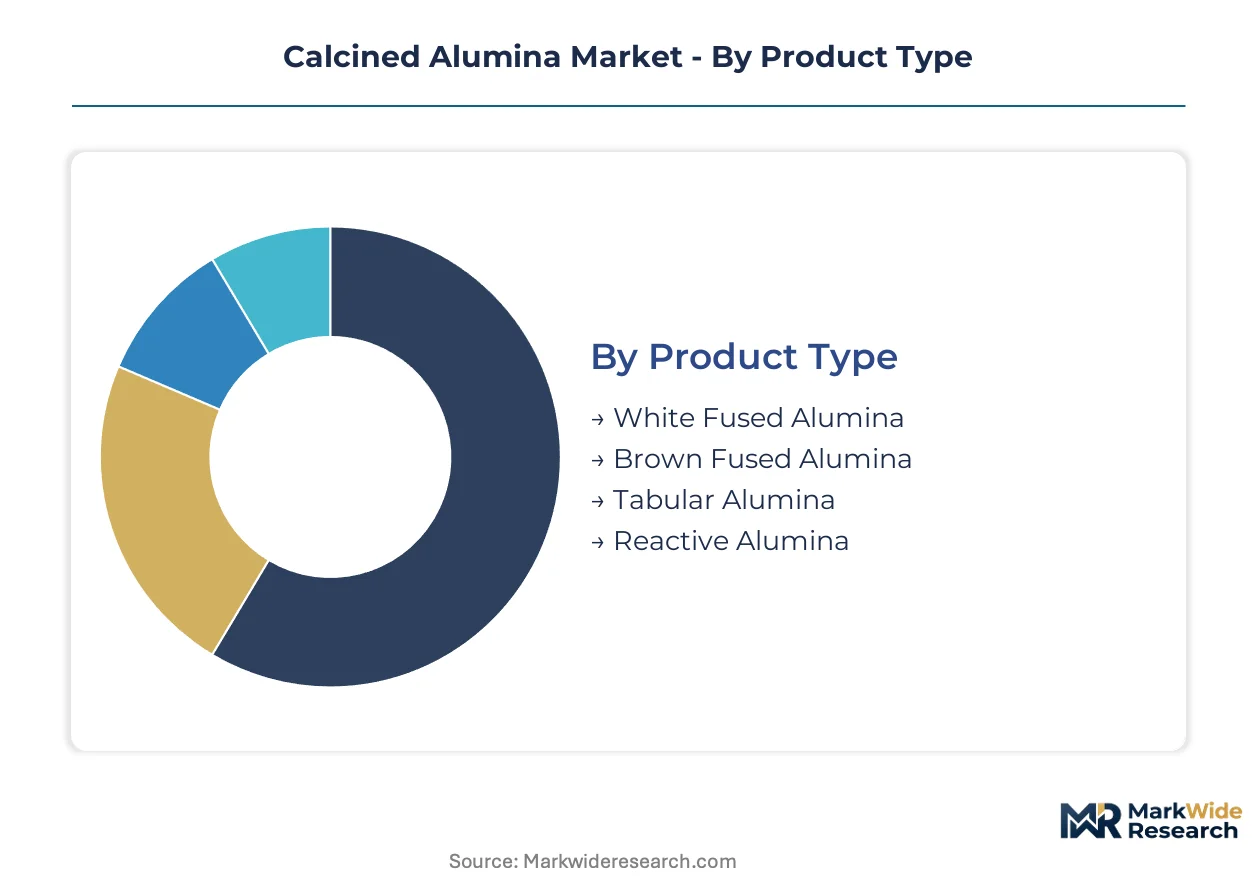
Calcined alumina producers configure product lines around thermal processing intensity and crystal phase control. Specification differentiation determines pricing tiers and customer qualification requirements across ceramic, abrasive, and refractory channels.
Product Type:
Supply concentration in high-purity grades favors integrated refiners with captive bauxite and in-house calcination capacity.
- White Fused Alumina:Electric-arc furnace processing above 2,000°C yields monocrystalline structure with hardness near 9 on the Mohs scale. Precision polishing and bonded abrasive manufacturers in Germany and Japan specify this grade for grain shape consistency and controlled friability.
- Reactive Alumina:Sub-micron particle distributions with controlled sintering behavior serve advanced ceramics and semiconductor substrate fabrication. Electronics manufacturers in South Korea and Taiwan are pulling high-purity reactive grades into chip packaging workflows.
- Brown Fused Alumina:Bauxite-coke fusion produces toughness-optimized grains for heavy-duty grinding wheels and sandblasting media.
- Tabular Alumina:Sintered alpha-alumina spheres deliver thermal shock resistance for steel and cement kiln refractory linings.
Tabular alumina absorbs the bulk of installed capacity; reactive alumina is expanding most quickly.
Application:
Cost tier separation between commodity abrasives and specification-critical ceramics drives divergent margin structures.
- Refractories:High-temperature linings for steel and cement kilns consume volume-intensive tabular grades where thermal shock resistance governs material selection. Integrated Chinese supply chains compress procurement timelines for Asian steel producers.
- Ceramics:Advanced component fabrication requires sub-micron reactive alumina with batch-to-batch consistency for sintering parameter control. German industrial ceramics clusters around Cologne negotiate long-term offtake agreements bundling material supply with technical service.
- Abrasives:Bonded and coated abrasive manufacturers balance grain toughness against friability for grinding efficiency.
- Polishing Compounds:Precision surface finishing applications specify white fused alumina for controlled particle geometry.
Refractories anchor volume demand; ceramics is climbing the fastest on semiconductor substrate pull-through.
End User:
Customer type fragmentation across heavy industry and precision manufacturing segments creates divergent sales cycle dynamics.
- Electronics:Semiconductor packaging and substrate manufacturers qualify reactive alumina through 12-18 month material certification cycles. South Korean chip foundries are consolidating procurement around traceable high-purity supply.
- Automotive Components:Ceramic brake pads and exhaust system substrates specify calcined alumina for thermal stability under cyclic loading.
- Aerospace:Ceramic matrix composites and thermal protection systems require ultra-high-purity grades with documented impurity profiles.
- Energy Sector:Solid oxide fuel cell manufacturers and nuclear ceramic producers specify controlled sintering behavior.
Electronics commands premium pricing; automotive components is gaining share fastest on brake pad ceramicization trends.
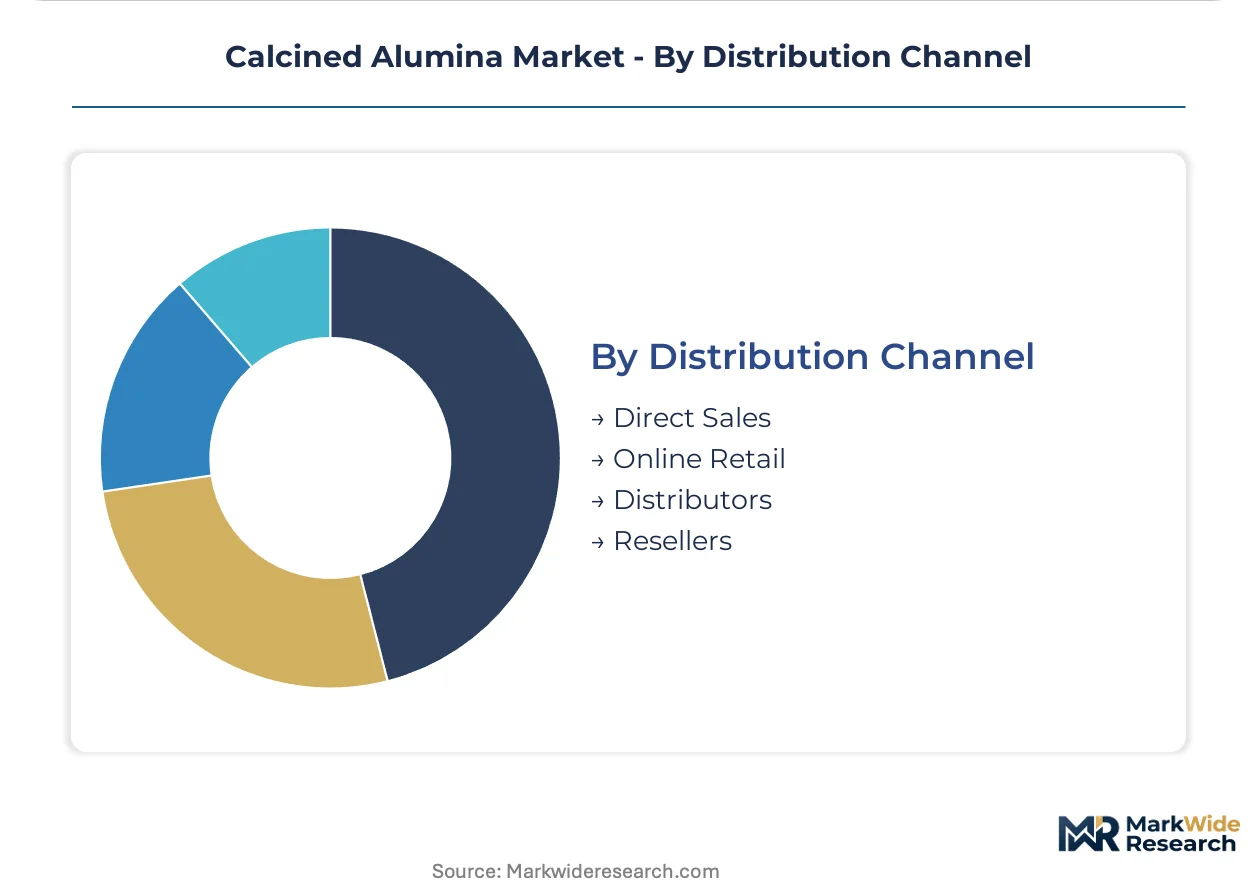
Distribution Channel:
Volume concentration in direct mill relationships is displacing traditional distributor intermediaries for specification-critical grades.
- Direct Sales:Large ceramic and refractory manufacturers negotiate long-term offtake agreements with calciner technical service integration. European advanced ceramics producers bundle sintering parameter optimization with material supply contracts.
- Distributors:Regional stockists serve fragmented abrasive and polishing compound manufacturers with standardized grades and shorter lead times.
- Online Retail:Small-volume specialty grades and R&D quantities move through digital procurement platforms.
- Resellers:Independent traders handle spot market volumes and geographic arbitrage for commodity grades.
Direct sales captures the majority of high-purity volume; online retail is expanding most quickly for R&D and pilot-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial corridor concentrates China's calcined alumina calcination capacity, with integrated alumina-to-ceramic supply chains serving domestic refractory manufacturers and export channels.
China
Steel industry refractory consumption and semiconductor substrate fabrication pull high-purity reactive alumina through Shandong and Henan provinces. MEE particulate discharge limits and dual carbon goals force calciner efficiency upgrades. Zhengzhou and Zibo industrial clusters anchor tabular alumina production for cement kiln lining applications.
United States
EPA Clean Air Act compliance costs elevate operating thresholds for legacy calciners in the Midwest and Gulf Coast regions. Continuous emissions monitoring systems and selective catalytic reduction retrofits reshape capital allocation. Ohio and Louisiana host refractory-grade alumina processing tied to steel and petrochemical customer bases.
Germany
Advanced ceramics manufacturers in the Cologne-Hoechst cluster negotiate long-term offtake agreements bundling reactive alumina supply with sintering parameter optimization. REACH registration obligations and CE marking requirements harden market access for imported material. North Rhine-Westphalia anchors European high-purity grade specification and technical service integration.
India
Domestic steel capacity expansion under PLI scheme incentives creates localized demand for cost-competitive tabular alumina. BIS standards and CEA power sector regulations shape calciner energy sourcing decisions. Odisha and Gujarat industrial corridors leverage captive bauxite reserves for integrated refining-to-ceramics output.
Japan
Semiconductor packaging and precision polishing applications specify ultra-high-purity reactive and white fused alumina grades. METI industrial policy and JIS standards govern material qualification cycles for electronics manufacturers. Kyushu and Kansai regions concentrate advanced ceramics R&D and chip substrate fabrication demand.
Calcined Alumina Market Competitive Landscape
The competitive structure tilts toward integrated bauxite-to-alumina refiners with captive raw material control. Tiered differentiation separates commodity-grade suppliers from specification-critical high-purity specialists serving semiconductor and aerospace channels. Three archetypes dominate: integrated mining-refining conglomerates with upstream bauxite reserves; specialty chemical producers focusing on sub-micron reactive grades; and regional refractory-grade processors optimizing logistics proximity to steel and cement customers. Capacity expansion and backward integration into bauxite mining represent the dominant competitive moves across Asian supply corridors.
Among integrated Asian conglomerates, Hindalco Industries and CHALCO exemplify the upstream-controlled archetype leveraging captive bauxite reserves across Indian and Chinese supply corridors. Specialty-grade positioning is occupied by Showa Denko, which represents the ultra-high-purity tier serving semiconductor ceramics qualification requirements. European market presence is anchored by Almatis, sitting within the geographically diversified processor tier with manufacturing footprints spanning multiple continents to service refractory producer clusters.
| Leading Market Players |
|---|
| Hindalco Industries |
| Showa Denko |
| Almatis |
| Zibo Yishengjia Aluminum |
| CHALCO |
| Alteo |
| Nabaltec |
| National Aluminum Company Limited |
| Sumitomo Chemical |
| Others |
Value Network & Pricing Analysis
Flash calcination technology adoption across German and Japanese refractory manufacturers is compressing capital requirements for new capacity entry while simultaneously intensifying price competition in standardized grades. This production-method transition concentrates margin pressure on legacy rotary kiln operators unable to achieve comparable fuel efficiency, reshaping competitive economics across European and Asian supply corridors.
Pricing Analysis
Yield-based pricing anchors semiconductor-grade reactive alumina contracts, where sub-micron particle consistency directly determines chip packaging throughput. Three-tier pricing structure across premium, standard, and economy levels separates qualification-critical electronics grades from commodity refractory tiers. Cost compression in standard-grade tabular alumina is intensifying because Chinese integrated producers leverage captive bauxite reserves. Abrasive manufacturers exhibit highest price sensitivity, while semiconductor foundries prioritize batch traceability over unit cost.
Supply Chain Analysis
Skilled kiln operator availability constrains expansion timelines across Shandong and Henan provinces, where MEE enforcement has elevated technical hiring requirements. Supply concentrates in China, Guinea, and Australia for bauxite feedstock, with India emerging as calcination capacity. The chain draws from captive mining, merchant refining, and toll calcination arrangements. Single-source vulnerability runs through Guinean bauxite corridors subject to export policy shifts. Distribution runs through direct mill relationships for specification-critical grades, regional stockists for commodity abrasives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions compliance costs and REACH registration obligations are forcing calciner technology upgrades that weaker, non-integrated players cannot fund, accelerating consolidation toward upstream-controlled conglomerates.
For Market Incumbents: Anticipate fused alumina substitution threats in precision polishing by deepening reactive alumina R&D for semiconductor substrate applications. Defensive consolidation moves should prioritize backward integration into Guinean or Australian bauxite reserves and flash calcination retrofits at legacy rotary kiln facilities to sustain cost parity with greenfield competitors. For New Entrants and Emerging Players: Enter via India's PLI-scheme steel capacity expansion, where localized tabular alumina demand outpaces domestic calcination supply. White-space targets include 3D printing ceramic feedstocks requiring controlled particle distributions and carbon-border-adjustment-compliant low-carbon grades for EU refractory procurement. Go-to-market angle should bundle technical service with material supply contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty-grade positioning, where semiconductor ceramics qualification creates durable moats. Long-term viability favors integrated bauxite-to-alumina refiners with renewable energy integration and captive raw material control. Acquisition target archetype: regional refractory-grade processors in India or Southeast Asia lacking upstream integration. Signal to watch: EU CBAM implementation timeline accelerating low-carbon capacity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive Guinean or Australian reserves insulate Hindalco and CHALCO from merchant feedstock volatility. |
| Flash Calcination Technology Deployment | German and Japanese refractory manufacturers reduce natural gas consumption per ton through sub-two-second residence times. |
| Long-term Offtake Agreement Structuring | Cologne-Hoechst ceramics clusters bundle reactive alumina supply with sintering parameter optimization services. |
| Semiconductor Grade Qualification Investment | Showa Denko's 12-18 month certification cycles create switching costs for South Korean chip foundries. |
| Renewable Energy Integration Program | EU CBAM rewards low-carbon calcination processes, advantaging facilities with solar or wind power sourcing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving calciner plant managers, refractory procurement leads at steel manufacturers, ceramic R&D directors, and distribution channel partners across German, Chinese, and Indian supply corridors. Specific sources included EPA Clean Air Act enforcement databases, ECHA REACH registration records, China Customs export statistics, and SEC 10-K disclosures from integrated mining-refining conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation from end-use industry associations.
Granularity-level modeling deployed product-grade tier, end-use industry, and regional production hub dimensions at the country level across the projection horizon. Analytical framework derived CAGRs from historical shipment trajectories, capacity utilization rates, and substitution elasticity estimates for fused alumina alternatives. Industry-specific forecast inputs incorporated semiconductor wafer start projections from chip foundry capex announcements and steel refractory consumption intensity per ton of crude output.
Revisions become necessary when EPA emissions threshold tightening, EU carbon border adjustment mechanism scope expansion, or Guinean bauxite export policy shifts materialize. Forecasts reflect documented assumptions regarding energy price trajectories, regulatory enforcement intensity, and qualification cycle durations. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Diatomite Market
Ceramics
Thermal Spray Powder Market
Ceramics
North America Activated Alumina Market
Ceramics
Ceramic Frit Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Calcined Bauxite Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Ceramic Substrate Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Ball Clay Market
Ceramics
White Fused Alumina Market
Ceramics
Advanced Ceramics Market