
 Gold Recycling Market | 2026-2036
Gold Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Gold Recycling Market Insights
Buyer consolidation among consumer electronics OEMs is repositioning collection channel economics across the gold recycling value chain. Umicore leverages its integrated refining and materials technology platform to capture value from complex electronic waste streams. Heraeus anchors its competitive stance through deep specialization in high-purity precious metals recovery for industrial applications. Aurubis competes by extending its copper smelting infrastructure into polymetallic scrap processing, lowering unit recovery costs for contained gold.
Gold recycling recovers metallic gold from end-of-life products and manufacturing residues through pyrometallurgical, hydrometallurgical, or electrolytic processes, typically achieving purities from 99.5% to 99.99% depending on downstream application requirements. The output serves as a critical input for luxury goods fabrication, semiconductor bonding wire, and investment-grade bullion, substituting for mined supply where provenance and carbon footprint matter. Electronic waste dominates volume throughput among source types due to rising device obsolescence rates and regulatory collection mandates, while jewelry scrap contributes disproportionately to margin pools because of higher gold content and simpler metallurgy. Hydrometallurgical extraction is gaining share among processing methods as refiners seek to limit emissions from pyrometallurgical smelting and handle lower-grade feedstock economically.
The EPA oversees hazardous waste classification for spent electronics in the United States, while the EU's WEEE Directive and REACH framework govern collection targets and chemical restrictions across European member states. Japan's METI enforces home appliance recycling quotas that directly mobilize gold-bearing scrap into licensed recovery channels. Stakeholders must monitor how carbon border adjustments and chain-of-custody certification requirements reshape feedstock access and refining economics across jurisdictions.
Market Dynamics
Refinery investment is redirecting toward traceable supply chains as the EU's Conflict Minerals Regulation and tightening due-diligence standards reshape feedstock access economics. Small-scale aggregators in Gujarat cluster now compete with integrated multinationals for jewelry scrap flows.
Growth Catalysts
- Conflict Minerals Regulation:The EU's due-diligence mandate is redirecting refinery capital toward certified supply chains, expanding traceable feedstock premiums.
- Electronics obsolescence:Rising device turnover rates under Japan's METI recycling quotas are mobilizing gold-bearing scrap into licensed recovery channels.
- Hydrometallurgical extraction:This lower-emission processing method is gaining share as refiners seek to handle lower-grade feedstock economically.
Market Restraints
- Pyrometallurgical emissions:Smelting-based recovery faces escalating carbon border adjustment exposure and permitting friction.
- Gujarat cluster concentration:Small-scale Indian refiners dominate jewelry scrap aggregation, creating supply bottleneck risk.
- Copper smelter competition:Polymetallic infrastructure at copper majors compresses unit recovery costs for contained gold.
Strategic Opportunities
- Semiconductor bonding wire:High-purity recovery for electronics interconnects represents underpenetrated premium demand.
- India's PLI scheme:Domestic manufacturing incentives are expanding jewelry fabrication residue availability for local refiners.
- Blockchain traceability:Chain-of-custody certification convergence with refining operations unlocks ethical sourcing premiums.
Industry Challenges
- Assay standardization:Variable scrap grading across small-scale collectors complicates feedstock valuation and contract terms.
- Hydrometallurgical capex:Leaching circuit investments require extended payback periods against volatile gold lease rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gold Recycling Market |
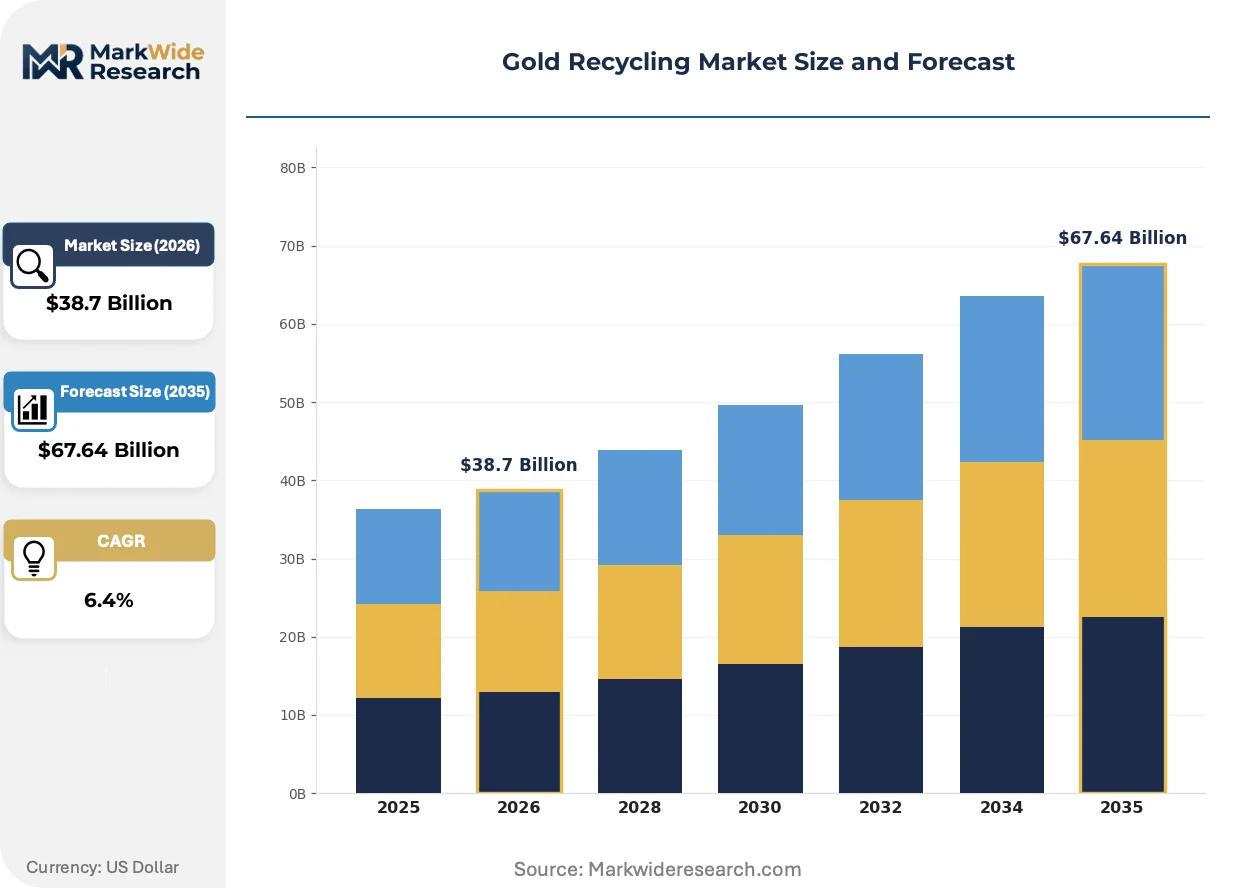
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Type: Electronic Waste, Jewelry Scrap, Industrial Scrap, Dental Scrap Processing Method: Chemical Leaching, Electrolytic Refining, Pyrometallurgical Smelting, Hydrometallurgical Extraction End Use Industry: Consumer Electronics, Aerospace Manufacturing, Precious Metals Trading, Luxury Goods, Scientific Instrumentation Collection Channel: Retailers, Scrap Dealers, Refineries, Authorized Collection Centers |
| Companies Covered | Sims Recycling Solutions, Valcambi, Umicore, PX Group, Heraeus, DONGSHENG Precious Metals Recycler, Aurubis, Materion, Tanaka Kikinzoku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gold Recycling Market Trends and Innovations
Hydrometallurgical recovery systems are absorbing capital allocation as environmental compliance costs reshape processing economics. Three distinct shifts are restructuring competitive positioning across the value chain.
Advanced leaching circuits using thiosulfate and chloride-based chemistries are absorbing market share from traditional smelting routes. Electronics refiners in East Asia are adopting these systems at accelerating pace to handle complex printed circuit board feedstock. The technology is absorbing margin pressure from carbon border adjustments while enabling economic recovery from sub-200 ppm gold grades.
REACH chemical restrictions and the EU's WEEE collection mandates are tightening material flow controls across European member states. Refiners must now document chain-of-custody through licensed collection networks rather than informal scrap channels. Germany and France are requiring third-party verification of recycled content claims for bullion investment products.
Buyer consolidation among consumer electronics OEMs is compressing collection channel margins and restructuring aggregator economics. Large manufacturers are internalizing reverse logistics for end-of-life devices, displacing independent e-waste collectors. This concentration is most visible in South Korean and Japanese appliance recycling quotas where METI enforcement directly mobilizes scrap into licensed recovery channels.
Gold Recycling Market Segmentation
Segmentation in gold recycling reveals how regulatory pressure and feedstock economics split value capture across distinct operational models. Each dimension carries specific compliance burdens and margin profiles that determine competitive positioning.
Source Type:
Certification requirements vary sharply across source categories, with conflict-mineral traceability mandates from the EU and EPA hazardous waste classifications governing electronic and industrial streams respectively.
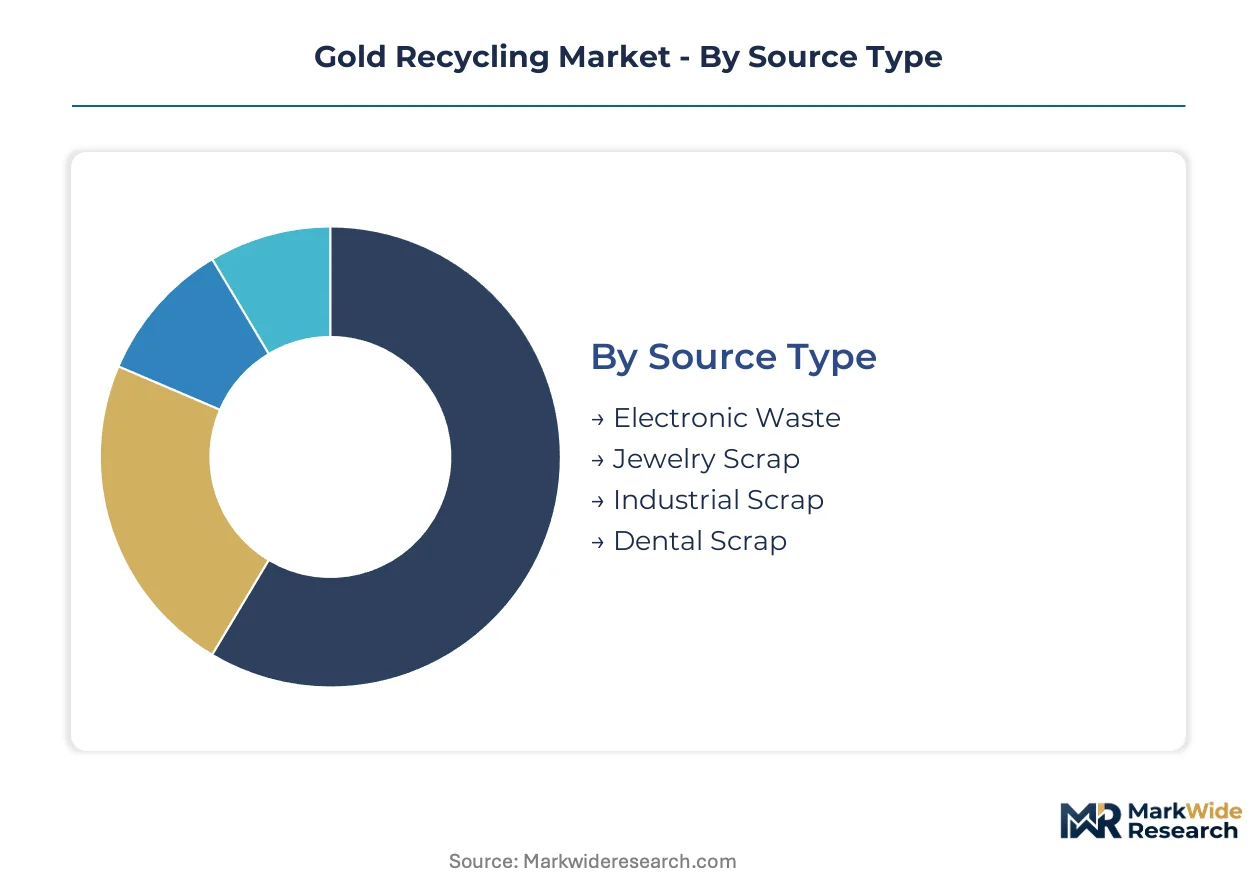
- Electronic Waste:Printed circuit boards and connectors contain 200-400 ppm gold alongside hazardous substrates. Japan's METI recycling quotas and EU WEEE collection mandates are concentrating investment in licensed recovery channels across East Asian and European processing hubs.
- Jewelry Scrap:High-karat manufacturing residues and end-of-life pieces yield simpler metallurgy with minimal hazardous content. India's Gujarat cluster dominates aggregation, with small-scale refiners competing on assay speed and domestic PLI scheme incentives.
- Industrial Scrap:Electroplating baths, semiconductor manufacturing sludge, and chemical process residues require specialized handling permits under EPA and REACH frameworks.
- Dental Scrap:Alloys containing gold, palladium, and platinum demand precious metals dealer licensing and dental waste disposal compliance.
Electronic waste sits at the top of the volume ranking, with jewelry scrap climbing the fastest as ethical sourcing premiums expand.
Processing Method:
Capital intensity and emissions exposure create distinct cost tiers across recovery technologies, with carbon border adjustments reshaping investment allocation.
- Hydrometallurgical Extraction:Thiosulfate and chloride-based leaching circuits handle sub-200 ppm grades economically while limiting Scope 1 emissions. German and French refiners are deploying these systems to meet CSRD disclosure requirements and avoid carbon border adjustment penalties.
- Pyrometallurgical Smelting:High-temperature reduction achieves 99.99% purity for bullion and bonding wire applications. Permitting friction and emissions compliance costs are compressing margins at legacy copper smelter complexes.
- Chemical Leaching:Acid-based dissolution targets specific metal complexes in mixed industrial residues, requiring ECHA REACH registration for reagent handling.
- Electrolytic Refining:Electrochemical deposition produces ultra-high purity for semiconductor interconnects, with BIS certification required for Indian electronics supply chain integration.
Hydrometallurgical extraction commands the steepest expansion trajectory, while pyrometallurgical smelting retains volume leadership in bullion-oriented output.
End Use Industry:
Application-specific purity standards and procurement specifications segment demand into distinct customer archetypes with diverging price sensitivity.
- Consumer Electronics:Bonding wire and connector plating demand 99.99% purity with documented chain-of-custody. South Korean and Taiwanese OEMs are consolidating reverse logistics to secure certified recycled feedstock.
- Luxury Goods:Jewelry and watch fabrication prioritizes provenance certification over marginal purity gains. Swiss and Italian manufacturers command premiums for blockchain-traceable recycled content.
- Precious Metals Trading:Bullion investment products require third-party verification of recycled content claims under German and French national standards.
- Aerospace Manufacturing:Thermal barrier coatings and electrical contacts specify exact alloy compositions with full material pedigree documentation.
- Scientific Instrumentation:Laboratory equipment and analytical standards demand ultra-trace impurity specifications.
Consumer electronics generates the largest volume call, with luxury goods delivering the strongest margin expansion.
Collection Channel:
Channel structure determines feedstock access economics, with regulatory licensing creating barriers that favor integrated operators over independent aggregators.
- Authorized Collection Centers:Licensed facilities under Japan's METI quotas and EU WEEE frameworks provide guaranteed volume flows with full documentation. South Korean electronics majors are internalizing these channels through captive reverse logistics networks.
- Scrap Dealers:Independent aggregators dominate jewelry scrap flows in India's Gujarat cluster, competing on assay speed and cash payment terms despite variable grading standards.
- Retailers:Jewelry and electronics retail networks offer consumer-facing collection with brand-aligned ethical sourcing narratives.
- Refineries:Integrated operators capture margin across collection and processing, with Umicore and Aurubis extending direct collection infrastructure for complex electronic waste streams.
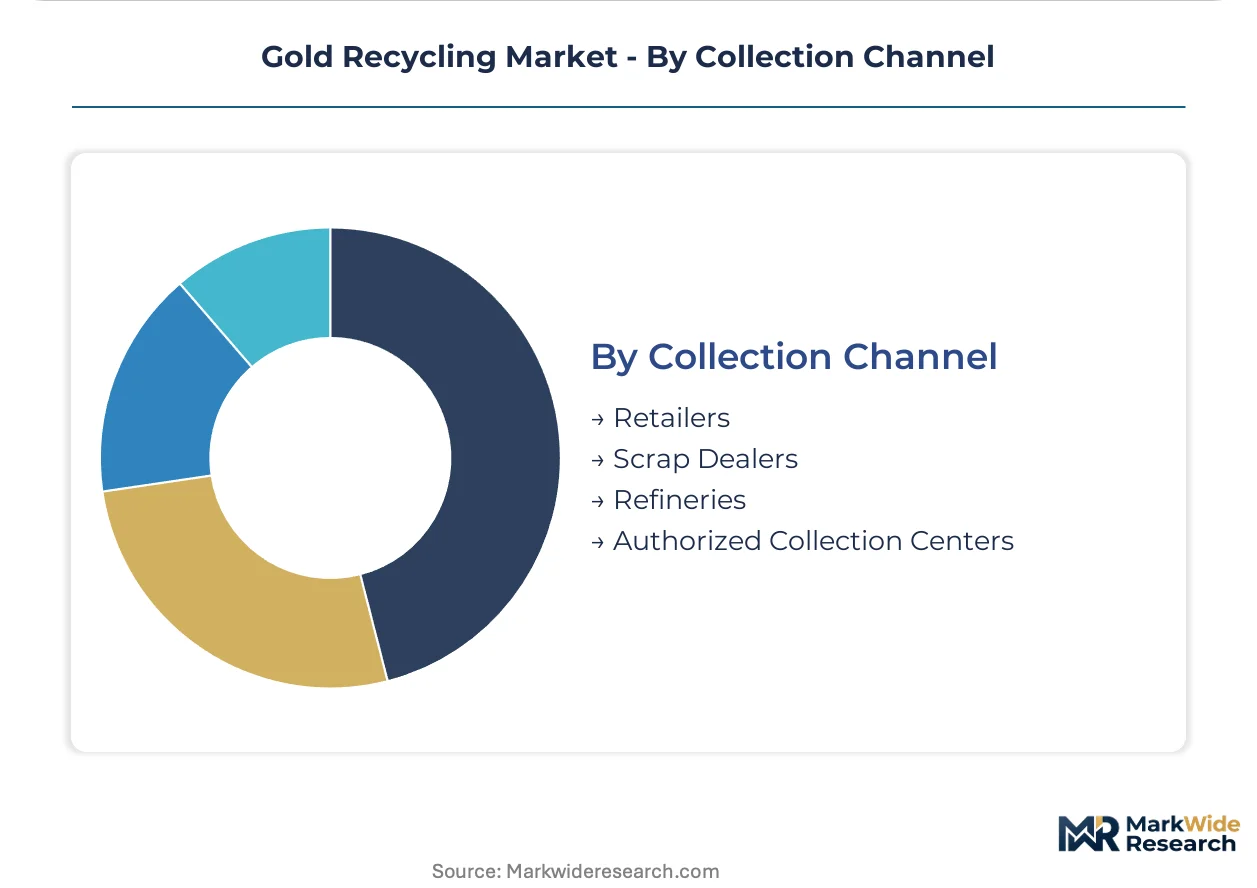
Authorized collection centers anchor volume throughput, with refinery-integrated channels gaining share fastest through backward integration into feedstock sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's refinery sector commands premium positioning through CSRD-aligned hydrometallurgical investments, while India's Gujarat cluster aggregates jewelry scrap through small-scale networks that compete on speed rather than scale.
United States
Electronics OEM reverse logistics and semiconductor manufacturing residues drive feedstock availability. The EPA classifies spent printed circuit boards as hazardous waste, channeling material toward licensed refiners. Texas and Arizona host copper smelter complexes that extend polymetallic recovery into gold-bearing industrial streams.
Germany
Bullion investment products and automotive electronics plating generate dual demand channels. The national standard mandates third-party verification of recycled content claims for precious metals trading. Saxony and North Rhine-Westphalia concentrate hydrometallurgical refinery capacity serving CSRD disclosure requirements.
India
Jewelry fabrication residue and domestic manufacturing incentives expand feedstock pools under the PLI scheme. BIS certification requirements govern electronics supply chain integration for recovered gold. Gujarat's small-scale refiners aggregate scrap through cash-payment networks that prioritize assay velocity over documentation depth.
Japan
Home appliance recycling quotas and consumer electronics obsolescence mobilize complex printed circuit board flows. METI enforcement directs gold-bearing scrap into licensed recovery channels with full chain-of-custody documentation. The Kanto region anchors processing infrastructure aligned with JIS standards for high-purity output.
Switzerland
Luxury watch fabrication and bullion trading create premium-grade demand with provenance sensitivity. The national precious metals framework requires dealer licensing and audit trails for dental and industrial scrap flows. The Ticino corridor concentrates refiners serving blockchain-traceable ethical sourcing premiums.
Gold Recycling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value capture tiers. The market structure concentrates around integrated materials technology platforms and copper smelter extensions, with mid-scale hydrometallurgical operators occupying niche positions. Three archetypes dominate: integrated refining-to-materials conglomerates, copper-based polymetallic processors, and high-purity precious metals specialists. Capacity expansion into licensed collection networks and backward integration into reverse logistics represent the dominant competitive vectors reshaping feedstock access economics.
Among integrated materials conglomerates, Umicore and Heraeus exemplify the technology-platform archetype, anchoring competitive positioning through combined refining and advanced materials capabilities. Aurubis occupies the copper-smelter extension tier, leveraging polymetallic infrastructure to compress unit recovery costs for contained gold in complex electronic waste streams. These three entities represent distinct strategic postures rather than interchangeable competitors, with each archetype capturing value from different feedstock complexity gradients and end-use purity requirements.
| Leading Market Players |
|---|
| Sims Recycling Solutions |
| Valcambi |
| Umicore |
| PX Group |
| Heraeus |
| DONGSHENG Precious Metals Recycler |
| Aurubis |
| Materion |
| Tanaka Kikinzoku |
| Others |
Pricing and Supply Chain Analysis
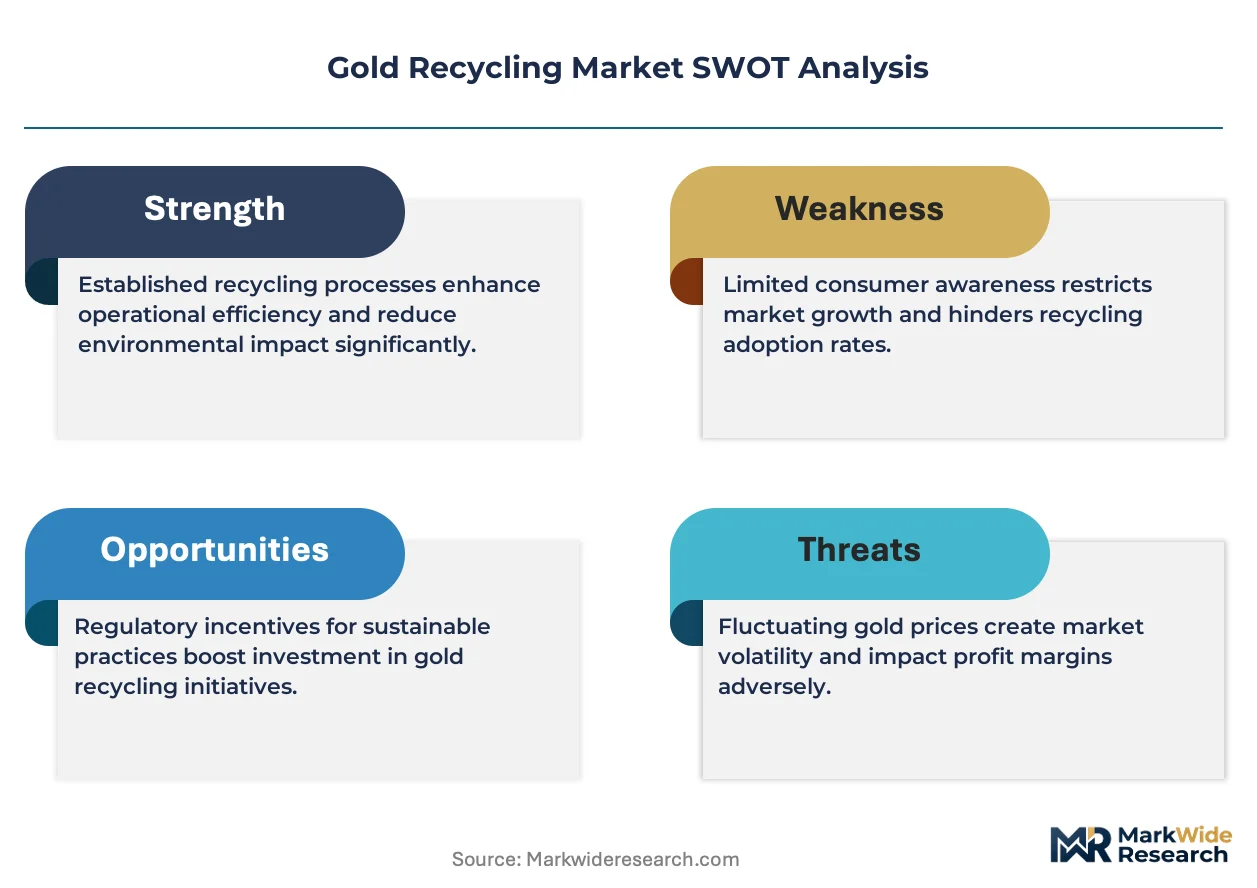
Carbon border adjustment exposure on pyrometallurgical smelting feeds through to premium tier pricing for hydrometallurgical output, with German and French refiners capturing ethical sourcing premiums while Gujarat's small-scale operators compete on assay velocity and cash terms.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for certified recycled bullion. Three-tier pricing structure across traceable premium, standard licensed, and informal economy levels segments buyers by documentation requirements. Price differentiation hinges on chain-of-custody certification depth and volume scale. Pricing pressure stems from copper smelter polymetallic competition compressing unit recovery costs. Electronics OEMs exhibit highest price sensitivity due to consolidated procurement power, while Swiss luxury goods manufacturers accept substantial premiums for blockchain-verified provenance.
Supply Chain Analysis
Chain-of-custody certification under EU Conflict Minerals Regulation and Japan's METI quotas gates feedstock access to licensed channels. Supply concentrates in India, Germany, and Japan as primary aggregation and refining hubs. Raw material flows draw from printed circuit board assemblies, jewelry manufacturing residues, and semiconductor electroplating sludge. Single-source vulnerability runs through Gujarat's small-scale aggregator networks for high-karat scrap. Distribution runs through authorized collection centers under WEEE frameworks, with refinery-integrated channels gaining fastest through backward integration into reverse logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gold recycling market represents a late-cycle quality story as semiconductor bonding wire and luxury provenance specifications command widening premiums over commodity bullion.
For Market Incumbents: To counter hydrometallurgical margin compression from carbon border adjustments, Umicore-class integrated platforms should deepen backward integration into licensed e-waste collection networks. Heraeus-type specialists must anchor capacity expansion in CSRD-aligned jurisdictions to sustain premium positioning. Certification investment in blockchain traceability systems secures ethical sourcing contract tiers. For New Entrants and Emerging Players: Launch via authorized collection center licensing under Japan's METI quotas or India's PLI scheme incentives. Semiconductor bonding wire recovery for South Korean and Taiwanese OEMs offers the most penetrable white-space target. Scrap dealer aggregation partnerships in underlicensed geographies provide the critical go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hydrometallurgical operators because assay standardization gaps and informal channel fragmentation create consolidation value. Five-to-ten year viability rests on carbon border adjustment trajectory and electronics OEM reverse logistics internalization pace. Acquisition targets should show licensed collection infrastructure and BIS or JIS certification pathways. The signal to watch is German and French national standard convergence on third-party recycled content verification.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | Thiosulfate leaching investments in Germany and Japan absorb carbon border adjustment exposure while handling sub-200 ppm grades. |
| Blockchain Traceability Integration | Chain-of-custody certification convergence with refining operations unlocks ethical sourcing premiums from Swiss luxury manufacturers. |
| Licensed Collection Network Buildout | Backward integration into METI and WEEE-authorized channels secures guaranteed volume flows with full documentation. |
| Semiconductor Bonding Wire Specialization | Electrolytic refining for 99.99% purity targets underpenetrated premium demand from South Korean and Taiwanese OEMs. |
| Gujarat Cluster Aggregation Partnerships | Assay standardization investments in India's small-scale refinery networks address supply bottleneck risk for jewelry scrap. |
Research Methodology
Direct dialogue with refinery operations directors, electronics OEM procurement leads, precious metals traders, and regulatory compliance officers grounded qualitative assessments in operational reality. Secondary validation drew from EPA hazardous waste classifications, EU WEEE collection mandate disclosures, METI recycling quota reports, and BIS certification databases. Bottom-up feedstock flow modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation outputs reflect source type, processing method, end use industry, and collection channel dimensions modeled throughout the forecast period. CAGRs were derived from feedstock availability projections, regulatory enforcement trajectory, and technology substitution curves for hydrometallurgical versus pyrometallurgical routes. Gold lease rate volatility and carbon border adjustment implementation pace served as key industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt carbon border adjustment acceleration or electronics OEM reverse logistics internalization. Model outputs reflect assumptions on regulatory enforcement consistency, technology cost curves, and feedstock grade degradation trends. A model refresh is warranted upon material change in EU Conflict Minerals Regulation scope or India PLI scheme jewelry fabrication incentive structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Cesium Market
Metals & Minerals
Selenium Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Garnet Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Nickel Mining Market