
 Balanced Salt Solution for Cell Culture Market | 2026-2036
Balanced Salt Solution for Cell Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Balanced Salt Solution for Cell Culture Market Outlook
Buyer concentration among contract research organizations is recalibrating procurement leverage across the supply base. Thermo Fisher Scientific Inc. leverages its distribution breadth to anchor shelf presence in North American academic laboratories. Lonza Group Ltd. sustains premium positioning through cGMP-compliant manufacturing infrastructure. Sigma-Aldrich Co. LLC differentiates via deep catalog breadth spanning classical and specialized salt formulations.
Balanced salt solution for cell culture constitutes a sterile, isotonic aqueous medium containing precise concentrations of inorganic salts, glucose, and buffering agents such as sodium bicarbonate or HEPES, manufactured under aseptic conditions to maintain physiological pH and osmolarity for mammalian cell maintenance. Its primary purpose spans short-term cell rinsing, dilution, and incubation in bioprocessing workflows where ionic equilibrium prevents osmotic shock. Dulbecco's PBS occupies the largest volume share due to universal compatibility with adherent and suspension cell protocols. Ready-to-use liquid formulations capture expanding share as biopharmaceutical companies eliminate in-house hydration steps to reduce contamination risk. Powder formats retain relevance in emerging markets where cold-chain logistics constrain liquid distribution economics.
FDA enforces current Good Manufacturing Practice standards for cell culture media used in therapeutic biologics production, compelling suppliers to maintain Drug Master Files and process validation documentation. EMA's Annex 1 revision on sterile manufacturing elevates environmental monitoring requirements for salt solution fill-finish operations. ISO 13485 certification increasingly gates supplier access to diagnostic device manufacturers integrating cell culture reagents into finished test kits. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and JP standards to anticipate reformulation obligations and qualification retesting costs.
Market Dynamics
Biopharmaceutical companies eliminating in-house powder hydration are consolidating procurement around sterile liquid formats, compressing supplier margins while elevating qualification barriers for fill-finish operations.
Growth Catalysts
- Cell-based therapy pipelines:CAR-T and regenerative medicine developers require cGMP-grade balanced salt solutions at clinical and commercial scale, pulling volume from research-grade suppliers.
- FDA Drug Master File requirements:Therapeutic biologics manufacturers must source from suppliers with validated DMFs, locking in qualified vendor relationships and reducing competitive churn.
- HEPES buffering adoption:CO2-independent formulations enable satellite manufacturing in facilities lacking controlled atmosphere infrastructure, expanding addressable production sites.
Market Restraints
- Pharmaceutical-grade raw material concentration:USP-grade sodium chloride and dibasic phosphate supply concentrates among three specialty chemical producers, exposing formulators to input cost volatility.
- EMA Annex 1 environmental monitoring:Revised sterile manufacturing guidelines mandate continuous viable particle detection in Grade A fill-finish zones, adding capital intensity to facility qualification.
- Lyophilized media substitution:Powdered balanced salt alternatives with extended ambient stability threaten liquid format economics in markets with underdeveloped cold-chain infrastructure.
Strategic Opportunities
- Indian biologics manufacturing expansion:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting multinational fill-finish investment requiring qualified salt solution supply.
- Point-of-care cell therapy production:Decentralized manufacturing models near treatment centers demand small-batch, patient-specific media logistics currently underserved by bulk distribution networks.
- ISO 13485 certification differentiation:Diagnostic device manufacturers integrating cell culture reagents into IVD kits require quality system alignment, creating premium positioning for certified suppliers.
Industry Challenges
- Aseptic processing technician scarcity:Grade A fill-finish operations require operators with validated gowning and intervention training, constraining capacity expansion timelines.
- Multi-pharmacopeial harmonization complexity:Divergent USP, EP, and JP monograph specifications for endotoxin and sterility testing force redundant qualification batches and extended release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balanced Salt Solution for Cell Culture Market |
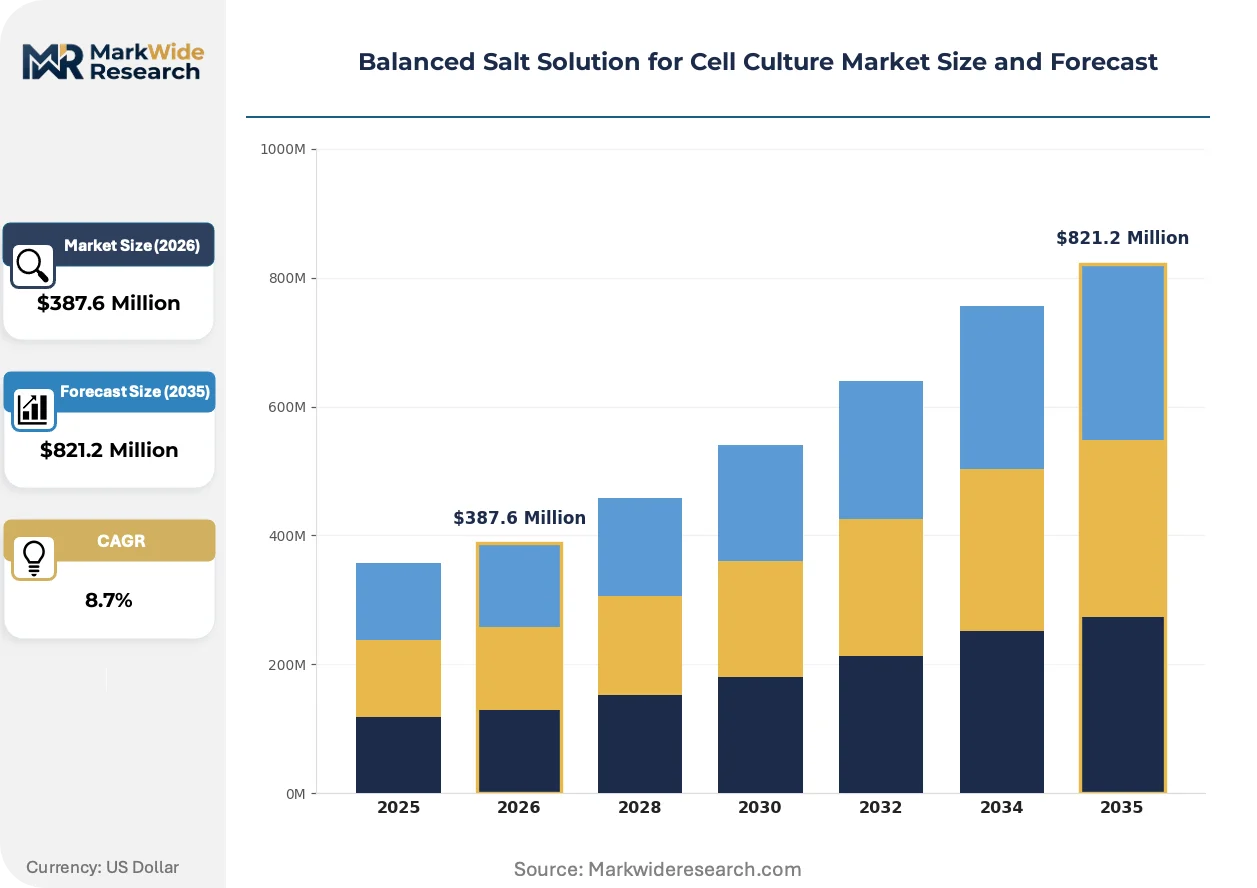
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dulbecco's PBS, Hanks' Balanced Salt Solution, Eagle's Minimal Essential Medium, Leibovitz's L-15 Usage Type: Cell Viability Testing, In Vitro Fertilization, Tissue Engineering, Drug Development Formulation Type: Liquid, Powder, Concentrate, Ready-to-use End User: Biopharmaceutical Companies, Research Laboratories, Academic Institutions, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza Group Ltd., Sigma-Aldrich Co. LLC, EMD Millipore, Corning Life Sciences B.V., PromoCell GmbH, Becton Dickinson & Co., Wheaton Industries Inc., Atlanta Biologicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balanced Salt Solution for Cell Culture Market Strategic Shifts
Ready-to-use sterile liquid formats are compressing powder reconstitution workflows while single-use connection technologies eliminate open-system interventions, fundamentally restructuring fill-finish economics and contamination risk profiles.
Closed-system aseptic filling technology is rewriting production floor layouts. Isolator-based lines with robotic decontamination cycles enable continuous operation without human intervention. Contract manufacturers in Germany and Massachusetts are retrofitting legacy suites to capture cell therapy media volumes. This compression of environmental exclusion technology is displacing conventional cleanroom architectures and elevating capital barriers for new entrants.
EMA's Annex 1 revision on sterile manufacturing mandates continuous viable environmental monitoring with alarm thresholds tied to intervention documentation. Fill-finish operators must now correlate every excursion to batch disposition decisions. European suppliers are investing in real-time microbial detection systems to preempt regulatory scrutiny. The compliance burden falls heaviest on multi-product facilities lacking dedicated cell culture media lines.
Consolidated procurement through group purchasing organizations is compressing supplier margins while elevating technical service expectations. Academic medical centers and mid-tier CROs now negotiate enterprise contracts spanning media, sera, and reagents. Thermo Fisher's channel density in North America captures this concentration, while smaller formulators retreat to specialty applications. The behavioral shift is most visible in United States research clusters where procurement centralization has accelerated post-pandemic.
Balanced Salt Solution for Cell Culture Market Segmentation
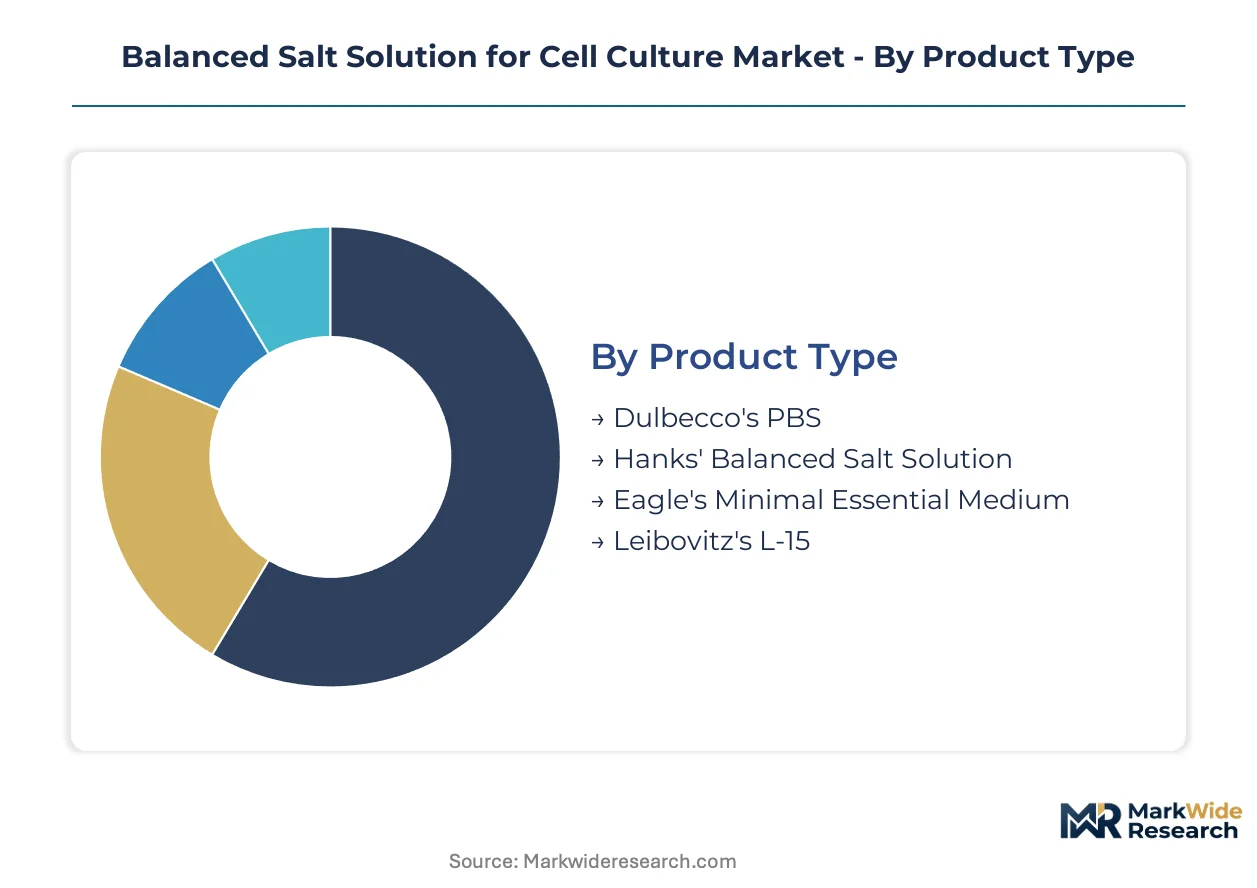
Balanced salt solution procurement patterns diverge sharply across formulation formats and end-use applications. Technical specifications governing ionic composition and buffering capacity create distinct qualification barriers that segment supplier access and pricing power.
Product Type:
Volume concentration favors universal formulations, while specialty media command premium positioning through protocol-specific optimization.
- Dulbecco's PBS:Phosphate-buffered saline maintains physiological pH through sodium phosphate and sodium chloride equilibrium, serving as the default rinsing medium across adherent and suspension cell workflows. Demand concentrates in United States biologics manufacturing clusters where FDA DMF-qualified supply chains anchor procurement decisions.
- Hanks' Balanced Salt Solution:HEPES-buffered formulation enables CO2-independent operation, eliminating controlled atmosphere infrastructure requirements. German and Chinese cell therapy developers are standardizing on this format for satellite manufacturing facilities lacking centralized incubation systems.
- Eagle's Minimal Essential Medium:Nutrient-enriched formulation supports extended cell maintenance beyond simple rinsing applications.
- Leibovitz's L-15:Air-equilibrated medium designed for atmospheric CO2 conditions in field and point-of-care settings.
Today's leader: Dulbecco's PBS. Tomorrow's challenger: Hanks' Balanced Salt Solution.
Usage Type:
Application maturity determines specification stringency, with therapeutic applications imposing cGMP compliance that research workflows bypass.
- Drug Development:High-throughput screening and bioprocess optimization require batch-to-batch consistency validated through pharmacopeial testing. United States biopharmaceutical companies are consolidating procurement around suppliers with ISO 13485 alignment for diagnostic integration.
- Tissue Engineering:Scaffold seeding and organoid maintenance demand pyrogen-controlled formulations with documented endotoxin thresholds. Chinese regenerative medicine centers are driving volume expansion through CDSCO-aligned import substitution programs.
- Cell Viability Testing:Standardized rinsing protocols for metabolic assay workflows.
- In Vitro Fertilization:Clinical-grade specifications for gamete and embryo handling.
Drug Development commands current procurement volume; Tissue Engineering climbs fastest on regenerative medicine investment.
Formulation Type:
Supply chain configuration separates cold-chain dependent liquids from ambient-stable alternatives with distinct distribution economics.
- Ready-to-use:Sterile liquid in final concentration eliminates hydration contamination risk and compresses workflow time. Biopharmaceutical companies in Massachusetts and Bavaria are mandating this format for cGMP therapeutic production to satisfy EMA Annex 1 environmental monitoring requirements.
- Liquid:Pre-diluted sterile solution requiring refrigerated transport and storage infrastructure.
- Powder:Lyophilized or granular format reducing shipping weight and cold-chain dependency.
- Concentrate:10X or higher dilution factor reducing storage footprint at point of use.
Ready-to-use dominates therapeutic manufacturing; Powder retains emerging market relevance where cold-chain gaps persist.
End User:
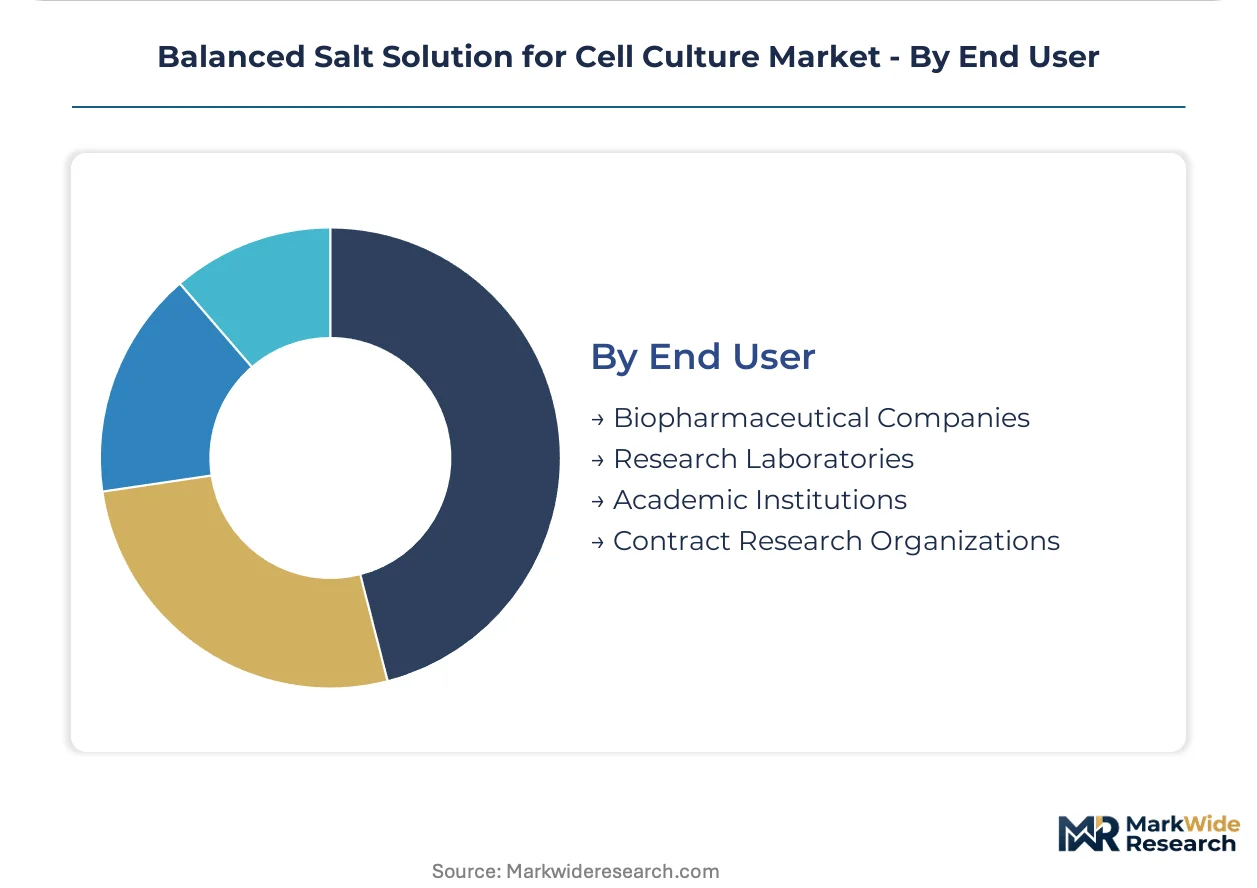
Customer scale determines contract structure, with enterprise procurement concentrating volume among multinational suppliers while fragmented research buyers sustain specialty formulators.
- Biopharmaceutical Companies:Integrated therapeutic developers and CDMOs require validated DMFs and audit-ready quality systems. German fill-finish operators are capturing this segment through EMA-aligned sterile manufacturing infrastructure.
- Contract Research Organizations:Centralized procurement through group purchasing organizations is compressing margins while elevating technical service expectations across North American academic medical centers.
- Research Laboratories:Protocol diversity and small batch requirements favor catalog breadth over single-source consolidation.
- Academic Institutions:Budget-constrained buyers prioritizing classical formulations with established citation histories.
Biopharmaceutical Companies anchor revenue concentration; Contract Research Organizations are consolidating fastest through procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical procurement exceeds German volumes by a factor of three, yet Chinese regenerative medicine investment is compressing that gap through CDSCO-aligned import substitution programs.
United States
FDA Drug Master File requirements lock therapeutic biologics manufacturers into validated supplier relationships, reducing competitive churn among salt solution formulators. The IRA's domestic manufacturing incentives are accelerating CDMO capacity expansion in Greater Boston and the San Francisco Bay Area. Massachusetts fill-finish operators are retrofitting legacy suites to capture cell therapy media volumes under EMA-aligned environmental monitoring protocols.
Germany
EMA Annex 1 revisions mandate continuous viable particle detection in Grade A fill-finish zones, elevating capital intensity for sterile salt solution production. Bavarian contract manufacturers are investing in isolator-based lines with robotic decontamination cycles to preempt regulatory scrutiny. Heidelberg and Munich biotech clusters are standardizing on Hanks' Balanced Salt Solution for satellite manufacturing facilities lacking centralized incubation systems.
China
CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting multinational fill-finish investment requiring qualified salt solution supply. NMPA alignment with USP-grade raw material specifications is forcing domestic formulators to consolidate procurement around three specialty chemical producers. Shanghai and Suzhou biologics manufacturing clusters are driving volume expansion through state-backed regenerative medicine centers.
India
BIS certification requirements for cell culture media used in diagnostic device manufacturing are gating supplier access to IVD kit integrators. CDSCO's accelerated biosimilar review timelines are pulling cGMP-grade balanced salt solution demand from research-grade suppliers. Hyderabad and Bengaluru biotech corridors are emerging as preferred locations for multinational fill-finish investment under production-linked incentive schemes.
Japan
PMDA's alignment with ICH Q7 guidelines for active pharmaceutical ingredients extends to cell culture media used in therapeutic biologics production. METI's biomanufacturing competitiveness program is subsidizing isolator-based filling technology adoption in Osaka and Tokyo pharmaceutical zones. Kanto region CDMOs are capturing regional demand through ISO 13485-certified supply chains aligned with diagnostic device manufacturer requirements.
Balanced Salt Solution for Cell Culture Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where cGMP compliance separates premium positioning from catalog breadth strategies. Three to five multinational life science groups anchor North American and European procurement through distribution density and Drug Master File portfolios. Mid-tier formulators retreat to specialty applications with protocol-specific optimization. Competitive moves concentrate on sterile fill-finish capacity expansion and ISO 13485 certification acquisition for diagnostic integration.
Among diversified conglomerates with channel density advantages, Thermo Fisher Scientific Inc. and EMD Millipore occupy positions spanning research-grade through cGMP-tier supply. Lonza Group Ltd. exemplifies the premium-tier archetype through validated manufacturing infrastructure. Sigma-Aldrich Co. LLC represents catalog breadth differentiation across classical and specialized salt formulations. These three anchors illustrate the strategic divergence between scale-driven distribution and compliance-driven qualification.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza Group Ltd. |
| Sigma-Aldrich Co. LLC |
| EMD Millipore |
| Corning Life Sciences B.V. |
| PromoCell GmbH |
| Becton Dickinson & Co. |
| Wheaton Industries Inc. |
| Atlanta Biologicals |
| Others |
Value Chain & Pricing Dynamics
USP-grade sodium chloride pricing indices cascade through balanced salt solution manufacturing tiers, compressing margins at powder-format suppliers while elevating premium capture for cGMP-qualified liquid formulators serving FDA Drug Master File-dependent biopharmaceutical buyers.
Pricing Analysis
Capacity additions in Germany and Massachusetts are reshaping price floors for sterile fill-finish operations as isolator-based lines with robotic decontamination cycles elevate capital barriers. Three-tier pricing structure across cGMP-certified, ISO 13485-aligned, and research-grade levels separates therapeutic biologics procurement from diagnostic device integration and academic catalog buying. Pricing pressure stems from consolidated procurement through group purchasing organizations compressing supplier margins across North American academic medical centers. Contract research organizations exhibit highest price sensitivity due to centralized enterprise negotiations, while cell therapy developers show lowest sensitivity given DMF-qualification lock-in requirements.
Supply Chain Analysis
Grade A fill-finish operator scarcity in Bavarian and Massachusetts manufacturing corridors constrains sterile salt solution capacity expansion timelines despite isolator technology investments. Supply concentrates in the United States, Germany, and China where biologics manufacturing clusters anchor procurement decisions. Raw material dependencies center on USP-grade sodium chloride, dibasic sodium phosphate, and HEPES buffering agents sourced from three specialty chemical producers. Single-source vulnerability in pharmaceutical-grade sodium chloride exposes formulators to input cost volatility. Distribution runs through cold-chain dependent logistics for ready-to-use liquid formats, with ambient-stable powder alternatives serving emerging markets lacking refrigerated infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities separate EMA Annex 1 compliance investments in Germany from CDSCO-aligned import substitution economics in India, with production-linked incentive schemes compressing cost differentials for qualified salt solution supply.
For Market Incumbents: Anticipate lyophilized media substitution threats in cold-chain-constrained markets by accelerating isolator-based fill-finish capacity in Massachusetts and Bavaria. Deepen backward integration into USP-grade raw material sourcing to deflect sodium chloride price volatility from three specialty chemical producers. Prioritize ISO 13485 certification acquisition for diagnostic device manufacturer integration. For New Entrants and Emerging Players: Point-of-care cell therapy production facilities near treatment centers represent an underserved buyer archetype requiring small-batch, patient-specific media logistics currently bypassed by bulk distribution networks. Target Indian biologics manufacturing expansion under CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives. Deploy technical service-heavy direct sales models to differentiate from catalog breadth competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier formulators possessing EMA-aligned sterile manufacturing infrastructure and pending ISO 13485 certification for diagnostic integration. Long-term viability hinges on cGMP compliance moats widening as FDA Drug Master File requirements harden therapeutic biologics supplier relationships. Monitor CDSCO biosimilar approval velocity as inflection indicator for Indian manufacturing demand pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Fill-Finish Capacity Expansion | EMA Annex 1 environmental monitoring mandates elevate capital barriers for sterile salt solution production in Germany. |
| ISO 13485 Certification Acquisition | Diagnostic device manufacturers integrating cell culture reagents into IVD kits require quality system alignment for supplier access. |
| Backward Integration into USP-Grade Raw Materials | Three specialty chemical producers concentrate pharmaceutical-grade sodium chloride supply, exposing formulators to input cost volatility. |
| Point-of-Care Logistics Network Development | Decentralized cell therapy manufacturing near treatment centers demands small-batch media distribution currently underserved by bulk networks. |
| CDSCO-Aligned Import Substitution Programs | Indian PLI scheme incentives attract multinational fill-finish investment requiring qualified salt solution supply from domestic formulators. |
Study Parameters
Multiple input streams — primary interviews with bioprocessing executives, regulatory affairs leads at salt solution formulators, and GPO procurement managers; secondary validation through FDA Drug Master File databases, EMA sterile manufacturing guidance documents, and CDSCO biosimilar approval records — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor CAGRs across formulation type, end-use application, and geographic regulatory cluster dimensions. Modeled outputs incorporate cell therapy pipeline advancement rates, fill-finish capacity utilization in Bavaria and Massachusetts, and CDSCO approval pathway velocity as industry-specific forecast inputs throughout the projection horizon.
Inputs from EMA Annex 1 revision documentation and CDSCO PLI scheme disclosures were available through the study window; gaps in real-time Grade A environmental monitoring compliance rates introduce uncertainty bands around sterile fill-finish capacity expansion timelines. Forecasts reflect assumptions regarding isolator technology adoption curves and raw material price index stability. Material deviation in CDSCO biosimilar approval velocity or USP-grade sodium chloride supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market