
 Asia-Pacific Transfection Reagent and Equipment Market | 2026-2036
Asia-Pacific Transfection Reagent and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Transfection Reagent and Equipment Market Outlook
Direct distribution to academic consortia is reconfiguring as group purchasing organizations across Australia and South Korea consolidate procurement volumes. Thermo Fisher Scientific leverages its regional logistics network to sustain instrument placement contracts with major research universities. Promega Corporation competes through localized reagent manufacturing that reduces cold-chain dependency for temperature-sensitive lipid formulations. Bio-Rad Laboratories anchors its position with field service density that supports high-utilization electroporation workflows in core facilities.
Transfection reagent and equipment encompasses chemical formulations, physical delivery systems, and viral vectors designed to introduce nucleic acids into eukaryotic cells with efficiencies typically ranging from 30% to 95% depending on cell type and method. These tools serve as foundational infrastructure for gene therapy development, recombinant protein manufacturing, and CRISPR-based editing workflows across pharmaceutical and academic research settings. Reagent categories capture the largest margin pool due to recurring purchase cycles and protocol-specific optimization requirements, while electroporation instruments represent the fastest-expanding technology segment as clinical translation of cell therapies intensifies. Academic institutions constitute the highest-volume end user segment, though pharmaceutical companies generate superior per-account revenue through validated GMP-grade supply agreements.
Japan's PMDA enforces stringent quality standards for gene therapy manufacturing materials that elevate compliance costs for imported reagent portfolios. Australia's TGA alignment with PIC/S guidelines shapes audit requirements for contract research organizations conducting multi-site transfection studies. India's CDSCO emerging gene therapy framework creates preparatory demand for documentation-ready product lines among domestic biotech firms. Stakeholders must monitor regulatory divergence between national pharmacopeias as cell and gene therapy pipelines advance toward commercial authorization across the region.
Market Dynamics
Clinical translation of cell therapies is compressing validation timelines for electroporation workflows, forcing suppliers to pre-qualify GMP-grade reagent lines before regulatory submission rather than after proof-of-concept completion.
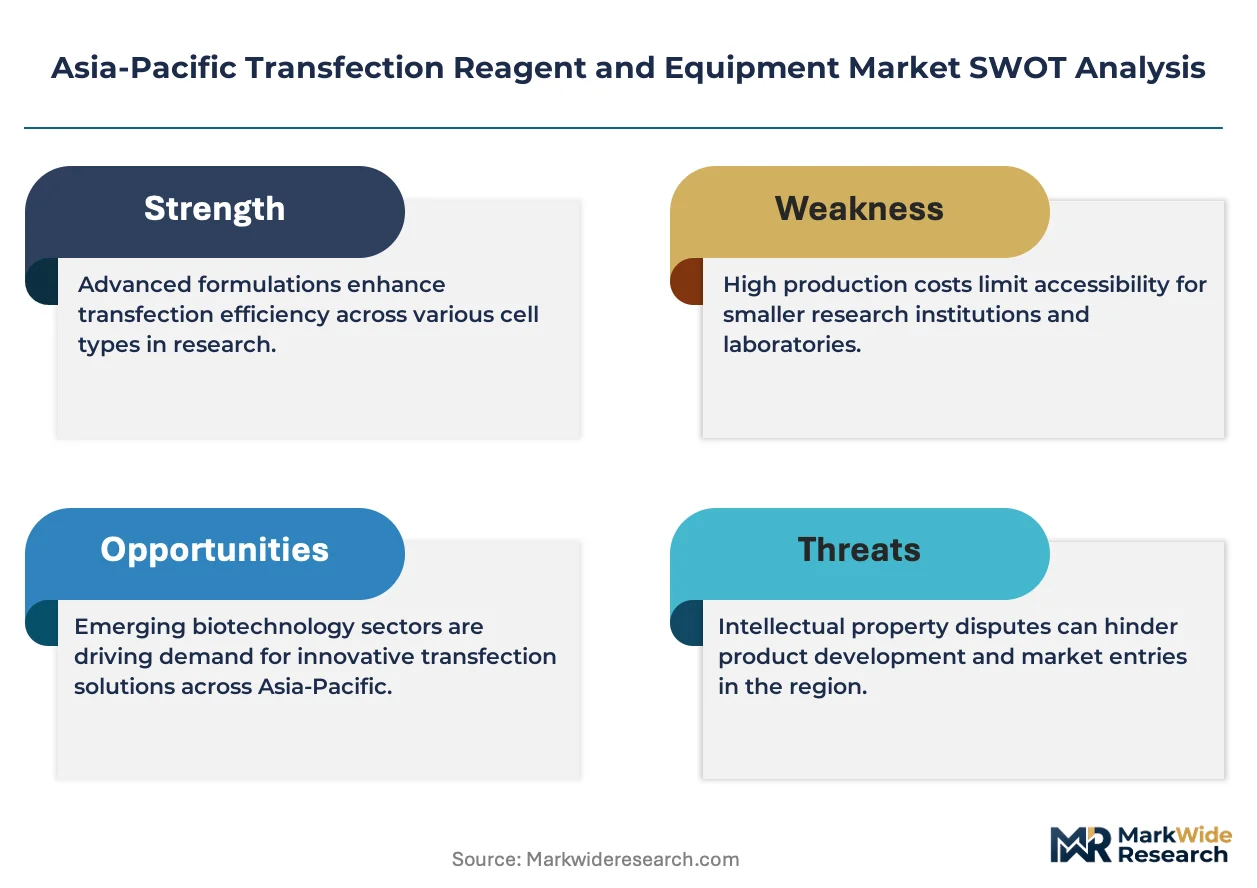
Growth Catalysts
- Japan's PMDA gene therapy framework:Accelerated approval pathways for regenerative medicines expand demand for documentation-ready transfection materials with traceable manufacturing histories.
- Biologics manufacturing:Contract development organizations in China scale transient expression systems for monoclonal antibody production, driving recurring reagent procurement cycles.
- CRISPR editing workflows:Academic core facilities across Australia consolidate RNP complex delivery protocols, standardizing electroporation as the preferred non-viral method.
Market Restraints
- Lipid raw material concentration:Ionizable lipid synthesis capacity concentrates among specialized chemical suppliers in South Korea and Singapore, creating single-source vulnerability for formulated reagent producers.
- PMDA import documentation:Japan's foreign manufacturer registration requirements extend lead times for novel reagent introductions by six to nine months.
- Chemical transfection efficiency ceilings:Primary T-cell populations resist lipid-mediated nucleic acid delivery, limiting addressable indications in immuno-oncology.
Strategic Opportunities
- India's CDSCO preparatory demand:Domestic biotech firms invest in documentation-capable reagent portfolios ahead of formal gene therapy commercialization guidelines.
- Electroporation-microfluidics convergence:Closed-system processing enables point-of-care cell modification workflows for decentralized autologous therapies.
- Group purchasing consolidation:Australian academic consortia aggregate procurement volumes, creating dedicated supplier tier relationships with volume-commitment pricing.
Industry Challenges
- Field service engineer scarcity:Electroporation instrument deployment requires specialized bioelectrical troubleshooting expertise that outpaces regional training program output.
- GMP-grade certification timelines:Reagent manufacturers face eighteen-month validation cycles for pharmaceutical-grade manufacturing documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Transfection Reagent and Equipment Market |
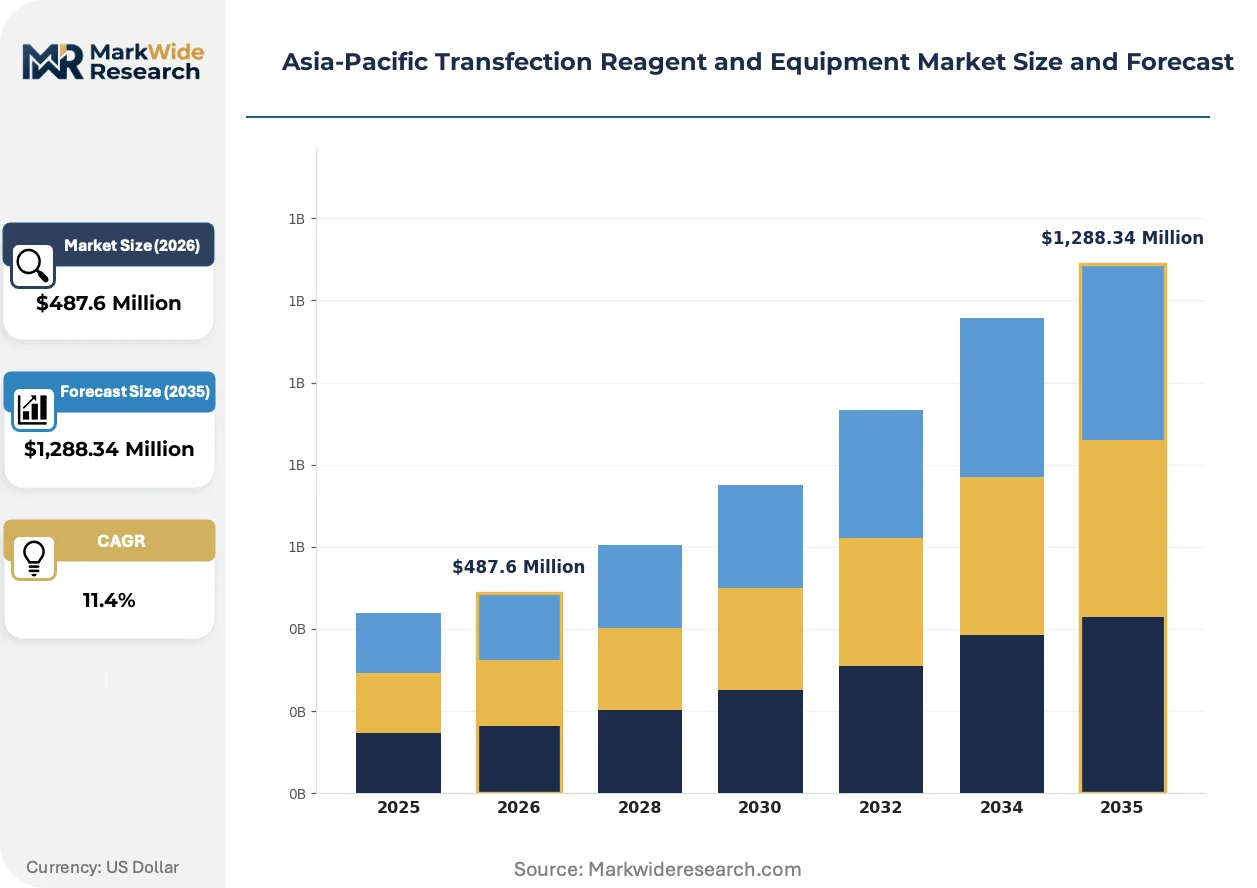
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Kits, Consumables Technology: Chemical, Physical, Viral, Electroporation End User: Pharmaceutical Companies, Academic Institutions, Biotech Firms, Contract Research Organizations Application: Gene Manipulation, Protein Production, Vaccination, Cell Line Development |
| Companies Covered | Thermo Fisher Scientific Inc, Promega Corporation, Bio-Rad Laboratories Inc, Lonza Group Ltd, Qiagen NV, Merck KGaA, Polyplus-transfection SA, MaxCyte Inc, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Transfection Reagent and Equipment Market Strategic Shifts
Non-viral delivery modalities are overtaking lentiviral vectors in clinical pipelines, compressing the technology adoption curve from academic research through commercial manufacturing.
Engineered ribonucleoprotein complexes enable direct protein-RNA delivery without genetic integration. Cell therapy developers in China and Japan adopt these systems for regulatory-simplified editing workflows. This approach is rendering obsolete plasmid-based expression strategies that require extended selection timelines.
Australia's TGA alignment with PIC/S guidelines mandates audit-ready supply chain documentation for multi-site transfection studies. Contract research organizations restructure vendor qualification protocols to satisfy cross-border inspection standards. Reagent suppliers with pre-established master files capture preferential positioning in Australian government-funded research tenders.
Consolidated procurement through university purchasing cooperatives displaces individual laboratory ordering across South Korea and Taiwan. Research institutions negotiate multi-year reagent supply agreements with embedded technical support and protocol optimization services. This concentration is most visible in Seoul's biotech corridor, where three purchasing cooperatives manage transfection spend for seventeen affiliated research hospitals.
Asia-Pacific Transfection Reagent and Equipment Market Segmentation
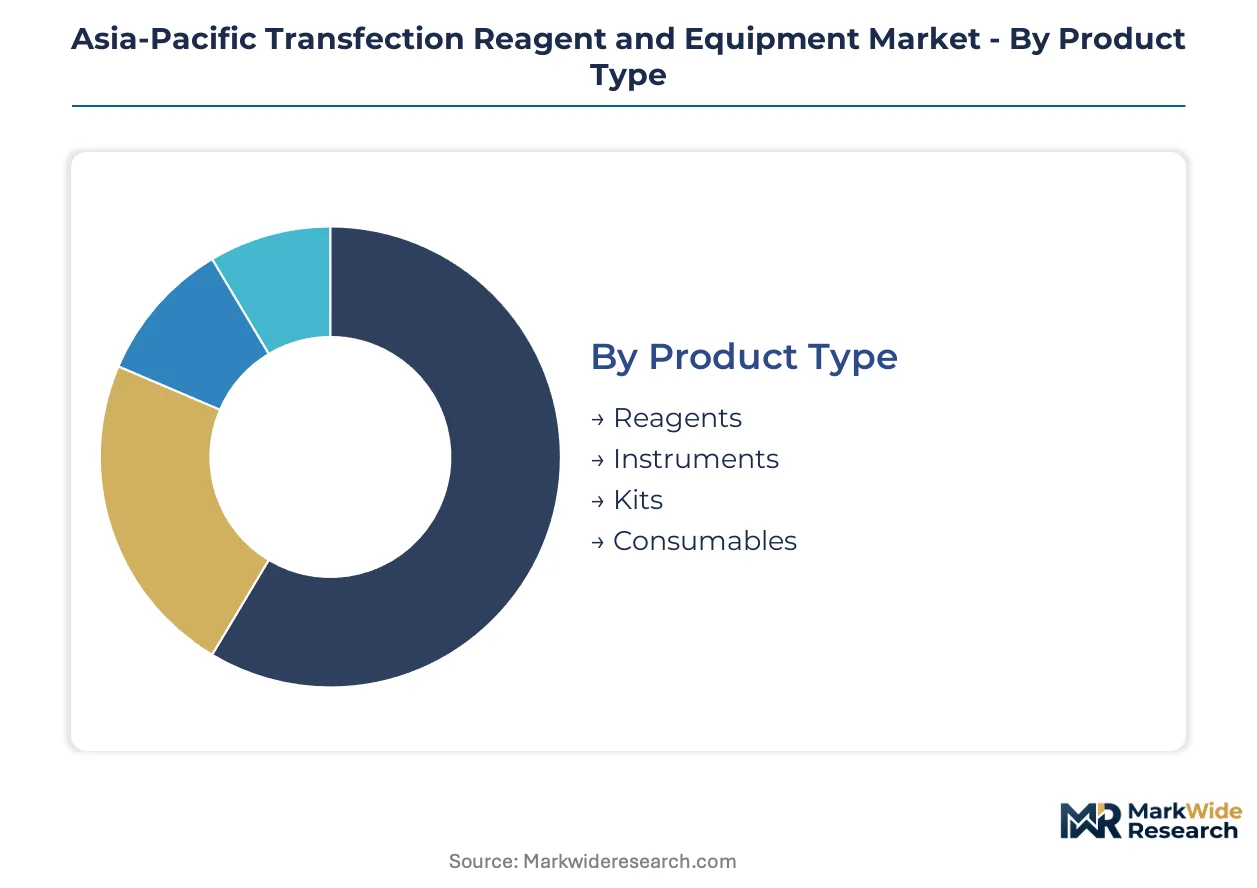
Transfection market segmentation reveals divergent margin structures across product formats and technology modalities. Chemical reagents command recurring revenue streams while electroporation instruments capture upfront capital deployment. End-user concentration in pharmaceutical manufacturing versus academic procurement creates distinct pricing architectures.
Product Type:
Cost tier differentiation separates consumable replenishment cycles from capital equipment amortization schedules.
- Reagents:Lipid-based and polymer formulations enable transient nucleic acid delivery with protocol-specific optimization requirements. China's biotech clusters around Shanghai and Suzhou drive bulk procurement of GMP-grade chemical formulations for cell therapy manufacturing.
- Instruments:Electroporation systems and microfluidic processors deliver physical transfection with voltage-parameter precision. Japan's PMDA documentation requirements for clinical-grade equipment extend qualification timelines and elevate compliance investment.
- Kits:Pre-formulated reagent-instrument combinations reduce protocol development burden for standardized workflows.
- Consumables:Electroporation cuvettes, specialized plates, and single-use chambers complete system-level revenue capture.
Reagents hold installed capacity. Instruments are rotating up the share rankings.
Technology:
Application suitability determines modality selection across cell type sensitivity and payload complexity.
- Chemical:Lipofection and calcium phosphate precipitation offer cost-efficient delivery for adherent cell lines. Primary T-cell populations resist lipid-mediated entry, constraining immuno-oncology addressability.
- Physical:Microinjection and biolistics serve specialized applications requiring direct nuclear access. Australia's academic core facilities deploy these methods for hard-to-transfect primary cultures.
- Viral:Lentiviral and adenoviral vectors achieve stable integration but face biosafety classification burdens. South Korean CDMOs maintain viral packaging capacity for gene therapy developers.
- Electroporation:Pulsed electrical fields permeabilize membranes for RNP complex delivery without genomic integration. Clinical translation of cell therapies across China and Japan accelerates non-viral adoption curves.
Electroporation is climbing the fastest. Chemical methods retain volume dominance in research settings.
End User:
Customer type stratification creates divergent contract structures from validated supply agreements to discretionary procurement.
- Pharmaceutical Companies:GMP-grade reagent lines with traceable manufacturing histories support regulatory submissions. Japan's accelerated approval pathways for regenerative medicines expand documentation-ready material demand.
- Academic Institutions:Core facility consolidation across Australia and South Korea aggregates purchasing volumes through group procurement organizations.
- Biotech Firms:India's CDSCO preparatory investment drives documentation-capable portfolio adoption ahead of formal gene therapy commercialization guidelines.
- Contract Research Organizations:Multi-site study execution requires audit-ready supply chain documentation aligned with TGA and PIC/S inspection standards.
Pharmaceutical companies hold installed capacity. Biotech firms are rotating up the share rankings.
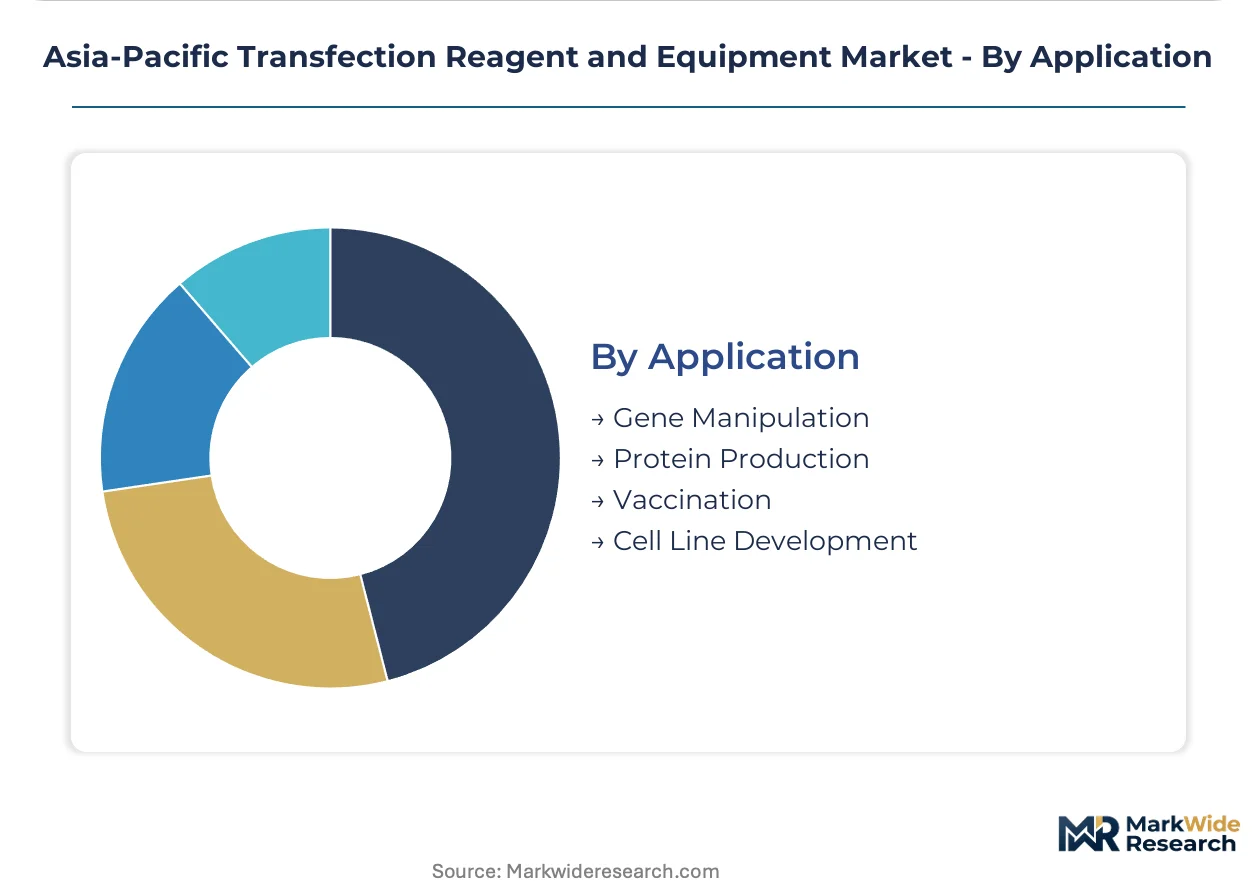
Application:
Volume concentration in therapeutic manufacturing versus research tool development shapes technology preference.
- Gene Manipulation:CRISPR-based editing workflows standardize electroporation for RNP delivery across Australian academic consortia. Ribonucleoprotein complexes displace plasmid-based strategies with reduced selection timelines.
- Protein Production:Transient expression systems in Chinese CDMOs scale monoclonal antibody manufacturing with recurring reagent replenishment cycles.
- Vaccination:DNA and mRNA vaccine development leverages lipid nanoparticle formulations with ionizable lipid supply concentration in South Korea and Singapore.
- Cell Line Development:Stable transfection for biologics manufacturing requires extended selection protocols favoring viral vector integration.
Gene manipulation holds installed capacity. Protein production is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex anchors reagent import velocity for the Asia-Pacific transfection market, handling specialized cold-chain logistics for temperature-sensitive lipid formulations. This maritime infrastructure underwrites supply security for biotech clusters across the region's eastern seaboard.
China
Pharmaceutical companies in Shanghai and Suzhou drive electroporation system deployment for cell therapy manufacturing. NMPA's accelerated review pathways for innovative biologics compress validation timelines for GMP-grade reagent documentation. The Yangtze River Delta biotech corridor concentrates demand among contract development organizations scaling transient expression systems.
Japan
PMDA's gene therapy framework mandates traceable manufacturing histories for clinical-grade transfection materials. METI's regenerative medicine promotion policies expand documentation-ready reagent procurement by domestic pharmaceutical manufacturers. The Kanto region's research hospitals consolidate electroporation workflows through core facility standardization.
Australia
TGA alignment with PIC/S guidelines shapes audit requirements for multi-site transfection studies conducted by contract research organizations. Group purchasing cooperatives across New South Wales and Victoria aggregate academic procurement volumes. Sydney's research hospitals negotiate multi-year reagent agreements with embedded technical support services.
South Korea
Ionizable lipid synthesis capacity concentrates among specialized chemical suppliers serving formulated reagent producers. MFDS guidelines for gene therapy products elevate compliance investment for imported manufacturing materials. Seoul's biotech corridor consolidates purchasing through three cooperatives managing transfection spend for seventeen affiliated research hospitals.
India
CDSCO's emerging gene therapy framework creates preparatory demand for documentation-capable reagent portfolios among domestic biotech firms. PLI scheme incentives for pharmaceutical manufacturing attract investment in GMP-grade supply infrastructure. Maharashtra's biotech clusters invest ahead of formal commercialization guidelines.
Asia-Pacific Transfection Reagent and Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in reagent formulation. The vendor base stratifies between diversified life science conglomerates with regional logistics networks and focused reagent manufacturers with localized production capabilities. Three archetypes dominate: instrument-anchored systems suppliers, reagent-centric formulation specialists, and viral vector packaging service providers. Competitive moves concentrate on GMP-grade certification acquisition and field service engineer density expansion.
Among US-based diversified suppliers, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify instrument-anchored positioning with regional logistics infrastructure. Promega Corporation represents the reagent-centric archetype through localized manufacturing approaches. These three occupy positions spanning system integration and consumable supply, reflecting the market's bifurcation between capital equipment placement and recurring reagent procurement cycles.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Promega Corporation |
| Bio-Rad Laboratories Inc |
| Lonza Group Ltd |
| Qiagen NV |
| Merck KGaA |
| Polyplus-transfection SA |
| MaxCyte Inc |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo port complex channels cold-chain logistics costs for temperature-sensitive lipid formulations, concentrating supply-side leverage among ionizable lipid producers in South Korea and Singapore while forcing three-tier pricing stratification across GMP-grade, research-grade, and bulk-unformulated tiers for downstream biotech clusters in China and Japan.
Pricing Analysis
Volume-discount tiering separates pharmaceutical procurement under long-term GMP-grade supply agreements from academic spot purchasing and CDMO bulk contracts. Price differentiation rests on certification grade against PMDA and NMPA standards plus embedded field service density. Cost compression in research-grade chemical reagents is intensifying because Australian group purchasing cooperatives aggregate demand across seventeen affiliated hospitals. Academic consortia exhibit highest price sensitivity; pharmaceutical manufacturers with validated workflows show lowest elasticity due to regulatory switching costs.
Supply Chain Analysis
Contract-manufacturing concentration for ionizable lipids sits with specialized chemical suppliers in South Korea and Singapore, with secondary formulation capacity in China and Japan. Raw material dependencies include synthetic cholesterol, polyethylene glycol derivatives, and proprietary cationic lipid architectures. Single-source vulnerability pervades the ionizable lipid tier where three suppliers serve the regional market. Distribution runs through direct field service networks for electroporation instruments and cold-chain logistics partnerships for reagent replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement organizations across Australia and South Korea, fragmenting individual laboratory discretion and compressing supplier margins through volume-commitment negotiations.
For Market Incumbents: Build regulatory documentation moats by pre-qualifying master files with PMDA and TGA ahead of competitor submissions. Deepen field service engineer density in China's Yangtze River Delta biotech corridor to lock in high-utilization electroporation workflows. Anchor position through backward integration into ionizable lipid synthesis to offset South Korean supplier concentration risk. For New Entrants and Emerging Players: India's Maharashtra biotech clusters offer underpenetrated documentation-capable reagent demand ahead of CDSCO formal commercialization guidelines. Target electroporation-microfluidics convergence for point-of-care autologous therapy workflows in Japan's Kanto region research hospitals. Pursue technical service bundling as primary go-to-market angle against established instrument-anchored competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reagent-centric formulation specialists with localized manufacturing capabilities over capital-intensive instrument platforms. Long-term viability hinges on GMP-grade certification velocity and regulatory master file accumulation. Monitor PMDA accelerated approval pathway utilization rates as inflection indicator for documentation-ready material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Grade Certification Acquisition | PMDA master file pre-qualification secures preferred positioning in Japanese pharmaceutical procurement tenders. |
| Field Service Engineer Expansion | Bioelectrical troubleshooting density in Shanghai-Suzhou clusters supports high-utilization electroporation instrument contracts. |
| Ionizable Lipid Backward Integration | In-house synthetic capacity reduces single-source dependency on South Korean and Singaporean chemical suppliers. |
| Group Purchasing Cooperative Engagement | Multi-year agreements with Australian academic consortia embed volume-commitment pricing and technical support services. |
| Electroporation-Microfluidics Convergence | Closed-system processing enables decentralized autologous cell therapy workflows for Japan's regenerative medicine pipeline. |
Study Parameters
Operator-level perspectives from cell therapy manufacturing directors, regulatory affairs leads at pharmaceutical companies, core facility managers at Australian research hospitals, and procurement officers at Chinese CDMOs anchored the qualitative base. Secondary validation drew from PMDA gene therapy submission databases, NMPA accelerated review pathway disclosures, TGA PIC/S alignment guidelines, and trade flow data through the Shanghai-Ningbo port complex. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from instrument placement and reagent consumption patterns.
Scenario-bracketing framed low, baseline, and high cases across the projection horizon based on CDSCO guideline finalization timing and PMDA approval pathway utilization rates. Segmentation dimensions spanned product type, technology modality, end-user archetype, and application area with regional regulatory cluster overlays. CAGRs were derived from instrument replacement cycles, reagent replenishment frequencies, and clinical translation pipeline maturation trajectories. Forecast inputs incorporated electroporation system deployment rates in Chinese biotech clusters and GMP-grade reagent documentation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates into localized reagent manufacturing would shift outcomes through accelerated price competition. Regulatory divergence between national pharmacopeias, ionizable lipid supply disruptions, and field service engineer scarcity present revision risks. Quarterly review of PMDA submission volumes, CDSCO guideline publication status, and Australian cooperative procurement award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Automated Cell Culture Equipment Market