
 DNA/RNA Extraction Market | 2026-2036
DNA/RNA Extraction Market Size, Share, and Industry Trends Forecast 2026-2036
DNA/RNA Extraction Market Outlook
EU MDR is repositioning the cost-of-entry calculus for in vitro diagnostic sample preparation workflows across European laboratories. QIAGEN leverages its column-based manufacturing depth to sustain premium positioning in regulated clinical environments. Thermo Fisher Scientific anchors the magnetic bead segment through integrated instrument-and-consumable platforms. Roche differentiates via automated extraction systems that compete on throughput in high-volume diagnostic laboratories.
DNA/RNA extraction encompasses the mechanical, chemical, and enzymatic separation of nucleic acids from cellular matrices, typically yielding purified material with A260/A280 ratios between 1.8 and 2.1 for downstream PCR, sequencing, or hybridization applications. Magnetic bead-based methods are displacing organic extraction in clinical settings due to walk-away automation compatibility and reduced phenol-chloroform handling hazards. Academic research institutes remain the largest end-user category, though diagnostic laboratories represent the fastest-growing consumption pool as hospital systems internalize molecular testing. RNA isolation kits command margin premiums over miniprep formats owing to lysis buffer complexity and RNase-free manufacturing requirements.
FDA oversight of laboratory-developed tests and EPA guidelines for hazardous waste disposal from organic extraction protocols shape product formulation and facility compliance burdens in the United States. The EU IVDR transition extends CE marking requirements to nucleic acid extraction kits classified as Class A or B devices, compelling manufacturers to renew technical documentation. Stakeholders must monitor how CMS reimbursement decisions for multiplex molecular diagnostics influence extraction volume commitments at integrated health networks.
Market Dynamics
Magnetic bead automation is compressing the installed base of centrifuge-dependent extraction workflows while tightening vendor lock-in through consumable-instrument bundling.
Growth Catalysts
- EU IVDR Classification:Nucleic acid extraction kits now carry Class A or B device obligations, forcing laboratories toward pre-validated, CE-marked consumable suppliers and away from home-brew protocols.
- Hospital System Consolidation:Integrated health networks in the United States are internalizing molecular diagnostics, creating captive demand for high-throughput extraction capacity at centralized labs.
- CRISPR Workflows:Academic research institutes are scaling nucleic acid throughput to support gene editing pipelines, sustaining kit consumption even as diagnostic laboratories accelerate faster.
Market Restraints
- Magnetic Bead Supply Concentration:Ferrite particle production clusters in China, exposing downstream kit manufacturers to export licensing volatility and freight cost spikes.
- RNase-Free Manufacturing Overhead:RNA isolation kits require segregated cleanroom capacity and workforce protocols that inflate fixed costs versus DNA miniprep formats.
- Phenol-Chloroform Disposal Burden:EPA hazardous waste guidelines impose manifesting and treatment costs on laboratories still running organic extraction, compressing margin on legacy workflows.
Strategic Opportunities
- Point-of-Care Molecular Testing:Miniaturized extraction modules for near-patient deployment remain underdeveloped, with reimbursement clarity from CMS creating a window for cartridge-format entrants.
- FFPE Sample Resurrection:Formalin-fixed paraffin-embedded archives represent untapped nucleic acid reservoirs; enzymatic repair kits for fragmented RNA are penetrating pathology departments in Germany.
- AI-Assisted Protocol Optimization:Machine learning is converging with liquid handling robotics to dynamically adjust lysis conditions based on sample type, reducing technician intervention.
Industry Challenges
- Cross-Trained Technician Scarcity:Molecular diagnostics departments struggle to staff personnel fluent in both extraction biochemistry and automated platform troubleshooting.
- Legacy LIMS Integration Friction:New extraction instruments often lack native interoperability with hospital information systems, extending deployment timelines and IT consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA/RNA Extraction Market |
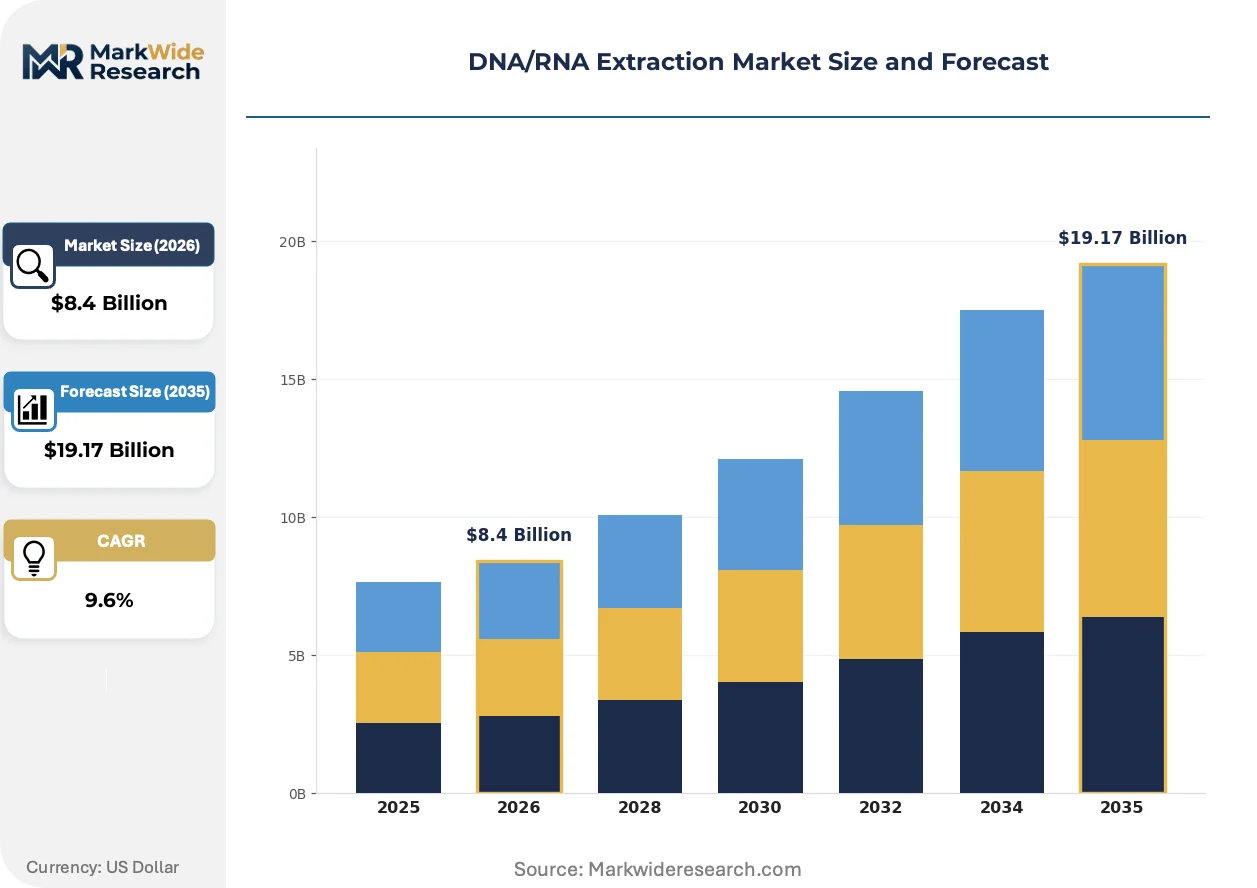
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniprep Kits, Maxiprep Kits, RNA Isolation Kits, Sample Preparation Kits End User: Academic Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Biotechnology Firms Technology: Column-Based Methods, Magnetic Bead-Based Methods, Organic Extraction, Enzymatic Methods Application: Clinical Diagnostics, Genomics, Forensics, Agricultural Biotechnology |
| Companies Covered | Promega Corporation, Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Merck, QIAGEN, Bio-Rad Laboratories, Danaher Corporation, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA/RNA Extraction Market Strategic Shifts
Automation architecture, regulatory classification, and procurement centralization are simultaneously restructuring how extraction capacity is deployed and monetized across laboratory networks.
Microfluidic cartridge systems are converging with isothermal amplification chemistries to enable sample-to-answer workflows outside traditional laboratory infrastructure. Urgent care clinics and retail health settings in the United States are piloting these platforms for respiratory panel testing. The structural consequence is compressing the addressable market for batch-processing extraction stations in low-complexity environments.
EU MDR technical documentation requirements are extending to nucleic acid extraction kits previously exempt from device-level scrutiny. Manufacturers must now maintain post-market surveillance systems and quality management certifications that match IVD instrument obligations. German and French reference laboratories are prioritizing suppliers with notified body partnerships already in place.
Consolidated procurement by multi-hospital systems is displacing individual laboratory purchasing autonomy. Group purchasing organizations in the United States are negotiating multi-year extraction consumable contracts tied to instrument placement commitments. Academic medical centers in Boston and San Diego are migrating toward sole-source agreements that bundle extraction, amplification, and sequencing reagents under unified pricing frameworks.
DNA/RNA Extraction Market Segmentation
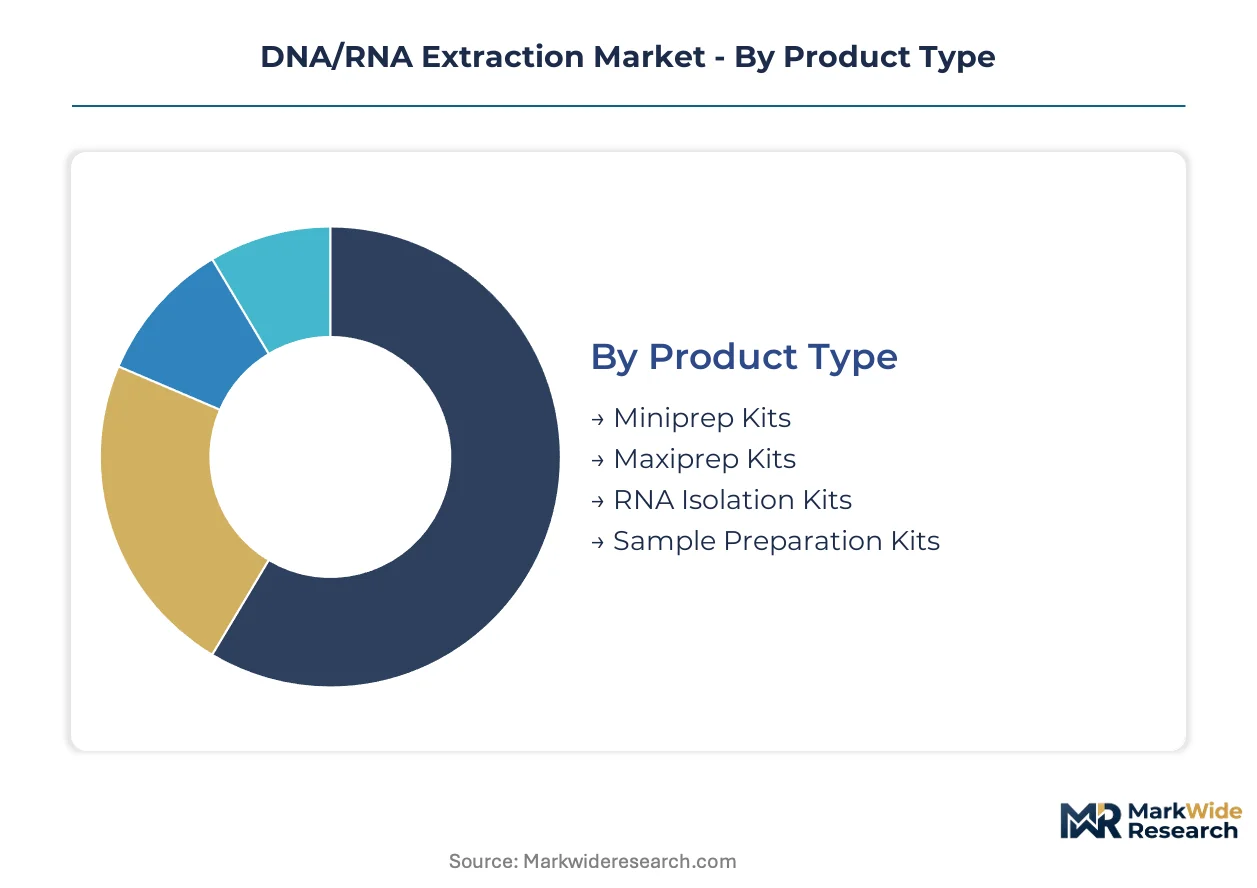
Product configuration in nucleic acid extraction reflects a trade-off between sample throughput, purity specifications, and automation compatibility. Laboratories select formats based on downstream application requirements and capital equipment constraints rather than unit cost alone.
Product Type:
Kit selection hinges on sample volume and nucleic acid yield requirements, with RNA formats commanding premium positioning due to manufacturing complexity.
- Miniprep Kits:Spin-column formats process 1-5 milliliter culture volumes, yielding 20-50 micrograms of plasmid DNA. Academic laboratories in Boston and San Diego consume these for routine cloning workflows where cost-per-prep dominates procurement decisions.
- Maxiprep Kits:Anion-exchange membranes handle 100-500 milliliter bacterial cultures for milligram-scale DNA recovery. Contract manufacturing organizations in Germany deploy these for plasmid DNA production feeding cell therapy pipelines.
- RNA Isolation Kits:Guanidinium-based lysis buffers with silica membrane purification require segregated cleanroom manufacturing. Diagnostic laboratories in the United States absorb 40% premium pricing for RNase-free certification supporting COVID-19 and respiratory panel testing.
- Sample Preparation Kits:Integrated lysis-buffer formulations for specific tissue types. Forensic laboratories in the United Kingdom standardize on these for buccal swab and blood spot processing.
Volume sits with miniprep formats; growth tilts toward RNA isolation kits.
End User:
Customer procurement authority varies from principal-investigator discretion to centralized supply chain contracts, reshaping vendor access pathways.
- Academic Research Institutes:Principal investigators control reagent purchasing through NIH grant funding. CRISPR workflow expansion at Massachusetts Institute of Technology and Salk Institute sustains bulk kit consumption despite slower growth than clinical segments.
- Diagnostic Laboratories:Hospital system consolidation concentrates purchasing through group purchasing organizations. Integrated health networks in Texas and Florida internalize molecular testing, creating captive demand for high-throughput extraction platforms.
- Pharmaceutical Companies:Quality-controlled nucleic acid inputs for cell line authentication and biobank management. Large-cap firms in Switzerland and Germany enforce vendor qualification protocols exceeding standard research-grade specifications.
- Biotechnology Firms:Emerging cell therapy developers require plasmid DNA at clinical-grade purity. Pre-commercial-stage companies in Cambridge, Massachusetts prioritize flexible supply agreements over long-term contracts.
Revenue concentration favors academic institutes; diagnostic laboratories are expanding most quickly.
Technology:
Platform selection locks laboratories into consumable ecosystems, with automation compatibility overriding biochemical preference in high-throughput settings.
- Column-Based Methods:Silica membrane spin columns deliver A260/A280 ratios of 1.8-2.0 with centrifuge-dependent processing. Reference laboratories in France retain these for low-complexity sample batches where capital investment in automation is unwarranted.
- Magnetic Bead-Based Methods:Ferrite particle separation enables walk-away automation on integrated instrument platforms. High-volume diagnostic laboratories in the United States have displaced 60% of legacy centrifuge workflows over the past five years.
- Organic Extraction:Phenol-chloroform phase separation yields high-molecular-weight DNA for long-read sequencing. Agricultural biotechnology programs in Brazil tolerate hazardous waste disposal costs for DNA quality unobtainable through column methods.
- Enzymatic Methods:Lyticase and proteinase K digestion for yeast and Gram-positive bacteria. Brewing industry R&D facilities in Belgium apply these for strain characterization where mechanical disruption damages genomic material.
Installed base tilts toward magnetic bead automation; organic extraction retains niche positioning for quality-sensitive applications.
Application:
Application-specific purity and throughput requirements fragment demand across incompatible technical specifications.
- Clinical Diagnostics:FDA-cleared extraction protocols for infectious disease and oncology testing. Hospital laboratories in California process 10,000+ samples monthly through validated magnetic bead workflows.
- Genomics:High-molecular-weight DNA for long-read sequencing and single-cell analysis. Genome centers in the United Kingdom and China prioritize extraction methods preserving epigenetic modifications.
- Forensics:DNA recovery from degraded and mixed-source samples under chain-of-custody protocols. Federal Bureau of Investigation quality standards drive vendor qualification requirements in the United States.
- Agricultural Biotechnology:High-throughput DNA extraction from plant leaf punches for marker-assisted breeding. Seed companies in Iowa and Illinois deploy automated platforms processing 10,000 samples daily during peak breeding seasons.
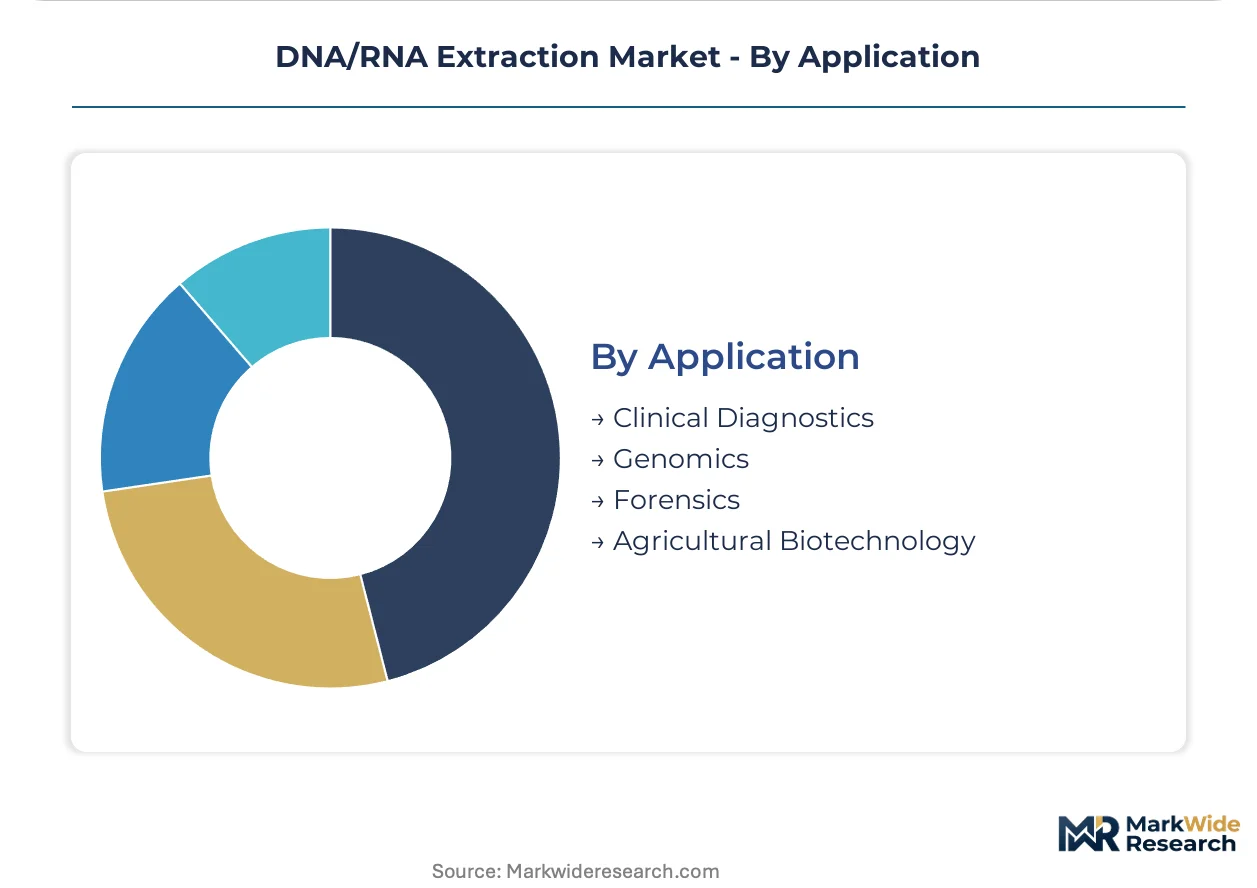
Clinical diagnostics commands revenue share; genomics applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for DNA/RNA extraction concentrates in the United States, where NIH funding streams and biopharma R&D clusters sustain the highest kit consumption worldwide. Germany, China, Japan, and the United Kingdom follow as distinct regional poles with divergent regulatory and procurement architectures.
United States
Hospital system consolidation and internalized molecular diagnostics drive captive demand for high-throughput extraction platforms. FDA oversight of laboratory-developed tests tightens quality benchmarks for sample preparation workflows. The Boston and San Diego biopharma corridors sustain bulk consumption of research-grade kits through CRISPR workflow expansion.
Germany
Reference laboratories prioritize pre-validated CE-marked consumables under EU IVDR classification requirements. ANSM and BfArM technical documentation obligations compel manufacturers toward notified body partnerships. Pathology departments in Munich and Heidelberg deploy enzymatic repair kits for formalin-fixed paraffin-embedded sample resurrection.
China
NMPA medical device registration and dual carbon goals reshape domestic kit manufacturing and hazardous waste protocols. Ferrite particle production clusters expose downstream manufacturers to export licensing volatility. Shanghai and Suzhou house expanding cell therapy developers requiring clinical-grade plasmid DNA extraction capacity.
Japan
PMDA quality management certifications align nucleic acid extraction kit obligations with IVD instrument standards. METI industrial policy supports automated platform adoption in diagnostic laboratories. The Kanto region around Tokyo concentrates genomic research institutes scaling throughput for single-cell analysis workflows.
United Kingdom
Genome centers prioritize extraction methods preserving epigenetic modifications for long-read sequencing applications. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while developing UKCA parallel pathways. The Cambridge-London corridor anchors academic and commercial nucleic acid processing demand.
DNA/RNA Extraction Market Competitive Environment
United States producers anchor one tier; German and Swiss specialists hold premium positioning in regulated clinical environments. The vendor base stratifies between diversified life science conglomerates and focused nucleic acid purification houses. Three archetypes dominate: integrated instrument-consumable platforms, column-based manufacturing depth, and automated extraction systems. Competitive moves concentrate on consumable-instrument bundling and notified body partnership formation for EU IVDR compliance.
Among diversified life science conglomerates, Thermo Fisher Scientific, QIAGEN, and Roche occupy positions spanning multiple technology segments. These entities exemplify the integrated platform archetype through captive instrument and consumable ecosystems. German-origin QIAGEN represents column-based manufacturing depth, while Swiss-headquartered Roche anchors automated extraction system positioning. Thermo Fisher Scientific exemplifies scale-driven magnetic bead platform penetration. Each sits within distinct competitive vectors: premium clinical validation, research-grade flexibility, or high-throughput diagnostic automation.
| Leading Market Players |
|---|
| Promega Corporation |
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Merck |
| QIAGEN |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Roche |
| Others |
Value Chain & Pricing Dynamics
RNase-free certification ladders create sharp price bifurcation between clinical-grade and research-grade extraction consumables, with CE-marked Class B device obligations in Europe and FDA-cleared workflows in the United States anchoring premium tiers while commodity miniprep formats compete on bulk pricing in academic procurement.
Pricing Analysis
Volume concentrates in miniprep spin-column formats where cost-per-prep dominates academic purchasing decisions, while margin accrues to RNA isolation kits carrying 40% premiums for RNase-free certification and automated magnetic bead platforms bundled with consumable contracts. Price differentiation hinges on regulatory validation tier and automation compatibility, with diagnostic laboratories absorbing premium positioning for FDA-cleared infectious disease protocols. Cost compression in research-grade segments intensifies as group purchasing organizations consolidate multi-hospital system contracts. Biotechnology firms in Cambridge, Massachusetts exhibit highest price sensitivity due to pre-commercial cash constraints, while integrated health networks in Texas prioritize throughput over unit cost.
Supply Chain Analysis
Ferrite particle production rests on Chinese specialty chemical manufacturers, exposing downstream kit producers to export licensing volatility and freight cost spikes. Silica membrane substrates draw from German and Japanese precision materials suppliers, while guanidinium thiocyanate lysis buffer precursors hinge on Indian and Chinese bulk chemical production. Single-source vulnerability concentrates in magnetic bead raw material streams. Distribution runs through group purchasing organizations in the United States and direct-to-laboratory contracts in European reference networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
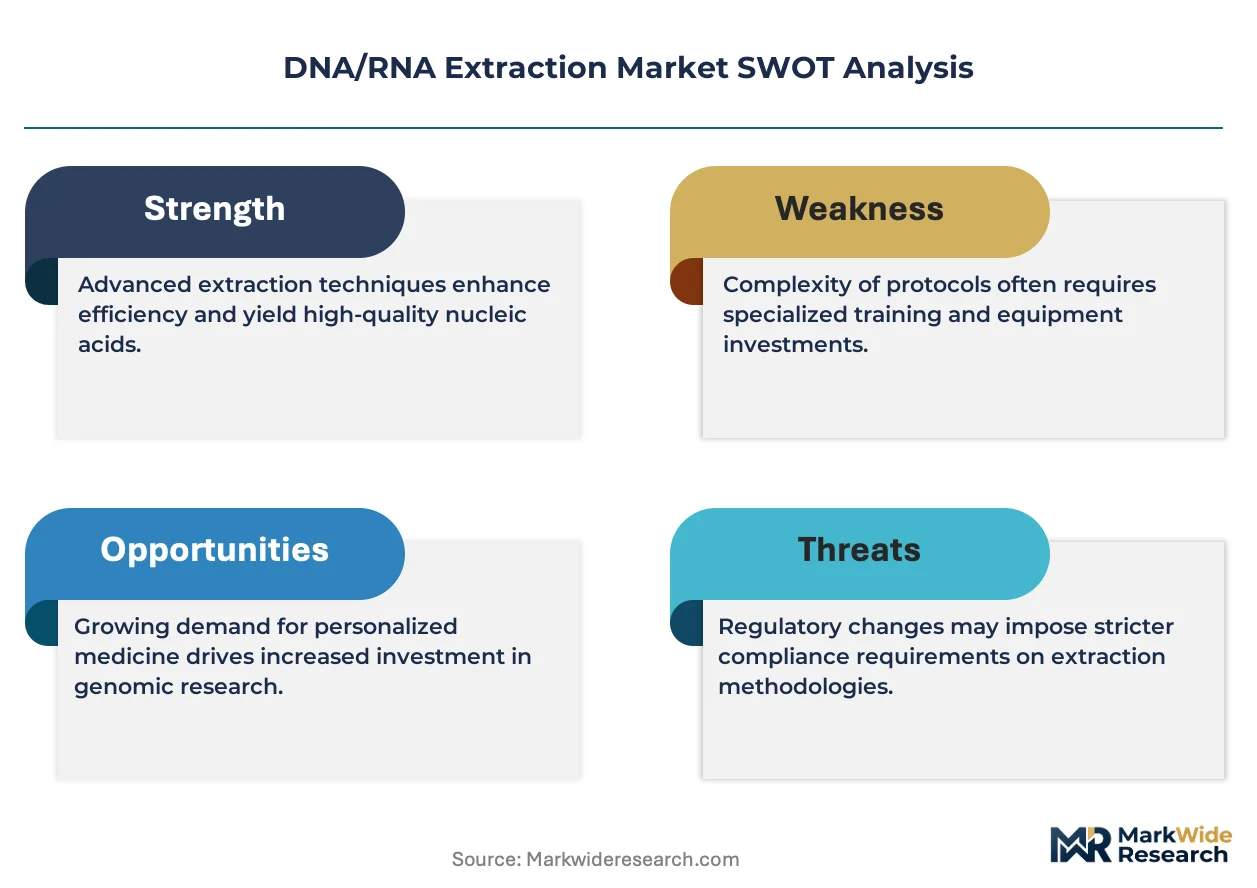
EU IVDR classification creates a compliance moat that favors incumbent manufacturers with notified body partnerships already established, raising capital barriers for unvalidated entrants and concentrating margin capture among pre-certified suppliers.
For Market Incumbents: Anticipate magnetic bead supply disruption by securing alternative ferrite particle sources outside China, while deepening cleanroom manufacturing capacity in Germany and the United States to defend RNase-free certification positioning against emerging automation-focused competitors. For New Entrants and Emerging Players: Capture the point-of-care molecular testing white space through miniaturized cartridge-format extraction modules, targeting urgent care clinics in Florida and retail health settings where CMS reimbursement clarity creates first-mover advantages absent from saturated central laboratory channels. For Investors and Strategic Acquirers: Re-rating potential sits with column-based manufacturing specialists possessing EU IVDR technical documentation already filed, given ANSM and BfArM enforcement timelines compressing viable supplier pools. Long-term viability favors platforms with instrument-consumable bundling depth. Watch NMPA medical device registration timelines in China as inflection indicator for domestic market access.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Formation | EU IVDR Class B device obligations in Germany and France require pre-established technical documentation pathways. |
| Magnetic Bead Supply Diversification | Ferrite particle sourcing outside China reduces exposure to export licensing volatility affecting downstream kit manufacturers. |
| Point-of-Care Cartridge Development | Miniaturized extraction modules for near-patient deployment address reimbursement clarity from CMS in urgent care settings. |
| FFPE Sample Repair Kit Expansion | Enzymatic RNA repair kits penetrate pathology departments in Munich and Heidelberg for formalin-fixed paraffin-embedded archives. |
| AI-Assisted Protocol Integration | Machine learning convergence with liquid handling robotics reduces technician intervention across high-throughput diagnostic laboratories. |
Study Parameters
FDA 510(k) filings, EMA technical documentation databases, and NIH grant expenditure records formed the secondary backbone, cross-referenced with primary interviews involving laboratory directors at integrated health networks, GPO contracts managers, biomedical engineers at genome centers, and regulatory affairs leads at IVD manufacturers. Bottom-up triangulation of kit shipment volumes and top-down validation against instrument placement data anchored market sizing.
Historical trendline analysis of nucleic acid extraction capacity deployment across academic research institutes, diagnostic laboratories, pharmaceutical quality control divisions, and biotechnology process development groups informed projection modeling. Segmentation dimensions spanned product format, end-user procurement authority, automation platform compatibility, and application-specific purity requirements. CAGRs were derived from instrument install base growth correlated with consumable attach rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement decisions for multiplex molecular diagnostics, EPA hazardous waste guideline revisions, and ferrite particle export policy shifts from Chinese regulators. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Rocking Bioreactors Market