
 Cryopreservation Freezer Market | 2026-2036
Cryopreservation Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Cryopreservation Freezer Market Analysis
Biobank operations is expanding as the dominant end-use vertical, displacing traditional research-laboratory procurement with automated high-capacity installations. Thermo Fisher Scientific Inc. leverages its diagnostic-to-storage workflow integration to anchor large biobank contracts. Custom Biogenic Systems specializes in custom aluminum rack systems for legacy infrastructure retrofits. Merck KGaA competes through cryopreservation media bundling with freezer hardware.
A cryopreservation freezer maintains biological specimens at temperatures typically below minus 150 degrees Celsius using mechanical cascade refrigeration or liquid nitrogen vapor-phase systems to arrest metabolic degradation. The equipment serves pharmaceutical development, clinical biobanking, and regenerative-medicine supply chains where thermal stability directly determines sample viability. Ultra-Low Freezers retain the largest installed base but face margin compression from energy-efficiency mandates and refrigerant-phaseout schedules. Liquid Nitrogen technology captures the fastest growth trajectory among cooling methods, driven by stem-cell and CAR-T therapy storage protocols demanding minus 196 degrees Celsius uniformity. Cryogenic Storage Units concentrate margin pools in automated inventory systems with robotic retrieval and chain-of-custody software.
FDA 21 CFR Part 11 governs electronic record-keeping for temperature monitoring, while EPA SNAP regulations restrict hydrofluorocarbon refrigerants in new equipment manufacturing. The EU MDR elevates traceability requirements for medical-device-classified storage systems used in clinical applications. Stakeholders must weigh refrigerant-transition timelines against biobank automation investments as regulatory compliance costs diverge across cooling-technology platforms.
Market Dynamics
Biobank automation is compressing procurement cycles for cryopreservation freezers as large-scale repositories replace discrete laboratory purchases with integrated storage ecosystems requiring robotic inventory management and chain-of-custody software.
Growth Catalysts
- Cell Therapy Manufacturing:CAR-T and stem-cell therapy commercialization is expanding demand for liquid nitrogen vapor-phase systems capable of maintaining minus 196 degrees Celsius uniformity across high-volume sample libraries.
- FDA 21 CFR Part 11:Electronic record-keeping mandates for temperature monitoring are accelerating replacement of legacy mechanical freezers with validated digital systems in United States clinical biobanks.
- Regenerative Medicine Infrastructure:Government funding for advanced therapy medicinal products in Germany and Japan is building dedicated cold-chain facilities requiring cryogenic storage capacity.
Market Restraints
- Refrigerant Supply Concentration:EPA SNAP restrictions on hydrofluorocarbon production are creating input cost volatility for mechanical cascade ultra-low freezer manufacturers dependent on legacy coolant supply chains.
- Technical Temperature Uniformity Limits:Mechanical refrigeration systems face fundamental barriers reaching minus 150 degrees Celsius consistently, forcing biobanks toward higher-cost liquid nitrogen alternatives for critical samples.
- EU MDR Compliance Burden:Medical device classification for clinical storage systems is extending validation timelines and elevating documentation costs for equipment vendors serving European healthcare institutions.
Strategic Opportunities
- India Biobank Infrastructure:CDSCO regulatory frameworks for biological sample storage remain underdeveloped, creating first-mover advantage for automated cryogenic system vendors establishing reference installations.
- Software-Defined Storage:Integration of inventory management platforms with freezer hardware is enabling predictive maintenance and remote monitoring services as recurring revenue streams.
- Retrofit Automation Kits:Legacy aluminum rack infrastructure in United States academic medical centers presents aftermarket opportunity for robotic retrieval system upgrades without full equipment replacement.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized expertise in vacuum insulation and cryogenic fluid dynamics is concentrated among aging workforce cohorts in Japan and Germany, constraining manufacturer expansion.
- Validation Timeline Compression:Biobank operators demand faster FDA 21 CFR Part 11 qualification protocols while regulators maintain rigorous documentation standards, creating execution friction for equipment deployments.
- Legacy System Integration Complexity:Automated storage installations must interface with existing laboratory information management systems, requiring custom middleware development that extends project delivery schedules.
Report Scope
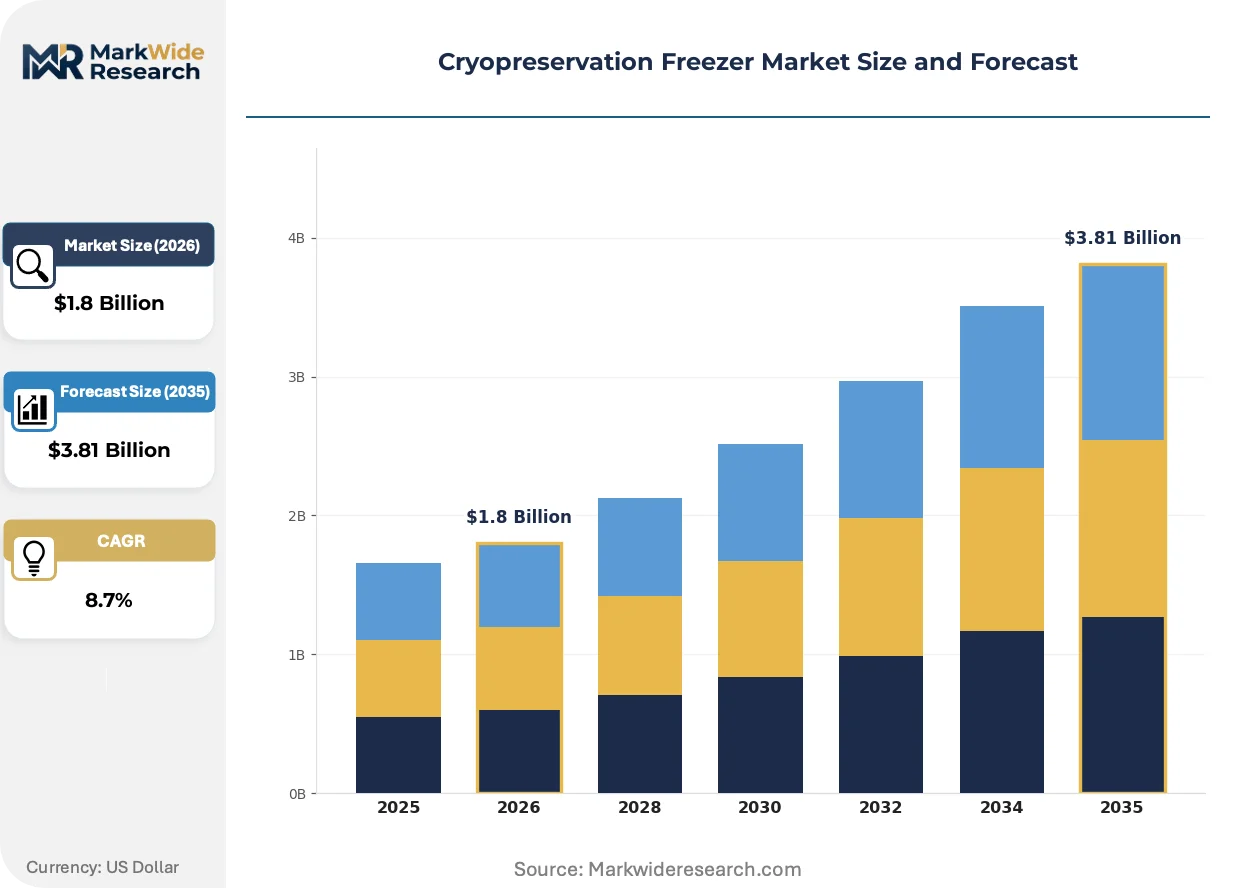
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryopreservation Freezer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Freezers, Portable Freezers, Ultra-Low Freezers, Cryogenic Storage Units Technology: Mechanical Cooling, Cryocoolers, Liquid Nitrogen, Thermoelectric Systems End User: Biobanks, Research Institutions, Healthcare Facilities, Pharmaceutical Companies Application: Cell Preservation, Tissue Preservation, Stem Cell Storage, Vaccine Storage |
| Companies Covered | Thermo Fisher Scientific Inc., Custom Biogenic Systems, Merck KGaA, Linde LLC, PHC Holdings Corp., Azenta US Inc., Chart Industries Inc., BioLife Solutions Inc., Planer PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryopreservation Freezer Market Emerging Trajectories
Modular freezer architecture is replacing monolithic storage designs as biobanks seek scalable capacity expansion without disrupting operational sample repositories. Three developments are restructuring competitive requirements.
Mechanical cascade refrigeration is modularizing into swappable compressor units that enable field replacement without decommissioning entire freezer banks. Biobank operators in the United States are adopting these configurations to minimize sample transfer risk during maintenance cycles. This architecture is compressing total cost of ownership calculations by reducing downtime penalties and extending equipment service life.
EU F-Gas Regulation phase-down schedules are mandating hydrofluorocarbon refrigerant transitions for new equipment manufacturing. European freezer vendors are accelerating natural refrigerant adoption, primarily propane and ethane blends, to maintain market access. Ultra-low temperature product lines serving German pharmaceutical cold chains are most affected, with manufacturers redesigning compressor systems to accommodate flammable coolant chemistries.
Service unbundling is separating hardware procurement from validation and maintenance contracts in large biobank tenders. United States academic medical centers are increasingly sourcing equipment from one vendor while contracting specialized third-party firms for FDA 21 CFR Part 11 qualification and ongoing temperature mapping. This channel fragmentation is compressing manufacturer margin capture and elevating importance of open-system interoperability standards.
Cryopreservation Freezer Market Segmentation
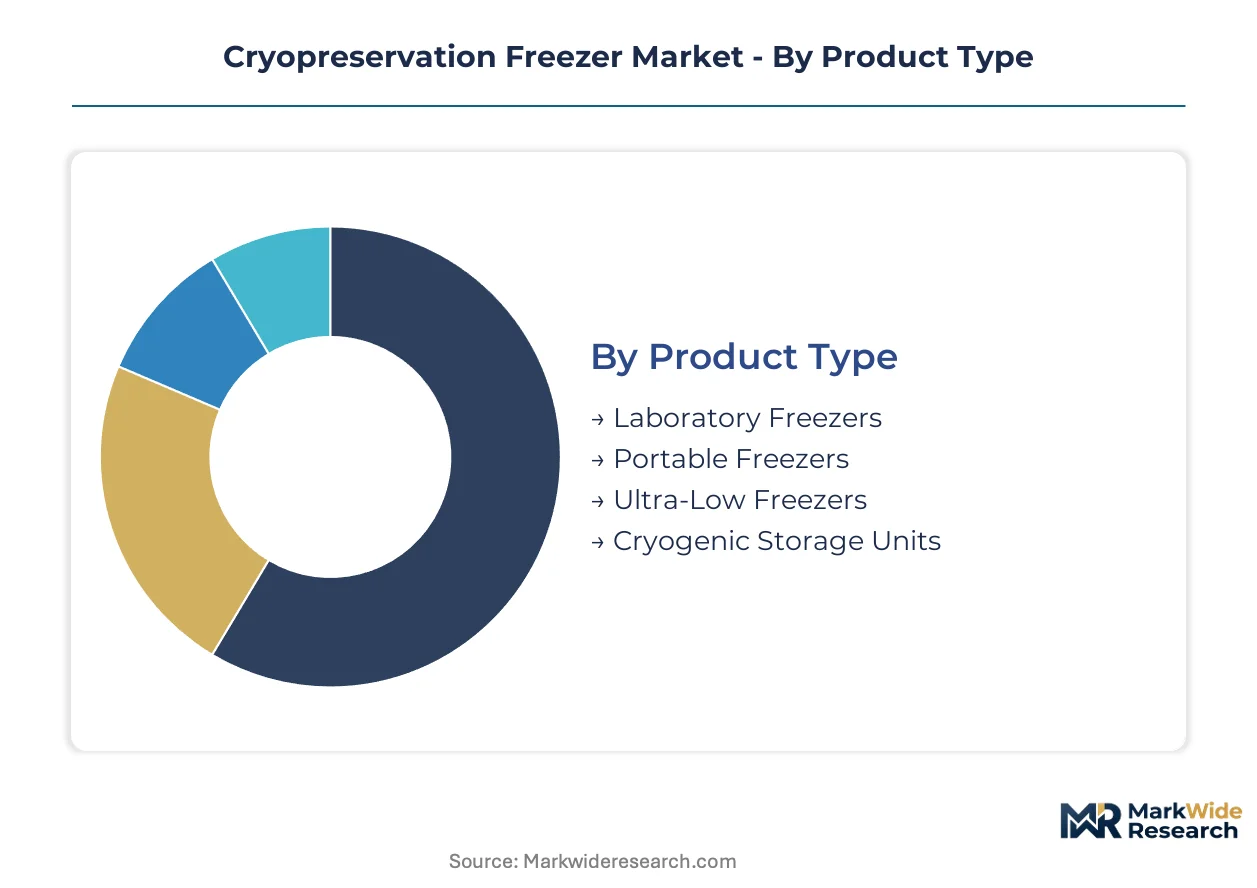
Cryopreservation freezer procurement decisions diverge sharply across user workflows. Biobank operators prioritize automation compatibility and chain-of-custody validation, while research laboratories emphasize capital efficiency and footprint flexibility. Understanding these segment-specific buying logics clarifies why product positioning must align with operational scale rather than temperature performance alone.
Product Type:
Purchase volume and facility infrastructure determine which freezer architecture biobank procurement committees specify.
- Ultra-Low Freezers:Mechanical cascade systems maintain minus 80 to minus 150 degrees Celsius through dual-stage compression. United States academic medical centers are replacing aging units ahead of EPA SNAP refrigerant phase-down deadlines, compressing replacement cycles.
- Cryogenic Storage Units:Liquid nitrogen vapor-phase systems achieve minus 196 degrees Celsius uniformity through vacuum-insulated dewar construction with robotic inventory retrieval. Stem-cell therapy manufacturers in Germany are specifying these for CAR-T production facilities.
- Laboratory Freezers:Compact under-counter units serve discrete research workflows with minus 20 to minus 40 degrees Celsius capacity.
- Portable Freezers:Battery-powered transport units bridge clinical sample collection sites to central biobank facilities.
Ultra-Low Freezers lead on scale; Cryogenic Storage Units lead on momentum.
Technology:
Cooling method selection locks buyers into distinct refrigerant supply chains, maintenance protocols, and regulatory compliance pathways.
- Liquid Nitrogen:Cryogenic fluid delivers minus 196 degrees Celsius through controlled vapor-phase exposure, eliminating compressor maintenance and refrigerant regulatory exposure. Japanese regenerative medicine infrastructure investments are expanding vapor-phase capacity.
- Mechanical Cooling:Cascade refrigeration using hydrofluorocarbon or natural refrigerant blends serves minus 80 degree applications with lower operating costs. EPA SNAP restrictions are forcing United States manufacturers toward propane and ethane coolant transitions.
- Cryocoolers:Stirling-cycle and Gifford-McMahon systems provide closed-cycle cooling for specialized research instruments.
- Thermoelectric Systems:Solid-state Peltier cooling serves portable and point-of-care applications where compressor noise and vibration are prohibitive.
Liquid Nitrogen commands premium positioning; Mechanical Cooling retains volume dominance.
End User:
Capital deployment scale and sample custody requirements segment buyer sophistication and contract complexity.
- Biobanks:Automated high-capacity repositories manage millions of specimens with robotic retrieval, barcode tracking, and FDA 21 CFR Part 11 validation. Large-scale installations in the United States are displacing discrete laboratory purchases.
- Pharmaceutical Companies:Cold-chain integration from manufacturing through distribution demands validated temperature mapping and redundant backup systems. German pharmaceutical clusters are building dedicated cryogenic capacity for advanced therapy medicinal products.
- Research Institutions:Academic laboratories prioritize equipment cost and flexibility over automation integration.
- Healthcare Facilities:Hospital biorepositories balance clinical sample custody requirements against capital budget constraints.
Biobanks concentrate automation investment; Pharmaceutical Companies drive specification escalation.
Application:
Biological material type dictates temperature uniformity requirements, storage duration, and retrieval frequency.
- Stem Cell Storage:Pluripotent and induced pluripotent cell lines require minus 196 degrees Celsius vapor-phase preservation to maintain viability across decades. CAR-T therapy commercialization in Japan is expanding demand for validated cryogenic capacity.
- Cell Preservation:Primary cell cultures and cell lines for research use tolerate minus 80 to minus 150 degrees Celsius mechanical freezing with dimethyl sulfoxide cryoprotectant.
- Tissue Preservation:Organ and tissue specimens for transplantation or research require controlled-rate freezing and specialized cryoprotectant protocols.
- Vaccine Storage:mRNA and viral vector vaccines demand ultra-low temperature stability through distribution networks.
Stem Cell Storage anchors premium system deployment; Cell Preservation sustains volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping cryopreservation freezer procurement as biobank operators migrate investments toward jurisdictions with streamlined validation pathways. The United States, Germany, and Japan concentrate demand, yet compliance cost differentials are redirecting manufacturing capacity toward Singapore and South Korea.
United States
FDA 21 CFR Part 11 mandates are accelerating replacement cycles for legacy mechanical freezers in academic medical centers. The EPA SNAP refrigerant phase-down is forcing cascade system manufacturers toward propane and ethane blends. The Boston-Cambridge biotech corridor is deploying automated cryogenic storage for CAR-T manufacturing facilities.
Germany
EMA and EU MDR traceability requirements are elevating documentation burdens for clinical biobank equipment procurement. The EU F-Gas Regulation is mandating hydrofluorocarbon transitions for new ultra-low freezer manufacturing. The Heidelberg-Mannheim biopharma cluster is building dedicated vapor-phase capacity for advanced therapy medicinal products.
Japan
METI funding for regenerative medicine infrastructure is expanding liquid nitrogen storage capacity for induced pluripotent stem cell repositories. PMDA quality standards for cellular therapy products are enforcing strict temperature uniformity validation. The Kansai region around Osaka is concentrating automated biobank installations for pharmaceutical cold-chain integration.
India
CDSCO regulatory frameworks for biological sample storage remain underdeveloped, creating first-mover opportunities for automated system vendors. The Department of Biotechnology's biobank initiatives are establishing reference installations in public health institutions. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune is importing cryogenic capacity for clinical trial material storage.
Singapore
The Health Sciences Authority's streamlined medical device registration is attracting cryopreservation equipment manufacturers seeking Asia-Pacific market access. Government biomedical research funding is building centralized biorepository infrastructure. The one-north research precinct is consolidating automated storage systems for regional pharmaceutical headquarters operations.
Cryopreservation Freezer Market Vendor Landscape
Portfolio diversification dominates the current landscape as equipment vendors bundle cryopreservation media, validation services, and software platforms to capture recurring revenue streams. The market structure concentrates around diversified life-science conglomerates with diagnostic-to-storage workflow integration, mid-scale specialists in custom aluminum rack fabrication, and industrial gas suppliers leveraging cryogenic fluid distribution networks. Three archetypes anchor positioning: integrated workflow providers, hardware-centric fabricators, and cryogenic infrastructure operators. M&A activity and service unbundling represent the dominant competitive vectors reshaping vendor relationships with large biobank operators.
Within the integrated workflow tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify conglomerate strategies spanning reagent supply through validated storage hardware. Custom Biogenic Systems occupies a position among North American specialists focused on legacy infrastructure retrofit solutions. Linde LLC and Chart Industries Inc. represent industrial gas and cryogenic engineering archetypes with vapor-phase system deployment capabilities. These groupings illustrate how competitive positioning diverges between workflow-integrated platforms and point-solution hardware vendors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Custom Biogenic Systems |
| Merck KGaA |
| Linde LLC |
| PHC Holdings Corp. |
| Azenta US Inc. |
| Chart Industries Inc. |
| BioLife Solutions Inc. |
| Planer PLC |
| Others |
Supply Flow & Price Mechanics
Automated versus manual storage system bifurcation separates premium cryogenic installations from commodity mechanical units, with that divergence manifesting in both pricing power and supply chain configuration. FDA 21 CFR Part 11 validation requirements in the United States and EU MDR traceability mandates in Germany compress margins on standard ultra-low freezers while elevating pricing authority for integrated robotic systems with chain-of-custody software.
Pricing Analysis
Distributor margins on mechanical cascade systems are compressing as EPA SNAP refrigerant phase-downs force coolant transitions toward propane and ethane blends. Three-tier pricing structure across premium, standard, and economy levels reflects automation integration depth and validation documentation completeness. Pricing pressure stems from service unbundling trends in United States academic medical centers, where buyers separate hardware procurement from third-party FDA qualification. Research laboratories exhibit highest price sensitivity; stem-cell therapy manufacturers show lowest sensitivity due to sample viability risk.
Supply Chain Analysis
Domestic-content requirements under the EU F-Gas Regulation and Buy American provisions for federally funded biobanks in the United States are reshaping sourcing toward regional compressor fabrication. Vacuum-insulated dewar manufacturing concentrates in Germany, Japan, and the United States; cryogenic fluid distribution networks rest on industrial gas infrastructure anchored in these same markets. Single-source vulnerability runs through specialized aluminum rack fabrication for legacy retrofits. Distribution runs through life-science equipment distributors with validation service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryopreservation freezer market functions as a regulatory compounder where FDA 21 CFR Part 11 and EU MDR validation milestones continuously refresh replacement cycles and specification escalation.
For Market Incumbents: To counter margin compression from service unbundling, embed predictive maintenance software as standard hardware features to recapture recurring revenue streams. Backward integration into cryogenic fluid distribution networks secures supply continuity for vapor-phase system deployments. Lock in biobank automation contracts through middleware development for laboratory information management system integration. For New Entrants and Emerging Players: CDSCO regulatory frameworks in India remain underdeveloped, opening a window for automated cryogenic system vendors establishing reference installations before compliance maturation. Target Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune for clinical trial material storage capacity. Pursue software-defined storage partnerships with existing hardware incumbents lacking predictive analytics capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where validation expertise concentrates among aging cryogenic engineering cohorts in Japan and Germany. Five-to-ten-year viability favors vendors with integrated workflow platforms spanning reagent supply through validated storage hardware. Target acquisition archetype: mid-scale specialists in custom aluminum rack fabrication with installed base relationships in United States academic medical centers. Watch for EPA SNAP enforcement acceleration as inflection signal for mechanical cascade replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Compliance | EPA SNAP and EU F-Gas mandates force coolant chemistry redesigns for market access retention. |
| Biobank Automation Integration | Robotic inventory retrieval with FDA 21 CFR Part 11 validation anchors large-scale contract wins. |
| Software-Defined Storage Development | Predictive maintenance platforms transform hardware vendors into recurring revenue service providers. |
| Legacy Infrastructure Retrofit Kits | Aftermarket robotic retrieval upgrades capture margin from aging United States academic medical center installations. |
| Cryogenic Fluid Distribution Expansion | Industrial gas infrastructure control secures vapor-phase system deployment capacity for CAR-T manufacturing. |
Methodological Framework
Multiple input streams — primary interviews with biobank operations directors, pharmaceutical cold-chain managers, and cryogenic equipment procurement committees; secondary validation through FDA 510(k) filings, EU MDR technical documentation, and EPA SNAP regulatory dockets; plus customs records for cryogenic dewar and compressor trade flows — were reconciled through bottom-up and top-down triangulation. Conversations with biomedical engineers at United States academic medical centers and German advanced therapy medicinal product facilities informed automation adoption timelines. SEC filings from diversified life-science conglomerates and specialized equipment manufacturers provided financial benchmarking for margin structure analysis.
Historical shipment data for ultra-low and cryogenic storage units were cross-referenced against panel input from biobank operators regarding replacement cycle compression. The analytical framework modeled volume and value across product type, cooling technology, end-user sophistication tier, and application temperature requirement throughout the forecast period. CAGRs were derived from segment-level growth differentials weighted by installed base composition. Industry-specific forecast inputs included CAR-T therapy manufacturing capacity buildouts in Japan and regenerative medicine infrastructure investments in Germany.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant supply disruption or accelerated EU MDR enforcement timelines. Projections reflect assumptions regarding biobank automation adoption curves and regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Single Use Bioprocessing Market