
 RNA Isolation and Enrichment Reagent Market | 2026-2036
RNA Isolation and Enrichment Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
RNA Isolation and Enrichment Reagent Market Analytics
Pharmaceutical-grade RNA purity specifications is reorganizing procurement criteria across the value chain. Thermo Fisher Scientific leverages its integrated supply network to sustain bulk reagent availability for high-throughput sequencing workflows. QIAGEN dominates automated nucleic acid purification platforms, while Promega Corporation specializes in research-use reagent formulations that anchor its position in academic channels.
RNA isolation and enrichment reagents comprise buffered solutions, chaotropic salts, and silica-based or magnetic bead matrices engineered to lyse cells, stabilize nucleic acids, and selectively bind RNA with A260/A280 purity ratios exceeding 1.8 for downstream quantitative PCR or transcriptomic analysis. Magnetic bead kits capture the fastest-growing product category as clinical diagnostic laboratories automate extraction workflows for infectious disease panels. Pharmaceutical companies represent the deepest end-user margin pool, given their stringent lot-to-lot consistency requirements and validated supply agreements for GMP-compliant manufacturing.
FDA quality system regulations and ISO 13485 standards shape reagent performance benchmarks for in-vitro diagnostic applications, while EPA guidelines govern chemical waste disposal from precipitation-based protocols. EMA's In Vitro Diagnostic Medical Devices Regulation in Europe raises conformity assessment barriers for kit manufacturers seeking CE-marked access. Stakeholders must monitor evolving nucleic acid amplification technology standards and regional diagnostic regulatory harmonization to align R&D investment with compliant product roadmaps.
Market Dynamics
Automated nucleic acid extraction platforms are compressing manual workflow demand while tightening purity specifications for downstream sequencing applications. Pharmaceutical manufacturers now require GMP-validated reagent lots with documented chain-of-custody, forcing suppliers to reconfigure quality systems and inventory management.
Growth Catalysts
- Infectious disease panel expansion:Clinical diagnostic laboratories in the United States are scaling automated RNA extraction for respiratory and sexually transmitted infection screening, driving magnetic bead kit procurement.
- ISO 13485 certification mandates:In-vitro diagnostic manufacturers across Europe must demonstrate quality management compliance for CE-marked reagent kits, elevating certified supplier preference.
- Transcriptomic research funding:Academic medical centers in Germany and the United Kingdom are expanding single-cell RNA sequencing programs, sustaining research-use reagent demand.
Market Restraints
- Chaotropic salt cost volatility:Guanidinium thiocyanate and guanidinium hydrochloride prices fluctuate with specialty chemical supply chains concentrated in China, compressing reagent formulation margins.
- Silica membrane supply concentration:High-purity glass fiber membrane production clusters in Japan and Germany, creating single-source vulnerability for spin-column kit manufacturers.
- EMA MDR conformity assessment:Europe's In Vitro Diagnostic Medical Devices Regulation extends technical documentation review timelines, delaying new kit market entry by 12-18 months.
Strategic Opportunities
- Point-of-care molecular testing:Brazil and Mexico are expanding decentralized diagnostic infrastructure, creating demand for lyophilized reagent formats that eliminate cold-chain requirements.
- mRNA therapeutics manufacturing:Pharmaceutical companies require GMP-grade RNA isolation reagents for in-process control and release testing, opening premium pricing tiers.
- Artificial intelligence-assisted protocol optimization:Machine learning platforms are converging with automated liquid handling to reduce extraction failure rates and reagent consumption per sample.
Industry Challenges
- Nucleic acid amplification technician shortage:Clinical laboratories face recruitment gaps for molecular diagnostics specialists capable of troubleshooting qPCR inhibition and extraction failure modes.
- Cross-platform validation burden:Diagnostic manufacturers must revalidate reagent performance across multiple thermal cycler and sequencing instrument models, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNA Isolation and Enrichment Reagent Market |
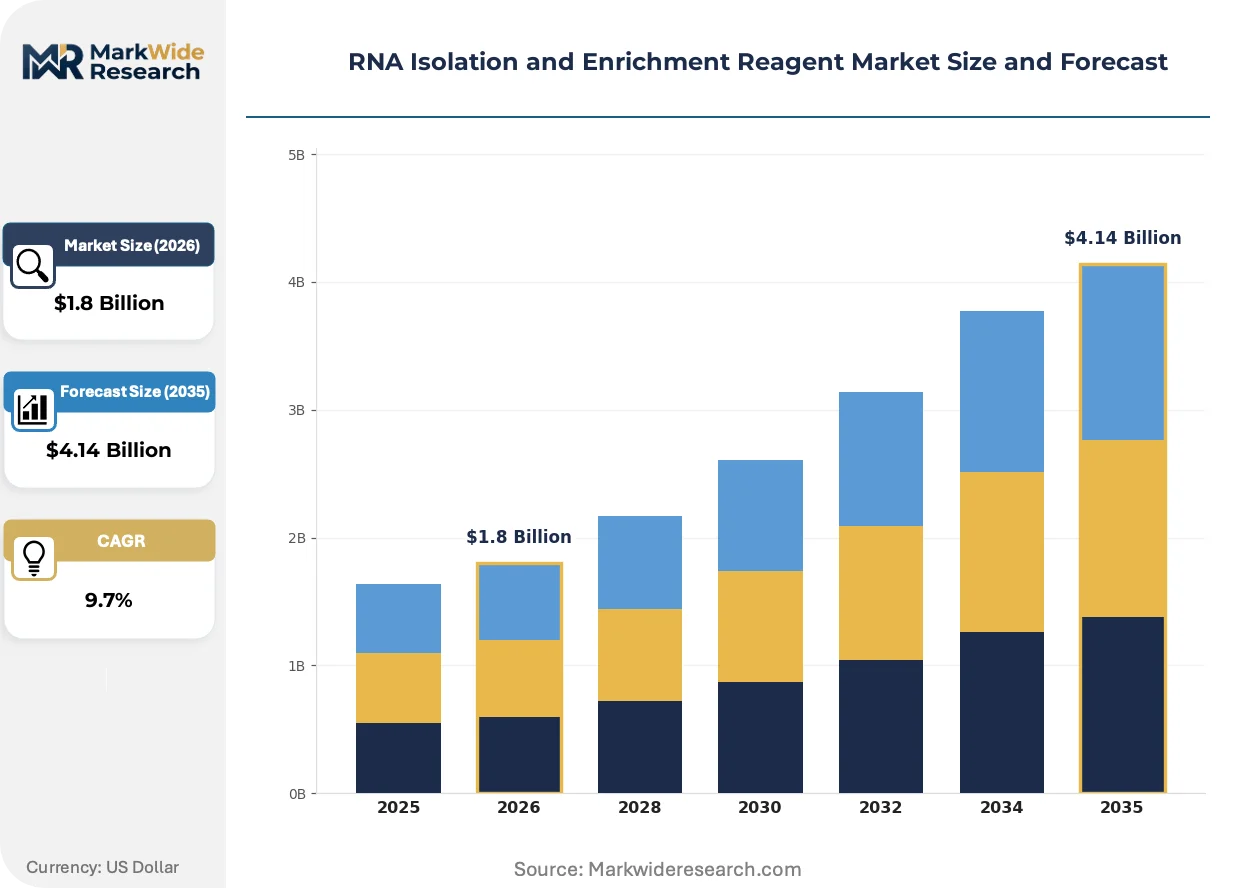
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Bead Kits, Column-Based Kits, Reagent Kits, Precipitation Kits Application: Research Laboratories, Diagnostic Laboratories, Academic Institutes, Healthcare Institutions End User: Pharmaceutical Companies, Biotechnology Firms, Diagnostic Labs, Academic Research Centers Technology: Polymerase Chain Reaction, Gel Electrophoresis, Nucleic Acid Amplification, Microarray Analysis |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, QIAGEN, F. Hoffmann-La Roche Ltd., Promega Corporation, Agilent Technologies Inc., Bio-Rad Laboratories Inc., Takara Bio Inc., Zymo Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNA Isolation and Enrichment Reagent Market Evolving Landscape
RNA isolation workflows are fragmenting into high-throughput automated pipelines and specialized manual protocols for rare sample types. This divergence is compressing mid-scale kit demand while rewarding suppliers with platform-agnostic reagent formulations.
Magnetic bead technology is bifurcating the product landscape. Silica-coated paramagnetic particles enable walk-away automation on liquid handling robots. Large reference laboratories in the United States are adopting these systems for COVID-19 and influenza surveillance programs. The technology is bifurcating market share between integrated platform vendors and open-system reagent suppliers.
EPA hazardous waste regulations are tightening disposal requirements for phenol-chloroform extraction protocols. Academic institutions must now document chemical waste manifests and implement neutralization procedures. Research laboratories in California and Massachusetts are responding by accelerating migration to column-based and bead-based alternatives that eliminate organic solvent handling.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for hospital-affiliated laboratories. Three national GPOs now control the majority of diagnostic reagent spending in the United States. Academic medical centers in Texas and Florida are most visibly affected, with purchasing departments mandating sole-source contracts for RNA isolation workflows.
RNA Isolation and Enrichment Reagent Market Segmentation
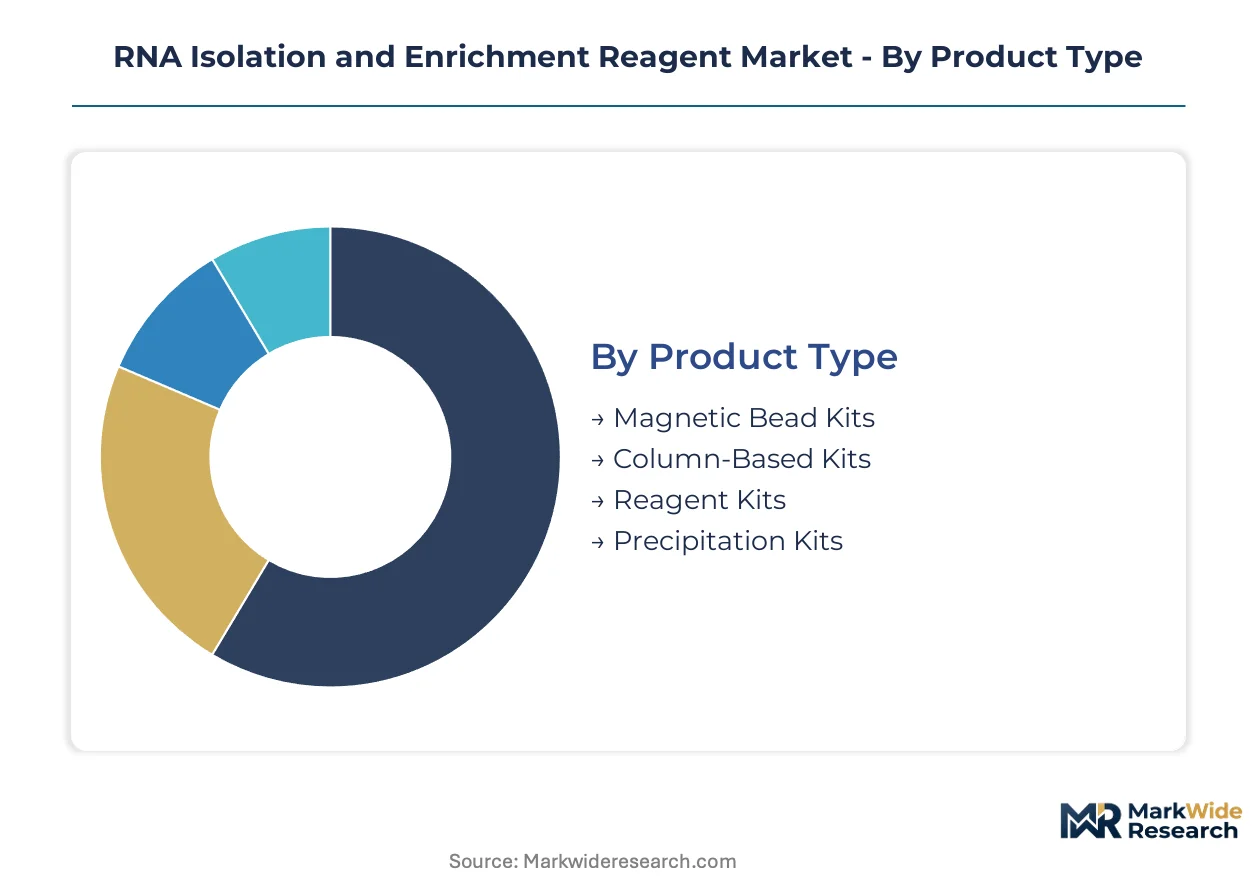
RNA isolation reagent procurement patterns diverge sharply across product formats and end-use settings. Automated diagnostic platforms favor magnetic bead workflows while academic researchers retain manual column-based protocols. Understanding these segment boundaries clarifies where suppliers must configure distinct quality systems and pricing architectures.
Product Type:
Magnetic bead kits dominate export-led supply chains serving high-throughput clinical laboratories, while precipitation kits remain concentrated in domestic research markets with established manual workflows.
- Magnetic Bead Kits:Silica-coated paramagnetic particles enable walk-away automation on liquid handling robots. Demand concentrates in United States reference laboratories running respiratory and sexually transmitted infection surveillance panels, driven by ISO 13485 certification requirements for in-vitro diagnostic workflows.
- Column-Based Kits:Spin-column formats using glass fiber membranes deliver intermediate throughput with minimal equipment investment. Academic medical centers in Germany and the United Kingdom sustain procurement for single-cell RNA sequencing programs, constrained by silica membrane supply concentration in Japan and Germany.
- Reagent Kits:Buffered solutions and chaotropic salts for customized protocol development serve specialized research applications.
- Precipitation Kits:Phenol-chloroform and alcohol-based methods retain niche use for rare sample types where membrane binding fails.
Column-based kits command the established base. The steepest expansion runs through magnetic bead formats.
Application:
Cost tier stratification separates premium-validated diagnostic workflows from economy-grade research protocols.
- Research Laboratories:Academic and government facilities prioritize protocol flexibility over regulatory documentation. Procurement emphasizes reagent kits with customizable buffer formulations for non-standard sample matrices.
- Diagnostic Laboratories:Clinical reference labs require lot-to-lot consistency documentation and chain-of-custody records. United States hospital-affiliated laboratories drive magnetic bead kit volumes through consolidated group purchasing organization contracts.
- Academic Institutes:University core facilities balance cost constraints against publication-grade purity requirements, sustaining mid-tier column-based kit demand.
- Healthcare Institutions:Point-of-care settings in Brazil and Mexico are expanding decentralized molecular testing infrastructure, creating demand for lyophilized reagent formats.
Diagnostic laboratories concentrate premium spending. Research laboratories expand most quickly in emerging markets.
End User:
Customer type determines margin structure, with pharmaceutical manufacturers demanding GMP-validated lots at premium pricing tiers.
- Pharmaceutical Companies:mRNA therapeutic manufacturers require GMP-grade RNA isolation reagents for in-process control and release testing. These end users negotiate validated supply agreements with documented manufacturing change control procedures.
- Biotechnology Firms:Mid-size drug developers balance research-scale flexibility against emerging clinical diagnostic requirements, creating hybrid procurement patterns.
- Diagnostic Labs:Commercial testing facilities prioritize automation compatibility and regulatory pre-certification over formulation customization.
- Academic Research Centers:Grant-funded investigators remain price-sensitive, driving reagent kit demand through institutional purchasing agreements.
Pharmaceutical companies anchor the premium tier. Biotechnology firms are climbing the fastest as therapeutic pipelines mature.
Technology:
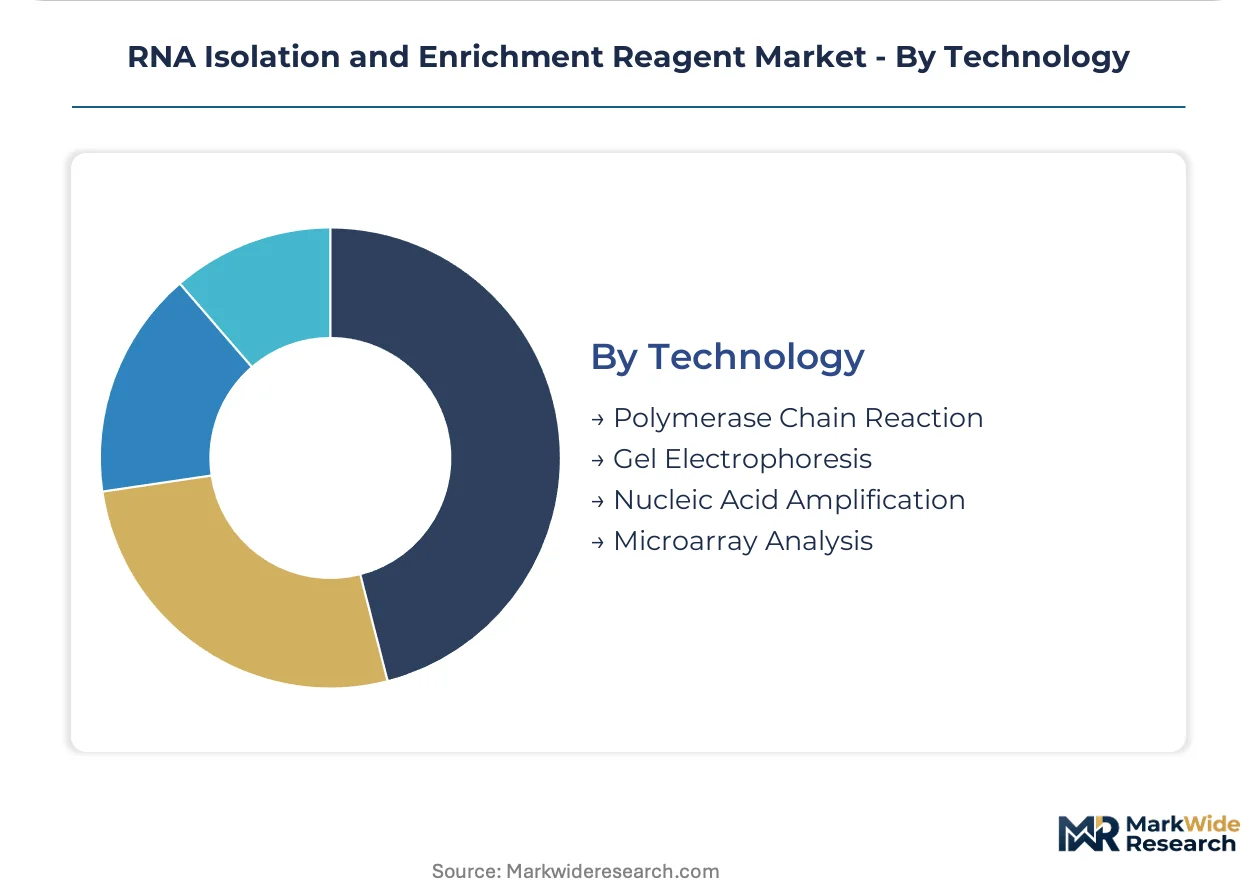
Application maturity determines reagent specification stringency, with amplification-based workflows imposing the tightest purity thresholds.
- Polymerase Chain Reaction:qPCR and RT-PCR applications require A260/A280 purity ratios exceeding 1.8 to prevent amplification inhibition. Clinical diagnostic laboratories in the United States scale automated extraction specifically for infectious disease panel testing.
- Nucleic Acid Amplification:Isothermal and digital amplification methods extend sensitivity requirements, driving demand for high-integrity RNA with minimal genomic DNA contamination.
- Gel Electrophoresis:Traditional separation methods retain use for educational settings and quality control verification of extraction yield.
- Microarray Analysis:Transcriptome profiling applications require specialized enrichment reagents for ribosomal RNA depletion prior to hybridization.
PCR-based workflows command the installed base. Nucleic acid amplification methods are gaining share fastest in point-of-care development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical manufacturing for chaotropic salts and silica membranes clusters in China, Japan, and Germany, creating supply dependencies that shape regional procurement strategies. Reagent kit assembly and quality validation concentrate near major diagnostic and pharmaceutical demand centers.
United States
Hospital-affiliated reference laboratories in Texas and Florida drive magnetic bead kit volumes through group purchasing organization contracts. FDA quality system regulations enforce lot-to-lot consistency documentation for in-vitro diagnostic applications. Academic medical centers in Boston and the San Francisco Bay Area anchor single-cell RNA sequencing demand for research-use reagents.
Germany
EMA's In Vitro Diagnostic Medical Devices Regulation elevates conformity assessment barriers for CE-marked kit market entry. Transcriptomic research funding flows to university core facilities in Heidelberg and Munich, sustaining column-based kit procurement. Baden-Württemberg hosts precision diagnostics manufacturers requiring ISO 13485-certified reagent suppliers.
China
Guanidinium thiocyanate production concentrates in Jiangsu and Shandong provinces, exposing reagent formulators to specialty chemical price volatility. NMPA medical device regulations tighten nucleic acid extraction kit registration requirements for clinical diagnostic use. Yangtze River Delta biotech clusters in Shanghai and Suzhou expand automated platform adoption for infectious disease surveillance.
United Kingdom
Academic medical centers in Cambridge and Oxford expand single-cell RNA sequencing programs, driving research-use reagent demand. MHRA post-Brexit regulatory frameworks diverge from EMA MDR implementation timelines, creating dual compliance burdens for kit suppliers. London-based contract research organizations negotiate validated supply agreements for GMP-compliant manufacturing.
Brazil
ANVISA medical device regulations govern import registration for diagnostic reagent kits serving public health laboratory networks. Decentralized molecular testing infrastructure expansion in São Paulo and Minas Gerais creates demand for lyophilized reagent formats. Federal university hospitals in Rio de Janeiro retain manual column-based workflows for research applications.
RNA Isolation and Enrichment Reagent Market Competitive Landscape
Concentration sits with diversified life science conglomerates that leverage integrated supply networks and automated platform ecosystems. The competitive structure tiers across premium-validated diagnostic suppliers, mid-scale research reagent specialists, and regional chemical manufacturers. Three archetypes dominate: integrated platform vendors bundling hardware and consumables, open-system reagent suppliers serving multiple automation brands, and specialty chemical producers supplying raw chaotropic salts and membrane matrices. Competitive moves center on strategic partnerships with diagnostic instrument manufacturers and backward integration into high-purity chemical production.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated supply network archetype. QIAGEN occupies a position within the automated platform vendor tier. Research reagent specialists include Promega Corporation and Zymo Research Corporation. Japanese life science tool providers such as Takara Bio Inc. represent the Asia-Pacific manufacturing base. Regional chemical manufacturers in China and Europe supply upstream raw materials to kit assemblers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| QIAGEN |
| F. Hoffmann-La Roche Ltd. |
| Promega Corporation |
| Agilent Technologies Inc. |
| Bio-Rad Laboratories Inc. |
| Takara Bio Inc. |
| Zymo Research Corporation |
| Others |
Value Network & Pricing Analysis
Magnetic bead format substitution for silica spin-columns is redrawing procurement economics and geographic sourcing patterns simultaneously. Clinical diagnostic laboratories in the United States now prioritize automated workflows that command premium pricing tiers, while academic researchers in Germany and the United Kingdom sustain mid-tier column-based demand constrained by membrane supply bottlenecks. This format migration concentrates pricing power with integrated platform vendors capable of bundling hardware and consumables.
Pricing Analysis
FDA quality system regulations dictate the pricing tier structure across diagnostic and research-use segments. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical-grade lots from ISO 13485-certified diagnostic kits and research-use formulations. Price differentiation rests on certification grade and volume scale, with pharmaceutical manufacturers showing least price sensitivity due to validated supply agreement requirements. Cost compression in research-grade tiers is intensifying because group purchasing organizations consolidate hospital-affiliated laboratory procurement.
Supply Chain Analysis
Jiangsu and Shandong province production of guanidinium thiocyanate anchors global chaotropic salt supply for reagent formulators. High-purity silica membrane manufacturing draws from Japanese and German specialty glass fiber producers, creating single-source vulnerability for spin-column kit assemblers. Supply chain risk centers on specialty chemical price volatility tied to Chinese environmental enforcement cycles. Distribution runs through life science distributors serving diagnostic instrument manufacturers and direct contracts with pharmaceutical quality departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA isolation and enrichment reagent demand sits in early-cycle expansion as mRNA therapeutic manufacturing scales validated GMP supply requirements. Pharmaceutical pipeline maturation and infectious disease panel automation create durable tailwinds for premium-tier suppliers.
For Market Incumbents: Secure backward integration into high-purity chaotropic salt production to defend margin position against Chinese supply volatility. Lock in multi-year validated supply agreements with mRNA therapeutic manufacturers before EMA MDR conformity assessment timelines extend competitive entry windows. For New Entrants and Emerging Players: Differentiate on lyophilized reagent formats for point-of-care molecular testing in Brazil and Mexico where cold-chain infrastructure gaps create white-space opportunity. Target decentralized diagnostic laboratory networks with open-system magnetic bead formulations compatible with multiple automation platforms. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors automated nucleic acid purification specialists with installed base momentum. Long-term viability over the next decade hinges on regulatory certification depth rather than formulation innovation alone. Watch EMA-FDA regulatory harmonization progress as the signal for cross-border scaling inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | EMA MDR compliance enables CE-marked kit access across European diagnostic laboratories. |
| Backward Integration into Chaotropic Salts | Captive supply of guanidinium thiocyanate insulates margins from Jiangsu province price volatility. |
| Lyophilized Format Development | Cold-chain elimination opens ANVISA-regulated procurement channels in Brazilian public health networks. |
| Automated Platform Partnership | Liquid handling robot compatibility secures reference laboratory contracts through GPO sole-source agreements. |
| GMP Validation Infrastructure Buildout | Pharmaceutical-grade lot documentation captures mRNA therapeutic in-process control spending. |
Research Methodology
Cross-validation between primary interviews with reagent procurement managers and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with diagnostic laboratory directors, pharmaceutical quality affairs leads, academic core facility managers, and group purchasing organization contract specialists combined with EMA MDR technical documentation, ISO 13485 certification databases, and NMPA registration records. Bottom-up demand modeling from end-user procurement patterns triangulates against top-down supply capacity assessments.
Sensitivity analysis across product format adoption curves, regulatory approval timelines, and raw material cost scenarios shapes the projection framework. Segmentation dimensions include product type, application setting, end-user category, and technology workflow across the analysis window. CAGRs derive from fitted growth curves calibrated to pharmaceutical pipeline expansion rates and diagnostic automation penetration benchmarks. mRNA therapeutic manufacturing capacity buildouts and infectious disease panel menu expansion serve as key forecast inputs.
Material uncertainties — EMA MDR implementation delays, Chinese environmental policy shifts affecting chaotropic salt production, and nucleic acid amplification technician shortage severity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization progress and automation adoption continuity. Practitioners should keep alternative scenarios live as ISO 13485 certification backlog conditions and GPO consolidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Cryopreservation Equipment Market