
 Global Latex Agglutination Test Kits Market | 2026-2036
Global Latex Agglutination Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Latex Agglutination Test Kits Market Foresight
The EU In Vitro Diagnostic Regulation is consolidating procurement standards across European hospital networks and reference laboratories. Bio-Rad Laboratories leverages its CE-IVD portfolio and quality management systems to sustain long-term supply agreements with national health services. Thermo Fisher Scientific anchors its position through integrated reagent-instrument workflows that reduce laboratory validation burdens. Meridian Bioscience differentiates via specialized infectious disease panels targeting Streptococcus and C. difficile detection.
Latex agglutination test kits employ polystyrene or latex particles coated with antibodies or antigens that visibly clump when binding target analytes in serum, plasma, or whole blood samples. These assays serve primarily as cost-effective screening and confirmatory tools for infectious pathogens, blood group antigens, and autoimmune markers in clinical and transfusion medicine settings. Qualitative kits dominate routine screening workflows in resource-limited settings where instrument infrastructure remains scarce, while automated agglutination systems capture margin pools in high-throughput reference laboratories. Rapid test kits are gaining traction in emergency departments and decentralized clinics seeking same-result clinical decision-making without capital equipment investment.
The FDA's Class II medical device controls and the EU IVDR's performance evaluation requirements shape product development timelines and market access pathways for kit manufacturers. India's CDSCO and the country's BIS standards for medical devices create additional conformity layers for imports and domestic production. China's NMPA enforces rigorous clinical trial data for IVD registration, extending approval cycles for multinational suppliers. Stakeholders must monitor evolving notified body capacity in Europe and divergent evidence requirements across major jurisdictions to align regulatory investment with commercial prioritization.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing approval timelines and forcing manufacturers to consolidate quality management systems around CE-IVD certification pathways. This regulatory pressure is reshaping competitive positioning by favoring kit suppliers with established notified body relationships and clinical evidence libraries.
Growth Catalysts
- India's CDSCO fast-track pathways:The country's streamlined medical device registration for essential diagnostics is accelerating kit approvals for tuberculosis and enteric fever screening. Government health programs now mandate decentralized testing at primary health centers.
- Polystyrene bead surface chemistry advances:Enhanced antibody conjugation protocols are improving test sensitivity for C. difficile toxin detection. Reference laboratories in Germany and Japan are validating these next-generation formulations for bloodstream infection panels.
- Point-of-care workflow integration:Emergency departments in Brazil and South Africa are adopting rapid agglutination formats that eliminate cold-chain requirements. These kits enable same-shift clinical decisions without capital equipment investment.
Market Restraints
- Natural rubber latex supply volatility:Malaysia and Thailand concentrate 85% of global latex feedstock production. Climate-driven yield fluctuations and plantation labor shortages are creating raw material cost instability for particle manufacturers.
- EU IVDR performance evaluation burdens:The regulation's expanded clinical evidence requirements for Class B and C devices are extending kit recertification cycles to 18-24 months. Smaller manufacturers lack the capital reserves to maintain parallel technical documentation teams.
- Nucleic acid amplification test substitution:PCR and isothermal amplification platforms are capturing confirmatory testing volumes for Streptococcus and respiratory pathogen panels. Hospital laboratories in the US and Western Europe are prioritizing instrument-based workflows over manual agglutination methods.
Strategic Opportunities
- Vietnam's provincial laboratory network expansion:The country's Ministry of Health is deploying 600 district-level diagnostic hubs by 2027. These facilities require instrument-free screening tools for dengue fever and typhoid surveillance.
- Autoimmune marker multiplexing:Converging latex particle engineering with lateral flow architecture enables simultaneous detection of rheumatoid factor, anti-CCP, and ANA antibodies. Rheumatology clinics in Australia and Canada are piloting these consolidated panels.
- Direct-to-clinic distribution platforms:E-procurement networks in Kenya and Nigeria are bypassing traditional distributor markups for public sector tenders. Manufacturers establishing local fulfillment centers can capture 15-20 point margin improvements on routine infectious disease kits.
Industry Challenges
- ISO 13485 auditor capacity constraints:The EU's notified body restructuring has reduced available quality system certification resources by 40%. Manufacturers face 9-12 month queue delays for surveillance audit scheduling.
- Legacy instrument integration complexity:Automated agglutination analyzers from the 2010s lack standardized data exchange protocols. Hospital IT departments in Italy and Spain are demanding HL7 FHIR compatibility that requires firmware redevelopment.
- Antibody lot-to-lot consistency:Polyclonal serum sourcing from immunized animals introduces binding affinity variation that invalidates control ranges. Production teams must maintain parallel validation studies across 3-5 donor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Latex Agglutination Test Kits Market |
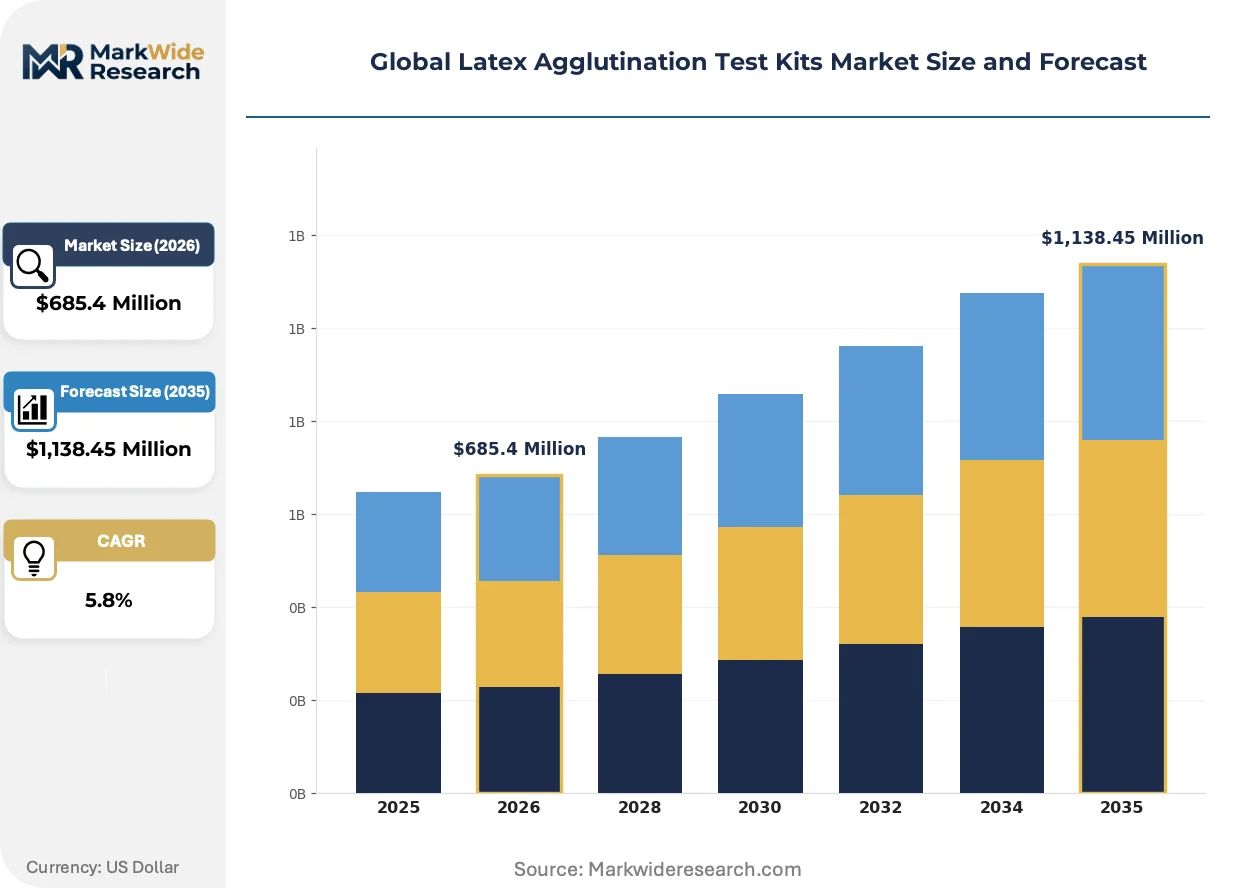
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Qualitative Kits, Quantitative Kits, Rapid Test Kits, Multiplex Kits Technology: Manual Agglutination, Automated Agglutination, Microplate Agglutination, Slide Agglutination Application: Infectious Disease Detection, Blood Typing, Hormone Assays, Autoimmune Disorder Diagnosis, Allergy Testing End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Clinical Pathology Labs, Biotech Companies |
| Companies Covered | Bio-Rad Laboratories Inc., HiMedia Laboratories, Thermo Fisher Scientific Inc., Atlas Medical GmbH, Creative Diagnostics, Cardinal Health Inc., Becton Dickinson and Company, Meridian Bioscience Inc., bioMérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Latex Agglutination Test Kits Market Shifts & Advancements
Surface-engineered nanoparticles and digital readout technologies are displacing conventional visual interpretation methods. These advances are compressing result turnaround times while expanding test menu breadth beyond traditional infectious disease applications.
Carboxyl-functionalized latex microspheres with uniform 0.8-1.2 micron diameters are electrifying quantitative agglutination assay development. Clinical chemistry laboratories in South Korea and the Netherlands are adopting these materials for high-precision C-reactive protein and rheumatoid factor measurements. The technology is enabling instrument-free quantitative readouts through smartphone camera colorimetry, collapsing the cost barrier between reference laboratory and point-of-care testing tiers.
The FDA's enforcement discretion policy for certain Class I IVDs is creating parallel regulatory pathways for agglutination-based COVID-19 serology and influenza screening. Manufacturers are bifurcating product portfolios between 510(k) cleared formats for hospital procurement and research-use-only variants for international distribution. Academic medical centers in the US are leveraging this flexibility to validate custom antibody panels without full premarket submission requirements.
Hospital group purchasing organizations in the US are consolidating infectious disease diagnostics into multi-year sole-source contracts. These arrangements bundle latex agglutination kits with automated immunoassay platforms and molecular systems, displacing standalone kit purchasing at independent laboratories. The concentration of buying power is most visible in the Southeast and Midwest, where regional health systems now control 60-70% of inpatient infectious disease testing volumes through centralized procurement committees.
Global Latex Agglutination Test Kits Market Segmentation
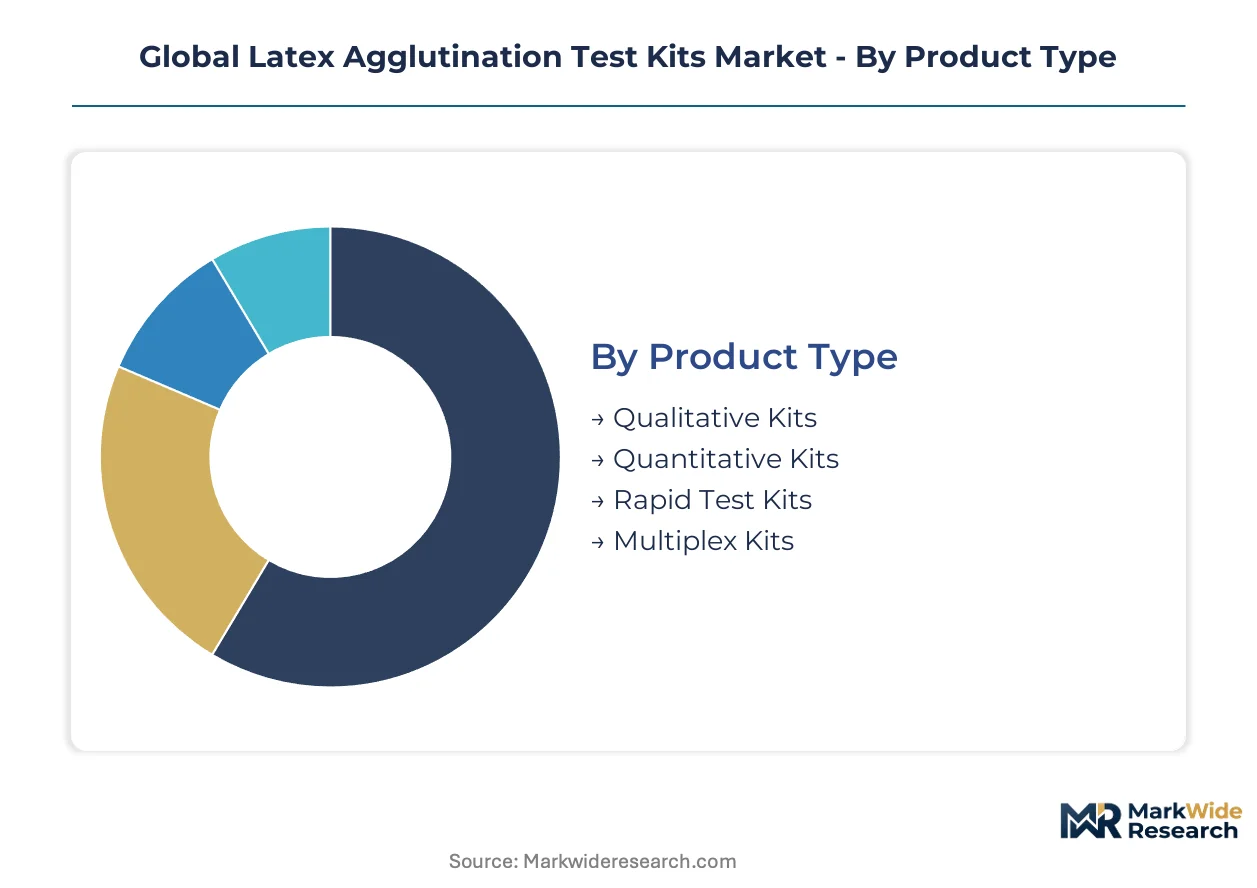
Latex agglutination test kits fragment across four intersecting dimensions that determine pricing power and regulatory pathway. Product format and automation level together dictate whether kits penetrate decentralized clinics or anchor centralized laboratory workflows.
Product Type:
Volume economics favor single-analyte formats while premium pricing attaches to multiplexed and quantitative configurations.
- Qualitative Kits:Binary positive-negative readouts using visible particle clumping dominate tuberculosis and streptococcal screening in India's primary health centers. India's CDSCO fast-track pathways prioritize these formats for government tenders where instrument infrastructure remains absent.
- Quantitative Kits:Calibrated particle suspensions with turbidimetric endpoints enable precise C-reactive protein and rheumatoid factor measurements. Reference laboratories in Germany and Japan validate these for high-precision autoimmune panels where numerical cutoffs guide therapy decisions.
- Rapid Test Kits:Single-use cassettes with dried reagent zones eliminate cold-chain requirements for emergency department workflows in Brazil and South Africa.
- Multiplex Kits:Spatially separated antibody zones on shared reaction membranes detect multiple pathogens simultaneously, gaining traction in dengue-chikungunya differential diagnosis.
Mature deployment sits with qualitative formats in resource-limited settings. Newer deployment is concentrated in multiplex configurations for differential fever panels.
Technology:
Automation intensity separates capital-intensive hospital installations from instrument-free field diagnostics.
- Manual Agglutination:Technician-mediated tube or slide mixing remains the default for blood banks in Italy and Spain performing ABO-Rh confirmation. These workflows absorb skilled labor but avoid analyzer capital expenditure in low-volume transfusion services.
- Automated Agglutination:Robotics-controlled pipetting and imaging systems process 200-400 samples hourly for hospital infectious disease panels in the US and Western Europe. The EU IVDR's performance evaluation requirements favor suppliers with integrated reagent-instrument bundles that reduce laboratory validation burdens.
- Microplate Agglutination:96-well formats with photometric endpoints enable batch processing of autoimmune antibody screens in high-throughput reference laboratories.
- Slide Agglutination:Glass-mounted reaction chambers suit immediate bedside testing for enteric fever in Vietnam's district-level diagnostic hubs.
Manual methods dominate blood bank confirmation workflows. Automated systems are expanding fastest in hospital core laboratories seeking labor arbitrage.
Application:
Disease prevalence patterns and reimbursement granularity shape which test menus achieve commercial scale.
- Infectious Disease Detection:Pathogen-specific antibody and antigen detection covers streptococcal pharyngitis, C. difficile toxin, and enteric fever. Government health programs in India and Vietnam mandate decentralized screening at primary care tier for tuberculosis and typhoid surveillance.
- Blood Typing:ABO-Rh and extended antigen phenotyping secures transfusion safety in hospital blood banks and centralized collection centers. The EU's CE-IVD framework governs reagent validation for these critical safety applications.
- Hormone Assays:Particle-enhanced detection of human chorionic gonadotropin and thyroid markers competes with chemiluminescence platforms in clinical chemistry laboratories.
- Autoimmune Disorder Diagnosis:Rheumatoid factor and anti-CCP antibody detection serves rheumatology clinics in Australia and Canada piloting consolidated lateral flow panels.
- Allergy Testing:Specific IgE detection against aeroallergens and food proteins occupies a niche in specialist immunology practices.
Infectious disease applications command the broadest geographic footprint. Autoimmune testing is climbing fastest as rheumatology clinics adopt consolidated screening protocols.
End User:
Procurement concentration and technical capability create distinct customer archetypes with diverging price sensitivity.
- Diagnostic Laboratories:Hospital-affiliated and independent testing facilities process high-volume infectious disease panels under quality accreditation schemes. US group purchasing organizations bundle agglutination kits with automated platforms through multi-year sole-source contracts.
- Research Institutes:Academic medical centers leverage FDA enforcement discretion for custom antibody panel validation without full premarket submissions.
- Blood Banks:Transfusion services prioritize lot-to-lot consistency for reagents with direct patient safety implications under strict national hemovigilance protocols.
- Clinical Pathology Labs:Community-based testing facilities in Kenya and Nigeria bypass traditional distributor markups through e-procurement networks.
- Biotech Companies:Diagnostic developers source bulk particle suspensions and antibody conjugates for in-house assay manufacturing.
Diagnostic laboratories represent the most mature procurement channel. Clinical pathology labs in emerging markets are gaining share fastest through direct distribution platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia and Thailand dominate natural rubber latex feedstock production, while diagnostic consumption concentrates in India, Germany, and the United States. This geographic split between raw material supply and end-use demand shapes procurement strategies and logistics networks for kit manufacturers.
India
Government health programs mandate decentralized tuberculosis and enteric fever screening at primary health centers. CDSCO fast-track pathways accelerate approvals for instrument-free diagnostic formats. Maharashtra and Karnataka host manufacturing clusters where domestic producers assemble kits for public sector tenders.
Germany
Reference laboratories validate next-generation polystyrene bead formulations for bloodstream infection panels. EU IVDR performance evaluation requirements favor suppliers with established notified body relationships. The Rhine-Ruhr metropolitan region concentrates quality-accredited diagnostic facilities serving hospital networks across Central Europe.
United States
Hospital group purchasing organizations consolidate infectious disease diagnostics into multi-year sole-source contracts. FDA Class II medical device controls shape product development timelines for domestic manufacturers. The Southeast and Midwest regional health systems control the majority of inpatient testing volumes through centralized procurement committees.
Japan
Clinical chemistry laboratories adopt carboxyl-functionalized latex microspheres for high-precision autoimmune measurements. PMDA enforces rigorous clinical trial data requirements for IVD registration. The Kanto region around Tokyo anchors high-throughput reference laboratory networks validating quantitative agglutination assays.
Brazil
Emergency departments in São Paulo and Rio de Janeiro adopt rapid agglutination formats that eliminate cold-chain requirements. ANVISA regulates medical device registration for imported diagnostic kits. Southeast Brazil hosts the country's largest hospital networks driving point-of-care workflow integration.
Global Latex Agglutination Test Kits Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with integrated reagent-instrument portfolios. Quality management system maturity and notified body relationships now determine market access more than price positioning. Three archetypes dominate: multinational platform suppliers bundling agglutination kits with automated systems; mid-cap specialists focusing on infectious disease panels; and regional manufacturers serving government tenders in emerging markets. Consolidation through strategic partnerships and geographic licensing agreements represents the primary competitive dynamic, alongside capacity expansion into fast-track regulatory jurisdictions.
Among diversified platform suppliers, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., and bioMérieux SA exemplify archetypes built around CE-IVD portfolio breadth and quality management infrastructure. These entities occupy positions where integrated reagent-instrument workflows reduce laboratory validation burdens for hospital network customers. Meridian Bioscience Inc. represents the specialist tier, with positioning concentrated in targeted infectious disease detection formats. Regional tender specialists include HiMedia Laboratories, which anchors procurement relationships with government health programs in South Asia through domestic manufacturing presence.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc. |
| HiMedia Laboratories |
| Thermo Fisher Scientific Inc. |
| Atlas Medical GmbH |
| Creative Diagnostics |
| Cardinal Health Inc. |
| Becton Dickinson and Company |
| Meridian Bioscience Inc. |
| bioMérieux SA |
| Others |
Supply & Pricing Matrix
Polyclonal antibody production teams concentrated in Southeast Asian immunization facilities create labor-cost differentials that widen spreads between economy-tier rapid test kits and premium quantitative formats. CDSCO fast-track registration fees in India and EU IVDR performance evaluation costs in Europe further stratify end-user pricing across regulatory jurisdiction tiers.
Pricing Analysis
Margin tightening in economy-tier qualitative kits reflects raw material cost instability from Malaysian and Thai latex feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVD certified automated systems from CDSCO-registered manual formats and research-use-only variants. Price differentiation hinges on ISO 13485 quality system maturity and notified body relationship depth. Hospital group purchasing organizations in the US exhibit lowest price sensitivity through multi-year sole-source bundling, while Kenya's e-procurement clinical pathology labs drive hardest bargain terms.
Supply Chain Analysis
Freight cost premiums on temperature-sensitive antibody conjugates elevate landed costs for European and North American kit assemblers sourcing from Asian immunization facilities. Natural rubber latex feedstock concentrates in Malaysia and Thailand, while polystyrene bead manufacturing clusters in Germany and Japan. Raw material dependencies span plantation-grade latex, carboxyl-functionalized microspheres, and donor animal serum pools. Single-source vulnerability sits with Thai plantation labor shortages. Distribution runs through hospital group purchasing organizations in developed markets and direct-to-clinic e-procurement platforms in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU IVDR's 18-24 month recertification cycles and expanded clinical evidence requirements erect compliance moats that favor incumbent suppliers with capital reserves for parallel technical documentation teams.
For Market Incumbents: Cement notified body relationships and CE-IVD portfolio breadth to defend against nucleic acid amplification test substitution in hospital core laboratories. Prioritize backward integration into polystyrene bead surface chemistry to capture margin pools from next-generation C. difficile toxin detection formulations. Capacity expansion into Maharashtra and Karnataka manufacturing clusters secures domestic production credentials for India's government health program tenders. For New Entrants and Emerging Players: Smartphone camera colorimetry readout technology offers a technology-first wedge into instrument-free quantitative segments underserved by legacy visual interpretation formats. Target Vietnam's 600-district provincial laboratory network expansion for dengue fever and typhoid surveillance kits requiring zero cold-chain infrastructure. Pursue autoimmune marker multiplexing pilots with rheumatology clinics in Australia and Canada as the most penetrable application white-space. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap infectious disease panel specialists given EU IVDR consolidation pressure on smaller manufacturers lacking surveillance audit scheduling capacity. Long-term viability over a multi-year horizon favors targets with established PMDA clinical trial data libraries and CDSCO domestic manufacturing presence. Watch ISO 13485 auditor queue delays as the signal indicating accelerated distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Portfolio Expansion | EU IVDR performance evaluation requirements favor suppliers with existing notified body relationships and clinical evidence libraries. |
| Backward Integration into Bead Chemistry | Carboxyl-functionalized latex microsphere production captures margin pools from high-precision autoimmune and CRP measurement demand. |
| CDSCO Fast-Track Registration | Streamlined medical device pathways in India accelerate kit approvals for government-mandated tuberculosis and enteric fever screening. |
| Direct-to-Clinic Distribution Platforms | E-procurement networks in Kenya and Nigeria bypass traditional distributor markups for 15-20 point margin improvements. |
| Multiplex Panel Development | Spatially separated antibody zones enable simultaneous dengue-chikungunya differential diagnosis for Vietnam's district-level diagnostic hubs. |
Research Methodology
CDSCO registration filings, EU IVDR performance evaluation documentation, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with regulatory affairs leads at kit manufacturers, biomedical engineers at reference laboratories, GPO contracts managers at US hospital systems, and procurement officers at India's primary health centers validated demand assumptions and pricing dynamics. Bottom-up unit economics triangulated against top-down infectious disease testing volume estimates across the analysis window.
Historical trendline analysis of latex agglutination kit shipments by product format, automation level, application area, and end-user channel anchored the projection framework. Segmentation modeling incorporated qualitative versus quantitative kit configurations, manual versus automated processing workflows, infectious disease versus autoimmune versus blood typing applications, and diagnostic laboratory versus point-of-care facility end-user archetypes. CAGRs were derived from regression analysis of segment-specific growth trajectories, with nucleic acid amplification substitution rates and IVDR compliance cost inflation as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural rubber latex supply disruption scenarios or accelerated PCR platform adoption in Western European hospital networks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market