
 Bioprocessing Systems Market | 2026-2036
Bioprocessing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprocessing Systems Market Analysis
Contract manufacturers is redrawing procurement patterns across the bioprocessing value chain as biotech firms outsource upstream and downstream operations. Thermo Fisher Scientific leverages its integrated consumables and instrumentation portfolio to anchor long-term service agreements. Sartorius AG specializes in single-use bioreactor technologies that dominate mid-scale biologics production. Danaher Corporation extends its filtration and chromatography reach through Pall Corporation's membrane expertise.
Bioprocessing systems encompass integrated equipment trains for cell culture, fermentation, filtration, and fluid management, typically operating under validated aseptic conditions with precise control of temperature, pH, dissolved oxygen, and shear forces to maintain cell viability and product titer. These systems serve the industrial production of monoclonal antibodies, recombinant proteins, viral vectors, and cell therapies. Cell culture systems command the largest installed base, while single-use technology within filtration systems and mixer systems captures the fastest replacement cycle as facilities retrofit stainless-steel lines. Automated systems integrated with advanced analytics are pulling margin pools toward data-driven process control platforms.
FDA's process validation guidance and EMA's good manufacturing practice framework for advanced therapy medicinal products shape equipment qualification requirements and batch release protocols. China's NMPA alignment with ICH Q5A through Q5D standards is opening market access for foreign bioprocessing equipment suppliers. The EU AI Act and FDA's emerging framework for artificial intelligence in manufacturing will determine how automated bioprocessing systems validate real-time release testing. Stakeholders must decide whether to build in-house digital twin capabilities or partner with specialized analytics platform vendors.
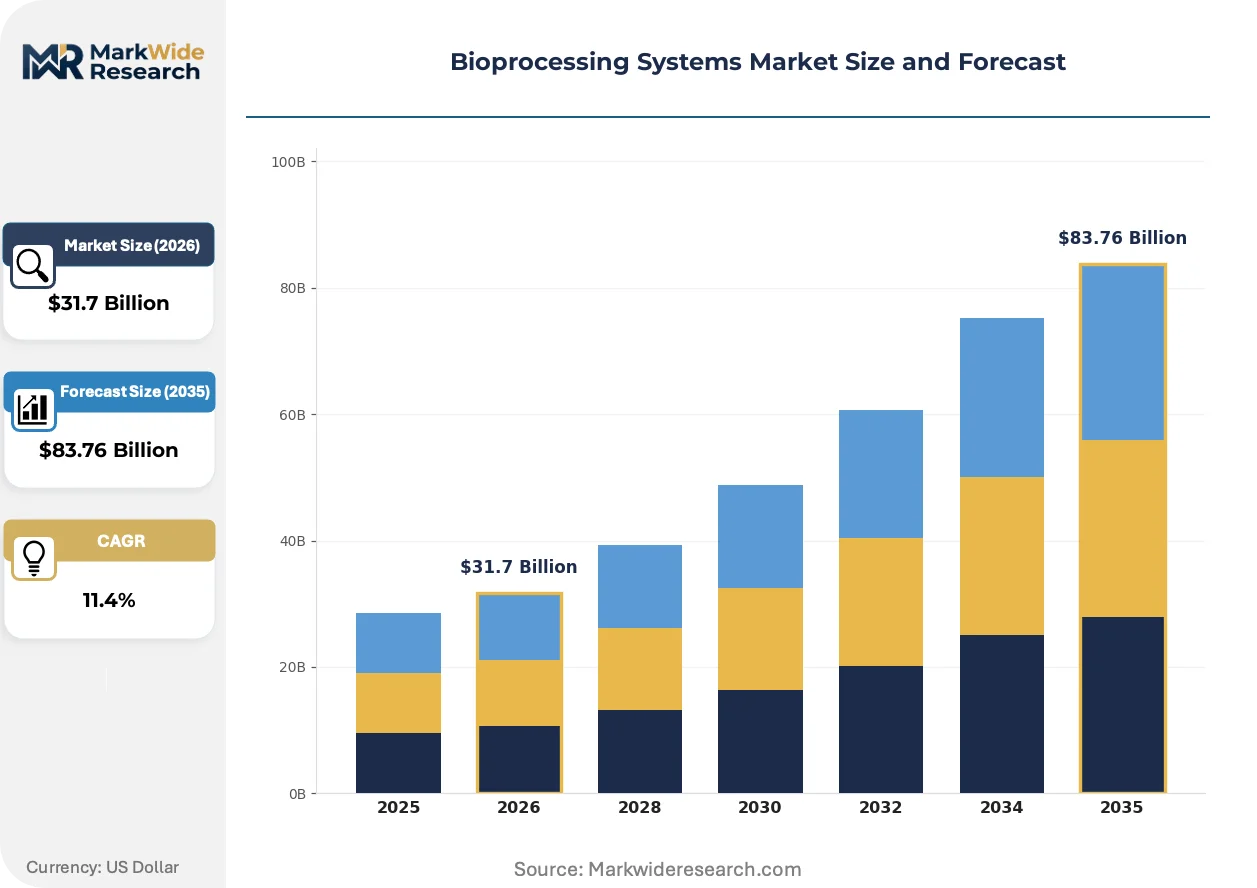
Market Dynamics
Single-use technology adoption is compressing equipment replacement cycles while contract manufacturers reconfigure procurement toward flexible capacity models. FDA and EMA contamination control guidance accelerates facility retrofit decisions.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Cell and gene therapy manufacturers require specialized bioprocessing infrastructure for viral vector production, expanding equipment demand across European manufacturing clusters.
- Continuous processing:Integrated perfusion bioreactor systems reduce facility footprint and operating costs, attracting investment from mid-scale biologics producers seeking operational efficiency.
- China's NMPA ICH alignment:Harmonized quality standards enable foreign equipment suppliers to access domestic biologics manufacturing expansion without duplicate validation protocols.
Market Restraints
- Resin and membrane supply concentration:Chromatography media production concentrates among limited specialized chemical suppliers, creating input cost volatility and allocation risk during demand surges.
- Stainless steel asset stranding:Existing fixed-tank infrastructure represents sunk capital that delays single-use conversion decisions at established multi-product facilities.
- Extractables and leachables testing burden:FDA polymer qualification requirements extend validation timelines for new single-use consumables, compressing supplier margins.
Strategic Opportunities
- India's CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore require modular bioprocessing trains to serve export-oriented biologics production.
- Real-time release testing:FDA's emerging AI manufacturing framework creates regulatory space for automated quality verification systems integrated with process analytical technology.
- Digital twin convergence:Bioprocess simulation platforms combined with IoT sensor networks enable predictive maintenance and batch optimization for continuous manufacturing lines.
Industry Challenges
- Bioprocess engineer scarcity:Specialized expertise in cell culture scale-up and aseptic operations remains concentrated among experienced practitioners, constraining facility startup timelines.
- Multi-modal facility integration:Hybrid stainless-steel and single-use architectures require complex validation matrices that extend commissioning schedules and regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprocessing Systems Market |
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $83.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Culture Systems, Fermentation Systems, Filtration Systems, Mixer Systems Application: Biologics Production, Vaccine Development, Cell Therapy, Gene Therapy End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Technology: Single-Use Technology, Automated Systems, Advanced Analytics, Fluid Management |
| Companies Covered | Thermo Fisher Scientific Inc., Sartorius AG, Danaher Corporation, Merck KGaA, Pall Corporation, Eppendorf SE, Lonza Group AG, Applikon Biotechnology B.V., GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprocessing Systems Market Emerging Trajectories
Automation and data integration are redefining how bioprocessing systems validate, control, and document production. Equipment vendors compete on analytics platforms rather than hardware specifications alone.
Modular skid-mounted bioreactor systems are fragmenting the traditional equipment procurement model. Cell therapy manufacturers and viral vector producers adopt these pre-validated units to compress facility build timelines. Standardized module interfaces enable rapid reconfiguration between batch and continuous modes, reducing capital risk for product pipeline transitions.
EU AI Act provisions for high-risk industrial applications establish conformity assessment requirements for automated bioprocessing control systems. Equipment manufacturers must document algorithmic transparency and validation datasets for real-time release testing implementations. German and Swiss biologics facilities face accelerated compliance timelines as notified bodies develop sector-specific guidance.
CDMOs now unbundle equipment procurement from long-term service agreements, forcing vendors to compete on consumables attach rates and technical support responsiveness. This purchasing pattern shift concentrates in the United States and Germany where contract manufacturing capacity expands fastest. Biotech sponsors prioritize equipment platforms with transferable process protocols across multiple manufacturing sites.
Bioprocessing Systems Market Segmentation
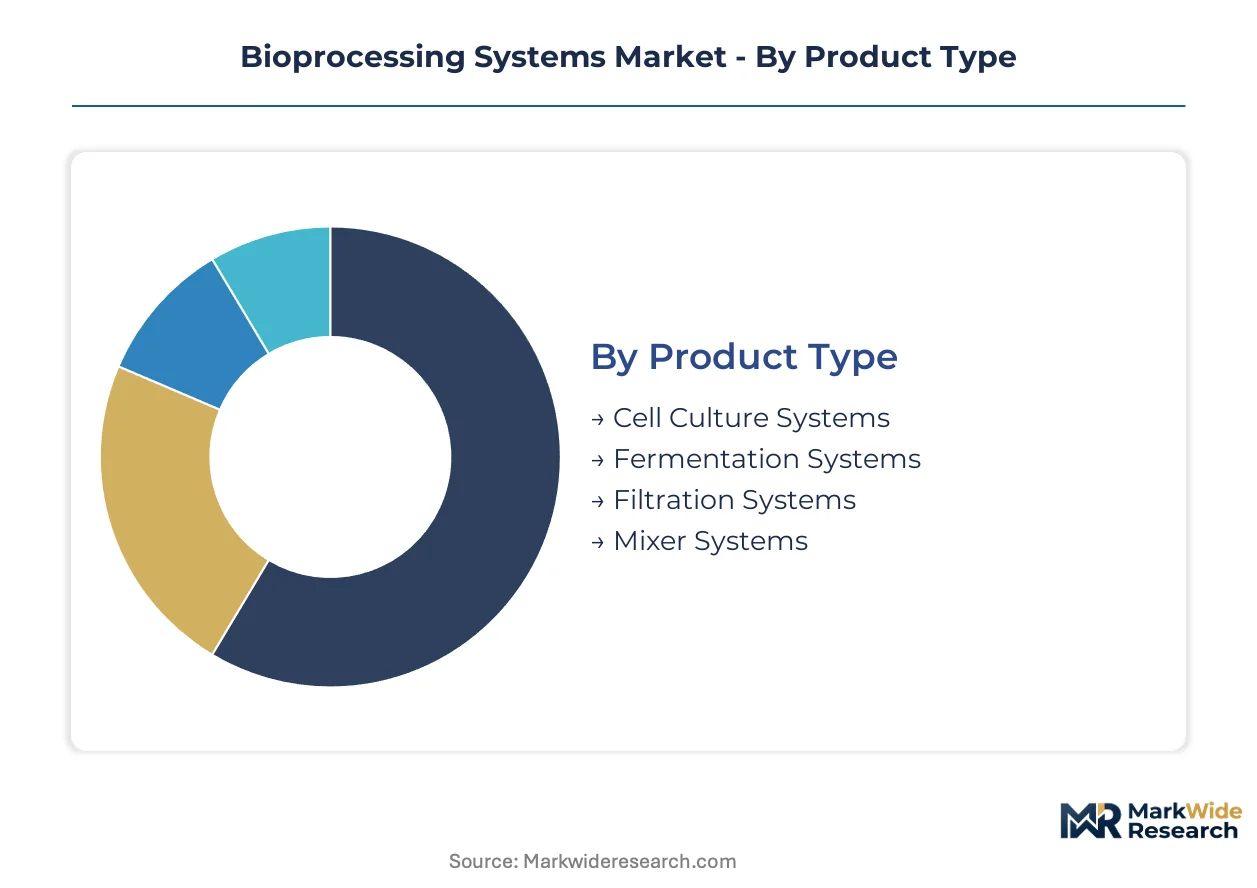
Bioprocessing equipment purchasing decisions diverge sharply by operational scale and regulatory exposure. Single-use technologies command premium positioning in cell therapy facilities where batch flexibility outweighs capital efficiency.
Product Type:
FDA process validation guidance and EMA good manufacturing practice frameworks create divergent equipment qualification burdens across system categories.
- Cell Culture Systems:Stainless-steel and single-use bioreactor configurations support adherent and suspension cell propagation with precise control of dissolved oxygen, pH, and temperature parameters. Pharmaceutical companies in the United States and Germany anchor installed base expansion as monoclonal antibody titers climb and perfusion processing gains regulatory acceptance.
- Filtration Systems:Tangential flow and normal flow filtration skids handle cell harvest, clarification, and final fill-finish operations with membrane-based separation. Contract manufacturers in China and India drive replacement demand as facilities retrofit stainless-steel trains for single-use membrane cassettes to compress turnaround times.
- Fermentation Systems:Microbial culture vessels for recombinant protein and antibiotic production operate at larger working volumes than mammalian systems.
- Mixer Systems:Single-use mixing bags and stainless-stank agitators handle media preparation, buffer formulation, and product pooling.
Cell Culture Systems handle the majority of throughput; Filtration Systems is the fastest mover on share.
Application:
Cost tier differentiation separates blockbuster-scale biologics infrastructure from modular cell and gene therapy platforms.
- Biologics Production:Monoclonal antibody and recombinant protein manufacturing commands the largest equipment footprint with multi-thousand liter bioreactor trains and downstream purification suites. Established manufacturing clusters in Massachusetts, North Rhine-Westphalia, and Jiangsu Province concentrate capacity expansion where FDA and NMPA alignment streamlines cross-border tech transfer.
- Cell Therapy:Autologous and allogeneic cell processing requires closed-system bioreactors, automated cell washers, and cryopreservation units with patient-specific chain-of-custody protocols. EMA Advanced Therapy Medicinal Products framework shapes European facility design while United States academic medical centers anchor early commercial scale-up.
- Vaccine Development:Viral and bacterial vaccine production leverages both egg-based and cell culture platforms with surge capacity requirements.
- Gene Therapy:Viral vector manufacturing for AAV and lentiviral delivery demands specialized transfection and purification equipment.
Biologics Production captures the dominant share of installed capacity; Cell Therapy is expanding most quickly as manufacturing networks mature.
End User:
Procurement authority concentrates differently across customer types, with contract manufacturers unbundling equipment from service agreements.
- Contract Manufacturers:CDMOs in the United States, Germany, and China prioritize modular, transferable platforms that enable rapid client onboarding and multi-product scheduling. These operators drive single-use adoption fastest as they compete on facility changeover speed and regulatory inspection readiness.
- Pharmaceutical Companies:Large-cap biopharma retains in-house manufacturing for pipeline assets and legacy blockbusters, often maintaining hybrid stainless-steel and single-use architectures. Their procurement emphasizes long-term consumables contracts and global service network coverage.
- Biotech Firms:Venture-funded developers outsource manufacturing or lease capacity, influencing equipment specification through sponsor quality agreements rather than direct capital expenditure.
- Research Institutions:Academic and government laboratories operate at pilot scale with emphasis on publication-grade process data and training utility.
Contract Manufacturers drive the steepest equipment demand trajectory; Pharmaceutical Companies retain the largest cumulative installed base.
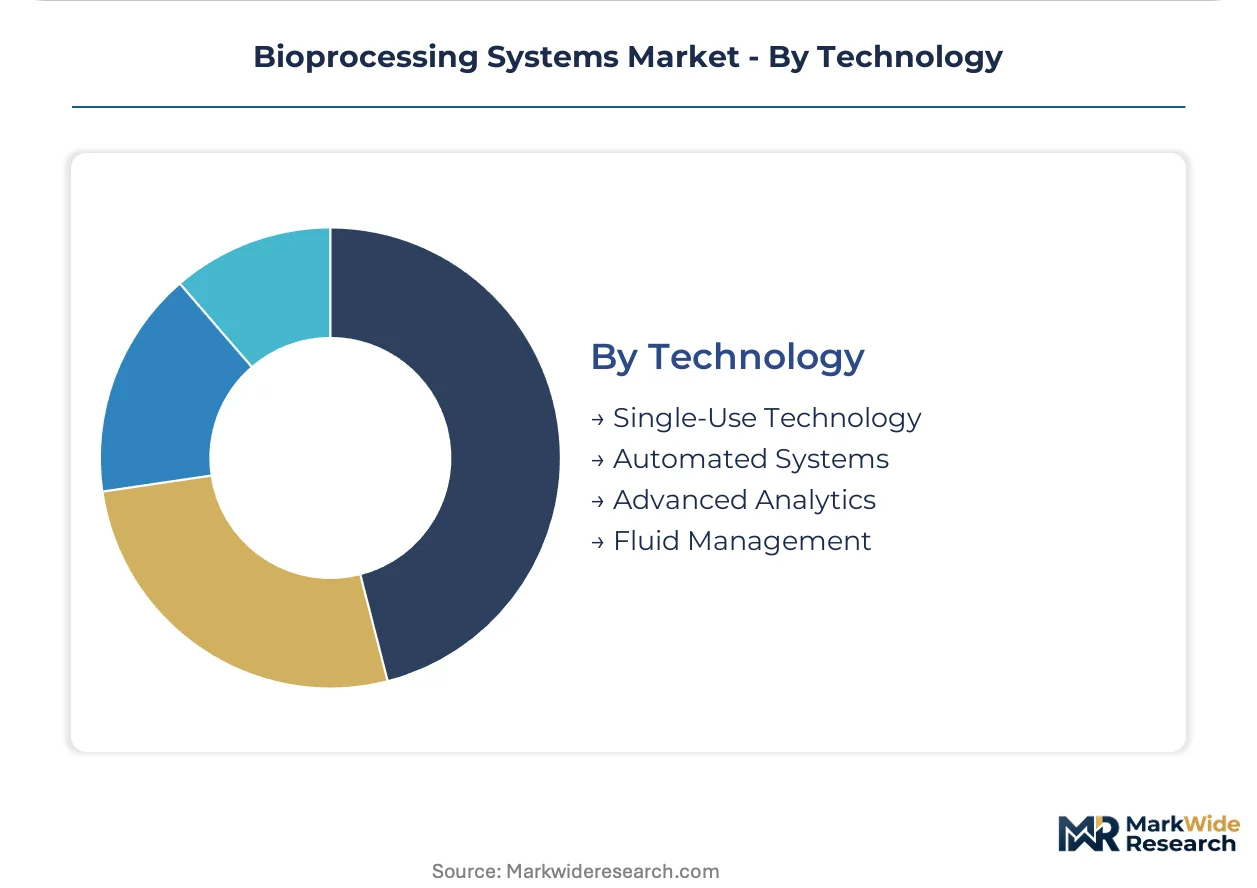
Technology:
Supply concentration in polymer resin and sensor components shapes competitive positioning across technology tiers.
- Single-Use Technology:Disposable bioreactors, mixing bags, and filtration assemblies eliminate cleaning validation cycles and reduce cross-contamination risk. FDA polymer qualification requirements and extractables testing protocols extend supplier development timelines while EMA guidance accelerates European facility conversion.
- Automated Systems:Programmable logic controllers and distributed control systems integrate unit operations with electronic batch records and real-time alarming. German and Swiss biologics facilities face compressed EU AI Act compliance timelines for algorithmic process control validation.
- Advanced Analytics:Process analytical technology sensors and multivariate data analysis platforms enable real-time release testing.
- Fluid Management:Single-use tubing, connectors, and transfer assemblies complete closed-system architectures.
Single-Use Technology commands the dominant procurement volume; Automated Systems is gaining share fastest as facilities integrate AI-enabled process control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers and large-cap biopharma concentrate equipment procurement in three manufacturing clusters. FDA process validation guidance, EMA good manufacturing practice frameworks, and China's NMPA ICH alignment collectively shape qualification requirements across these demand centers.
United States
Massachusetts and North Carolina biologics corridors anchor monoclonal antibody capacity expansion as titers climb toward gram-per-liter thresholds. FDA process validation guidance mandates equipment qualification protocols that extend commissioning timelines for new facilities. Greater Boston contract manufacturers retrofit stainless-steel trains with single-use bioreactors to compress client onboarding cycles.
Germany
North Rhine-Westphalia and Bavaria manufacturing clusters drive perfusion bioreactor adoption for operational efficiency gains. EU AI Act provisions establish conformity assessment requirements for automated process control systems that German notified bodies interpret for biologics applications. Swissmedic alignment with EMA standards enables cross-border equipment qualification between Basel and Freiburg facilities.
China
Jiangsu Province and Shanghai biologics parks concentrate NMPA-aligned capacity for domestic and export-oriented production. ICH Q5A through Q5D harmonization eliminates duplicate validation protocols for foreign equipment suppliers entering the market. Suzhou industrial park contract manufacturers expand modular bioprocessing trains to serve international biotech sponsors.
India
Hyderabad and Bangalore CDMO clusters require flexible single-use platforms for export-oriented biologics manufacturing. CDSCO alignment with ICH quality standards streamlines equipment import clearance for foreign vendors. Genome Valley contract manufacturers unbundle procurement from long-term service agreements to compete on changeover speed.
Switzerland
Basel biologics corridor maintains premium-tier capacity for complex protein and antibody-drug conjugate production. Swissmedic manufacturing oversight aligns with EMA frameworks while preserving distinct national batch release protocols. Swiss facilities face compressed EU AI Act compliance timelines for algorithmic process control validation.
Bioprocessing Systems Market Vendor Landscape
Player mix skews toward diversified life science conglomerates with integrated consumables portfolios. Market structure concentrates among five entities controlling upstream and downstream technology stacks. Two strategic archetypes dominate: full-system integrators bundling hardware with long-term service contracts, and single-use specialists competing on consumables attach rates. Competitive moves center on capacity expansion in CDMO-heavy corridors and technology licensing for automated process control.
Among diversified conglomerates, Thermo Fisher Scientific Inc., Danaher Corporation, and Sartorius AG occupy positions reflecting different integration depths. Thermo Fisher represents the full-system archetype with consumables-instrumentation-service bundling. Danaher sits within the filtration-chromatography specialization tier through Pall Corporation's membrane expertise. Sartorius exemplifies the single-use technology anchor with bioreactor platforms dominating mid-scale production. These three entities collectively illustrate how vendor strategy diverges between hardware specification competition and analytics platform differentiation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| Danaher Corporation |
| Merck KGaA |
| Pall Corporation |
| Eppendorf SE |
| Lonza Group AG |
| Applikon Biotechnology B.V. |
| GEA Group AG |
| Others |
Supply Flow & Price Mechanics
FDA polymer qualification requirements for extractables and leachables testing simultaneously gate supplier entry and stratify price tiers across single-use consumables, compressing margins for new entrants while rewarding validated incumbents with premium positioning. Contract manufacturers in the United States and Germany leverage their procurement volume to negotiate cost-plus contracts indexed to resin commodity fluctuations, creating divergent pricing dynamics between established biologics corridors and emerging manufacturing clusters.
Pricing Analysis
Cost-plus contracts with resin indexation dominate procurement between CDMOs and single-use consumables suppliers, insulating buyers from polymer price volatility while preserving supplier margins through pass-through mechanisms. Price differentiation rests on FDA master file status and EMA qualified supplier designation, with certified vendors commanding 15-25% premiums over unvalidated competitors. Pricing pressure stems from contract manufacturers unbundling equipment from service agreements and demanding competitive consumables attach rates. Biotech firms exhibit highest price sensitivity due to limited capital reserves, while large-cap pharmaceutical companies prioritize supply security over unit cost optimization.
Supply Chain Analysis
Germany and the United States anchor precision bioreactor fabrication and advanced filtration skid assembly, while China concentrates polymer resin production and single-use bag manufacturing at scale. Chromatography media production draws from specialized chemical synthesis capabilities concentrated in Western Europe and North America, with protein A resin supply resting on limited qualified suppliers. Single-source vulnerability pervades high-performance membrane manufacturing, where Pall Corporation and Merck KGaA control dominant production capacity. Distribution runs through authorized distributor networks serving CDMO clusters, with direct OEM relationships reserved for pharmaceutical companies committing to multi-year consumables offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in cell culture scale-up and aseptic operations remains concentrated among experienced practitioners, constraining facility commissioning timelines and creating acquisition premiums for teams with proven tech-transfer records. This capability scarcity shapes competitive positioning across equipment vendors, contract manufacturers, and biotech sponsors competing for limited engineering talent.
For Market Incumbents: Fortify consumables attach rates by embedding predictive analytics platforms into bioreactor control systems, creating switching costs that resist CDMO procurement unbundling. Accelerate capacity addition in Hyderabad and Bangalore to capture India's CDMO expansion before regional suppliers establish local polymer qualification capabilities. Prioritize FDA master file maintenance and EMA qualified supplier status as defensive moats against emerging Asian consumables manufacturers seeking Western market entry. For New Entrants and Emerging Players: CDSCO fast-track certification for ICH-aligned quality standards offers the most penetrable regulatory pathway for foreign equipment suppliers entering India's biologics manufacturing expansion. Target modular single-use bioreactor systems for cell therapy applications, where batch flexibility requirements outweigh total cost of ownership considerations and incumbent positioning remains less entrenched. Pursue go-to-market partnerships with established CDMOs seeking second-source qualification for critical consumables, leveraging technical responsiveness against conglomerate service bureaucracy. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated process control platforms as software margins displace hardware-dependent revenue models, favoring analytics-specialist acquisitions over traditional equipment manufacturers. Long-term viability over the coming decade hinges on digital twin integration capabilities and real-time release testing validation records. Acquisition targets should demonstrate proven FDA AI manufacturing framework engagement and EU AI Act conformity assessment progress. Monitor CDMO consolidation announcements as inflection indicators for consumables pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Development | Predictive maintenance capabilities differentiate vendors serving German perfusion bioreactor installations. |
| Single-Use Resin Backward Integration | Captive polymer supply secures margins against chromatography media cost volatility from limited chemical suppliers. |
| Real-Time Release Testing Validation | FDA AI manufacturing framework alignment enables automated quality verification for Massachusetts contract manufacturers. |
| India CDMO Corridor Expansion | Hyderabad and Bangalore facility presence captures export-oriented biologics production demand from international sponsors. |
| EU AI Act Conformity Assessment | Algorithmic transparency documentation satisfies German notified body requirements for automated process control systems. |
Methodological Framework
Operator-level perspectives from bioprocess engineers, CDMO procurement directors, regulatory affairs specialists, and single-use technology R&D heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 483 observation databases, EMA manufacturing authorization records, and NMPA import registration filings. SEC 10-K equipment revenue disclosures and customs trade data for bioprocessing apparatus complemented interview insights. Bottom-up equipment unit forecasts triangulated against top-down biologics capacity expansion projections across the analysis window.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios, CDMO outsourcing penetration rates, and regulatory approval timeline variations. Segmentation modeling incorporated product type, application, end user, and technology dimensions alongside regional regulatory cluster alignment. CAGRs derived from historical equipment replacement cycles, facility build-out pipelines, and single-use technology conversion rates. Industry-specific inputs included perfusion processing adoption curves and cell therapy manufacturing network maturation timelines.
Underlying assumptions cover sustained FDA and EMA contamination control guidance enforcement, with deviation risk concentrated in resin supply disruptions and bioprocess engineer labor market tightening. Forecasts reflect these assumptions without claiming predictive certainty. Recalibration cycles align with material shifts in CDMO consolidation patterns, AI manufacturing framework finalization, and ICH quality standard harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market