
 Cell Culture Protein Surface Coating Market | 2026-2036
Cell Culture Protein Surface Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Culture Protein Surface Coating Market Intelligence
Expertise in biomaterial surface chemistry is rotating from academic research into commercial-scale production roles, unlocking new coating functionalities for complex cell models. Corning Incorporated leverages its deep materials science background to offer a wide array of pre-coated labware. Thermo Fisher Scientific Inc. competes through its extensive distribution network and broad life sciences portfolio. Merck KGaA differentiates with high-purity reagents and coatings specifically tailored for pharmaceutical drug discovery and development workflows.
Cell culture protein surface coatings are biomolecules applied to inert substrates like plastic labware to create a physiologically relevant microenvironment. These coatings, including natural proteins like collagen or synthetic polymers such as poly-L-lysine, mimic the extracellular matrix to facilitate cell attachment and growth. Collagen represents a foundational product type, but demand is shifting toward specialized coatings for stem cell culture. Tissue engineering and drug development are key applications influencing technical requirements for these surfaces.
Product quality and lot-to-lot consistency are critical, with oversight from regulatory bodies like the U.S. FDA and Europe's EMA, especially for coatings used in manufacturing advanced therapy medicinal products. ISO standards for biocompatibility also guide material selection and testing protocols across geographies including Japan and China. The primary strategic decision for suppliers involves balancing investment between high-margin, GMP-grade clinical products and high-volume, research-use-only offerings.
Market Dynamics
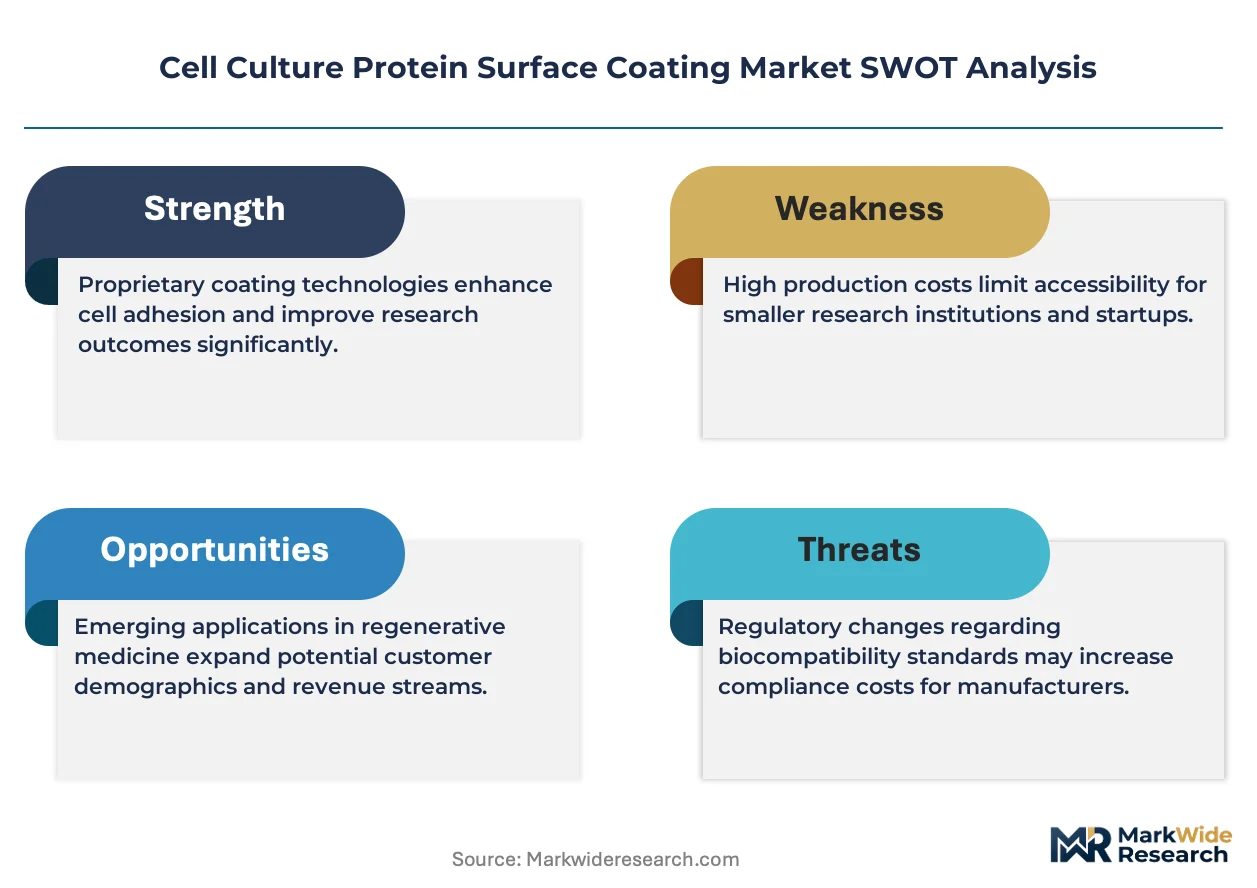
The market's central dynamic is the transition from biologically-derived coatings to synthetic, animal-free alternatives. This shift is driven by regulatory pressure from agencies like the FDA and EMA for greater lot-to-lot consistency and reproducibility in cell-based assays and therapeutic manufacturing workflows.
Growth Catalysts
- Specialized Coating Development:The expansion of stem cell research creates specific demand for advanced surfaces that can direct cell differentiation and maintain pluripotency, moving beyond simple attachment substrates used for basic cell lines.
- Biotechnology Cluster Growth:Concentrated research activity in biotechnology hubs, particularly within Germany and the United States, aggregates demand and accelerates the adoption of novel coating technologies for complex cell models and screening.
- Regenerative Medicine Expansion:Rising investment in tissue engineering applications directly translates to higher volume requirements for biocompatible and functionalized surfaces that are essential for cell proliferation and scaffold integration.
Market Restraints
- High Raw Material Costs:The production of GMP-grade coatings for clinical use requires expensive, highly purified reagents, creating a significant cost barrier compared to research-grade materials and limiting broader adoption in academic settings.
- Technical Mimicry Limits:Current synthetic polymers struggle to fully replicate the complex signaling and structural environment of the native extracellular matrix, limiting their utility for highly sensitive or primary cell cultures.
- Stringent Regulatory Hurdles:Extensive validation and documentation are required by the EMA and FDA for coatings used in therapeutic manufacturing, creating long and costly development timelines that deter new market entrants.
Strategic Opportunities
- Advanced In-Vitro Models:The emergence of organ-on-a-chip platforms and 3D bioprinting applications presents a significant opportunity for customized coatings that support complex, multi-cellular tissue structures and functions.
- Animal-Free Mandates:Regulatory initiatives in Europe promoting alternatives to animal-derived components create a clear pathway for suppliers of chemically defined, synthetic coatings to gain market share in pharmaceutical screening.
- Biopharma Growth in Asia:Expanding biopharmaceutical R&D investment in countries like China and South Korea opens new geographic markets for both high-volume research coatings and clinical-grade products as local manufacturing scales.
Industry Challenges
- Scaling Specialized Expertise:Translating academic biomaterial chemistry expertise into reliable, large-scale GMP manufacturing processes presents a significant operational hurdle, creating a bottleneck in qualified technical personnel.
- Lack of Performance Standards:The absence of universally accepted benchmarks for coating performance and functionality leads to variability in results across different labs and complicates direct product comparisons for end-users.
- Complex Certification Pathways:Navigating the requirements for ISO 10993 biocompatibility testing and subsequent GMP certification for novel materials is a resource-intensive process that can delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Culture Protein Surface Coating Market |
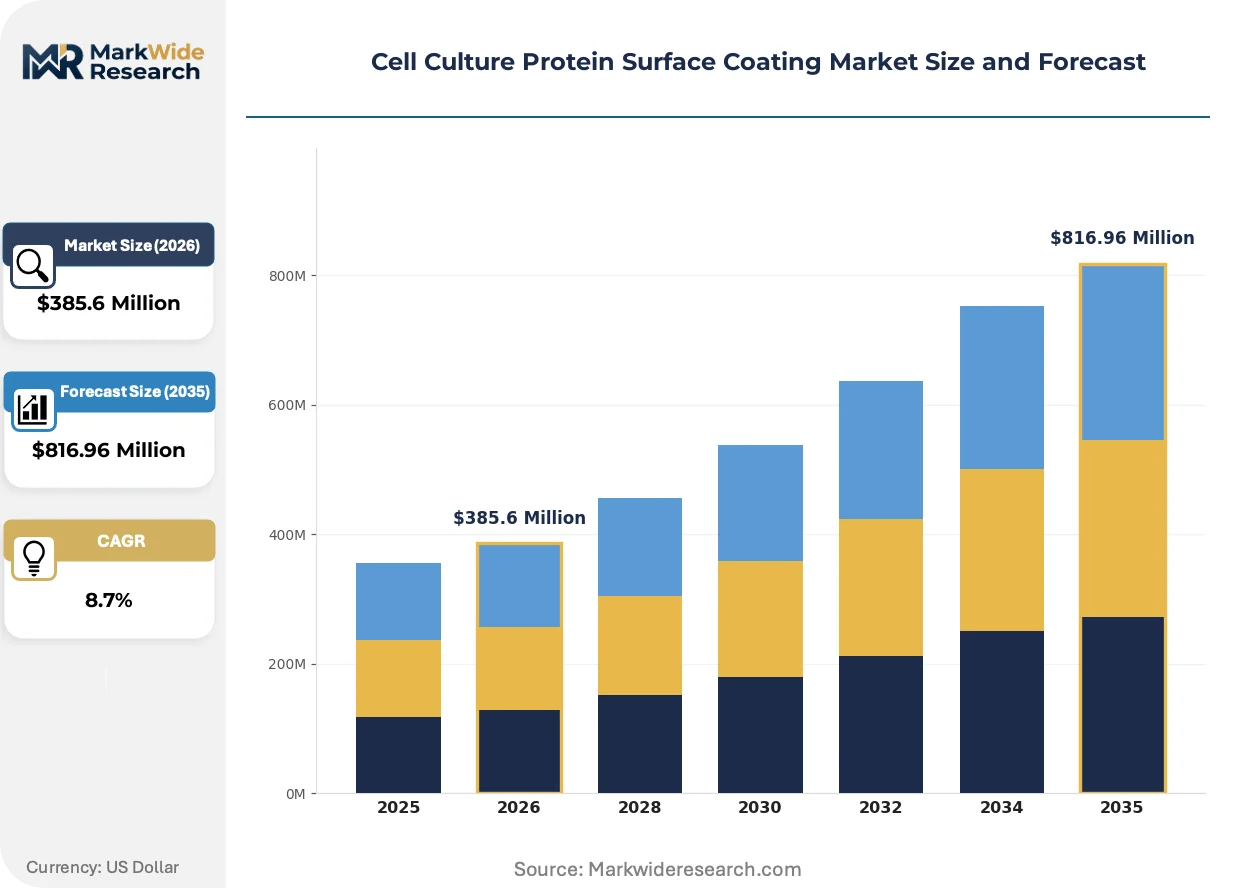
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Fibronectin, Gelatin, Poly-L-Lysine Application: Tissue Engineering, Drug Development, Regenerative Medicine, Diagnostics End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Academic Laboratories Form: Solution, Powder, Gel, Membrane |
| Companies Covered | Corning Incorporated, Thermo Fisher Scientific Inc., Merck KGaA, Sartorius AG, Greiner Bio-One International GmbH, Qiagen NV, Abcam PLC, Promega Corporation, Bio-Techne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Culture Protein Surface Coating Market Strategic Shifts & Innovations
The evolution of cell culture surfaces is defined by a move toward greater control and functionality. Innovations are focused on creating highly defined, reproducible microenvironments that actively guide cell behavior, rather than simply providing a passive attachment substrate for cells.
Chemically defined, synthetic polymer coatings provide a reproducible, animal-free alternative to biological extracts. Pharmaceutical research labs and contract manufacturing organizations are adopting these materials to improve assay consistency. This technology is supplanting traditional, undefined protein coatings derived from animal sources like collagen, particularly where lot-to-lot variability is a critical concern for regulatory submissions.
Heightened scrutiny from national regulators, including Japan's PMDA and China's NMPA, is increasing the compliance burden for biologics manufacturing. This pressure forces developers of advanced therapies to provide complete traceability for all raw materials. Consequently, suppliers are expanding their portfolios of GMP-grade products with extensive documentation to serve clinical and commercial manufacturing segments.
End-user preference is shifting toward purchasing pre-coated, ready-to-use labware instead of performing manual coating procedures in-house. This change disrupts the business model for bulk reagent suppliers, favoring integrated life science companies offering validated, disposable cultureware. The trend is most visible in high-throughput drug discovery workflows within US and European biopharmaceutical research centers.
Cell Culture Protein Surface Coating Market Segmentation
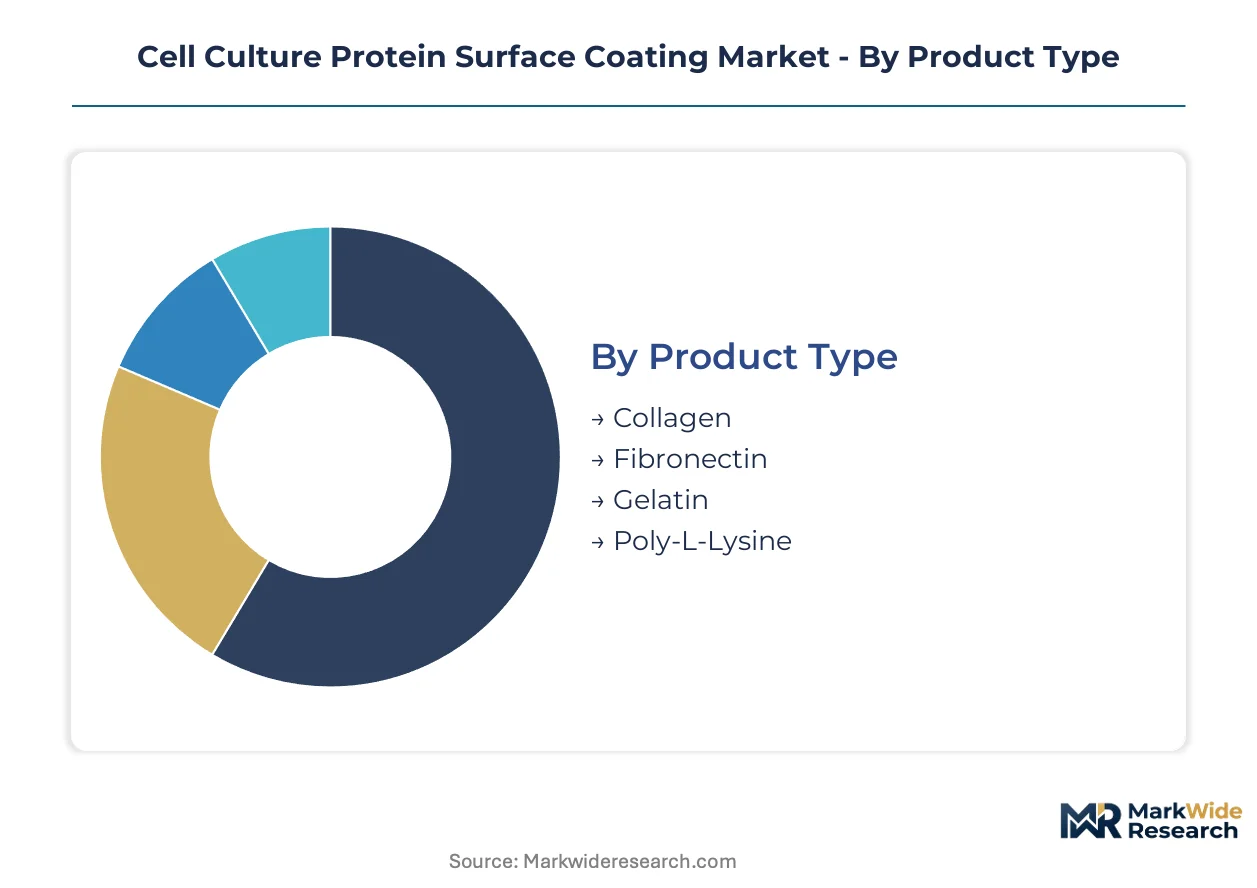
Understanding the Cell Culture Protein Surface Coating Market requires segmenting its diverse offerings. This segmentation highlights the distinct technical requirements, regulatory considerations, and end-user preferences that shape product development and adoption across various scientific disciplines.
Product Type:
Regulatory differentiation increasingly guides product type selection in the cell culture coating market.
- Collagen:This natural protein, often derived from animal sources, serves as a foundational coating for general cell attachment and proliferation. Regulatory bodies like the U.S. FDA scrutinize animal-derived materials, pushing for greater lot-to-lot consistency in therapeutic manufacturing.
- Fibronectin:A large glycoprotein promoting cell adhesion and migration, fibronectin is frequently employed for specific cell types requiring enhanced binding characteristics in academic research.
- Gelatin:Derived from collagen, gelatin offers a cost-effective coating solution for routine cell culture but shares similar challenges regarding batch variability due to its biological origin.
- Poly-L-Lysine:A synthetic, animal-free polymer, poly-L-lysine enhances cell adhesion through electrostatic interactions, providing a highly reproducible surface. Pharmaceutical research centers in the United States increasingly adopt these synthetic coatings for improved assay consistency and regulatory compliance.
Established volume favors Collagen; emerging adoption favors Poly-L-Lysine.
Application:
Application-specific requirements drive innovation within the cell culture protein surface coating sector.
- Tissue Engineering:This application focuses on creating functional biological substitutes for damaged tissues, demanding highly biocompatible and functionalized surfaces. These surfaces are essential for guiding cell proliferation and integration into complex scaffold structures.
- Drug Development:Cell culture coatings are critical for in-vitro models used in drug screening and toxicity testing of new pharmaceutical compounds. High-throughput drug discovery workflows in European biopharmaceutical research centers demand consistent, pre-coated labware for reliable results.
- Regenerative Medicine:This field aims to restore normal function to diseased or damaged tissues, frequently utilizing stem cells cultured on specialized surfaces that direct differentiation.
- Diagnostics:Cell-based assays for disease detection and monitoring require highly stable and reproducible coating chemistries to ensure assay reliability.
Demand for Drug Development remains strong, while Tissue Engineering presents significant growth potential.
End User:
The diverse end-user landscape reflects varying scale and regulatory needs across the cell culture protein surface coating market.
- Pharmaceutical Companies:These large-scale enterprises require GMP-grade coatings with extensive documentation for drug discovery and therapeutic manufacturing. They prioritize lot-to-lot consistency and strict regulatory compliance for advanced therapy medicinal products.
- Biotechnology Firms:Focused on developing novel biologics and cell-based therapies, these firms often drive demand for specialized coatings. These coatings support complex cell models and stem cell differentiation within biotechnology clusters in Germany.
- Research Institutions:Engaged in fundamental and applied research, these institutions require a wide array of coating types for diverse cell lines and experimental designs.
- Academic Laboratories:Primarily involved in basic scientific inquiry and education, these laboratories often balance performance with cost efficiency for research-use-only materials.
High-volume procurement characterizes Pharmaceutical Companies; specialized requirements define Biotechnology Firms.
Form:
Delivery format influences usability and application suitability for cell culture protein surface coatings.
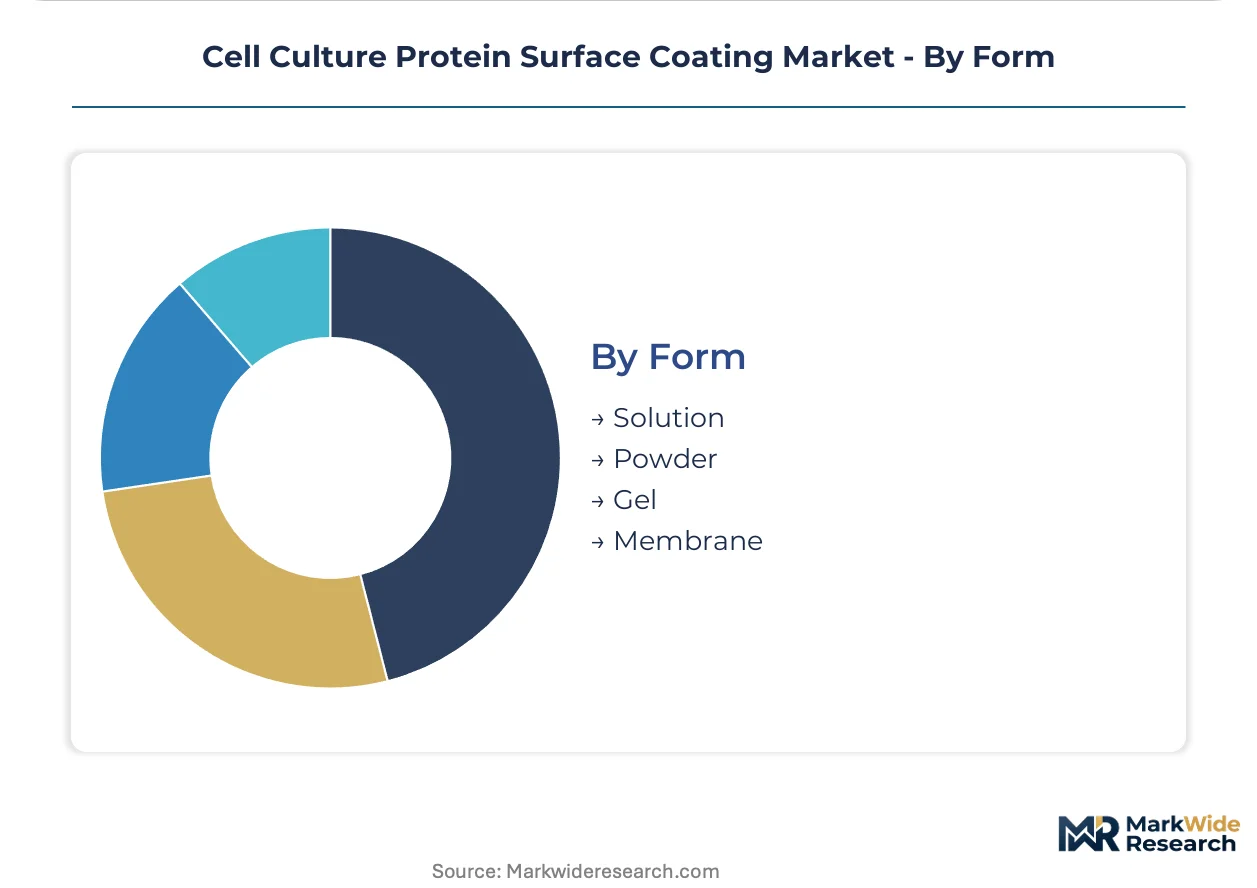
- Solution:Liquid formulations of coating proteins are ready for direct application to labware or custom surface treatments. This form is widely used in academic settings for its flexibility in preparing various surface concentrations.
- Powder:Concentrated dry forms of coating materials require reconstitution before use. Powder forms are often chosen for bulk purchasing and storage efficiency in larger research facilities.
- Gel:Three-dimensional matrices mimic the extracellular matrix, providing a more complex environment for cell culture. Tissue engineering applications frequently utilize gel forms to support cell encapsulation and 3D culture.
- Membrane:Thin, porous sheets pre-coated with proteins are used in specialized cell culture inserts and filtration applications for specific experimental setups.
Convenience drives adoption of Solution; specialized applications favor Gel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. FDA's stringent oversight significantly influences the global cell culture protein surface coating market, driving demand for highly reproducible and compliant materials. Regulatory pressures from agencies worldwide accelerate the shift towards synthetic, animal-free alternatives for advanced therapy medicinal products.
United States
Biopharmaceutical research and advanced therapy development drive substantial demand for cell culture protein coatings. The U.S. FDA mandates extensive validation and documentation for clinical-grade materials, impacting product development. The Boston-Cambridge biotech hub actively adopts pre-coated labware for high-throughput drug screening workflows.
Germany
Concentrated biotechnology clusters in Germany fuel specific demand for advanced coatings in stem cell research and regenerative medicine. The EMA's regulatory framework prioritizes lot-to-lot consistency for cell-based assays and therapeutic manufacturing. Munich's vibrant biotech sector actively integrates specialized surfaces for complex cell models.
Japan
Biologics manufacturing and advanced therapy development within Japan create a strong need for high-quality cell culture coatings. The PMDA's increased scrutiny on raw material traceability drives demand for GMP-grade products. Tokyo's pharmaceutical research centers seek reproducible, animal-free alternatives for compliant workflows.
China
Expanding biopharmaceutical R&D investment in China significantly boosts the market for both research-grade and clinical-grade coatings. The NMPA's compliance requirements for biologics manufacturing encourage adoption of well-documented, high-purity reagents. Shanghai's growing biopharmaceutical sector serves as a key hub for novel coating technology adoption.
South Korea
South Korea's expanding biopharmaceutical R&D and advanced stem cell research propel demand for specialized protein surface coatings. The MFDS enforces strict quality and safety standards for therapeutic applications. Seoul's life sciences institutions increasingly adopt customized coatings for directing cell differentiation and growth.
Cell Culture Protein Surface Coating Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the cell culture protein surface coating market. The market exhibits a tiered structure, with specialized innovators focusing on high-performance, GMP-grade products alongside broad portfolio providers offering extensive labware solutions. Regulatory compliance for advanced therapies also segments the competitive landscape. Competitive moves involve portfolio diversification into animal-free coatings and strategic partnerships to access new distribution channels.
Among established industry leaders, Corning Incorporated exemplifies a materials science-driven approach, offering a wide array of pre-coated labware for diverse cell culture needs. Thermo Fisher Scientific Inc. occupies a position as a broad life sciences portfolio provider, leveraging its extensive distribution network to reach a global customer base. Merck KGaA represents a specialist in high-purity reagents, with offerings tailored for pharmaceutical drug discovery and development workflows, emphasizing compliance and consistency in regulated environments.
| Leading Market Players |
|---|
| Corning Incorporated |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sartorius AG |
| Greiner Bio-One International GmbH |
| Qiagen NV |
| Abcam PLC |
| Promega Corporation |
| Bio-Techne |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for GMP-grade coatings lock in both raw material access and price visibility for advanced therapy manufacturers, stabilizing input costs. This contract-based approach mitigates volatility for critical components used in regulated biopharmaceutical workflows.
Pricing Analysis
Price spreads for cell culture coatings vary significantly across regions, with higher costs observed in markets with stringent regulatory oversight like the United States and Europe. The dominant pricing model is contract-based long-term offtake for clinical-grade materials, while research-use-only products often follow a per-unit transactional model. Price differentiation stems from certification level, such as GMP-grade versus research-grade, and the degree of customization for specialized applications. Academic laboratories exhibit the highest price sensitivity for basic coatings.
Supply Chain Analysis
China and the United States anchor the supply of critical raw materials for synthetic polymer coatings, including specialized amino acids and chemical intermediates. The production of high-purity collagen, a foundational coating, primarily sources from animal byproducts globally, subject to rigorous quality controls. Single-source vulnerability for highly specialized reagents poses a structural risk for clinical-grade products. Distribution runs through a mix of direct sales channels for large biopharmaceutical clients and extensive distributor networks for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a defensive moat due to the high regulatory entrenchment for clinical-grade materials, creating significant barriers to entry for uncertified suppliers.
For Market Incumbents: Shield existing market share by investing heavily in GMP-grade product development and expanding global regulatory certifications. Diversify product portfolios with animal-free synthetic coatings to counter the threat from emerging specialized polymer technologies. Leverage vertical integration into raw material sourcing to control costs and ensure supply consistency.
For New Entrants and Emerging Players: Fast-track ISO 10993 biocompatibility certification for novel synthetic polymers to address unmet needs in advanced in-vitro models. Target the academic research segment in emerging biopharma hubs like South Korea and China, which are less constrained by existing supplier relationships. A direct-to-lab online sales model offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized innovators focusing on high-performance, GMP-grade products with strong intellectual property in chemically defined coatings. The long-term viability of this sector is strong, driven by sustained biopharmaceutical R&D investment. A signal to watch is the increasing number of FDA approvals for advanced therapy medicinal products utilizing novel surface chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Animal-Free Coatings | Addresses regulatory shifts and expands market access in pharmaceutical screening. |
| Investment in GMP Manufacturing Capacity | Meets stringent quality requirements for advanced therapy medicinal products. |
| Strategic Partnerships with Labware Manufacturers | Expands distribution channels and offers integrated, pre-coated solutions to end-users. |
| R&D in 3D Cell Culture Substrates | Supports the development of complex in-vitro models and organ-on-a-chip platforms. |
| Geographic Expansion in Asia-Pacific | Captures growth from expanding biopharmaceutical R&D in China and South Korea. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, and academic research databases. This involved in-depth interviews with R&D directors, procurement leads, and regulatory affairs specialists from pharmaceutical companies, biotechnology firms, and research institutions. The analysis utilized both bottom-up market sizing and top-down validation to ensure data accuracy.
The analysis modeled segmentation dimensions including product type, application, end-user, form, and key geographic regions across the analysis window. Compound Annual Growth Rates were derived from historical trends, projected technology adoption, and anticipated regulatory impacts. Industry-specific forecast inputs included biopharmaceutical R&D spending and advanced therapy medicinal product approvals.
Underlying assumptions cover sustained investment in life sciences R&D and consistent regulatory pressure for animal-free alternatives, with deviation risk concentrated in unforeseen shifts in global biopharmaceutical funding. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market