
 Bioprocess Containers and Fluid Transfer Solutions Market | 2026-2036
Bioprocess Containers and Fluid Transfer Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprocess Containers and Fluid Transfer Solutions Market Outlook
Aftermarket service revenue for validation and integrity testing is reconfiguring margin pools away from commodity bag sales. Sartorius AG anchors its position through deep specialization in single-use assembly customization. Thermo Fisher Scientific leverages its diagnostic-to-biologics channel breadth to sustain pull-through for fluid transfer consumables. Danaher Corporation dominates bioprocess analytics integration, extending its influence into container closure integrity verification.
Bioprocess containers and fluid transfer solutions comprise sterilized, single-use or multi-use vessels, tubing manifolds, and sterile connection devices engineered from multi-layer polymer films with specified gas barrier properties and extractables profiles. These systems enable closed-system handling of cell culture media, harvest intermediates, and final drug substances without metallic vessel cleaning validation. Single-use bags command the largest value pool due to film formulation complexity and gamma-irradiation certification overhead. Tubing systems and connectors are gaining share fastest as modular, plug-and-play architectures displace welded stainless-steel networks in clinical-scale facilities.
FDA enforces Container Closure System guidance that mandates particulate and bioburden controls for all fluid contact surfaces in sterile biologics manufacturing. EMA's Annex 1 revision tightens barrier-isolation expectations, pushing pharmaceutical companies toward validated single-use transfer assemblies with demonstrable sterility assurance levels. ISO 13485 and USP Class VI compliance now function as baseline market-access credentials rather than differentiators. Stakeholders must weigh captive film extrusion investments against qualified supplier concentration risk as polymer supply chains face pharmaceutical-grade resin allocation constraints.
Market Dynamics
Single-use bioprocessing is consolidating procurement power among contract manufacturing organizations, forcing film suppliers to absorb gamma-irradiation certification costs while expanding customization depth to retain multi-year supply agreements.
Growth Catalysts
- EMA Annex 1 revision:The tightened barrier-isolation mandate accelerates validated single-use transfer assembly adoption across European sterile biologics facilities, displacing stainless-steel networks.
- Cell therapy manufacturing infrastructure:Commercial-scale autologous and allogeneic cell therapy production in the United States, Germany, and China demands closed-system fluid handling with demonstrable sterility assurance levels.
- Multi-layer polymer film innovation:Advanced gas barrier formulations with reduced extractables profiles enable longer hold times for sensitive biologics intermediates, expanding application scope beyond traditional monoclonal antibodies.
Market Restraints
- Pharmaceutical-grade resin allocation constraints:Concentrated polymer supply chains in Asia-Pacific create qualified supplier concentration risk, limiting film extrusion capacity expansion for multi-layer structures.
- FDA Container Closure System validation overhead:Particulate and bioburden control documentation requirements extend material qualification timelines, compressing margin pools for standard commodity bag configurations.
- Stainless-steel equipment refurbishment cycles:Extended useful life of validated metallic vessels in established biologics facilities delays single-use conversion decisions among cost-sensitive operators.
Strategic Opportunities
- Modular plug-and-play architectures:Tubing systems and sterile connection devices capture share from welded networks as clinical-scale facilities prioritize operational flexibility and reduced cleaning validation burden.
- Aftermarket service revenue expansion:Validation and integrity testing services reconfigure margin pools away from commodity hardware sales toward recurring technical support relationships.
- China cell therapy manufacturing buildout:NMPA regulatory alignment with international sterility standards opens demand for imported single-use assemblies with established gamma-irradiation certification.
Industry Challenges
- Bioprocess analytics integration complexity:Container closure integrity verification requires specialized technical personnel scarce among mid-scale contract manufacturers, constraining deployment velocity.
- Multi-supplier film qualification timelines:USP Class VI and ISO 13485 compliance documentation from secondary polymer sources extends supply chain redundancy implementation by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprocess Containers and Fluid Transfer Solutions Market |
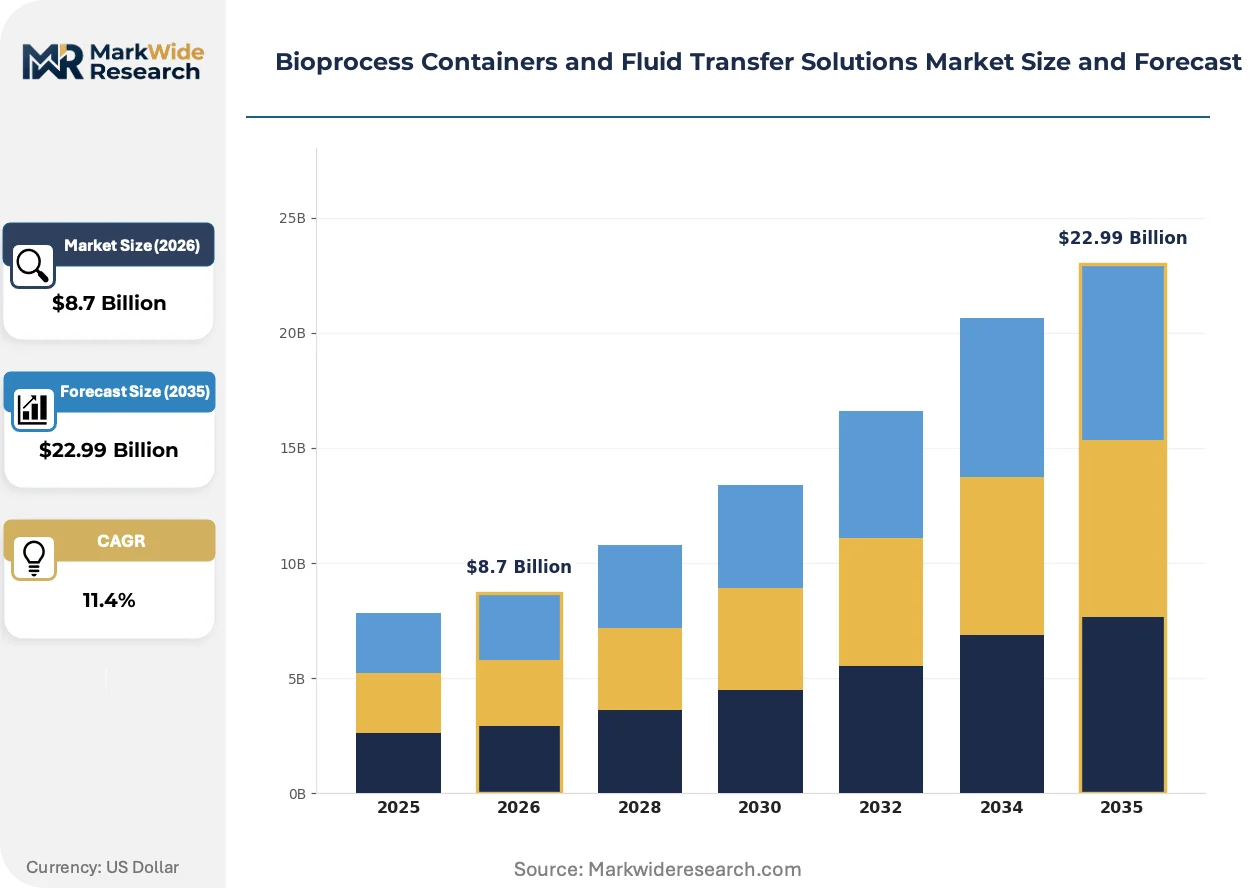
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Bags, Tubing Systems, Connectors, Filters Material: Polyethylene, Polypropylene, Silicone, Thermoplastic Elastomer Application: Cell Culture, Harvesting, Storage, Transport End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Contract Manufacturing Organizations |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Saint-Gobain Life Sciences, Merck KGaA, Danaher Corporation, Lonza, Cytiva, Parker Hannifin Corp, Avantor Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprocess Containers and Fluid Transfer Solutions Market Strategic Shifts
Film formulation science and sterility assurance methodologies are converging to redefine competitive differentiation, with technology vendors racing to embed sensing capabilities directly into disposable fluid paths.
Multi-layer polymer films with embedded barrier coatings are hybridizing gas permeation control with extractables reduction. Cell therapy manufacturers in the United States and Germany are adopting these structures for extended cold-chain holds of live-cell intermediates. The technology is hybridizing previously separate film functions—structural integrity, gas barrier, and biocompatibility—into unified substrates that compress supplier qualification overhead.
EMA's Annex 1 revision on sterile product manufacturing mandates demonstrable contamination control strategies for all fluid contact surfaces. European biologics facilities must now document sterility assurance levels for single-use transfer assemblies equivalent to barrier-isolated stainless systems. Modular connector manufacturers serving German and Swiss pharmaceutical clusters are accelerating validation dossier preparation to capture this compliance-driven replacement cycle.
Buyer concentration among top-tier contract manufacturing organizations is compressing supplier negotiation leverage and unbundling after-sales technical support from hardware procurement. Large CDMOs in the United States and Ireland now separately contract validation services from third-party testing laboratories rather than accepting bundled manufacturer offerings. This procurement fragmentation is most visible in cell therapy manufacturing, where specialized integrity testing requirements exceed standard supplier service capabilities.
Bioprocess Containers and Fluid Transfer Solutions Market Segmentation
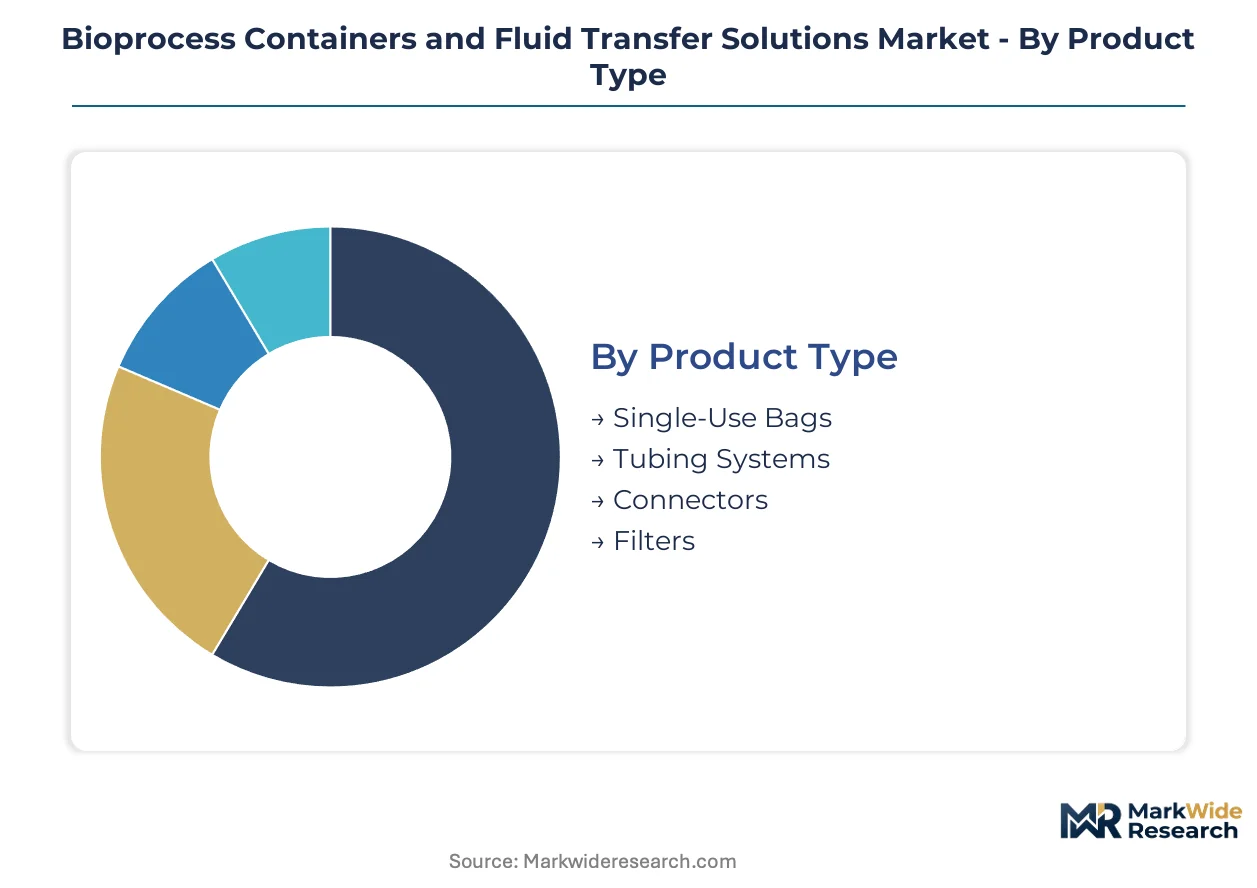
Segmentation in bioprocess containers and fluid transfer solutions reveals divergent procurement rhythms. Single-use bags turn over on campaign-based biologics production cycles while tubing systems refresh through modular facility upgrades.
Product Type:
Cycle times vary sharply across product categories, with campaign-driven consumables refreshing faster than capital-connected hardware.
- Single-Use Bags:Multi-layer polymer films with specified gas barrier properties and extractables profiles form the core value pool. Demand concentrates among contract manufacturing organizations in the United States and Germany as biologics pipelines deepen and gamma-irradiation certification overhead compresses supplier margins.
- Tubing Systems:Modular, plug-and-play architectures displace welded stainless-steel networks in clinical-scale facilities. Cell therapy manufacturers in China and Germany adopt these for operational flexibility and reduced cleaning validation burden, capturing share fastest from traditional fixed infrastructure.
- Connectors:Sterile connection devices enable closed-system fluid handling with demonstrable sterility assurance levels.
- Filters:Terminal and bioburden reduction configurations integrate into single-use assembly workflows.
Single-use bags anchor the volume base while tubing systems gain share at the steepest rate.
Material:
Cost tiers stratify sharply, with commodity thermoplastics dominating high-volume applications and specialized elastomers commanding premium positioning in cell therapy.
- Polyethylene:Pharmaceutical-grade resin formulations serve as the structural backbone for standard single-use bags. Supply chain concentration in Asia-Pacific creates qualified supplier risk, limiting extrusion capacity expansion for multi-layer structures.
- Silicone:Platinum-cured formulations deliver biocompatibility for extended cell culture contact. United States and German cell therapy facilities specify these for autologous production workflows where extractables profiles determine regulatory submission success.
- Polypropylene:Gamma-stable grades enable sterilization validation for fluid contact surfaces.
- Thermoplastic Elastomer:Sealing and gasket applications benefit from compression set resistance.
Polyethylene dominates procurement volumes while silicone climbs the fastest on cell therapy specification expansion.
Application:
Application maturity varies, with established monoclonal antibody workflows contrasting against nascent cell therapy protocols still defining standard configurations.
- Cell Culture:Closed-system media handling and expansion vessels require validated gas transfer properties. United States biotech firms and contract manufacturing organizations drive specification refinement as perfusion processes intensify and hold times extend.
- Storage:Cold-chain intermediate holding demands hybridized barrier coatings for live-cell preservation. German and Swiss pharmaceutical clusters adopt these structures for extended holds, compressing supplier qualification overhead through unified substrate designs.
- Harvesting:Clarification and collection workflows integrate single-use assemblies into downstream trains.
- Transport:Ship-ready configurations address logistics validation for distributed manufacturing networks.
Cell culture commands the installed base while storage applications expand most quickly on cell therapy manufacturing buildout.
End User:
Customer concentration is reconfiguring supplier relationships, with large contract manufacturers unbundling technical services from hardware procurement.
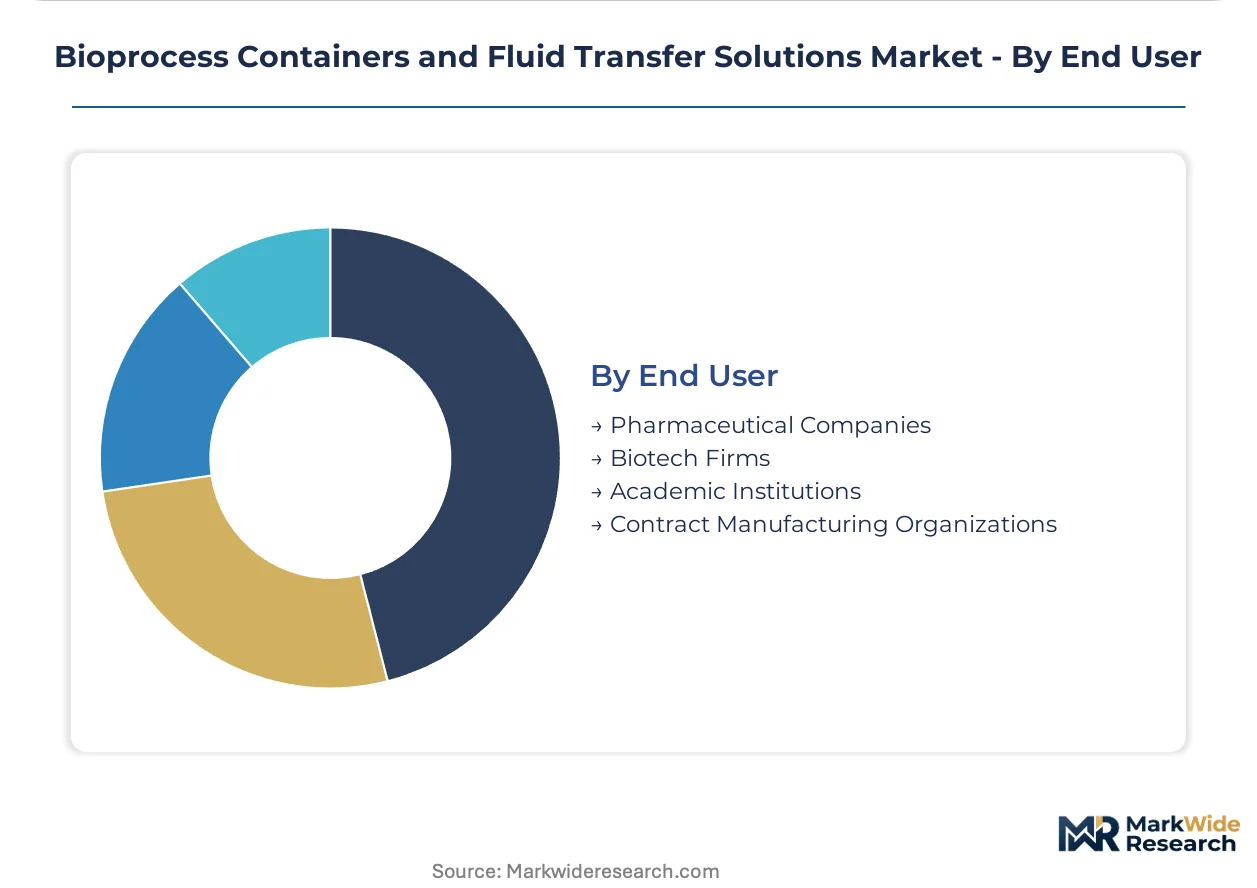
- Contract Manufacturing Organizations:Procurement power consolidation forces film suppliers to absorb gamma-irradiation certification costs. Large CDMOs in the United States and Ireland separately contract validation services from third-party testing laboratories, fragmenting traditional bundled offerings.
- Pharmaceutical Companies:In-house biologics manufacturing drives multi-year supply agreements with customization depth requirements. Established operators in Germany balance stainless-steel refurbishment cycles against single-use conversion decisions.
- Biotech Firms:Clinical-stage developers prioritize operational flexibility over capital investment in fixed infrastructure.
- Academic Institutions:Research-scale procurement follows funding cycle timing with lower validation stringency.
Contract manufacturing organizations anchor demand concentration while biotech firms represent the steepest expansion trajectory on pipeline maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Contract manufacturing organizations in Ireland and Singapore negotiate aggressively on standard bag configurations, while cell therapy developers in Switzerland and Massachusetts absorb premiums for customized assemblies with extended validation dossiers.
United States
Cell therapy manufacturing infrastructure concentrates demand for closed-system fluid handling. FDA Container Closure System guidance drives particulate and bioburden documentation requirements across sterile biologics facilities. The Greater Boston and San Francisco Bay Area clusters host autologous production workflows specifying platinum-cured silicone tubing for extended cell culture contact.
Germany
EMA Annex 1 revision tightens barrier-isolation mandates for European sterile biologics manufacturing. German pharmaceutical clusters in Bavaria and North Rhine-Westphalia document sterility assurance levels for single-use transfer assemblies equivalent to stainless-steel systems. Tubing manufacturers accelerate validation dossier preparation to capture this compliance-driven replacement cycle.
China
NMPA regulatory alignment with international sterility standards opens demand for imported single-use assemblies. Yangtze River Delta and Pearl River Delta biotech parks build out commercial-scale cell therapy capacity requiring gamma-irradiation certified multi-layer films. Domestic film extrusion capacity faces pharmaceutical-grade resin allocation constraints from concentrated Asia-Pacific supply chains.
Switzerland
Swissmedic enforcement of barrier-isolation expectations pushes pharmaceutical companies toward validated single-use transfer assemblies. Basel and Zurich pharmaceutical clusters adopt hybridized barrier coatings for extended cold-chain holds of live-cell intermediates. These unified substrate designs compress supplier qualification overhead for specialized cell therapy applications.
India
CDSCO harmonization with international biocompatibility standards enables contract manufacturing organization expansion. Hyderabad and Bengaluru biotech corridors develop clinical-scale facilities prioritizing operational flexibility over capital investment in fixed stainless-steel infrastructure. Gamma-irradiation certification overhead limits qualified local film suppliers.
Bioprocess Containers and Fluid Transfer Solutions Market Competitive Environment
Capability concentration sits with specialized film formulators; scale advantage sits with diversified life sciences conglomerates. The market structures around three tiers: integrated diagnostic-to-biologics platforms, pure-play single-use assembly specialists, and regional film extrusion fabricators. Dominant competitive moves include backward integration into captive polymer compounding and geographic expansion through qualified supplier accreditation in high-growth cell therapy clusters.
Among diversified life sciences platforms, Thermo Fisher Scientific and Danaher Corporation exemplify the diagnostic-to-biologics channel breadth archetype. Sartorius AG occupies a position within the pure-play specialization tier, anchoring its presence through single-use assembly customization depth. These three entities represent contrasting strategic postures: channel leverage versus technical specialization versus integrated analytics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Saint-Gobain Life Sciences |
| Merck KGaA |
| Danaher Corporation |
| Lonza |
| Cytiva |
| Parker Hannifin Corp |
| Avantor Inc |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade polyethylene resin concentration in Asia-Pacific extrusion facilities funnels margin capture toward gamma-irradiation certification providers and validation service laboratories downstream. Buyers in Germany and the United States absorb premium positioning for multi-layer film assemblies while CDMO procurement desks in Ireland and Singapore compress commodity bag pricing through volume aggregation.
Pricing Analysis
Aftermarket validation and integrity testing services now drive lifetime value capture, displacing hardware margins as CDMOs unbundle technical support from consumable procurement. Pricing stratifies across gamma-irradiation certified premium tiers, standard ISO 13485 compliant configurations, and economy grades for research-scale applications. Cost compression in standard bag configurations is intensifying as large contract manufacturers consolidate procurement power and force suppliers to absorb certification overhead. Biotech firms in clinical development demonstrate highest price sensitivity, while cell therapy manufacturers in Switzerland and Massachusetts absorb premiums for customized assemblies with extended validation dossiers.
Supply Chain Analysis
Export-control scrutiny on advanced polymer compounding equipment limits technology transfer to emerging film extrusion facilities, constraining qualified supplier expansion outside established manufacturing clusters. Geographic supply concentration centers on Germany, the United States, and China for finished single-use assemblies, with pharmaceutical-grade resin feedstock anchored in Asia-Pacific petrochemical complexes. Raw material dependencies include multi-layer coextrusion films, platinum-cured silicone formulations, and gamma-stable polypropylene grades. Single-source vulnerability persists for specialized barrier coating chemistries qualified to USP Class VI standards. Distribution runs through direct OEM relationships with large CDMOs and regional distributor networks serving mid-scale biotech facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use bioprocessing equipment demand tracks biologics pipeline maturation cycles, with current expansion reflecting post-downturn cell therapy manufacturing infrastructure buildout across United States, German, and Chinese clusters.
For Market Incumbents: Pre-empt qualification timeline compression by securing secondary polymer source accreditation before EMA Annex 1 enforcement tightens supplier validation windows. Defend margin position through backward integration into captive film compounding rather than absorbing gamma-irradiation certification costs indefinitely. Capacity addition in German and Swiss pharmaceutical corridors captures compliance-driven replacement cycles for stainless-steel networks.
For New Entrants and Emerging Players: Establish a beachhead in aftermarket validation services where CDMO procurement fragmentation has unbundled technical support from hardware sales. Target mid-scale cell therapy manufacturers in China and India requiring gamma-irradiation certification but lacking in-house testing infrastructure. Penetrate through third-party laboratory partnerships rather than competing directly with established film suppliers on commodity bag specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized film formulators with demonstrated USP Class VI qualification dossiers and established relationships with German and Swiss pharmaceutical clusters. Long-term viability over the next decade hinges on regulatory certification depth rather than extrusion scale alone. Watch for NMPA regulatory alignment completion as the signal indicating accelerated China cell therapy manufacturing demand for imported single-use assemblies.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma-Irradiation Certification Expansion | EMA Annex 1 revision mandates validated sterility assurance levels for European biologics facilities. |
| Backward Integration into Polymer Compounding | Captive resin formulation control reduces qualified supplier concentration risk from Asia-Pacific feedstock. |
| Aftermarket Validation Service Buildout | CDMO procurement fragmentation creates recurring revenue pools beyond commodity hardware sales. |
| China Cell Therapy Cluster Accreditation | NMPA alignment with international standards opens demand for imported single-use assemblies. |
| Multi-Layer Barrier Film Innovation | Hybridized gas barrier coatings enable extended cold-chain holds for live-cell intermediates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bioprocess engineering directors, CDMO procurement leads, regulatory affairs specialists managing FDA Container Closure System submissions, and polymer scientists at film extrusion facilities. Secondary validation drew from FDA guidance documents, EMA Annex 1 revision drafts, ISO 13485 certification registries, and USP Class VI compliance databases. Bottom-up demand modeling across end-user segments triangulated against top-down value chain analysis of film formulation costs and gamma-irradiation certification overhead.
Calibration against historical biologics capacity expansion cycles and cell therapy manufacturing facility announcements anchored volume projections across the modeling period. Segmentation dimensions included product type, material grade tier, application workflow, and end-user scale category. CAGRs were derived from weighted average growth across these segments, with specific inputs from biologics pipeline databases and contract manufacturing organization capital expenditure disclosures.
Sensitivities concentrate around pharmaceutical-grade resin allocation disruptions, EMA Annex 1 enforcement timing, and NMPA regulatory alignment completion in China. Material shifts in sterilization validation requirements or barrier-isolation technology standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Laboratory Filtration Devices Market