
 Cryogenic Vial Rack Market | 2026-2036
Cryogenic Vial Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Vial Rack Market Outlook
Chinese polymer processors is realigning cryogenic rack resin supply chains toward medical-grade polypropylene grades certified for liquid nitrogen exposure. Corning Incorporated leverages its glass-to-plastics manufacturing heritage to dominate high-throughput laboratory formats. Heathrow Scientific competes on color-coded rack systems that simplify sample retrieval workflows in multi-user biobanks. DWK Life Sciences anchors European demand through its DURAN borosilicate-adjacent brand trust translated into polymer rack reliability.
A cryogenic vial rack is a structured holder engineered from medical-grade polypropylene, aluminum, or carbon fiber composites to organize biological specimens at temperatures reaching minus 196 degrees Celsius in liquid nitrogen vapor phase storage. Its primary purpose is to prevent vial displacement, enable barcode scanning compatibility, and maximize cubic storage efficiency within automated retrieval systems. Plastic rack configurations sustain the largest volume share due to thermal shock resistance and manufacturing scalability, though aluminum variants occupy premium positions in pharmaceutical research where thermal conductivity uniformity matters for controlled-rate freezing. Custom size demand accelerates fastest as cell therapy manufacturers require non-standard footprints for proprietary cryobag and vial combinations.
The FDA enforces current Good Manufacturing Practice standards that mandate lot traceability for cryopreserved cellular products, compelling rack suppliers to integrate laser-etched identification matrices. ISO 20387 biobanking standards and the EU's In Vitro Diagnostic Regulation collectively reshape procurement specifications toward quality-system-certified rack manufacturers. Stakeholders must monitor how cell and gene therapy pipeline expansion redefines rack capacity requirements and automation interface protocols.
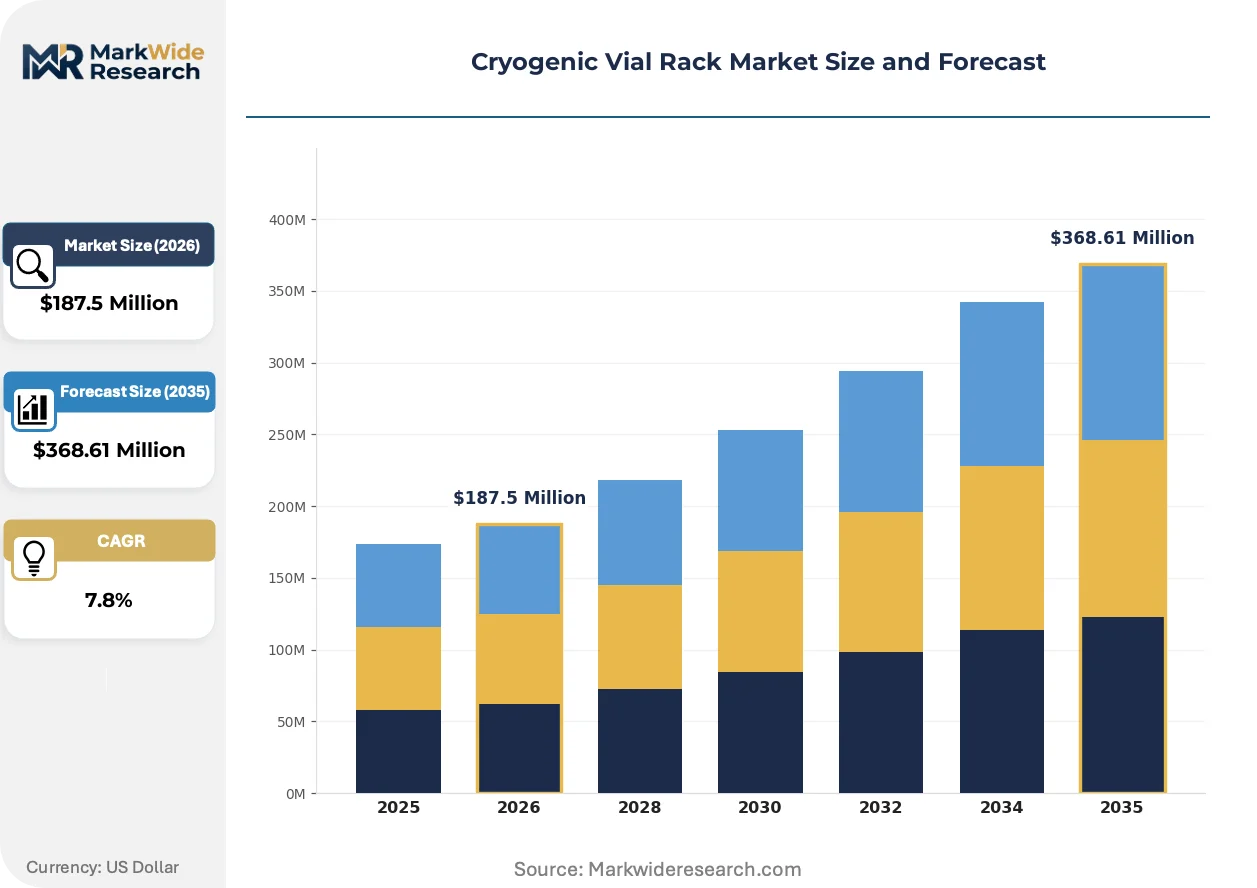
Market Dynamics
Cell therapy manufacturing scale-up is compressing rack procurement cycles from annual batch orders to quarterly automated system integrations, forcing suppliers to reconfigure production lines for rapid footprint customization.
Growth Catalysts
- Biobanking infrastructure expansion:NIH-funded repositories and private cryostorage networks in the United States multiply sample volumes, requiring barcode-traceable rack systems that integrate with automated retrieval infrastructure.
- ISO 20387 compliance mandates:Biobanking quality standards across Europe and Asia-Pacific compel facilities to source quality-system-certified racks with laser-etched identification matrices for full lot traceability.
- Liquid nitrogen vapor phase storage protocols:Advanced cell preservation methods demand medical-grade polypropylene racks rated for sustained minus 196 degrees Celsius exposure without thermal deformation.
Market Restraints
- Medical-grade resin supply concentration:Chinese polymer processors dominate certified polypropylene feedstock, creating geographic vulnerability for North American and European rack manufacturers.
- Aluminum thermal conductivity requirements:Pharmaceutical controlled-rate freezing applications require premium aluminum variants with uniform thermal properties, limiting substitution options and compressing margins.
- EU In Vitro Diagnostic Regulation compliance costs:Extended certification timelines and quality system documentation requirements delay new product introductions and elevate working capital needs.
Strategic Opportunities
- Cell therapy contract manufacturing expansion:CDMOs in Singapore and South Korea seek non-standard rack footprints for proprietary cryobag and vial combinations, opening white space for custom fabrication specialists.
- Automation interface standardization:Convergence of RFID tracking and robotic retrieval systems enables rack suppliers to capture recurring revenue through embedded sensor modules and software integration contracts.
- India biobanking infrastructure buildout:CDSCO-aligned national biorepository initiatives and regional cancer center networks generate demand for color-coded, multi-user workflow systems that reduce sample retrieval errors.
Industry Challenges
- Polymer engineering talent scarcity:Medical-grade polypropylene formulation expertise concentrates among aging specialist cohorts in Germany and Japan, constraining new product development velocity.
- Legacy freezer fleet incompatibility:Biobanks operating decade-old mechanical storage units face rack dimension mismatches with modern automation systems, forcing costly retrofit decisions or partial infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Vial Rack Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $368.61 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Rack, Plastic Rack, Aluminum Rack, Carbon Fiber Rack Application: Laboratory Storage, Pharmaceutical Research, Biobanking, Clinical Trials End User: Hospitals, Research Institutions, Biotechnology Companies, Pharmaceutical Firms Size: Standard Size, Custom Size, Small Size, Large Size |
| Companies Covered | Corning Incorporated, Heathrow Scientific, DWK Life Sciences, CELLTREAT Scientific Products, BioCision, Electron Microscopy Sciences, Spectrum Chemical, Genaxy Scientific, Tarsons Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Vial Rack Market Strategic Shifts
Material science advances and regulatory digitization are converging to transform rack specifications from passive storage containers into intelligent, traceable system components that anchor automated biorepository workflows.
Carbon fiber composite rack architectures are absorbing premium segment share from aluminum in pharmaceutical research settings. Cell therapy manufacturers in Switzerland and Massachusetts adopt these structures for their superior strength-to-weight ratios and elimination of thermal conductivity variation during controlled-rate freezing protocols. The material transition is absorbing capital allocation from traditional metal fabrication equipment toward automated composite layup and curing systems.
EMA's Medical Device Regulation implementation is reclassifying cryogenic storage accessories as Class I medical devices in Europe, mandating technical documentation and post-market surveillance systems. Rack suppliers must now maintain vigilance databases and periodic safety update reports, elevating compliance infrastructure costs. German and Dutch biobanks are responding by consolidating procurement around manufacturers with established quality management system certifications.
Cell therapy developers are unbundling rack procurement from freezer system purchases, establishing direct supplier relationships for customized footprints. This disintermediation of original equipment manufacturer captive supply chains accelerates in the United States, where CAR-T developers in Boston and San Francisco negotiate multi-year rack supply agreements independent of storage unit vendors. The shift compresses switching costs and elevates price transparency.
Cryogenic Vial Rack Market Segmentation
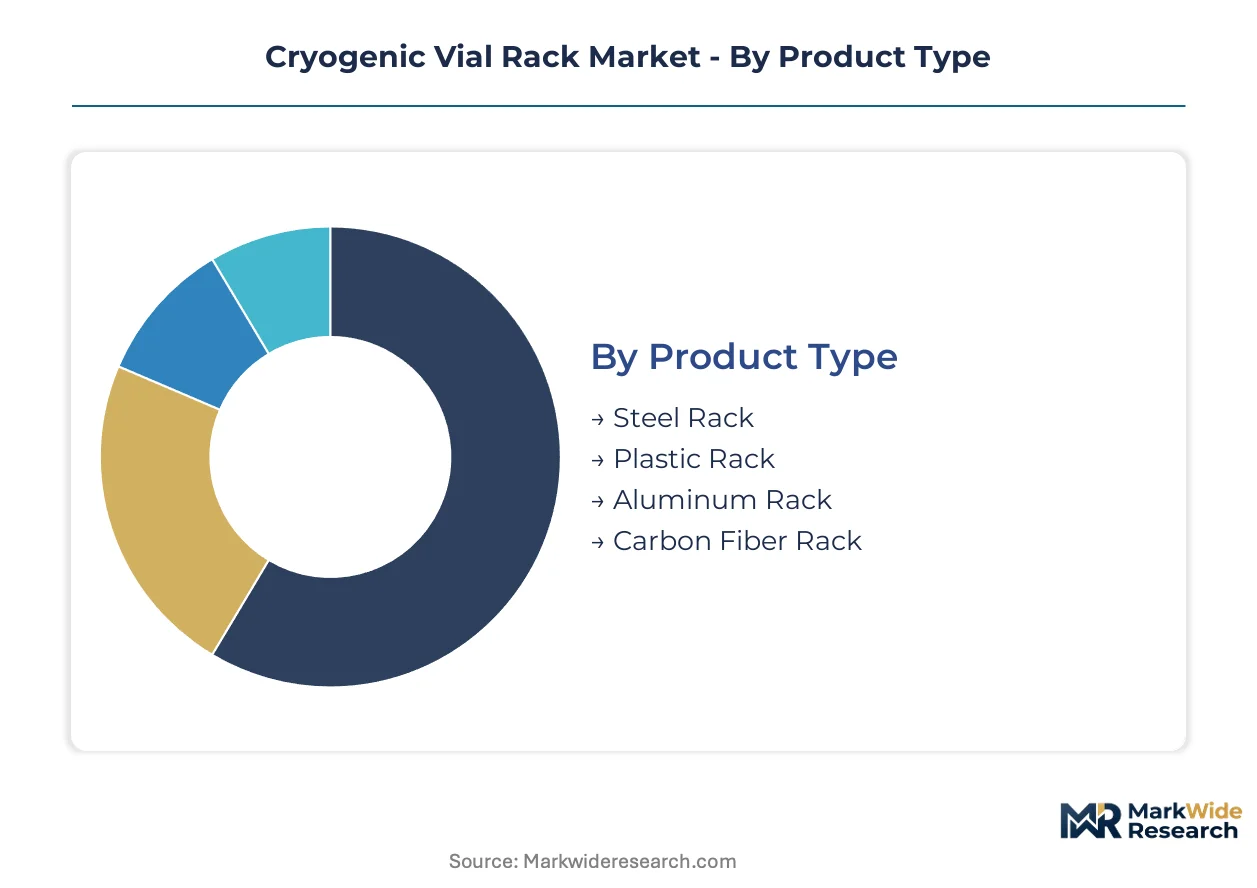
Cryogenic vial rack procurement patterns diver sharply between standardized biobank infrastructure and specialized cell therapy manufacturing. Rack configuration choices cascade through freezer compatibility, automation interface requirements, and regulatory documentation burdens.
Product Type:
Plastic racks dominate standalone laboratory deployments where thermal shock resistance and cost scalability matter most. Aluminum and carbon fiber variants embed primarily in integrated pharmaceutical freezing systems where thermal uniformity governs protocol compliance.
- Plastic Rack:Medical-grade polypropylene formulations withstand liquid nitrogen vapor phase exposure at minus 196 degrees Celsius without thermal deformation. Biobanking facilities in the United States favor these configurations for barcode-traceable high-density storage compatible with automated retrieval systems. Manufacturing scalability keeps unit economics favorable for multi-thousand rack deployments.
- Aluminum Rack:Uniform thermal conductivity properties enable precise controlled-rate freezing protocols essential for cellular product viability. Pharmaceutical research operations in Switzerland and Massachusetts specify these racks despite premium pricing, as temperature gradient consistency directly impacts CAR-T therapy manufacturing yields.
- Steel Rack:Legacy mechanical freezer fleets retain these durable structures for ambient-to-cryogenic transition storage where extreme cold exposure duration remains limited.
- Carbon Fiber Rack:Superior strength-to-weight ratios absorb capital allocation from traditional metal fabrication; cell therapy developers in Boston and Basel adopt these for proprietary cryobag configurations demanding non-standard footprints.
Volume placements concentrate in plastic rack configurations; the faster expansion belongs to carbon fiber architectures displacing aluminum in premium pharmaceutical applications.
Application:
Application segments stratify by regulatory intensity and sample throughput requirements, with biobanking demanding the most rigorous traceability infrastructure.
- Biobanking:ISO 20387 compliance mandates laser-etched identification matrices and quality-system-certified manufacturing. NIH-funded repositories and private cryostorage networks in the United States multiply rack procurement volumes as sample collections expand. Full lot traceability requirements compress supplier qualification timelines and elevate documentation standards.
- Pharmaceutical Research:Controlled-rate freezing protocols for cellular products require racks with verified thermal conductivity profiles. EMA's Medical Device Regulation reclassification as Class I devices in Europe mandates technical documentation and post-market surveillance systems, elevating compliance infrastructure costs for rack suppliers serving this segment.
- Laboratory Storage:Academic and commercial research labs prioritize color-coded workflow systems that reduce retrieval errors in multi-user environments.
- Clinical Trials:Decentralized cell therapy trials demand portable rack configurations compatible with varied site freezer dimensions and temporary storage protocols.
Procurement scale tilts toward biobanking infrastructure; steepest expansion trajectory sits with pharmaceutical research as cell therapy pipeline maturation accelerates manufacturing capacity builds.
End User:
End user categories reflect divergent procurement authority structures, with biotechnology companies increasingly disintermediating original equipment manufacturer captive supply chains.
- Biotechnology Companies:CAR-T developers in Boston and San Francisco negotiate multi-year rack supply agreements independent of storage unit vendors, compressing switching costs and elevating price transparency. Direct supplier relationships enable custom footprint specifications for proprietary cryobag and vial combinations.
- Pharmaceutical Firms:Integrated quality management systems demand rack manufacturers with established FDA current Good Manufacturing Practice compliance and vigilance database maintenance capabilities.
- Research Institutions:NIH-funded academic biorepositories balance automation compatibility requirements against constrained capital budgets, often prioritizing barcode-traceable plastic racks.
- Hospitals:Regional cancer center networks in India generate demand for color-coded multi-user workflow systems that reduce sample retrieval errors in high-stakes clinical environments.
Contract value concentrates with biotechnology companies; fastest share gains belong to hospital networks as national biorepository initiatives expand across Asia-Pacific markets.
Size:
Size segmentation tracks the tension between freezer fleet standardization and cell therapy manufacturing customization requirements.
- Custom Size:Non-standard footprints accommodate proprietary cryobag and vial combinations that cell therapy manufacturers in Singapore and South Korea specify for automated filling and sealing lines. CDMO procurement cycles compress from annual batch orders to quarterly integrations, forcing suppliers to reconfigure production lines for rapid customization.
- Standard Size:Dimensions align with dominant automated retrieval system specifications, enabling biobanks to maintain interoperability across multi-vendor freezer fleets.
- Small Size:Compact configurations serve decentralized clinical trial sites and satellite laboratory operations with limited storage capacity.
- Large Size:High-density architectures maximize cubic efficiency in central biorepositories where land and facility costs drive space optimization.
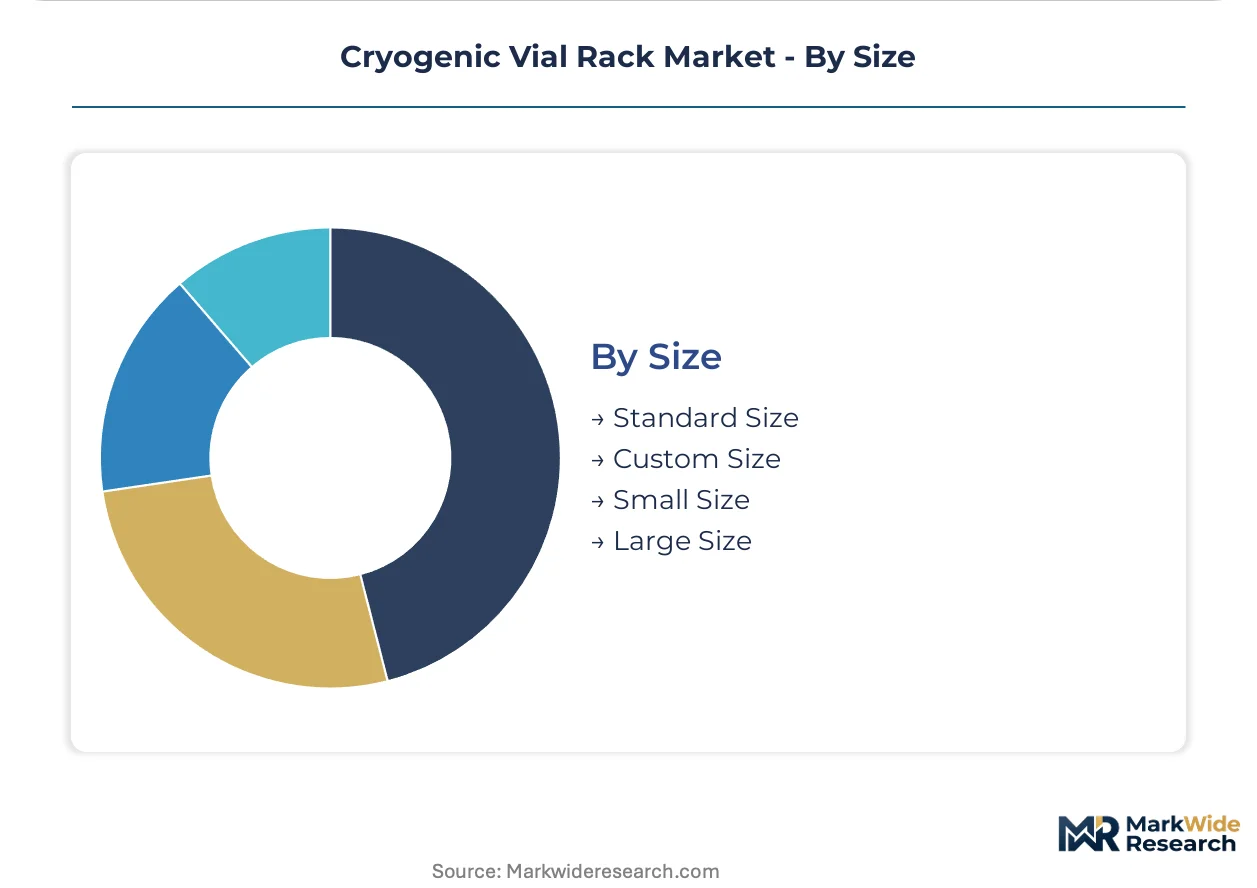
Shipment volumes cluster in standard dimensions; custom fabrication commands the steepest expansion trajectory as cell therapy manufacturing scales beyond templated configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polypropylene feedstock concentrates among Chinese polymer processors, creating geographic vulnerability for North American and European rack manufacturers while driving supply chain realignment toward certified resin sources.
United States
NIH-funded biorepositories and private cryostorage networks multiply sample volumes across Massachusetts and California. FDA 21 CFR Part 11 compliance requirements for electronic records push laboratories toward barcode-traceable rack systems. Boston and San Francisco host CAR-T developers negotiating direct multi-year rack supply agreements independent of storage unit vendors.
Germany
ISO 20387 biobanking standards compel facilities to source quality-system-certified racks with laser-etched identification matrices. EMA Medical Device Regulation reclassifies cryogenic storage accessories as Class I devices, mandating technical documentation. Bavaria and North Rhine-Westphalia anchor European demand through established quality management system certifications.
China
NMPA-aligned medical device regulations reshape procurement specifications toward quality-system-certified manufacturers. Polymer processors in Jiangsu and Zhejiang provinces realign resin supply chains toward medical-grade polypropylene grades certified for liquid nitrogen exposure. Yangtze River Delta biobanking infrastructure expands capacity for national cell therapy pipeline growth.
Switzerland
Cell therapy manufacturers in Basel adopt carbon fiber composite rack architectures for controlled-rate freezing protocols. Swissmedic vigilance database requirements elevate compliance infrastructure costs for rack suppliers. The Basel pharmaceutical cluster drives premium segment demand through strength-to-weight ratio specifications for proprietary cryobag configurations.
India
CDSCO-aligned national biorepository initiatives and regional cancer center networks generate procurement volumes for color-coded workflow systems. Maharashtra and Karnataka state governments fund biobanking infrastructure buildout. Mumbai and Bangalore biorepositories prioritize multi-user retrieval systems that reduce sample handling errors in high-stakes clinical environments.
Cryogenic Vial Rack Market Competitive Environment
Global majors compete with regional champions across material science capabilities and regulatory compliance infrastructure. Market structure tilts toward consolidated premium tiers where FDA and EMA certification barriers limit new entry, while standard plastic rack segments fragment across regional fabricators. Three archetypes dominate: integrated laboratory supply conglomerates with glass-to-plastics manufacturing heritage, specialized bioprocessing workflow designers, and custom fabrication specialists serving cell therapy CDMOs. Competitive moves concentrate on automation interface partnerships and rapid footprint customization capabilities.
Among integrated laboratory supply conglomerates, Corning Incorporated and DWK Life Sciences occupy positions anchored in manufacturing heritage translated into polymer rack reliability. Heathrow Scientific exemplifies the workflow specialization archetype through color-coded system design. These three entities represent distinct competitive vectors: materials science depth, regional brand trust, and user-experience optimization.
| Leading Market Players |
|---|
| Corning Incorporated |
| Heathrow Scientific |
| DWK Life Sciences |
| CELLTREAT Scientific Products |
| BioCision |
| Electron Microscopy Sciences |
| Spectrum Chemical |
| Genaxy Scientific |
| Tarsons Products |
| Others |
Value Chain & Pricing Dynamics
Medical-grade polypropylene resin costs cascade through three distinct pricing tiers as Chinese polymer processors in Jiangsu and Zhejiang provinces control certified feedstock supply for liquid nitrogen-rated grades. Biobanking procurement managers face escalating premiums for laser-etched traceability features while cell therapy CDMOs absorb rapid customization surcharges.
Pricing Analysis
After-sales service bundling separates rack suppliers into two camps: those including automation interface validation and RFID module calibration versus unbundled hardware-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Price erosion runs through standard plastic rack segments as regional fabricators compete on undifferentiated medical-grade polypropylene configurations. Biotechnology companies negotiating direct multi-year agreements exhibit lowest price sensitivity; academic research institutions operating NIH-funded repositories face tightest capital constraints.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO-aligned biorepository initiatives and China's NMPA medical device regulations are reshaping sourcing patterns toward local certified manufacturers. Supply concentrates among Chinese polymer processors for medical-grade polypropylene, German specialists for aluminum thermal conductivity formulations, and Swiss-German composite engineers for carbon fiber architectures. Raw material dependencies center on propylene feedstock, borosilicate-compatible resin additives, and aerospace-grade carbon fiber prepregs. Single-source vulnerability in Chinese certified polypropylene creates geographic concentration risk. Distribution runs through laboratory supply distributors, direct OEM partnerships, and cell therapy CDMO contract channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EMA Medical Device Regulation compliance costs and ISO 20387 certification barriers eliminate marginal regional fabricators lacking quality management system infrastructure.
For Market Incumbents: Acquire carbon fiber composite manufacturing capabilities to defend pharmaceutical research segment share against aluminum displacement. Integrate backward into medical-grade polypropylene compounding to reduce Chinese feedstock dependency. Expand laser-etching and RFID embedding capacity to capture automation interface recurring revenue streams threatened by specialized workflow designers. For New Entrants and Emerging Players: Rapid customization technology for non-standard rack footprints offers entry path into Singapore and South Korean CDMO markets. Target India's CDSCO-aligned national biorepository buildout with color-coded multi-user workflow systems. Pursue hospital network procurement contracts through regional cancer center relationships rather than competing for consolidated biobank infrastructure tenders. For Investors and Strategic Acquirers: Cell therapy manufacturers unbundling rack procurement from freezer system purchases is the leading indicator that direct supplier relationships will reshape competitive architecture. Five-to-ten year viability favors manufacturers with established FDA and EMA quality system certifications and vigilance database maintenance capabilities. Monitor carbon fiber composite adoption rates in Swiss and Massachusetts pharmaceutical clusters as inflection signal for material transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Interface Partnership | RFID tracking convergence with robotic retrieval systems enables recurring revenue capture through embedded sensor modules. |
| Carbon Fiber Manufacturing Scale-Up | Cell therapy developers in Basel and Boston adopt composite architectures for proprietary cryobag configurations. |
| Laser-Etching Capacity Expansion | FDA lot traceability mandates for cryopreserved cellular products require identification matrix integration capabilities. |
| Regional Certification Investment | EMA Class I medical device reclassification elevates compliance infrastructure costs that filter marginal competitors. |
| CDMO Custom Fabrication Capability | Quarterly procurement cycles in Singapore and South Korea demand rapid footprint customization production lines. |
Study Parameters
SEC 10-K filings, EMA medical device registration databases, and NIH biorepository procurement records formed the secondary backbone of this analysis. Primary interviews with biobank operations directors, cell therapy manufacturing executives, laboratory supply procurement managers, and polymer engineering specialists validated demand assumptions. Bottom-up rack shipment estimates triangulated against top-down biobanking infrastructure capacity expansion data.
Historical trendline analysis of biorepository automation investments and cell therapy manufacturing facility buildouts anchored projection modeling across the analysis window. Segmentation dimensions included material type, application intensity, end-user procurement authority structure, and regional regulatory framework cluster. CAGRs derived from weighted average of infrastructure expansion trajectories and therapeutic pipeline maturation timelines. Forecast inputs incorporated ISO 20387 adoption curves and FDA 21 CFR Part 11 compliance penetration rates.
Several conditions sit outside the modeled scope, including sudden tariff disruptions to Chinese polypropylene feedstock, breakthroughs in ambient-temperature cell preservation technologies, and unanticipated EMA regulatory reclassification of storage accessories to higher device classes. Forecasts reflect documented assumptions about therapeutic pipeline progression and infrastructure funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Global Biotechnology Reagents Market