
 Fluorescence Immunoassay Analyzers Market | 2026-2036
Fluorescence Immunoassay Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence Immunoassay Analyzers Market Foresight
CLIA-waived testing capability is collapsing the barrier between centralized labs and near-patient settings, reshaping procurement priorities across the fluorescence immunoassay analyzer landscape. F. Hoffmann-La Roche leverages its deep reagent-analyzer bundling strategy to lock in long-term service contracts with major health networks. Danaher Corporation sustains competitive pressure through aggressive backward integration into critical optical component supply. Abbott Laboratories dominates the cardiac marker detection segment with platforms engineered for emergency department throughput demands.
Fluorescence immunoassay analyzers are quantitative diagnostic instruments that excite fluorophore-labeled antibodies with specific wavelength light, then measure emitted light intensity at longer wavelengths to determine analyte concentration in biological samples; most benchtop systems operate with detection limits reaching picogram-per-milliliter sensitivity and throughput rates of 80-200 tests per hour. These instruments serve primarily in clinical diagnostics, pharmaceutical development, and epidemiological surveillance where rapid, specific biomarker quantification determines treatment decisions or regulatory submissions. Fully automated analyzers command the largest installed base due to labor cost containment priorities, while portable analyzer demand is accelerating fastest among decentralized care models and resource-limited settings. Lateral flow immunoassay technology occupies expanding share in screening applications where speed supersedes analytical precision requirements.
FDA quality-system regulation and CLIA complexity categorization directly determine which analyzer configurations qualify for waived, moderate, or high-complexity laboratory deployment, thereby segmenting addressable market boundaries. The EU In Vitro Diagnostic Regulation enforces stricter clinical evidence and post-market surveillance obligations, elevating compliance costs for manufacturers seeking CE-marked access. Stakeholders must monitor evolving reimbursement coding for multiplexed fluorescence panels, as payor acceptance of combined infectious disease and cardiac marker testing will determine whether analyzer utilization rates justify capital replacement cycles.
Market Dynamics
CLIA-waived testing capability is collapsing the barrier between centralized laboratories and near-patient settings, fundamentally restructuring procurement priorities and analyzer configuration requirements across the fluorescence immunoassay landscape.
Growth Catalysts
- FDA CLIA Complexity Reclassification:Waived-test designation for multiplex cardiac and infectious disease panels expands addressable placement sites into physician offices and urgent care clinics previously excluded from analyzer procurement.
- Optical Component Cost Curve:CMOS sensor and LED excitation source commoditization reduces benchtop system bill-of-materials, accelerating replacement cycles for legacy chemiluminescence platforms in mid-volume hospital laboratories.
- Emergency Department Throughput Mandates:Hospital administrators demand sub-15-minute turnaround for cardiac troponin and natriuretic peptide quantification, privileging fluorescence analyzers with random-access STAT processing over batch-oriented alternatives.
Market Restraints
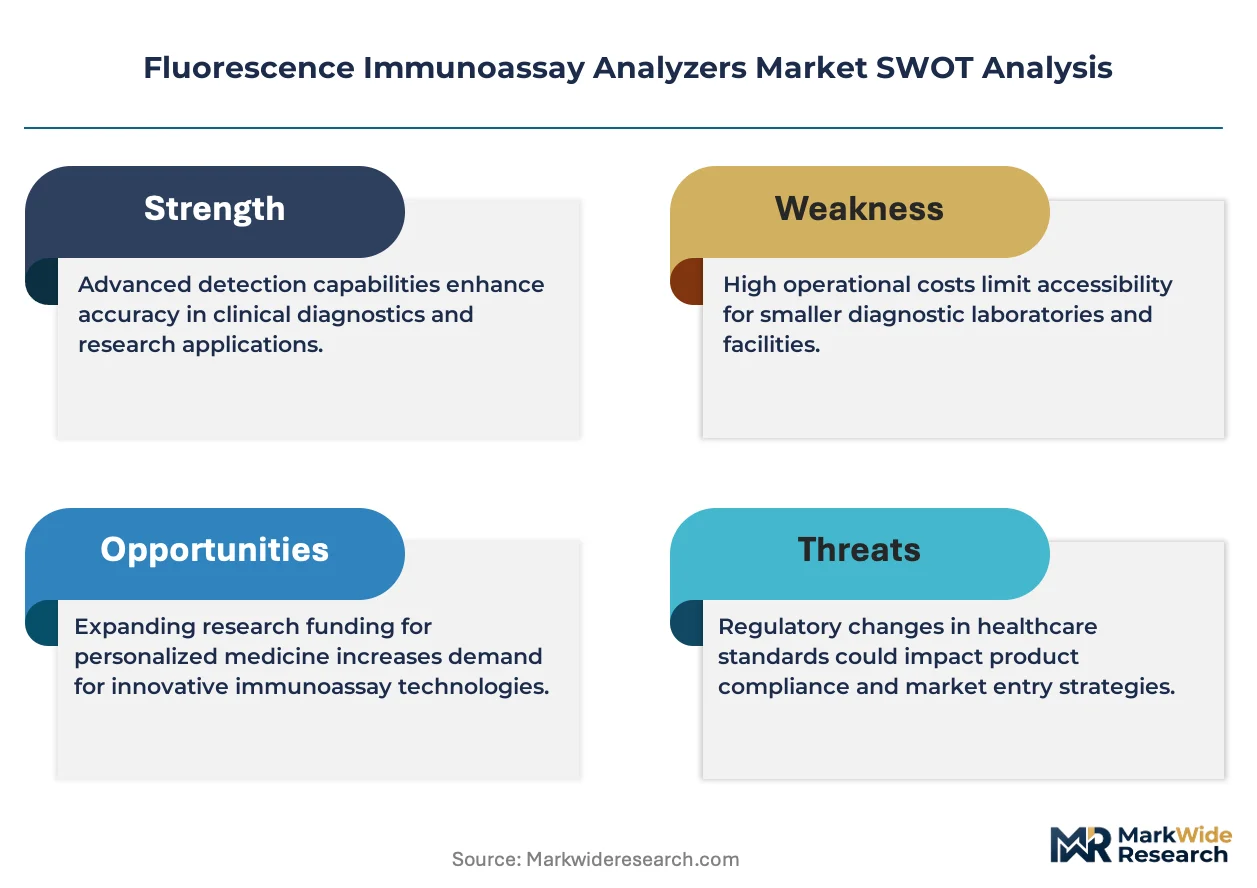
- Reagent-Analyzer Bundling Lock-in:Closed-system architectures prevent third-party assay development, constraining laboratory flexibility and elevating lifetime ownership costs versus open-platform alternatives.
- EU IVDR Clinical Evidence Burden:Stricter post-market surveillance and performance evaluation requirements under the In Vitro Diagnostic Regulation extend CE-marking timelines and compliance expenditures for manufacturers.
- Trained Operator Availability:Moderate- and high-complexity analyzer operation requires medical laboratory scientist certification, limiting deployment in resource-constrained settings without CLIA-waiver eligibility.
Strategic Opportunities
- India Diagnostic Laboratory Network Expansion:Corporate hospital chains and standalone pathology franchises are consolidating procurement, creating volume concentration for analyzers with reagent rental and per-test pricing structures.
- Multiplexed Respiratory Panel Reimbursement:Combined SARS-CoV-2, influenza, and RSV detection on single cartridge formats commands premium coding, incentivizing analyzer placement in ambulatory settings during respiratory seasonality.
- Artificial Intelligence-Assisted Result Interpretation:Machine learning algorithms for quality control flagging and rare analyte pattern recognition differentiate premium analyzer tiers, justifying elevated capital expenditure in reference laboratories.
Industry Challenges
- Legacy LIS Integration Complexity:Hospital information systems with decades-old HL7 interface specifications require costly middleware development for seamless analyzer connectivity and bidirectional data flow.
- Calibration and Control Material Supply Continuity:Lyophilized proficiency testing materials and traceable calibrator lots face manufacturing concentration risk, threatening analytical accuracy maintenance during supplier disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence Immunoassay Analyzers Market |
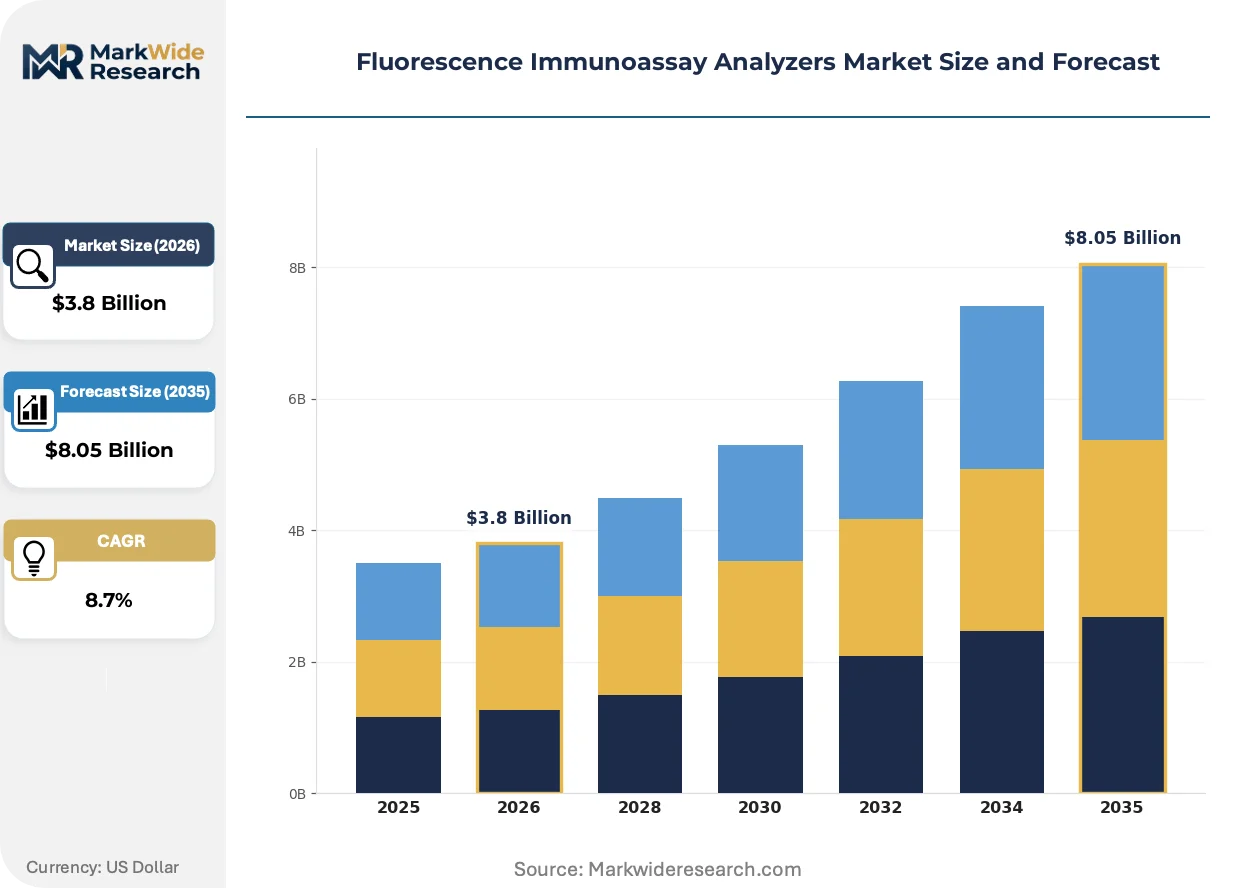
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzer, Portable Analyzer, Fully Automated Analyzer, Semi-Automated Analyzer Technology: Time-Resolved Fluorescence, Fluorescence Polarization, Fluorescence Resonance Energy Transfer, Lateral Flow Immunoassay Application: Infectious Disease Testing, Cardiac Marker Detection, Hormone Analysis, Oncology Marker Detection End User: Diagnostic Laboratories, Clinical Research Organizations, Blood Banks, Academic Laboratories |
| Companies Covered | F. Hoffmann-La Roche, Danaher Corporation, Thermo Fisher Scientific, DiaSorin, Beckman Coulter, Abbott Laboratories, bioMérieux, Sysmex Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence Immunoassay Analyzers Market Shifts & Advancements
Fluorescence immunoassay technology is converging with microfluidics and smartphone-based detection, compressing the form factor and cost structure boundaries that historically separated laboratory-grade from point-of-care instrumentation.
Time-resolved fluorescence detection is miniaturizing through lanthanide chelate chemistry integration into cartridge-based microfluidic architectures. Rural health clinics and pharmacy-based testing sites in Brazil and Southeast Asia are adopting these palm-sized readers for infectious disease screening. The technology is miniaturizing the minimum viable laboratory footprint from benchtop to pocket-scale, enabling deployment in settings without cold chain or trained technician infrastructure.
The EU In Vitro Diagnostic Regulation enforces stricter clinical evidence and post-market surveillance obligations than its predecessor directive. Manufacturers must generate prospective performance studies and maintain systematic vigilance systems, elevating compliance costs for CE-marked market access. Small-to-mid sized analyzer developers are responding through notified body consolidation and strategic deferral of novel assay launches until regulatory clarity stabilizes.
Hospital procurement committees are unbundling analyzer placement from exclusive reagent supply agreements, demanding competitive assay sourcing flexibility. Reference laboratories and integrated delivery networks are replacing sole-source contracts with dual-vendor strategies that pit reagent manufacturers against each other on per-test economics. This behavioral shift is most visible in United States health systems where laboratory consolidation has concentrated purchasing power within centralized supply chain functions.
Fluorescence Immunoassay Analyzers Market Segmentation
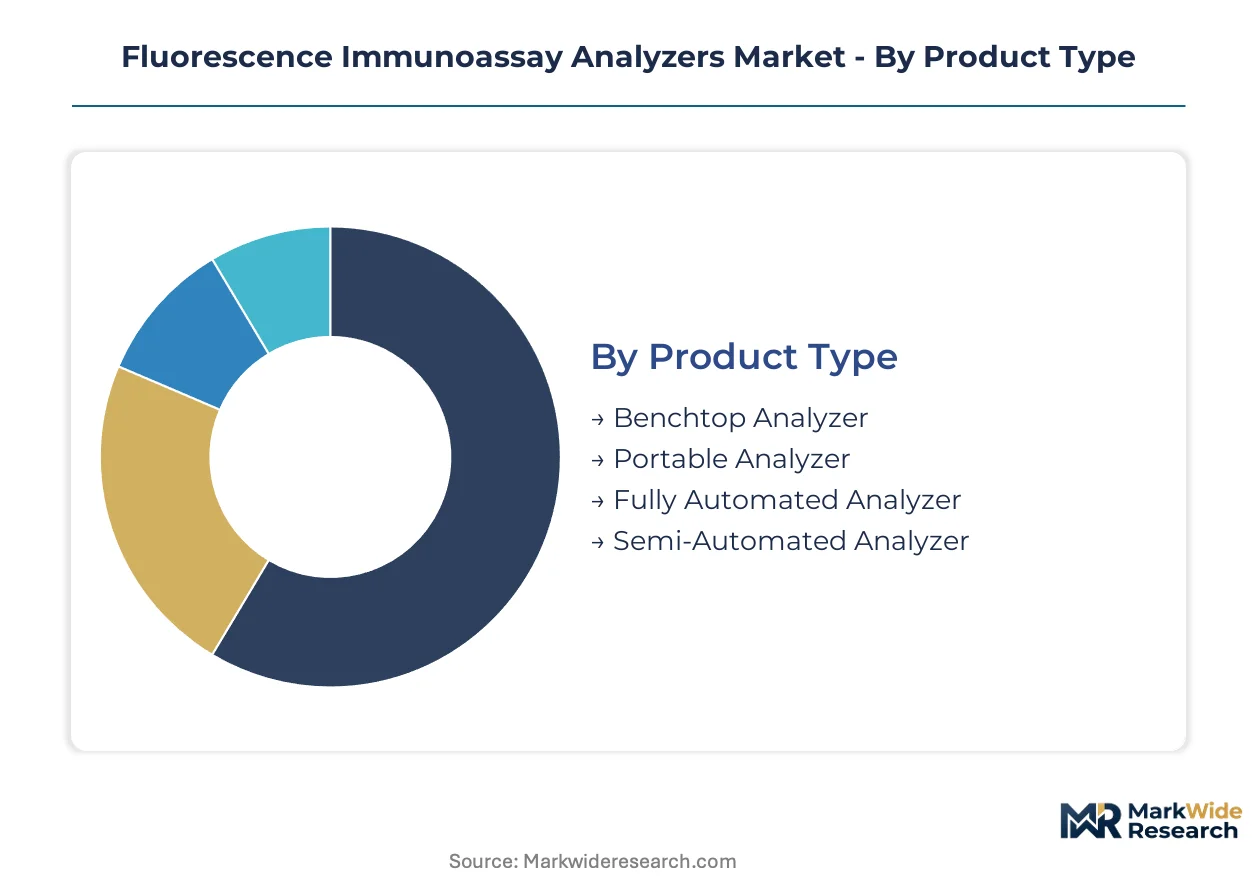
Analyzer configuration choices determine regulatory pathway eligibility, throughput economics, and competitive substitution exposure across the fluorescence immunoassay landscape. Procurement committees weigh capital intensity against reagent lock-in risk when segmenting vendor shortlists.
Product Type:
Portable analyzers face the most acute substitution pressure from smartphone-integrated lateral flow readers and electrochemical biosensors in decentralized care settings.
- Fully Automated Analyzer:Random-access architectures process 80-200 tests per hour with minimal operator intervention. Hospital laboratories in the United States prioritize these systems for labor cost containment and STAT cardiac marker workflows.
- Benchtop Analyzer:Mid-volume platforms balance throughput with capital efficiency, serving regional reference laboratories and consolidated health network satellites. CMOS sensor commoditization is compressing system bill-of-materials and accelerating replacement cycles for legacy chemiluminescence units.
- Portable Analyzer:Palm-sized units with LED excitation and cartridge-based microfluidics enable CLIA-waived deployment in urgent care clinics and pharmacy settings.
- Semi-Automated Analyzer:Requires manual sample preparation and reagent addition, limiting placement to moderate-complexity laboratories with certified medical laboratory scientists.
Fully automated analyzers anchor the volume base while portable analyzers gain share at the steepest rate.
Technology:
Cost tier differentiation separates premium detection modalities from commodity screening formats in procurement evaluations.
- Time-Resolved Fluorescence:Lanthanide chelate chemistry eliminates background autofluorescence through microsecond-scale emission decay measurement. Reference laboratories in Germany and Switzerland deploy these systems for high-sensitivity cardiac troponin and endocrine panels.
- Lateral Flow Immunoassay:Nitrocellulose membrane formats with visual or smartphone-read fluorescence enable mass screening without instrumentation infrastructure. Brazil's pharmacy-based testing networks and Southeast Asia's rural health posts are expanding adoption for infectious disease surveillance.
- Fluorescence Polarization:Measures molecular rotation rates to quantify small-molecule analytes without separation steps, serving therapeutic drug monitoring applications.
- Fluorescence Resonance Energy Transfer:Donor-acceptor pair proximity detection enables homogeneous assay formats, reducing wash steps and time-to-result in research settings.
Lateral flow immunoassay commands the largest test volume while time-resolved fluorescence delivers the highest analytical performance premium.
Application:
Customer type concentration varies sharply across clinical use cases, with emergency department procurement dominating cardiac workflows.
- Cardiac Marker Detection:Troponin and natriuretic peptide quantification demands sub-15-minute turnaround times. United States hospital administrators mandate STAT processing capabilities, privileging random-access fluorescence analyzers over batch-oriented alternatives.
- Infectious Disease Testing:Multiplexed respiratory panels combining SARS-CoV-2, influenza, and RSV detection command premium reimbursement coding. Ambulatory settings in the United States scale analyzer placement seasonally around respiratory virus circulation patterns.
- Hormone Analysis:Fertility and thyroid panels require picogram-per-milliliter sensitivity, driving specification requirements in reproductive endocrinology practices.
- Oncology Marker Detection:Tumor marker quantification for treatment monitoring and recurrence surveillance serves oncology clinics and reference laboratories with specialized immunoassay expertise.
Infectious disease testing generates the highest test frequency while cardiac marker detection commands the steepest instrument specification requirements.
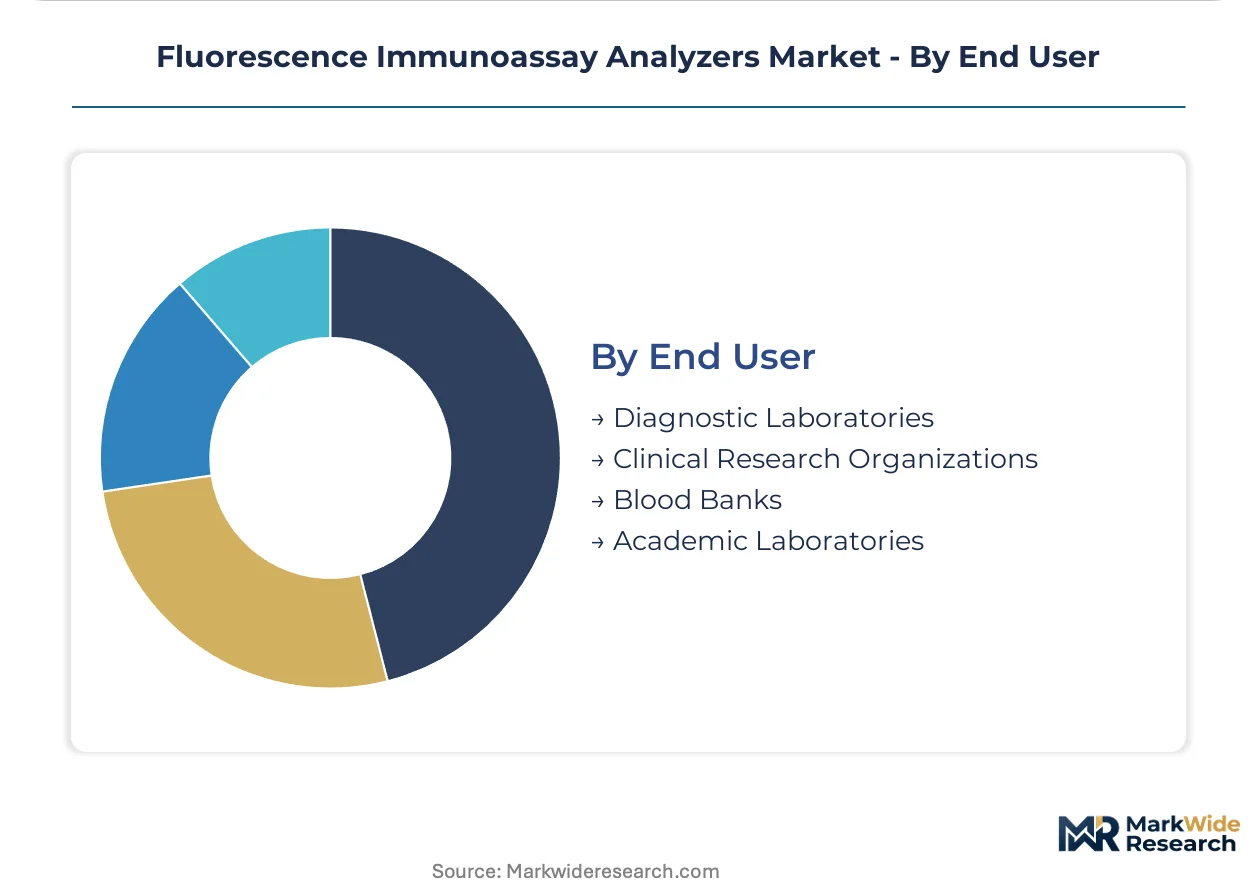
End User:
Supply concentration in calibrator and control material manufacturing shapes service continuity priorities across laboratory types.
- Diagnostic Laboratories:Corporate hospital chains and standalone pathology franchises in India are consolidating procurement, creating volume concentration for analyzers with reagent rental and per-test pricing structures.
- Clinical Research Organizations:Bioanalytical groups require GLP-compliant systems with extensive validation documentation for pharmaceutical development support.
- Blood Banks:Donor screening and infectious disease marker testing demand high-throughput batch processing with regulatory compliance for transfusion safety.
- Academic Laboratories:Research-focused installations prioritize open-platform architectures enabling custom assay development and publication-grade analytical characterization.
Diagnostic laboratories anchor the installed base while clinical research organizations present the most specialized service and validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical component manufacturing and analyzer assembly concentrate in Germany, the United States, Japan, and Switzerland, while diagnostic laboratory procurement scales fastest in India and Brazil as healthcare networks consolidate.
United States
Hospital consolidation and laboratory network expansion drive analyzer procurement at scale, with integrated delivery networks centralizing capital equipment decisions. FDA CLIA complexity reclassification for waived cardiac and infectious disease panels expands placement into physician offices and urgent care clinics. The Boston-Cambridge corridor anchors IVD development, while Texas Medical Center procurement committees unbundle analyzer placement from exclusive reagent agreements.
Germany
Reference laboratories in Germany deploy time-resolved fluorescence systems for high-sensitivity cardiac troponin and endocrine panels, demanding picogram-per-milliliter analytical performance. EU IVDR enforcement extends CE-marking timelines and elevates compliance expenditures for manufacturers seeking European market access. The Rhine-Main industrial cluster around Frankfurt hosts precision optical component fabrication serving analyzer OEMs.
India
Corporate hospital chains and standalone pathology franchises consolidate procurement, creating volume concentration for analyzers with reagent rental and per-test pricing structures. CDSCO regulatory pathways for IVD imports shape market entry strategies for multinational manufacturers. Diagnostic laboratory networks in Maharashtra and Karnataka scale analyzer deployment as healthcare penetration deepens in tier-2 cities.
Japan
Automated analyzer demand concentrates in university hospitals and reference laboratories prioritizing throughput and random-access STAT processing. PMDA quality system requirements for IVD manufacturing maintain stringent post-market surveillance obligations. The Kansai region around Osaka hosts specialized optical component suppliers serving domestic analyzer producers.
Brazil
Pharmacy-based testing networks and rural health posts expand adoption of portable fluorescence readers for infectious disease screening without cold chain infrastructure. ANVISA regulatory harmonization with Mercosur standards streamlines import approval for CLIA-waived analyzer configurations. São Paulo's diagnostic laboratory consolidation creates procurement leverage for health network administrators.
Fluorescence Immunoassay Analyzers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the fluorescence immunoassay analyzer landscape. Consolidated multinational conglomerates with diversified life science portfolios dominate premium benchtop and fully automated segments, while specialized IVD pure-plays and emerging portable system developers occupy distinct competitive tiers. Three archetypes define competitive positioning: integrated diagnostic giants with reagent-analyzer bundling strategies, precision optical component specialists backward integrated into system assembly, and point-of-care innovators compressing form factors through microfluidic integration. Dominant competitive moves include strategic reagent supply contract lock-in and geographic expansion through distributor network acquisition.
Among Swiss and German-based diagnostic conglomerates, F. Hoffmann-La Roche and Siemens Healthineers exemplify the integrated reagent-analyzer bundling archetype that dominates hospital laboratory procurement. Danaher Corporation occupies a position representing precision instrumentation conglomerates with backward integration into optical component supply chains. At the portable and point-of-care tier, Abbott Laboratories exemplifies specialists in cardiac marker detection platforms engineered for emergency department throughput demands. These three anchors represent distinct strategic vectors: bundling-driven installed base lock-in, component cost control, and clinical workflow specialization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Danaher Corporation |
| Thermo Fisher Scientific |
| DiaSorin |
| Beckman Coulter |
| Abbott Laboratories |
| bioMérieux |
| Sysmex Corporation |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
FDA quality-system regulation and CLIA complexity categorization simultaneously gates supplier qualification tiers and segments price differentiation across analyzer configurations, forcing manufacturers to absorb compliance costs into premium-tier pricing while commoditized portable systems compete on per-test economics alone.
Pricing Analysis
FDA CLIA complexity categorization dictates the pricing tier structure across fluorescence immunoassay analyzers. Three-tier pricing separates waived-configuration portable units from moderate-complexity benchtop systems and high-complexity fully automated platforms, with certification grade and throughput scale as primary price differentiation drivers. Cost compression in mid-volume benchtop segments intensifies because CMOS sensor commoditization erodes hardware margins. Physician office clinics exhibit highest price sensitivity, while reference laboratories demonstrate lowest sensitivity due to reagent-analyzer bundling lock-in effects.
Supply Chain Analysis
Strategic stockpiling of optical components and calibrator materials dominates inventory strategy over just-in-time approaches, given single-source vulnerability in lanthanide chelate chemistry supply. Manufacturing concentrates in Germany, the United States, and Japan for precision optical assembly, while CMOS sensors and LED excitation sources draw from Taiwan and South Korea. Lyophilized proficiency testing materials and traceable calibrator lots face manufacturing concentration risk. Distribution runs through integrated delivery network procurement committees and diagnostic laboratory GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence immunoassay analyzers sit in early-stage cyclical recovery as hospital capital equipment budgets normalize following pandemic-era respiratory panel demand spikes.
For Market Incumbents: Consolidate reagent-analyzer bundling contracts with major health networks before procurement committees complete their shift toward dual-vendor sourcing strategies. Deepen backward integration into captive LED excitation source production to defend margins against CMOS commoditization pressure. Prioritize CLIA-waiver pathway investments for multiplex cardiac panels to preempt portable electrochemical biosensor substitution in urgent care settings.
For New Entrants and Emerging Players: Lead with microfluidic cartridge-based architectures targeting India's consolidating pathology franchise networks, where reagent rental pricing models penetrate faster than capital sales. Focus initial deployment on Maharashtra and Karnataka tier-2 cities where corporate hospital chains centralize procurement decisions. Pursue CDSCO import pathway partnerships with established diagnostic distributors rather than direct market entry.
For Investors and Strategic Acquirers: EU IVDR implementation reshapes the acquisition landscape by elevating compliance infrastructure value above novel assay pipeline depth. Position holdings for 5-10 year horizon viability by targeting precision optical component specialists with existing notified body relationships and systematic vigilance capabilities. Monitor CE-marking timeline compression as the inflection signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waiver Pathway Expansion | FDA complexity reclassification unlocks physician office placement for multiplex cardiac panels. |
| Backward Integration into Optical Components | CMOS sensor and LED source captive supply compresses benchtop system bill-of-materials. |
| Reagent Rental Model Deployment | Per-test pricing structures penetrate India's consolidating diagnostic laboratory networks. |
| Dual-Vendor Sourcing Strategy | Reference laboratories unbundle exclusive agreements to pit reagent manufacturers on economics. |
| AI-Assisted Quality Control Integration | Machine learning algorithms differentiate premium analyzer tiers in high-throughput STAT processing. |
Research Methodology
A spread of perspectives from hospital laboratory directors, IVD regulatory affairs specialists, diagnostic procurement managers, and biomedical engineers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from FDA 510(k) filings, CMS reimbursement coding databases, EU IVDR notified body guidance documents, and CDSCO import registration records. Bottom-up installed base modeling and top-down healthcare capital expenditure triangulation anchored volume and value estimates.
Segmentation dimensions modeled span analyzer configuration type, detection technology modality, clinical application area, and end-user laboratory category across the projection horizon. CAGRs derive from regression analysis against historical replacement cycle patterns and capital equipment procurement elasticity. Forecast inputs incorporate CLIA-waiver expansion trajectories, respiratory panel reimbursement coding evolution, and optical component cost curve assumptions.
The analysis sits within stated boundaries; outcomes outside sustained hospital consolidation momentum and stable regulatory pathway timelines would require recalibration. Forecasts reflect documented assumptions regarding procurement committee behavioral shifts and reagent-analyzer bundling contract durations. Revision becomes warranted when EU IVDR enforcement intensity or FDA complexity reclassification pace crosses threshold discontinuities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Global Bioprocess Container Market