
 Lab Scale Bioreactors Market | 2026-2036
Lab Scale Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Scale Bioreactors Market Analytics
Cell and gene therapy process development is hardening as the dominant demand vertical for lab scale bioreactors. Merck KGaA leverages its integrated life science platform to anchor supply relationships across European biotech clusters. Thermo Fisher Scientific dominates North American distribution channels through extensive field service networks. Sartorius AG differentiates its portfolio with advanced single-use sensor integration for perfusion applications.
Lab scale bioreactors are benchtop or pilot-scale vessels engineered for controlled biological cultivation, typically ranging from milliliters to ten liters in working volume, with precise regulation of dissolved oxygen, pH, temperature, and agitation to optimize cell growth and metabolite production. Stainless steel systems retain entrenched positions in vaccine development workflows requiring steam-in-place sterilization protocols, while single-use formats capture expanding share in protein production applications where campaign flexibility reduces cross-contamination risk. Fed-batch technology leads current installed base composition, though perfusion configurations represent the fastest-growing segment as continuous bioprocessing gains traction among contract development organizations seeking intensified titers.
FDA process validation guidelines and EMA Good Manufacturing Practice standards shape equipment qualification requirements and documentation burdens for suppliers seeking pharmaceutical company procurement approval. ISO 14644 cleanroom classifications and ASME BPE design standards further constrain system architecture decisions for manufacturers targeting regulated end users. Stakeholders must monitor evolving biosafety containment classifications and regional divergence in single-use material extractables testing protocols to sustain market access across jurisdictions.
Market Dynamics
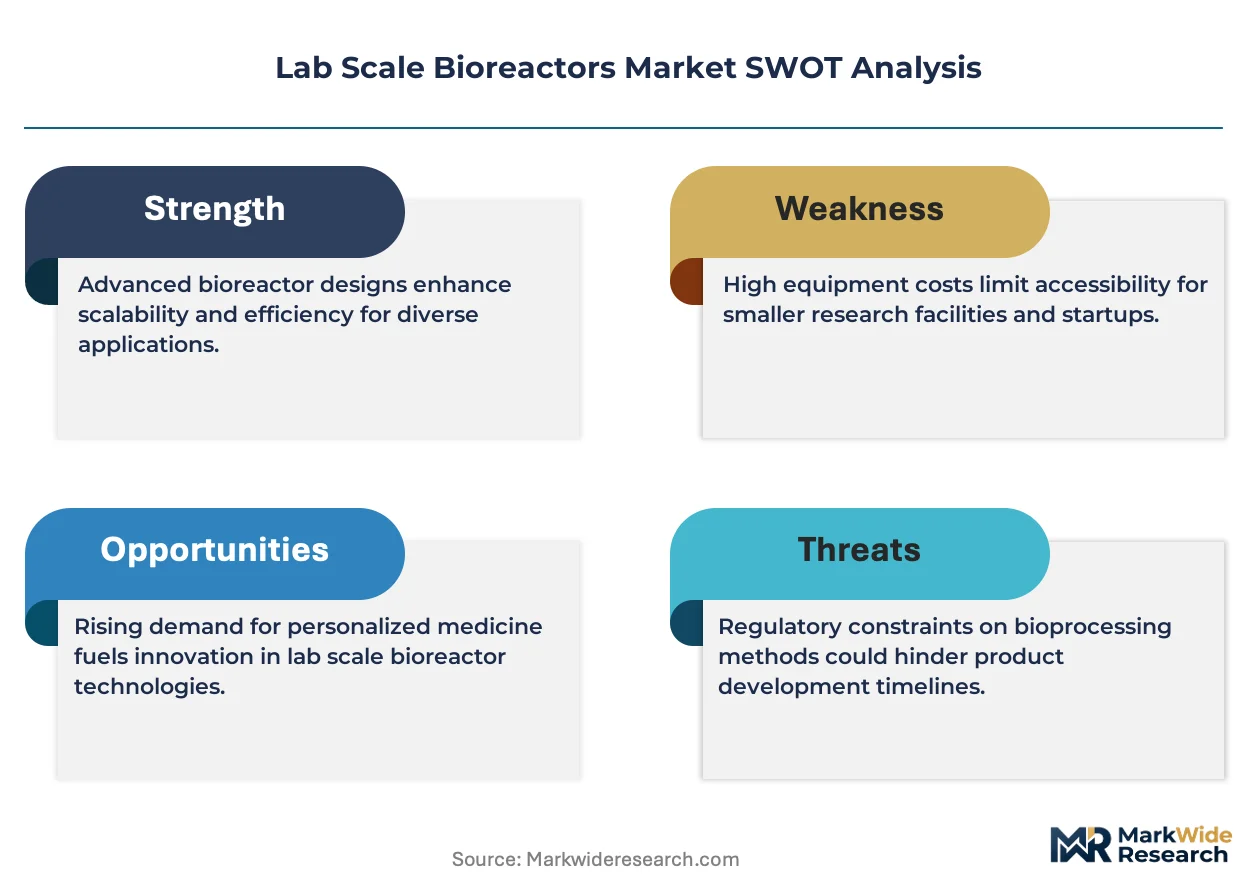
Single-use technology adoption is compressing equipment qualification timelines while FDA process validation requirements extend documentation burdens, creating a bifurcated procurement environment where campaign flexibility competes against steam-in-place sterilization protocols.
Growth Catalysts
- Cell and Gene Therapy Expansion:Developers scaling upstream process development require precision-controlled systems for viral vector production and cell line characterization. Academic research hubs in the United States, Germany, and China anchor instrument placement.
- FDA Process Validation Requirements:Equipment qualification standards under current pharmaceutical manufacturing guidelines reshape supplier documentation protocols. Biologics manufacturers prioritize vendors with pre-validated hardware configurations.
- Perfusion Technology Maturation:Continuous bioprocessing configurations enable intensified titers for contract development organizations. Fed-batch dominance erodes as perfusion captures fastest-growing segment status.
Market Restraints
- Single-Use Material Extractables Testing:Regional divergence in polymer validation protocols fragments supplier compliance costs. EMA and FDA maintain non-harmonized testing matrices for film-grade resins.
- Stainless Steel Entrenchment:Vaccine development workflows retain steam-in-place sterilization requirements. Legacy capital investments in fixed equipment limit conversion rates.
- Sensor Integration Complexity:Advanced single-use sensor modules for dissolved oxygen and pH monitoring carry premium pricing. Smaller biotechnology firms face capital allocation constraints.
Strategic Opportunities
- Chinese Biologics Manufacturing Clusters:NMPA regulatory harmonization efforts accelerate domestic bioreactor procurement. Local contract manufacturing organizations expand pilot-scale capacity.
- Modular Facility Design:Pre-fabricated cleanroom architectures enable rapid deployment of contained bioprocessing suites. ISO 14644 classifications integrate with portable bioreactor skids.
- Digital Twin Integration:Process simulation software converges with physical bioreactor hardware. Predictive modeling reduces scale-up failure rates for novel modalities.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Specialized expertise in perfusion operation and metabolite control remains concentrated. Academic training pipelines lag industry hiring velocity.
- Legacy System Interoperability:Data historians and distributed control systems from incumbent vendors resist open-architecture integration. Middleware development consumes implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Scale Bioreactors Market |
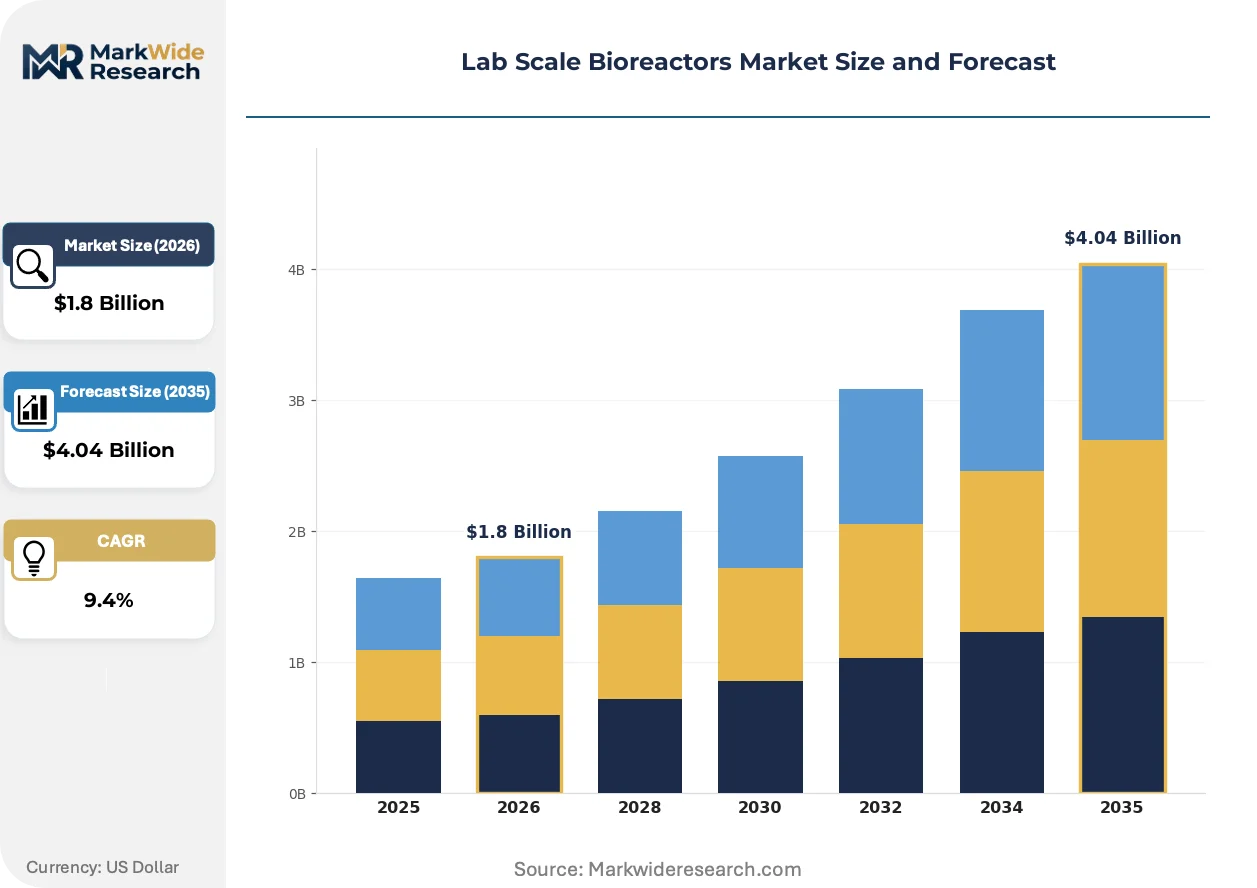
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Glass, Single-Use, Continuous Technology: Batch, Fed-Batch, Perfusion, Stirred-Tank End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Academic Labs Application: Cell Culture, Protein Production, Vaccine Development, Alcohol Fermentation |
| Companies Covered | Merck KGaA, INFORS HT, Sartorius AG, Pall Corporation, Applikon Biotechnology, Thermo Fisher Scientific, Danaher Corporation, Bioengineering AG, Eppendorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Scale Bioreactors Market Evolving Landscape
Process intensification and digitalization are compressing development cycles while regulatory convergence pressures reshape supplier qualification standards across pharmaceutical manufacturing networks.
Single-use bioreactor film technology is absorbing sensor embedding functions previously requiring external probe ports. Contract development organizations in North America and Europe are adopting these integrated formats at accelerated replacement cycles. The technology is absorbing capital expenditure from stainless steel validation infrastructure while enabling campaign-to-campaign turnover without cleaning validation.
EMA Good Manufacturing Practice standards for advanced therapy medicinal products are tightening equipment traceability requirements. Suppliers must now document material origins through polymer supply chains. European cell therapy developers are responding by consolidating vendor relationships with integrated life science platforms that control film resin sourcing.
Equipment-as-a-service contracts are displacing traditional capital purchase models among mid-cap biotechnology firms. Leasing structures bundle hardware, consumables, and field service into per-run economics. This shift concentrates most visibly in the United States where venture-backed developers prioritize operational expenditure treatment for financial reporting.
Lab Scale Bioreactors Market Segmentation
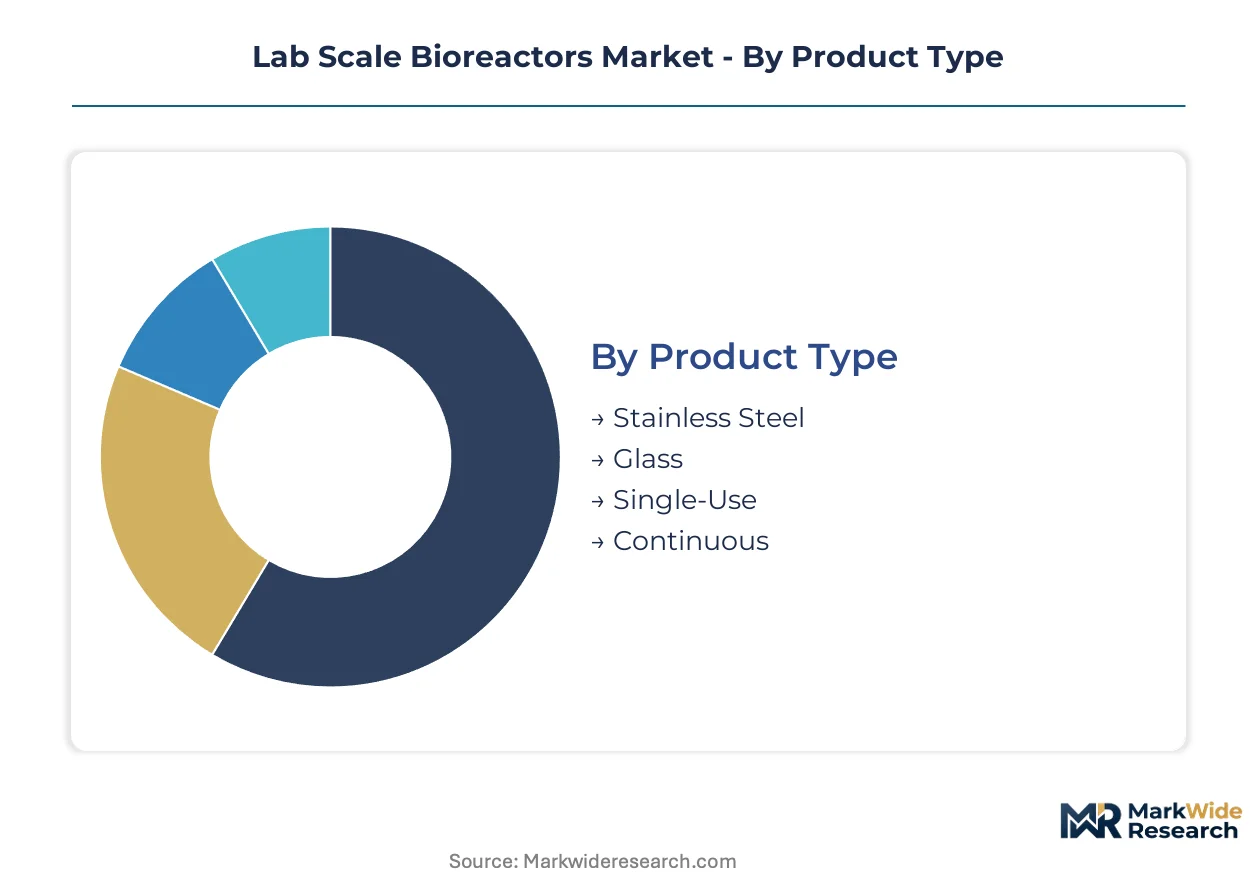
Segmentation in lab scale bioreactors reveals distinct capital deployment patterns across vessel technologies and operational modes. Procurement decisions hinge on sterilization protocols, campaign flexibility requirements, and regulatory qualification burdens that vary sharply by end-use environment.
Product Type:
Capital intensity peaks with stainless steel systems requiring extensive infrastructure for steam-in-place sterilization, while single-use formats shift expenditure toward consumable film supply chains.
- Stainless Steel:These vessels incorporate electropolished 316L stainless steel surfaces with ASME BPE compliant welds for repeated steam-in-place cycles. Pharmaceutical companies in Germany and the United States deploy these for vaccine seed train operations where thermal sterilization validation is mandatory. Legacy installed base and regulatory familiarity sustain demand despite longer qualification timelines.
- Single-Use:Multi-layer polymer film bags with embedded ports eliminate cleaning validation between campaigns. Contract development organizations in the United States and China are displacing fixed equipment with these formats to compress batch turnaround and reduce cross-contamination risk in multi-product facilities.
- Glass:Borosilicate vessels with magnetic drive impellers serve academic labs requiring visual process monitoring. Research institutions in Germany favor these for teaching applications and early-stage cell line development where transparency aids student training.
- Continuous:Integrated perfusion-ready hardware with cell retention devices enables steady-state operation. Biotech firms in China are piloting these configurations for intensified monoclonal antibody production prior to manufacturing scale-up.
Most installed capacity flows through stainless steel systems. Expansion is steepest in single-use formats.
Technology:
Operational complexity and metabolite control sophistication determine technology selection, with fed-batch dominating current workflows while perfusion gains traction among organizations seeking manufacturing intensification.
- Perfusion:Continuous media exchange with cell retention via alternating tangential flow or acoustic separators maintains high cell densities over extended durations. Contract development organizations in the United States are adopting these systems to achieve gram-per-liter titers that improve project economics for client molecules.
- Fed-Batch:Intermittent nutrient supplementation without cell removal remains the default for process characterization studies. Academic labs in China rely on these straightforward protocols for publications requiring reproducible baseline data across multiple research groups.
- Batch:Closed-system cultivation without mid-run intervention suits early-phase screening where simplicity outweighs optimization. Research institutions in Germany employ these for high-throughput clone selection prior to scale-up commitment.
- Stirred-Tank:Mechanical agitation with Rushton or pitched-blade impellers provides scalable mixing characteristics. Pharmaceutical companies standardize on these geometries to ensure kinematic similarity from bench to production scale.
Stirred-tank configurations anchor the installed base. Perfusion is climbing the fastest as continuous processing matures.
End User:
Procurement scale and qualification rigor diverge sharply between regulated manufacturers and research environments, with pharmaceutical companies driving premium system specifications.
- Pharmaceutical Companies:These organizations demand 21 CFR Part 11 compliant data historians and pre-validated hardware configurations for FDA submission support. Facilities in the United States prioritize vendors with established field service networks to minimize downtime during critical campaign windows.
- Biotech Firms:Venture-backed developers favor equipment-as-a-service contracts that convert capital expenditure to operational expenditure. Firms in China are leveraging NMPA regulatory harmonization to deploy identical hardware for domestic and export-bound process development.
- Research Institutions:National laboratories and government research centers balance capability against budget constraints. German Helmholtz Association centers coordinate bulk purchasing to standardize training and maintenance protocols across distributed sites.
- Academic Labs:University departments prioritize entry-level systems with modular upgrade paths for graduate research programs. Chinese Ministry of Education funding initiatives are expanding bioreactor access at tier-one universities to support biotechnology curriculum expansion.
Pharmaceutical companies command the largest unit volumes. Biotech firms are gaining share fastest through service-based procurement models.
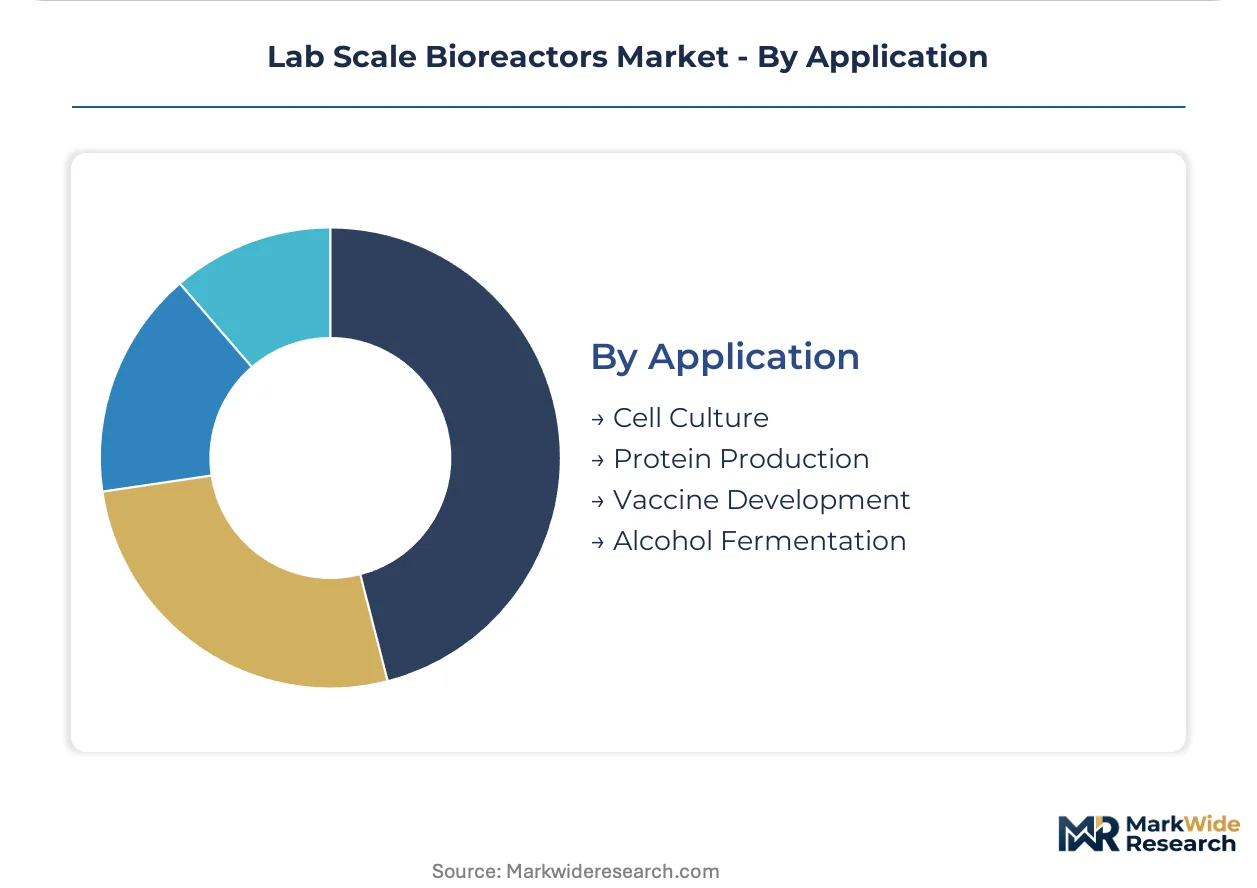
Application:
Biological product class determines sterility requirements, process duration, and analytical burden, with cell and gene therapy applications imposing the most stringent control specifications.
- Cell Culture:Mammalian and insect cell propagation for recombinant protein production requires precise dissolved oxygen and pH control. Developers in the United States are scaling these workflows for viral vector manufacturing to supply cell therapy clinical trials.
- Vaccine Development:Viral seed expansion and antigen production demand absolute containment for biosafety level 2 and 3 organisms. Institutes in Germany maintain dedicated stainless steel suites for influenza and pandemic preparedness manufacturing.
- Protein Production:Microbial and mammalian expression systems for therapeutic antibodies and enzymes dominate industrial demand. Chinese contract manufacturing organizations are expanding perfusion-based protein production to capture outsourced biologics manufacturing.
- Alcohol Fermentation:Yeast cultivation for beverage and industrial ethanol applications operates with reduced sterility requirements. Research institutions in Germany study these systems for metabolic engineering education and biofuel pathway development.
Cell culture applications absorb the majority of precision-controlled system placements. Vaccine development is expanding most quickly in response to pandemic preparedness investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping bioreactor procurement as contract development organizations migrate process development to jurisdictions with streamlined equipment qualification pathways. Cost-of-compliance gaps between FDA and NMPA filing requirements are accelerating facility investments in Asia-Pacific manufacturing clusters.
United States
Venture-backed cell therapy developers in Greater Boston and South San Francisco are scaling viral vector production capacity. FDA process validation guidelines under 21 CFR Part 11 mandate pre-qualified hardware configurations for IND-enabling studies. The Research Triangle Park corridor in North Carolina anchors contract manufacturing expansion for perfusion-based monoclonal antibody process development.
Germany
Helmholtz Association research centers coordinate bulk purchasing of glass vessel systems for academic training programs. EMA Good Manufacturing Practice standards for advanced therapy medicinal products tighten material traceability through polymer supply chains. The Munich biotech cluster concentrates perfusion technology piloting for European biologics manufacturers seeking intensified titers.
China
NMPA regulatory harmonization efforts enable domestic contract manufacturing organizations to deploy identical hardware for export-bound and domestic process development. The Yangtze River Delta biologics corridor in Shanghai and Suzhou expands pilot-scale single-use capacity. Local universities under Ministry of Education funding initiatives are standardizing bioreactor training curricula to address bioprocess engineering talent scarcity.
Switzerland
Swissmedic oversight of gene therapy manufacturing drives demand for contained bioprocessing suites with ISO 14644 cleanroom integration. The Basel pharmaceutical cluster maintains dedicated stainless steel infrastructure for pandemic vaccine seed train operations. Equipment-as-a-service contracts are penetrating mid-cap biotechnology firms prioritizing operational expenditure treatment.
United Kingdom
Cell and gene therapy catapult centers in London and Stevenage anchor public-private consortia for upstream process development. MHRA alignment with EMA post-Brexit maintains equipment qualification continuity for cross-border clinical supply. The Oxford-Cambridge arc concentrates academic spinouts transitioning from glass vessel screening to single-use scale-up.
Lab Scale Bioreactors Market Competitive Landscape
Portfolio diversification dominates the current landscape as integrated life science platforms absorb specialized bioreactor manufacturers to secure film resin supply chains. The vendor base stratifies across three tiers: diversified conglomerates with field service networks, mid-cap specialists with embedded sensor technology, and regional fabricators serving academic procurement. Strategic archetypes include platform integrators controlling consumable supply chains, technology licensors monetizing perfusion control algorithms, and service bundlers converting capital expenditure to per-run economics. M&A activity and capacity expansion in Chinese manufacturing clusters represent the dominant competitive vectors.
Among diversified conglomerates, Merck KGaA, Danaher Corporation, and Thermo Fisher Scientific occupy positions as platform integrators with extensive life science portfolios. Merck KGaA exemplifies the European archetype anchoring supply relationships across biotech clusters through integrated reagent and hardware bundling. Danaher Corporation represents the acquisition-driven consolidation pattern absorbing specialized vendors into interoperable workflows. Thermo Fisher Scientific anchors North American distribution density through field service infrastructure. These three entities collectively illustrate how scale-driven procurement preferences concentrate vendor selection among developers seeking single-source accountability for campaign turnaround.
| Leading Market Players |
|---|
| Merck KGaA |
| INFORS HT |
| Sartorius AG |
| Pall Corporation |
| Applikon Biotechnology |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Bioengineering AG |
| Eppendorf AG |
| Others |
Value Network & Pricing Analysis
Contract development organizations concentrate procurement authority for lab scale bioreactors, forcing suppliers toward equipment-as-a-service contracts that convert capital expenditure into per-run operational economics. This buyer archetype dominance compresses upfront pricing power while extending vendor revenue capture across consumable film supply chains and field service bundling.
Pricing Analysis
Direct-to-biotech-firm discounts bypass traditional distribution markups for high-volume perfusion system deployments. Three-tier pricing structure across premium sensor-integrated, standard configurable, and economy teaching-grade levels differentiates based on FDA pre-validation status and embedded dissolved oxygen probe sophistication. Cost compression in standard-tier stainless steel configurations intensifies as Chinese fabricators expand regional field service networks. Academic labs exhibit highest price sensitivity due to fixed grant funding cycles, while pharmaceutical companies prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China maintain hub-and-spoke patterns for single-use film bag replenishment. Multi-layer polymer resin supply draws from petrochemical complexes in Germany and the United States, while precision sensor modules source from Japanese and South Korean electronics manufacturers. Single-source vulnerability in platinum-cured silicone tubing for pharmaceutical-grade applications constrains campaign flexibility during supply disruptions. Distribution runs through integrated life science platforms that bundle hardware, consumables, and qualification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lab scale bioreactors function as a regulatory compounder where FDA process validation guidelines under 21 CFR Part 11 harden equipment qualification requirements into structural demand for pre-validated hardware configurations.
For Market Incumbents: Anchor field service network density in United States biotech clusters to defend against emerging Chinese suppliers expanding NMPA-aligned qualification support. Deepen backward integration into film resin supply chains to control material traceability documentation demanded by EMA Good Manufacturing Practice standards for advanced therapy medicinal products. Consolidate sensor embedding technology through captive development of single-use dissolved oxygen and pH modules. For New Entrants and Emerging Players: Enter via equipment-as-a-service contract structures targeting mid-cap biotechnology firms in Switzerland and the United Kingdom seeking operational expenditure treatment. White-space concentration exists in Chinese academic labs receiving Ministry of Education bioreactor curriculum expansion funding. Pursue modular cleanroom-integrated skid configurations for rapid deployment in pre-fabricated contained bioprocessing suites. For Investors and Strategic Acquirers: Integrated life science platforms are the most active acquirer in this space, absorbing specialized bioreactor manufacturers to secure consumable supply chain control. Long-term viability hinges on positioning against continuous bioprocessing intensification and digital twin convergence. Target acquisition archetype: mid-cap specialists with embedded perfusion control algorithms and established FDA master file documentation. Monitor NMPA regulatory harmonization progress as inflection signal for Chinese manufacturing cluster investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Technology Licensing | Contract development organizations in the United States license cell retention algorithms to intensify client titers. |
| Single-Use Film Backward Integration | Suppliers secure polymer resin sourcing to satisfy EMA material traceability requirements for European cell therapy developers. |
| Equipment-as-a-Service Expansion | Mid-cap biotechnology firms convert capital expenditure to operational expenditure through bundled per-run contracts. |
| Digital Twin Platform Integration | Process simulation software converges with physical bioreactor hardware to reduce scale-up failure rates. |
| Chinese Manufacturing Cluster Buildout | NMPA regulatory harmonization enables domestic contract manufacturing organizations to serve export-bound process development. |
Research Methodology
Bottom-up biopharmaceutical process development modeling reconciled against top-down bioreactor hardware supply tracking forms the analytical core. Primary interviews with bioprocess engineering directors, regulatory affairs leads, contract manufacturing organization procurement managers, and academic lab principal investigators combined with secondary validation against FDA 510(k) filings, EMA advanced therapy medicinal product submissions, NMPA registration databases, and ISO 14644 cleanroom certification records. Triangulation across these sources yields installed base estimates and replacement cycle projections.
Input-output matrices map vessel technology adoption against end-use application intensity across the projection horizon. Segmentation dimensions include product type, operational technology, end-user category, and regional regulatory cluster. CAGRs derive from regression analysis of historical placement data against cell and gene therapy clinical trial expansion trajectories. Forecast inputs incorporate perfusion technology maturation curves and single-use film supply chain capacity expansion timelines.
The model holds under sustained FDA and EMA regulatory convergence; deviation in NMPA harmonization velocity or polymer extractables testing standard fragmentation would shift regional demand distribution. Forecasts reflect documented assumptions regarding cell therapy commercialization rates and continuous bioprocessing adoption thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Laboratory Shakers Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Genetic Analyzer Systems Market