
 North America Cargo Handling Equipment Market | 2026-2036
North America Cargo Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cargo Handling Equipment Market Analytics
Multi-source procurement for electric drivetrain components is restructuring supply relationships across the North America cargo handling equipment sector. Hyster-Yale Materials Handling anchors its position through in-house production of lithium-ion battery packs for its lift truck portfolio. Konecranes leverages Finnish engineering heritage to dominate port crane installations along the U.S. Gulf Coast. Clark Material Handling Company competes on manufacturing scale from its Kentucky production base, sustaining cost advantages in the light-duty forklift segment.
North America cargo handling equipment encompasses powered industrial trucks, overhead cranes, and continuous conveying systems engineered to lift, transport, and position unit loads ranging from 2,000 to 120,000 pounds within commercial and industrial facilities. Electric drives now displace internal combustion engines in indoor warehousing applications, driven by zero-emission mandates and total cost of ownership reductions from eliminated fueling infrastructure. Forklifts occupy the largest revenue pool across product types, though automation technology represents the fastest-expanding margin segment as warehouse operators deploy autonomous mobile robots for horizontal transport. Heavy-duty capacity equipment serving steel and automotive manufacturing commands premium pricing due to specialized engineering requirements and limited qualified suppliers.
EPA Tier 4 Final emissions standards and OSHA powered industrial truck operator certification requirements shape product design and market access across the United States. Health Canada and provincial regulators in Ontario and Quebec enforce parallel equipment safety standards that manufacturers must satisfy for cross-border sales. Stakeholders must monitor state-level zero-emission equipment mandates, as California's Advanced Clean Trucks regulation creates precedent-setting procurement requirements that other jurisdictions may adopt.
Market Dynamics
Electrification mandates from EPA Tier 4 Final and state-level zero-emission rules are forcing fleet operators to retire diesel-powered forklifts and cranes ahead of normal replacement cycles, compressing capital deployment timelines across warehousing and intermodal terminals.
Growth Catalysts
- E-commerce fulfillment expansion:Parcel volume surges through Ohio, Michigan, and Illinois distribution hubs are sustaining equipment procurement cycles for automated guided vehicles and high-capacity forklifts.
- EPA emissions compliance:Off-road diesel equipment standards are accelerating electric drivetrain retrofits in California, where the Advanced Clean Trucks regulation creates precedent-setting procurement requirements.
- Lithium-ion battery maturation:Energy density improvements and thermal management advances are extending runtime for electric forklifts beyond single-shift operations, eliminating range anxiety in multi-shift warehousing.
Market Restraints
- Copper and rare earth input volatility:Electric motor and battery pack production faces raw material price swings that compress manufacturer margins and delay customer quotations.
- Midwest supplier concentration:Heavy-duty crane engineering capability clusters around Finnish and German engineering subsidiaries, creating import dependency for port infrastructure projects.
- ICE residual value collapse:Secondary market prices for internal combustion forklifts are deteriorating as resale buyers anticipate compliance retrofit costs, stranding capital for fleet operators.
Strategic Opportunities
- Mexico manufacturing corridor penetration:Nearshoring of automotive and appliance production to Nuevo León and Guanajuato is generating greenfield warehouse demand for electric material handling fleets.
- Battery-as-a-service models:Decoupled energy subscriptions allow mid-size 3PL operators to adopt electric fleets without absorbing lithium-ion capital risk or residual value exposure.
- OSHA training standard elevation:Enhanced operator certification requirements for autonomous systems create aftermarket education revenue streams and equipment vendor lock-in.
Industry Challenges
- Autonomous integration complexity:Warehouse management system interoperability with legacy WMS platforms requires custom middleware development that extends deployment timelines.
- High-voltage technician scarcity:Electric forklift maintenance demands certified battery technicians that vocational programs have not yet scaled to match fleet electrification velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cargo Handling Equipment Market |
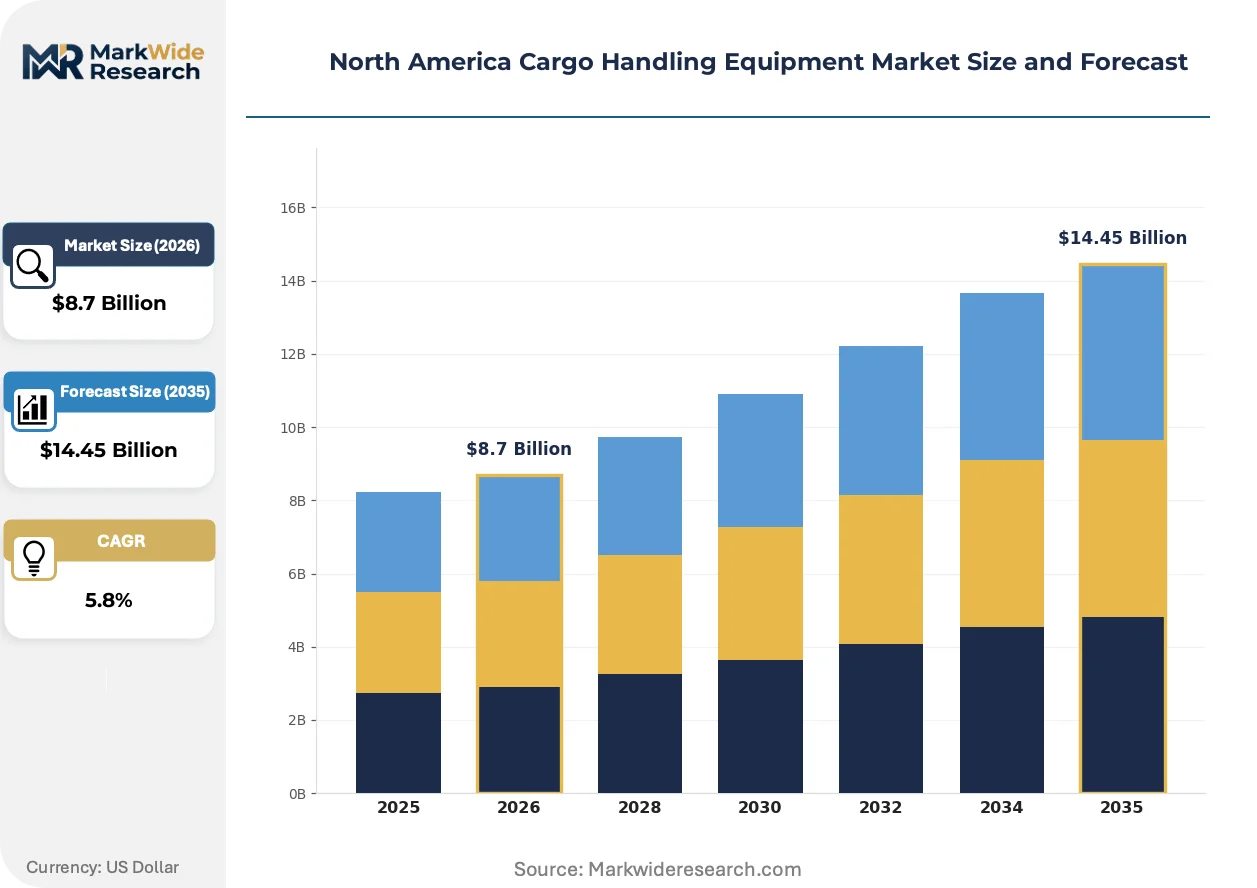
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Cranes, Conveyors, Pallet Jacks Technology: Automation, IoT Integration, Electric Drives, Hydraulic Systems End User: Logistics Providers, Warehouses, Manufacturing Plants, Retail Stores Capacity: Light-duty, Medium-duty, Heavy-duty, Specialty Equipment |
| Companies Covered | Crown Equipment Corporation, Hyster-Yale Materials Handling, Inc., Clark Material Handling Company, Hoist Liftruck, Tug Technologies, Emerson Electric, Konecranes, Cargotec, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cargo Handling Equipment Market Evolving Landscape
Automation architectures are migrating from fixed conveyor networks to flexible mobile robot fleets that adapt to seasonal volume swings without infrastructure modification.
Lithium-ion phosphate battery packs are overtaking lead-acid and nickel-cadmium chemistries in indoor warehousing applications. Third-party logistics operators in California and Texas are standardizing on fast-charge lithium configurations that eliminate battery swap stations. This chemistry transition is overtaking the traditional forklift dealer service model by reducing maintenance touchpoints and extending asset life cycles.
EPA Tier 4 Final compliance deadlines are compressing diesel equipment replacement windows across the United States. Fleet operators face accelerated capital deployment to avoid non-compliance penalties in regulated air basins. The Great Lakes industrial corridor is responding with lease-to-own structures that transfer residual value risk to equipment financiers.
Outcome-based fleet management contracts are displacing traditional equipment ownership in multi-site distribution networks. Retail and grocery chains are unbundling maintenance, energy, and uptime guarantees into per-pallet-handled pricing. This procurement evolution is most visible in Ontario and Quebec, where cross-border operators seek harmonized service level agreements across Canadian and US facilities.
North America Cargo Handling Equipment Market Segmentation
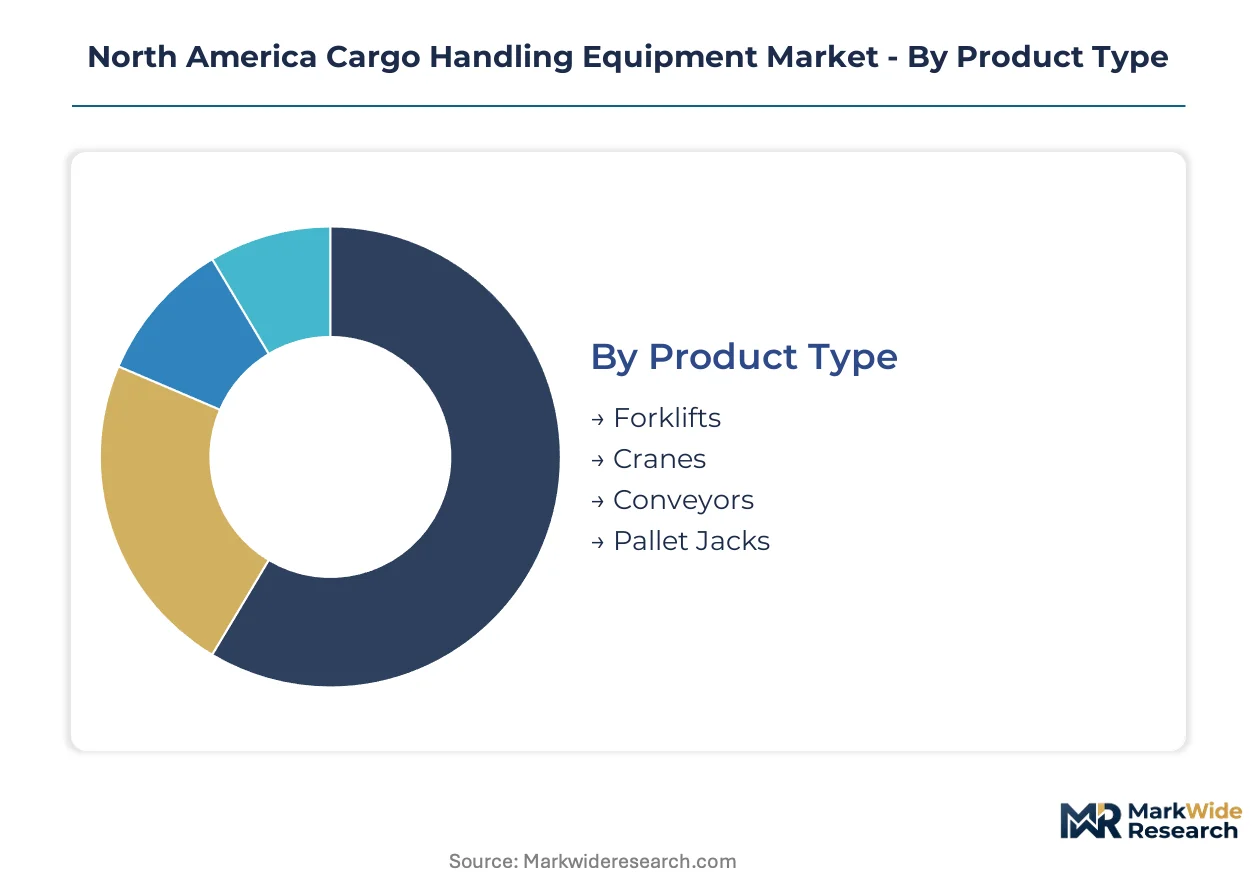
Equipment specification varies sharply across buyer profiles in the North America cargo handling equipment market. Procurement priorities diverge between e-commerce fulfillment operators seeking automation density and steel manufacturers demanding heavy-load precision.
Product Type:
Fleet composition reflects facility throughput requirements and load characteristics rather than capital availability alone.
- Forklifts:Counterbalance and reach truck configurations dominate indoor warehousing with lifting capacities from 3,000 to 12,000 pounds. Ohio, Michigan, and Illinois distribution hubs are standardizing on lithium-ion electric models to satisfy EPA Tier 4 Final compliance deadlines and eliminate battery swap infrastructure.
- Cranes:Overhead bridge cranes and gantry systems engineered for 10-ton to 100-ton loads serve automotive stamping plants and steel service centers. The U.S. Gulf Coast port corridor sustains procurement of ship-to-shore container cranes with specialized spreader mechanisms for intermodal transfer operations.
- Conveyors:Belt and roller systems for sortation and accumulation in parcel hubs.
- Pallet Jacks:Manual and electric walk-behind units for last-meter positioning in retail backrooms and food service distribution.
Forklifts lead volumes today; automation-ready crane systems are gaining share fastest in greenfield manufacturing investments.
Technology:
Technology selection separates compliance-driven retrofits from competitive automation investments.
- Automation:Autonomous mobile robots and automated guided vehicles navigate warehouse floors without fixed infrastructure using LiDAR and vision guidance. California fulfillment centers are deploying these systems to manage seasonal volume spikes without permanent conveyor installation.
- IoT Integration:Fleet telematics platforms track utilization, battery state-of-charge, and maintenance intervals through cloud-connected sensors. Third-party logistics operators in Texas are mandating OEM-native IoT stacks to unify visibility across multi-site networks.
- Electric Drives:AC induction and permanent magnet motors replacing internal combustion in indoor applications.
- Hydraulic Systems:Precision lifting mechanisms retained for outdoor heavy-capacity applications where electrification remains technically constrained.
Electric drives anchor current procurement volumes; automation technology is climbing the fastest as labor costs rise in distribution corridors.
End User:
End-use concentration determines equipment specification complexity and service contract structure.
- Logistics Providers:Asset-light third-party operators prioritize fleet flexibility and uptime guarantees over ownership. These customers are adopting battery-as-a-service models to transfer lithium-ion residual value risk to equipment financiers.
- Warehouses:Dedicated distribution facilities for retail and grocery chains demand high-density storage solutions with narrow-aisle forklift configurations. The Great Lakes industrial corridor sustains procurement cycles for double-deep reach trucks and automated storage retrieval systems.
- Manufacturing Plants:Automotive and appliance production facilities in Nuevo León and Guanajuato, Mexico are generating demand for electric material handling fleets synchronized with assembly line takt times.
- Retail Stores:Big-box and grocery backroom operations requiring compact pallet jacks and low-lift order pickers for rapid restocking cycles.
Warehouses lead volumes today; logistics providers are expanding fastest as outsourcing penetrates e-commerce fulfillment.
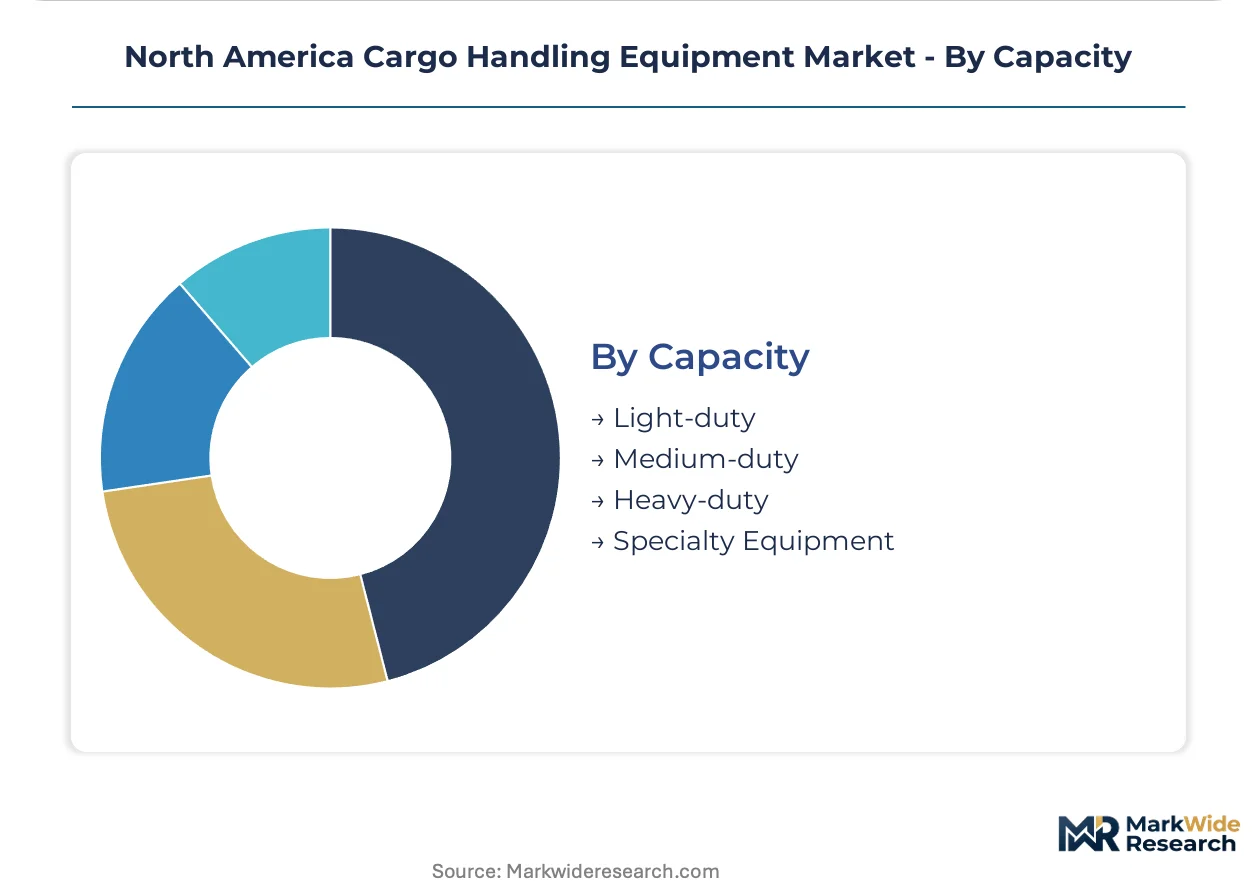
Capacity:
Load rating dictates engineering source and pricing tier more than any other specification.
- Heavy-duty:Equipment rated above 25,000 pounds for steel coil handling and automotive body stamping die transport. Limited qualified suppliers and specialized engineering requirements sustain premium pricing in this tier.
- Medium-duty:Forklifts and pallet trucks from 5,000 to 25,000 pounds serving general manufacturing and distribution. This segment captures standard warehouse fleet renewal cycles across the United States and Canada.
- Light-duty:Manual and electric pallet jacks below 5,000 pounds for retail and food service applications.
- Specialty Equipment:Explosion-proof lifts for chemical processing and refrigerated configurations for cold chain logistics.
Medium-duty equipment leads volumes today; heavy-duty systems are expanding most quickly with reshoring of metals and automotive production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cargo handling equipment procurement toward jurisdictions with favorable electrification incentives and lower compliance friction. Mexico's manufacturing corridor attracts fleet investment as EPA Tier 4 Final deadlines accelerate diesel retirement costs in the United States.
United States
E-commerce fulfillment centers in Ohio, Michigan, and Illinois drive automated guided vehicle deployment for parcel volume management. EPA Tier 4 Final emissions standards force electric drivetrain retrofits ahead of normal replacement cycles. The Great Lakes industrial corridor sustains intermodal freight transfer equipment procurement between rail and truck terminals.
Canada
Cross-border distribution networks in Ontario and Quebec seek harmonized service agreements for multi-site operations. Health Canada and provincial regulators enforce equipment safety standards parallel to OSHA requirements. Toronto and Montreal distribution hubs standardize on lithium-ion electric forklifts to eliminate battery swap infrastructure.
Mexico
Nearshoring of automotive and appliance production to Nuevo León and Guanajuato generates greenfield warehouse demand. The country's national industrial safety regulator enforces equipment certification requirements for cross-border supply chain integration. Mexico City Metro area distribution facilities adopt electric material handling fleets synchronized with assembly line operations.
North America Cargo Handling Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automation-ready configurations and battery-as-a-service models. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive component production, specialized crane engineering subsidiaries with Finnish and German heritage, and regional forklift fabricators competing on manufacturing scale. Dominant competitive moves include backward integration into lithium-ion battery pack production and strategic partnerships for autonomous system middleware development.
Among United States-based material handling specialists, Crown Equipment Corporation and Hyster-Yale Materials Handling occupy positions representing the integrated-manufacturer archetype with in-house energy storage capabilities. Clark Material Handling Company exemplifies the scale-driven regional fabricator competing from its Kentucky production base. Finnish engineering heritage anchors Konecranes within the heavy-lift port infrastructure segment along the U.S. Gulf Coast.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling, Inc. |
| Clark Material Handling Company |
| Hoist Liftruck |
| Tug Technologies |
| Emerson Electric |
| Konecranes |
| Cargotec |
| Terex Corporation |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility cascades through North American cargo handling equipment supply chains, compressing margins on electric forklift battery packs while amplifying pricing power for manufacturers with captive cell production. Copper and rare earth magnet cost swings force tiered pricing adjustments across heavy-duty crane motors and permanent magnet drive systems.
Pricing Analysis
Input-cost pass-through dominates pricing architecture, with lithium-ion battery pack costs flowing directly into equipment quotations on 30-60 day lag structures. Pricing stratifies across premium, standard, and economy tiers based on OSHA certification grade and after-sales service bundling. Pricing pressure stems from ICE residual value collapse as resale buyers anticipate compliance retrofit costs. Third-party logistics operators exhibit highest price sensitivity due to asset-light operating models, while steel manufacturers accept premium tiers for heavy-load precision engineering.
Supply Chain Analysis
OSHA and EPA certification requirements gate supplier qualification, limiting qualified crane engineering sources to Finnish and German heritage subsidiaries for port infrastructure projects. Component manufacturing concentrates in China for lithium-ion cells, South Korea for battery management systems, and Mexico for fabricated steel structures. Supply chains draw from copper cathodes, rare earth permanent magnets, and high-grade steel plate as critical inputs. Single-source vulnerability concentrates in Finnish-engineered port crane systems for Gulf Coast container terminals. Distribution runs through authorized dealer networks with captive service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
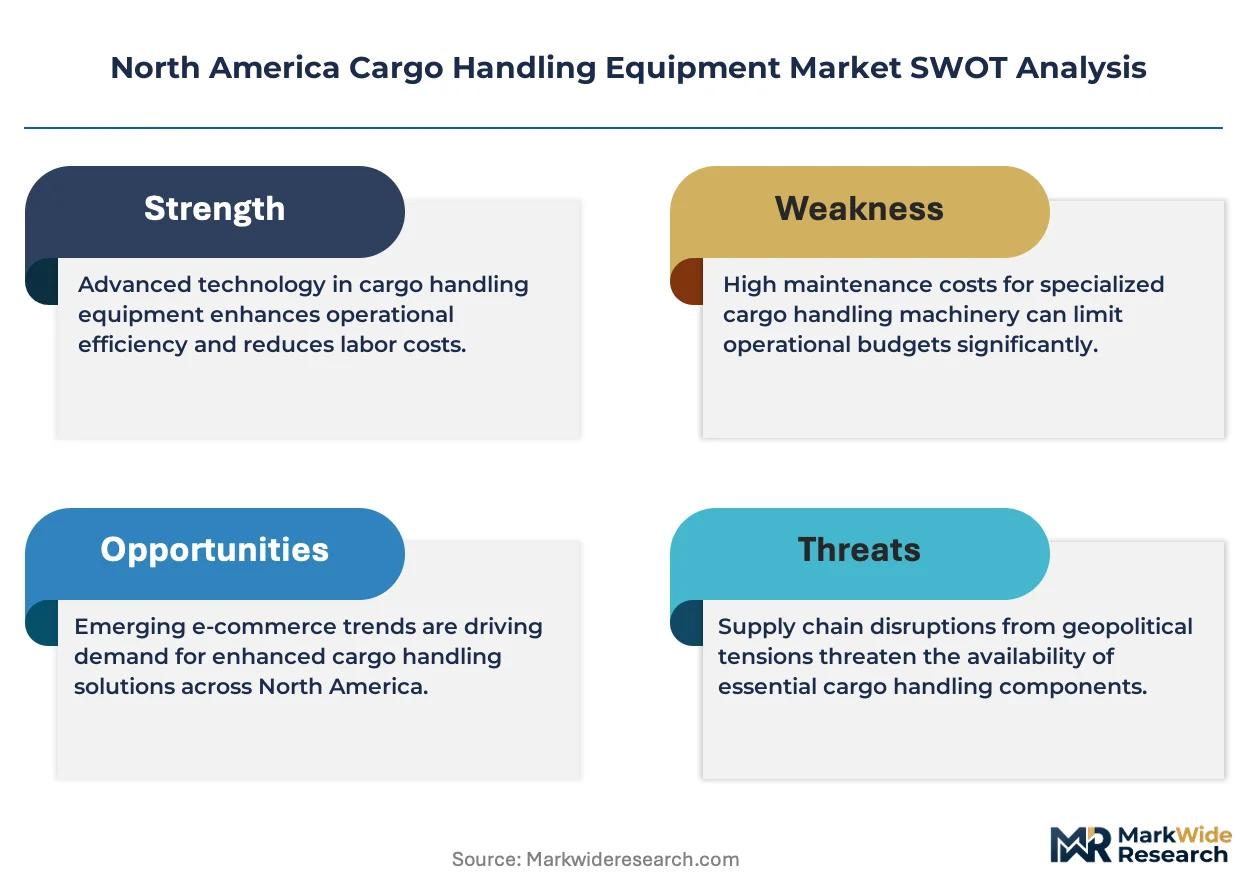
Margin expansion in this market rests on lithium-ion cost curves flattening and automation-ready equipment commanding premium positioning over standard electric models.
For Market Incumbents: Hedge against rare earth price volatility through long-term offtake agreements with magnet suppliers or backward integration into battery pack assembly. Incumbent manufacturers face emerging automation specialists threatening dealer service relationships; defend through captive technician certification programs aligned with OSHA elevated training standards. For New Entrants and Emerging Players: Enter via battery-as-a-service models targeting mid-size 3PL operators in Texas and California who seek electric fleet adoption without capital risk absorption. The most penetrable white space sits in autonomous mobile robot middleware for legacy WMS integration, where warehouse operators face deployment timeline extensions from custom development requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with automation-ready forklift fabricators possessing proprietary LiDAR guidance stacks and established OSHA training revenue streams. Long-term viability favors vendors with installed base telemetry data enabling predictive maintenance contracts. The signal to watch is California Advanced Clean Trucks regulation adoption velocity across additional state jurisdictions as procurement mandate expansion indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Production | Hyster-Yale's in-house lithium-ion manufacturing insulates margin from commodity swings and secures EPA compliance timelines. |
| Autonomous System Middleware Development | Strategic partnerships for WMS interoperability reduce deployment friction and extend vendor lock-in through software dependency. |
| Battery-as-a-Service Model Launch | Decoupled energy subscriptions transfer residual value risk and accelerate mid-market 3PL electric fleet adoption. |
| OSHA Certification Program Expansion | Enhanced operator training requirements for autonomous systems generate recurring aftermarket revenue and deepen customer switching costs. |
| Mexico Manufacturing Corridor Penetration | Greenfield facility establishment near Nuevo León automotive plants captures nearshoring-driven warehouse equipment procurement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet maintenance directors, plant engineers at automotive stamping facilities, OEM procurement teams, and aftermarket service heads with secondary validation against EPA enforcement databases, OSHA certification records, and customs import data for crane components. Bottom-up equipment shipment tallies triangulated against top-down industrial construction spending figures.
Segment-weighting approaches distributed value estimates across product type, technology tier, end-use concentration, and capacity rating dimensions throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles overlaid with electrification mandate acceleration curves and e-commerce fulfillment center construction pipelines.
Inputs from equipment OEMs and third-party logistics operators were available through the study window; gaps in autonomous system deployment run-rates introduce uncertainty bands around automation technology share projections. Forecasts reflect assumptions regarding EPA enforcement consistency and lithium-ion cost reduction trajectories. A model refresh is warranted upon material change in California regulatory adoption patterns or rare earth supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Germany Contract Logistics Market