
 Water Hauling Services Market | 2026-2036
Water Hauling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Water Hauling Services Market Outlook
Texas is narrowing the gap between freshwater scarcity and industrial demand through expanded fleet deployment across the Permian and Eagle Ford shale corridors. Gibson Energy leverages its midstream logistics backbone to sustain high-volume water transfer operations for upstream clients. Veolia dominates integrated water services, extending treatment and hauling capabilities across multiple basins. Big Rock Water Hauling Services anchors regional coverage in Alberta's oil sands, competing on cold-weather operational reliability.
Water hauling services encompass the bulk transport of non-potable and produced water via specialized vacuum trucks and tanker trailers, typically handling volumes from 500 to 5,000 gallons per load with pressure-rated vessels designed for corrosive brine and frac-flowback composition. The primary purpose centers on supporting hydraulic fracturing operations, municipal emergency supply, and agricultural irrigation where pipeline infrastructure remains absent or insufficient. Residential Delivery represents a mature segment with stable margins tied to rural household dependency on cistern refills, while Agricultural Use emerges as the fastest-growing category as drought-driven livestock and crop operations in the Great Plains expand contractual hauling arrangements. Emergency Services commands premium pricing during wildfire suppression and disaster response, though volume spikes remain unpredictable.
The EPA enforces Underground Injection Control permits that dictate produced water disposal pathways, directly shaping hauling distances and vendor selection criteria for oilfield operators. DOT hazardous materials regulations govern tanker specifications, driver certifications, and route planning across interstate corridors. State-level groundwater withdrawal permits issued by the Texas Commission on Environmental Quality further constrain supply access, forcing haulers to navigate fragmented allocation systems. Stakeholders must weigh fleet electrification timelines against the torque and range requirements of heavy-duty water transport before committing capital to next-generation equipment platforms.
Market Dynamics
Produced water volumes from Permian Basin shale operations now exceed freshwater demand for completions, forcing haulers to pivot from supply logistics toward brine disposal and recycling circuits. This inversion reconfigures fleet deployment, terminal infrastructure, and contract structures across the North American water hauling value chain.
Growth Catalysts
- EPA Underground Injection Control enforcement:Stricter UIC permit scrutiny in Texas and New Mexico lengthens disposal queue times, expanding captive hauling contracts for midstream water management.
- Hydraulic fracturing intensity:Extended lateral lengths in the Delaware Basin consume 15-50 million gallons per well, multiplying round-trip hauling requirements for frac crews operating 24-hour completion schedules.
- Drought-driven municipal emergency sourcing:Rural Texas municipalities now contract standby water hauling agreements as primary supply insurance, embedding haulers into public utility contingency planning.
Market Restraints
- Diesel price volatility:Fuel represents 35-40% of variable hauling costs, compressing margins when rack prices spike above regional baselines.
- Permitting fragmentation:Texas Commission on Environmental Quality groundwater withdrawal permits vary by aquifer and county, forcing haulers to maintain parallel compliance systems.
- Pipeline displacement threat:Permian operators including Pioneer Natural Resources and Diamondback Energy are constructing produced water gathering systems that eliminate 40-60 mile trucking legs.
Strategic Opportunities
- Alberta oil sands thermal operations:Steam-assisted gravity drainage facilities require continuous boiler feedwater logistics where pipeline frost heave limits fixed infrastructure.
- Electrification incentives:The US Inflation Reduction Act Section 45W credits offset battery-electric truck capital costs for fleets serving urban-fringe municipal contracts.
- Real-time logistics platforms:Integration of telematics with dispatch software enables dynamic load matching, reducing deadhead miles and asset idle time.
Industry Challenges
- Commercial Driver's License scarcity:The American Trucking Associations reports 80,000+ unfilled heavy-truck positions, forcing haulers to poach from oilfield competitors with signing bonuses.
- DOT hazmat certification timelines:Tank vehicle and hazardous materials endorsements require 4-6 week training periods, constraining fleet expansion velocity during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Hauling Services Market |
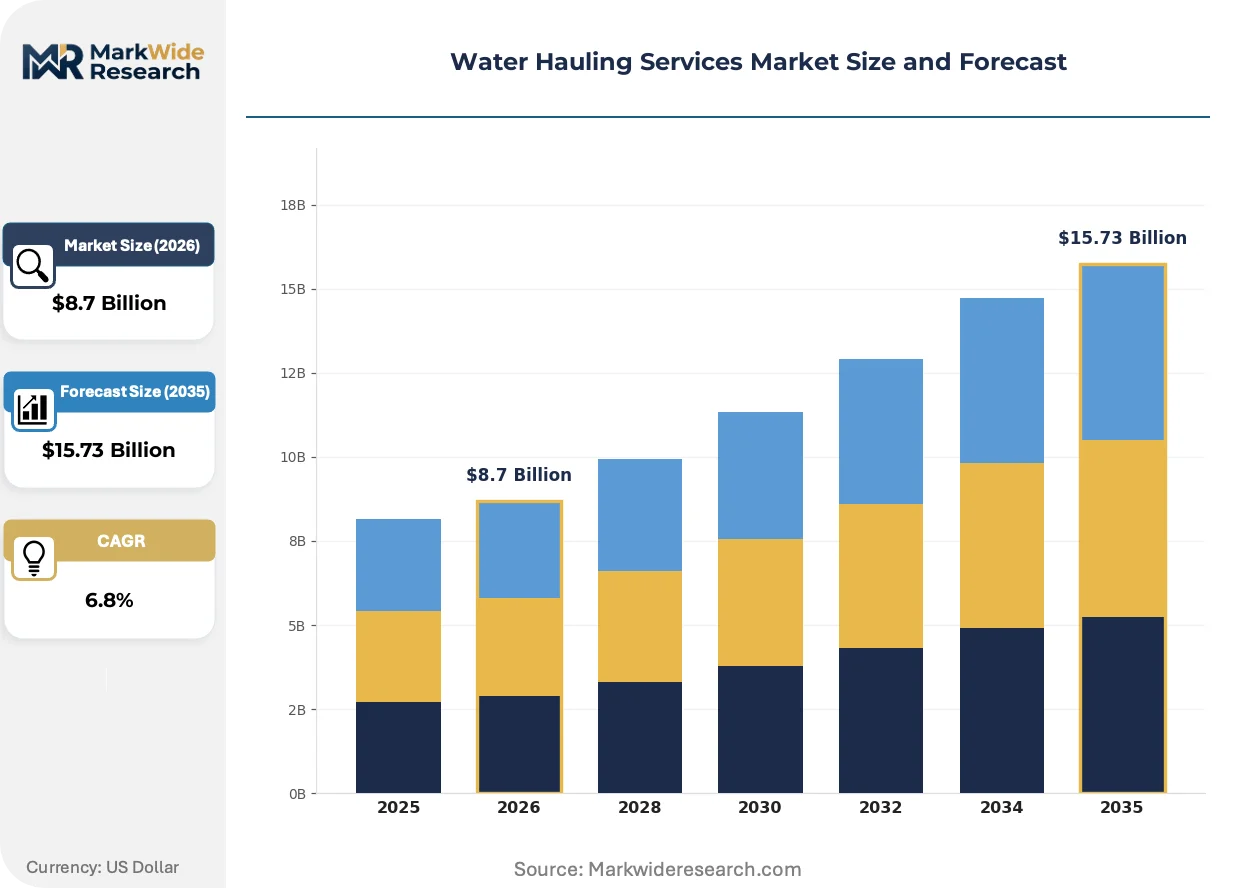
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Delivery, Construction Sites, Agricultural Use, Emergency Services End User: Homeowners, Contractors, Municipalities, Farms Capacity: 500 Gallons, 1000 Gallons, 3000 Gallons, 5000 Gallons Delivery Mode: Truck, Tanker, Portable Containers, On-site Storage |
| Companies Covered | Gibson Energy, Patrik’s Water Hauling, Fueloyal, HB Rentals, Big Rock Water Hauling Services, GEI Works, Veolia, Dalton Water, Zemba Bros, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Hauling Services Market Strategic Shifts
Digital freight matching and alternative powertrains are converging to compress hauling costs and emissions profiles simultaneously. This dual pressure is accelerating capital deployment toward connected fleet assets and energy transition pilot programs.
Automated dispatch algorithms leveraging GPS telemetry and well-completion schedules now optimize load sequencing in real time. Large Permian operators including Occidental Petroleum and ConocoPhillips have mandated API integration for all water logistics vendors, rendering obsolete manual phone-based dispatch coordination between field supervisors and trucking brokers.
EPA effluent limitation guidelines under the Clean Water Act are tightening produced water discharge standards for unconventional oil and gas extraction. The industrial consequence is a forced pivot toward closed-loop recycling systems that treat brine on-site rather than hauling to disposal wells, with Texas Railroad Commission jurisdiction seeing the most permit revision activity as operators pre-emptively consolidate hauling contracts with integrated treatment providers.
Long-term offtake agreements now displace spot-market water sourcing for multi-well pad development programs. E&P procurement teams in the Midland Basin have shifted toward 12-24 month minimum volume commitments that guarantee fleet availability, with penalties for underlift, replacing the historical month-to-month spot contracting that dominated 2015-2020 operations.
Water Hauling Services Market Segmentation
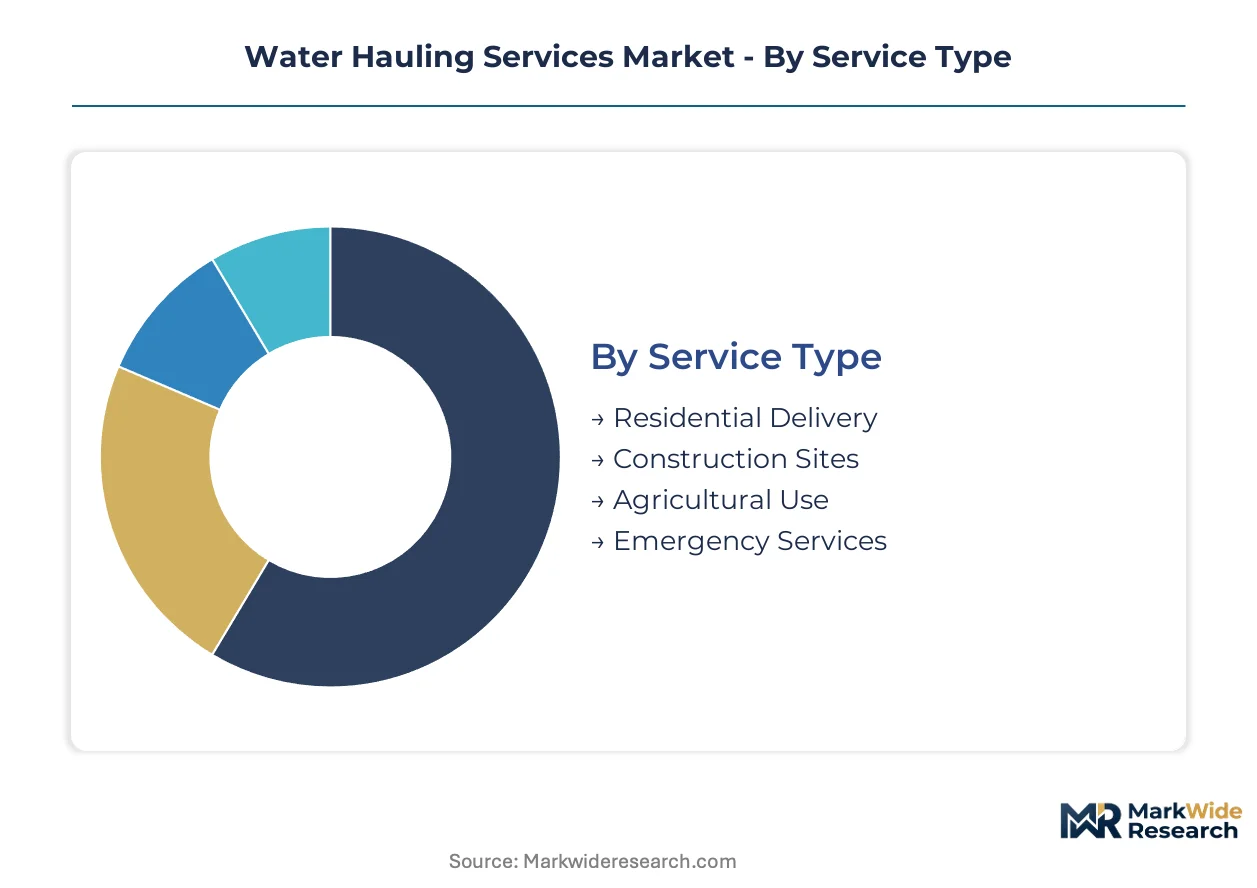
Water hauling service providers structure operations around four distinct dimensions that govern fleet configuration, pricing models, and contract terms. Each segmentation axis reveals divergent margin profiles and capital intensity requirements that shape competitive positioning across North American basins.
Service Type:
Application context dictates equipment specifications, with corrosive brine transport demanding pressure-rated vessels distinct from potable municipal delivery.
- Agricultural Use:Bulk transport for livestock watering and crop irrigation in drought-affected Great Plains counties. Texas Panhandle feedlots and Nebraska pivot-irrigation districts are expanding contractual hauling arrangements as groundwater pumping restrictions tighten.
- Emergency Services:Wildfire suppression tanker support and disaster response municipal backup. California Cal Fire contracts and Texas grid-failure contingency agreements command 40-60% rate premiums over standard commercial hauling.
- Residential Delivery:Cistern refill operations for rural households lacking municipal hookups. Stable recurring revenue tied to permanent rural population clusters.
- Construction Sites:Dust suppression and concrete batching water supply for infrastructure projects. Volume fluctuates with highway and commercial building permit cycles.
Emergency Services holds installed capacity. Agricultural Use is rotating up the share rankings.
End User:
Customer type segments reveal divergent procurement sophistication, with municipalities demanding multi-year service level agreements against spot-market farm contracting.
- Farms:Large-scale livestock operations and row-crop producers in water-stressed Kansas and Oklahoma counties. Drought-driven herd consolidation is concentrating demand among fewer, higher-volume accounts with 10,000+ gallon weekly requirements.
- Municipalities:Small-town water departments and rural utility districts sourcing emergency supply. Texas Commission on Environmental Quality standby contract mandates are embedding haulers into public utility contingency frameworks.
- Homeowners:Individual cistern-dependent rural residents. Fragmented demand with high customer acquisition costs relative to per-drop revenue.
- Contractors:Oilfield service companies and construction general contractors. Price-sensitive spot purchasing with limited loyalty or contract duration.
Municipalities hold installed capacity. Farms is climbing the fastest.
Capacity:
Volume tier selection balances route density against per-drop labor efficiency, with mid-range vessels dominating Permian Basin produced water logistics.
- 3000 Gallons:Standard configuration for multi-stop agricultural routes and small-pad oilfield completions. Delaware Basin frac crews favor this tier for 15-20 well pad programs where pipeline infrastructure remains incomplete.
- 5000 Gallons:Maximum single-drop efficiency for large-scale municipal contracts and centralized disposal well runs. Eagle Ford shale corridors deploy these units for 50+ mile hauls to UIC-permitted injection facilities.
- 500 Gallons:Restricted-access residential and remote construction site delivery. Maneuverability advantage offset by high driver-hour cost per gallon delivered.
- 1000 Gallons:Intermediate tier serving homeowner clusters and small-lot agricultural users. Limited differentiation from adjacent capacity classes.
3000 Gallons holds installed capacity. 5000 Gallons is gaining share fastest.
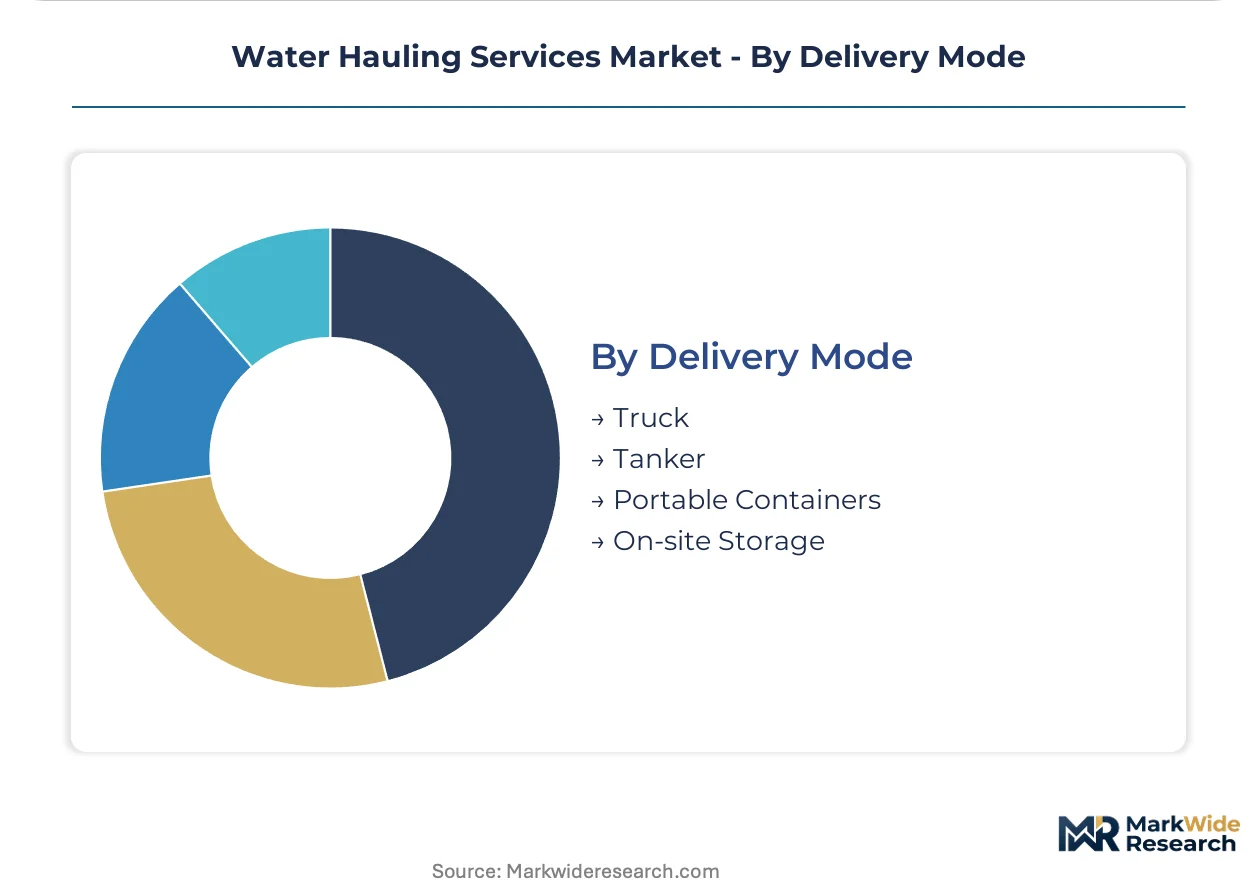
Delivery Mode:
Physical distribution method determines capital structure, with owned fleets requiring heavy asset deployment against brokered arrangements leveraging third-party capacity.
- Truck:Vacuum-equipped straight trucks with 80-150 barrel nominal capacity. Permian operators mandate API-integrated dispatch connectivity for real-time load tracking.
- Tanker:Semi-trailer configurations for 150-400 barrel long-haul disposal runs. DOT hazmat endorsement requirements constrain driver pool availability.
- Portable Containers:Modular totes and frac tanks for temporary on-site storage. Midland Basin multi-well pads deploy these for 72-hour completion water buffering.
- On-site Storage:Fixed tanks and impoundments with hauling limited to initial fill and periodic turnover. Reduces recurring transport intensity for continuous industrial processes.
Truck holds installed capacity. Tanker is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Underground Injection Control enforcement in the United States anchors regulatory pressure across the water hauling value chain. The Texas Commission on Environmental Quality and New Mexico Oil Conservation Division issue parallel groundwater withdrawal and disposal permits that shape vendor selection criteria. This regulatory triad concentrates operational complexity in the Permian Basin corridor.
United States
Permian Basin shale operators now generate produced water volumes exceeding freshwater demand for completions, forcing haulers to reconfigure fleet deployment toward brine disposal circuits. EPA effluent limitation guidelines under the Clean Water Act tighten discharge standards for unconventional extraction. Midland and Delaware Basin sub-regions see 15-50 million gallon per-well completion schedules that multiply round-trip hauling requirements for 24-hour frac crews.
Canada
Alberta oil sands thermal operations require continuous boiler feedwater logistics where pipeline frost heave limits fixed infrastructure deployment. Alberta Energy Regulator directives on steam-assisted gravity drainage water sourcing constrain withdrawal allocation systems. The Athabasca oil sands region anchors cold-weather operational reliability requirements for specialized vacuum truck fleets serving SAGD facilities.
Mexico
Burgos Basin shale development and offshore platform water logistics drive demand for tanker-based transport where pipeline infrastructure remains incomplete. Comisión Nacional del Agua groundwater concession permits fragment supply access across northern border states. Tamaulipas and Nuevo León shale corridors concentrate hauling contracts for international operators adapting Permian Basin logistics models.
Australia
Mining sector dust suppression and remote community water delivery sustain demand for long-haul tanker operations across the Pilbara and Queensland coal seams. National Water Commission allocation frameworks intersect with state-level environmental protection authority discharge rules. Western Australia's iron ore mining camps and Queensland's Bowen Basin coal operations embed haulers into 300+ kilometer transport legs with limited pipeline alternatives.
Water Hauling Services Market Competitive Environment
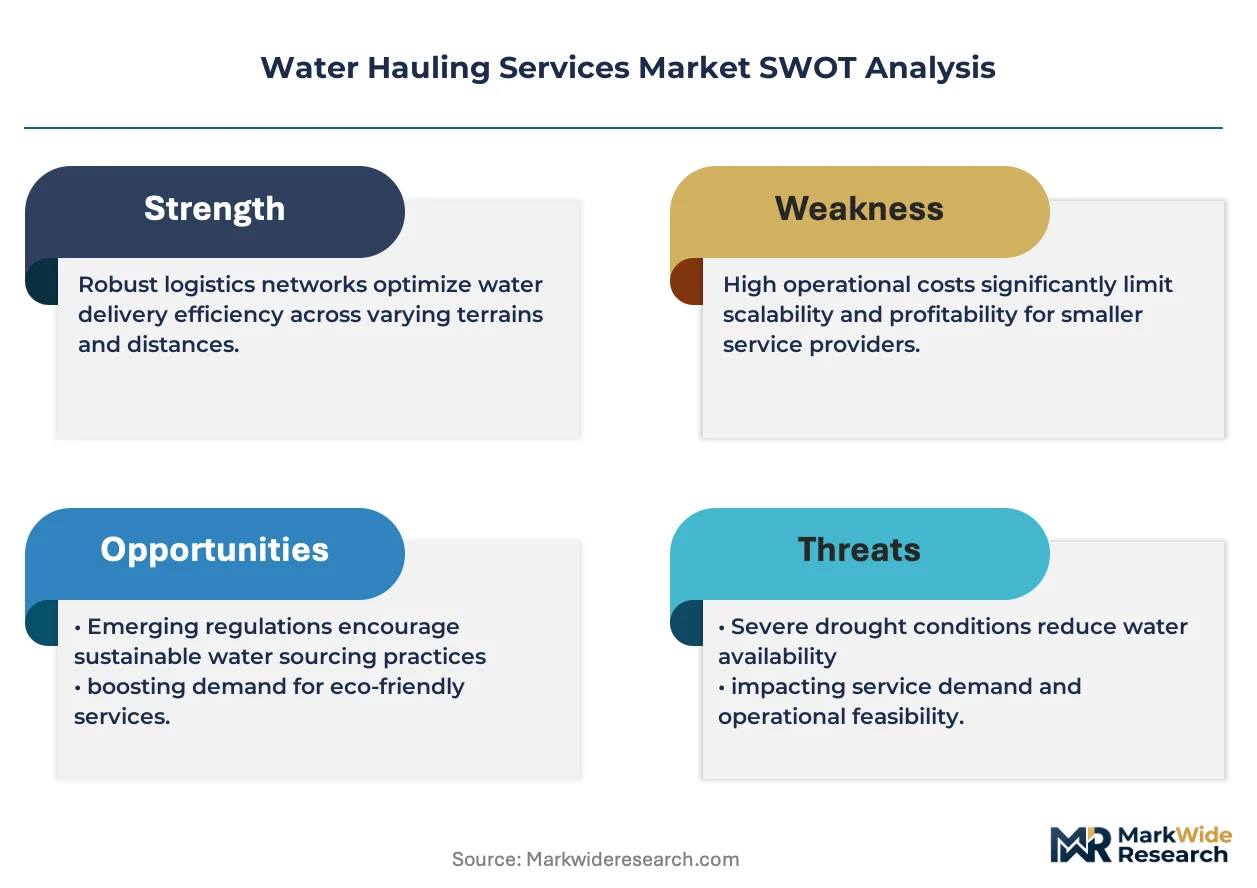
Capability concentration sits with integrated environmental services conglomerates; scale advantage sits with regional oilfield logistics specialists. The vendor base stratifies across three tiers: multinational water treatment and logistics platforms, basin-focused energy midstream operators, and single-region trucking specialists. Dominant competitive moves include backward integration into disposal well ownership and real-time dispatch platform deployment to compress deadhead mileage.
Within the multinational tier, Veolia exemplifies integrated service bundling across treatment and hauling capabilities. Gibson Energy anchors the energy midstream segment with logistics backbone deployment for upstream water transfer. Big Rock Water Hauling Services occupies a position in the regional specialist tier, competing on cold-weather operational reliability in Alberta's oil sands corridor.
| Leading Market Players |
|---|
| Gibson Energy |
| Patrik's Water Hauling |
| Fueloyal |
| HB Rentals |
| Big Rock Water Hauling Services |
| GEI Works |
| Veolia |
| Dalton Water |
| Zemba Bros |
| Others |
Value Chain & Pricing Dynamics
The Permian Basin disposal corridor anchors cost dynamics across the North American water hauling value chain, where concentration of UIC-permitted injection wells in Texas and New Mexico creates tiered pricing power for midstream operators while diesel volatility feeds downstream margin compression.
Pricing Analysis
Geographic price spreads of 40-60% separate Permian Basin produced water disposal runs from Great Plains agricultural delivery contracts, reflecting distance-to-well economics and permit scarcity. Contract-based long-term offtake agreements now dominate E&P procurement, replacing spot-market volatility with 12-24 month minimum volume commitments. Price differentiation rests on disposal well proximity and real-time dispatch integration, with API-connected vendors commanding premium positioning. Municipal buyers exhibit lowest price sensitivity due to emergency standby mandates, while oilfield contractors face acute cost compression during diesel rack spikes.
Supply Chain Analysis
Upstream feedstock for water hauling services draws from specialized tanker manufacturing concentrated in the United States, Canada, and Mexico, with pressure-rated vessel fabrication anchored in Texas and Alberta industrial corridors. Fleet operators depend on vacuum pump assemblies, DOT-certified tank materials, and telematics hardware from tier-1 automotive suppliers. Single-source vulnerability concentrates in hazmat-certified driver training networks, where CDL scarcity constrains expansion velocity. Distribution runs through owned fleet operations for integrated midstream operators, supplemented by brokered capacity during demand spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated E&P procurement teams and municipal utility districts, as multi-well pad development programs and TCEQ standby contract mandates embed haulers into long-term service frameworks.
For Market Incumbents: Pre-empt pipeline displacement threats by securing captive disposal well networks in the Midland and Delaware Basin corridors. Backward integration into UIC-permitted injection facilities locks in hauling volumes, while real-time dispatch platform deployment compresses deadhead mileage against emerging logistics competitors. For New Entrants and Emerging Players: Pursue Alberta oil sands thermal operations and Australian mining dust suppression corridors where cold-weather reliability requirements and 300-kilometer transport legs limit incumbent saturation. SAGD boiler feedwater logistics and Pilbara iron ore camp delivery represent penetrable white-space segments with premium pricing tolerance. For Investors and Strategic Acquirers: Basin-focused midstream operators with integrated treatment-hauling capabilities present the strongest acquisition target archetype, as EPA effluent guidelines force consolidation toward closed-loop recycling providers. Watch UIC permit queue lengthening in Texas and New Mexico as the inflection signal for captive hauling contract repricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Disposal Wells | Captive UIC-permitted injection capacity locks in hauling volumes against pipeline displacement. |
| Real-Time Dispatch Platform Deployment | API-integrated telematics reduces deadhead mileage for Permian Basin frac crew coordination. |
| Electrification Pilot Programs | IRA Section 45W credits offset battery-electric truck capital costs for municipal-fringe contracts. |
| Long-Term Offtake Agreement Structuring | 12-24 month minimum volume commitments guarantee fleet availability for multi-well pad programs. |
| Cold-Weather Operational Certification | Alberta Energy Regulator compliance enables SAGD facility servicing where pipeline frost heave limits fixed infrastructure. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet dispatch managers, E&P water logistics directors, TCEQ regulatory affairs officers, and municipal utility procurement leads. Secondary validation drew from EPA UIC permit databases, Texas Railroad Commission disposal well filings, DOT hazmat certification records, and E&P 10-K water management disclosures. Bottom-up triangulation across fleet capacity deployments and top-down reconciliation against basin-level produced water generation estimates anchored volume forecasts.
Calibration against historical contract award patterns and diesel price elasticity coefficients shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end user category, vessel capacity tier, and delivery mode, with hydraulic fracturing intensity and drought-driven municipal standby contracting as industry-specific demand drivers. CAGRs were derived from regression analysis of fleet utilization rates against completion activity indices.
Macroeconomic conditions sit as an overlay; deviation in diesel rack prices, CDL training throughput, or EPA enforcement intensity would shift the trajectory. Cross-checking against EIA petroleum product price benchmarks and American Trucking Associations labor market data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market