
 South Africa Courier, Express, and Parcel (CEP) Market | 2026-2036
South Africa Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Courier, Express, and Parcel (CEP) Market Insights
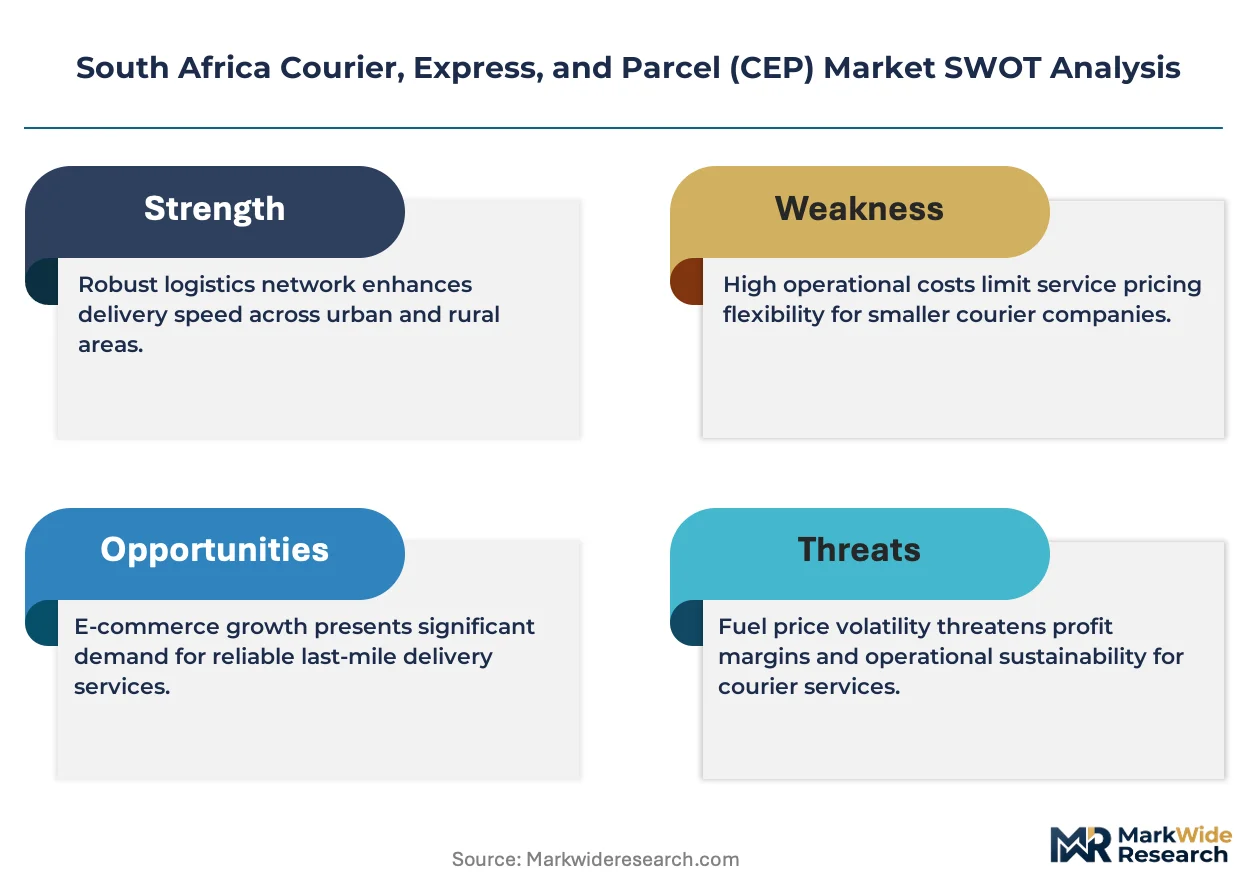
The capital-intensity divergence between asset-heavy integrators and lean last-mile specialists is redrawing competitive boundaries in South African logistics. DHL Group leverages its integrated air-ground network to sustain premium express margins across Johannesburg-Durban lanes. The Courier Guy anchors township penetration through hyperlocal pickup points that national carriers struggle to replicate.
Courier, Express, and Parcel services encompass time-definite transportation of documents and goods through integrated multimodal networks operating with defined service-level agreements and tracking protocols. The primary commercial purpose centers on bridging spatial and temporal gaps between producers and consumers across distributed supply chains. Standard delivery occupies the volume base as e-commerce retailers flood networks with price-sensitive parcels, while same-day delivery commands premium positioning in Gauteng and Western Cape urban cores where density justifies dedicated fleet deployment. Express service segments concentrate margin pools around pharmaceutical cold-chain and automotive parts shipments requiring temperature integrity and delivery guarantees.
The Department of Transport enforces cross-border customs modernization and fleet emissions standards that elevate compliance costs for road-based operators. National Energy Regulator of South Africa frameworks indirectly shape demand through electricity tariff structures affecting warehouse automation and electric vehicle charging infrastructure investments. Stakeholders must weigh electrification capex against diesel cost volatility while monitoring provincial logistics corridor development plans that will redistribute freight flows across the analysis window.
Market Dynamics
Fleet electrification mandates from the Department of Transport are forcing capital reallocation across South African logistics networks while e-commerce volume floods last-mile infrastructure in Gauteng and Western Cape urban corridors.
Growth Catalysts
- E-commerce fulfillment density:Johannesburg and Cape Town metropolitan zones generate sufficient parcel concentration to justify dedicated same-day fleet deployment and automated sorting investments.
- Cross-border customs modernization:The Department of Transport's streamlined clearance protocols reduce dwell times at Beitbridge and Lebombo border posts, accelerating regional express corridors into Zimbabwe and Mozambique.
- Cold-chain pharmaceutical demand:Temperature-controlled distribution networks expand as biologics and vaccine shipments require validated packaging and real-time monitoring across the analysis window.
Market Restraints
- Diesel price volatility:Road-based operators face margin compression from fuel input cost swings that electrification capex cannot immediately offset given grid reliability constraints.
- Concentrated port throughput:Durban Container Terminal handles the majority of maritime CEP inbound volume, creating single-point vulnerability for integrators dependent on sea-air intermodal connections.
- Last-mile labor scarcity:Township delivery networks confront driver retention challenges as gig-economy platforms compete for identical workforce pools.
Strategic Opportunities
- Eastern Cape underpenetration:Gqeberha and East London logistics corridors offer first-mover positioning as automotive manufacturing clusters generate outbound parcel density.
- Renewable energy logistics:Solar and wind component shipments create project-cargo express demand requiring specialized handling and installation-site delivery guarantees.
- Digital freight matching platforms:Algorithmic load consolidation connects fragmented owner-operator fleets to enterprise shippers, extracting idle capacity from informal transport networks.
Industry Challenges
- Electric vehicle charging infrastructure gaps:Long-haul electrification stalls without NERSA-approved grid upgrades along the N1 and N3 corridors, forcing hybrid fleet complexity.
- Skills mismatch in warehouse automation:Automated sortation and robotic picking systems outpace technician training pipelines, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Courier, Express, and Parcel (CEP) Market |
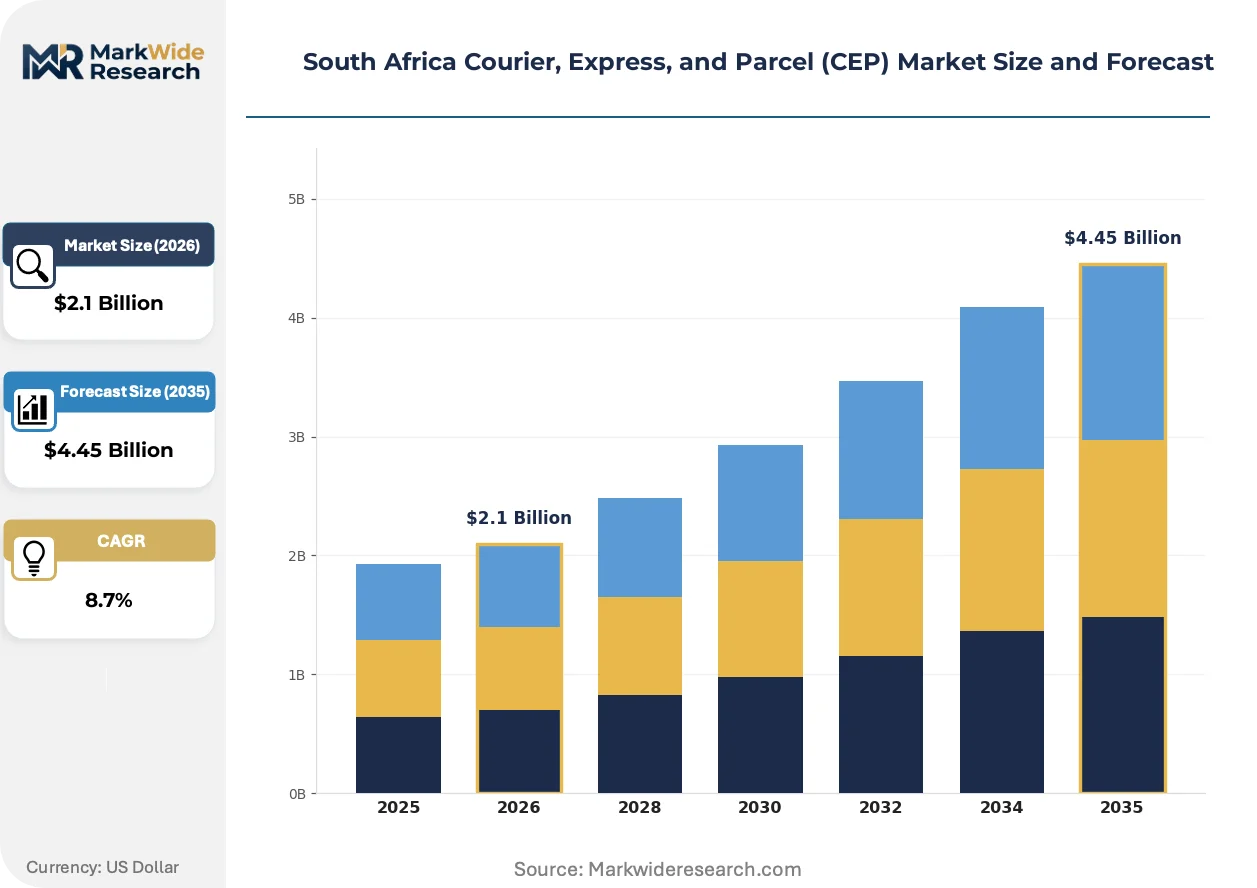
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, Express Service Delivery Mode: Ground Transportation, Air Freight, Rail Transport, Maritime Shipping End User: E-Commerce Retailers, Pharmaceuticals, Automotive Parts, Manufacturing Packaging Type: Boxed Products, Pallets, Envelopes, Crates |
| Companies Covered | The Courier Guy, DHL Group, RAM Hand-to-Hand Couriers, Aramex, United Parcel Service of America, Inc. (UPS), City Logistics (Pty) Ltd., FedEx, DPD Laser, Postnet South Africa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight platforms and electrification hardware are converging to reshape asset deployment models across South African logistics, compressing traditional network hierarchies while regulatory pressure accelerates compliance technology adoption.
Telematics-enabled dynamic routing is decomposing static hub-and-spoke networks into fluid, algorithm-orchestrated delivery meshes. E-commerce retailers in Sandton and Century City adopt these systems fastest, collapsing fixed route costs into variable per-parcel economics that reward density over scale.
The Department of Transport's fleet emissions standards are mandating telematics integration and carbon reporting across commercial vehicle registrations. Road-based operators face retrofit deadlines that favor newer fleet purchases over legacy diesel assets, with express carriers absorbing compliance costs through fuel surcharge mechanisms.
Subscription-based delivery memberships are displacing per-shipment pricing among urban consumers. Retailers in Johannesburg and Cape Town bundle unlimited delivery into loyalty programs, locking in recurring revenue while masking marginal cost fluctuations from fuel and labor volatility.
South Africa Courier, Express, and Parcel (CEP) Market Segmentation
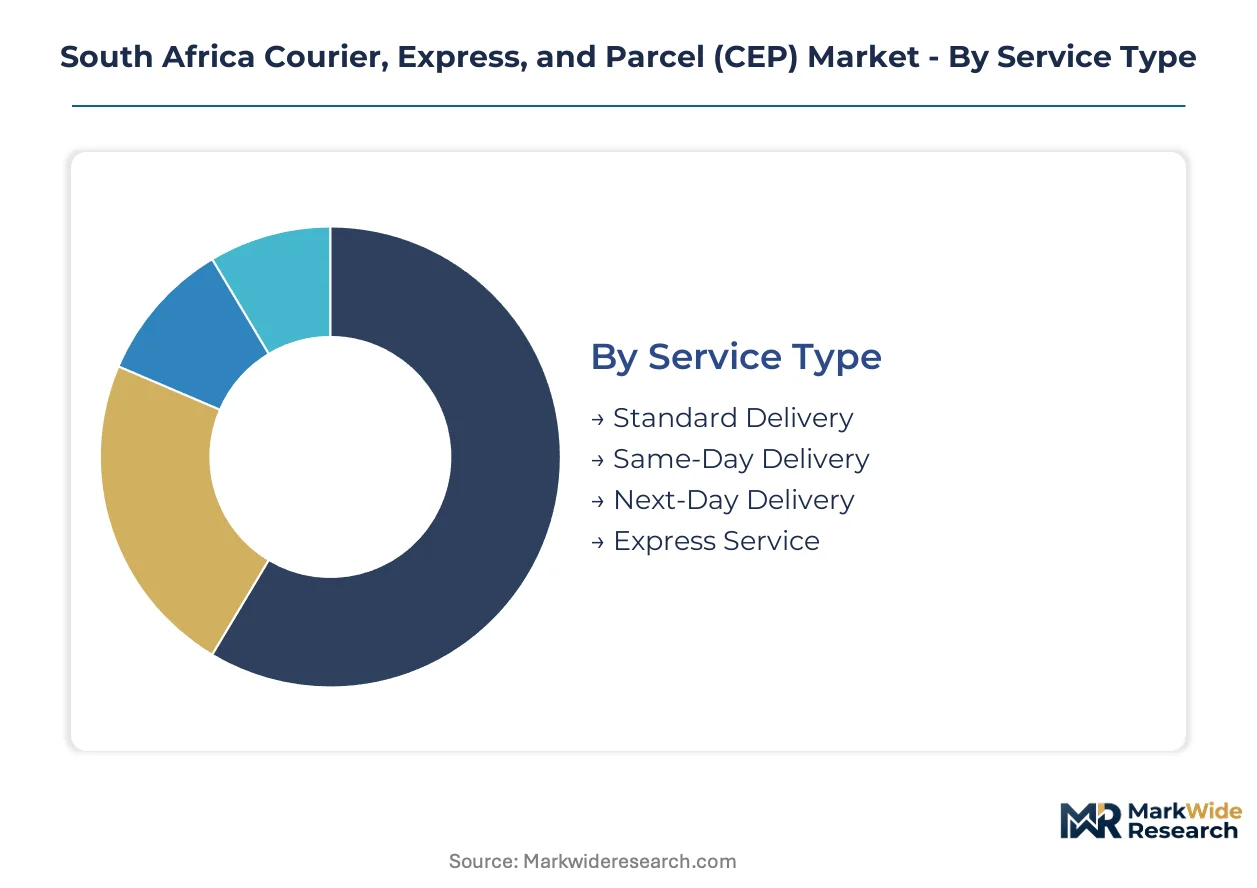
Segmentation in South African CEP logistics reveals how service tiers, modal choices, and end-use concentration create divergent margin profiles across Gauteng and Western Cape corridors. Understanding these divisions exposes where electrification mandates and e-commerce density reshape competitive positioning.
Service Type:
Substitution pressure runs deepest between standard and same-day delivery as urban consumers abandon deferred gratification for instant fulfillment across Johannesburg and Cape Town metropolitan zones.
- Standard Delivery:Deferred ground-based distribution with 2-5 day transit windows dominates e-commerce fulfillment volume. Retailers in Sandton and Century City leverage this tier for price-sensitive parcels where density justifies batch consolidation.
- Same-Day Delivery:Dedicated fleet deployment with dynamic routing algorithms compresses delivery windows to under six hours. Premium positioning captures disproportionate demand concentration in Gauteng and Western Cape urban cores where parcel density exceeds threshold economics.
- Next-Day Delivery:Overnight hub processing with morning drop guarantees occupies the middle tier. Pharmaceutical and automotive parts shippers favor this segment for predictable inventory replenishment without express premiums.
- Express Service:Time-definite multimodal networks with SLA guarantees and real-time tracking. Cold-chain pharmaceutical shipments and urgent manufacturing components require validated temperature integrity and delivery certainty.
Standard delivery anchors the volume base while same-day delivery gains share at the steepest rate.
Delivery Mode:
Cost tier stratification separates capital-intensive air networks from asset-light ground operations, with electrification mandates forcing reallocation across modal investments.
- Ground Transportation:Road-based fleet networks handle the majority of last-mile and intercity parcel volume. Diesel price volatility and Department of Transport emissions standards are forcing hybrid and electric vehicle adoption along N1 and N3 corridors.
- Air Freight:Integrated air-ground express networks sustain premium margins on Johannesburg-Durban lanes. Cold-chain pharmaceuticals and urgent automotive components demand the speed that only air cargo provides.
- Rail Transport:Bulk parcel consolidation on Transnet Freight Rail corridors offers cost advantages for non-urgent shipments. Modal share remains constrained by infrastructure reliability and scheduling rigidity.
- Maritime Shipping:Sea-air intermodal connections through Durban Container Terminal handle inbound international volume. Single-point port concentration creates vulnerability for integrators dependent on maritime CEP flows.
Ground transportation absorbs the greatest volume while air freight commands the highest margin premiums.
End User:
Application-specific requirements fragment service design, with temperature integrity and delivery guarantees separating pharmaceutical demand from commodity e-commerce flows.
- E-Commerce Retailers:Volume-flooding demand from online marketplaces and direct-to-consumer brands. Parcel concentration in Johannesburg and Cape Town justifies automated sorting investments and dedicated same-day fleet deployment.
- Pharmaceuticals:Biologics, vaccines, and temperature-sensitive medications require validated cold-chain packaging and real-time monitoring. Regulatory compliance from the country's national pharmaceutical regulator elevates service complexity.
- Automotive Parts:Just-in-time manufacturing supply chains demand precise delivery windows for production-critical components. Eastern Cape automotive clusters generate outbound express demand from Gqeberha and East London.
- Manufacturing:General industrial freight spans inbound raw materials and outbound finished goods. Procurement patterns favor cost-optimized standard delivery with periodic express exceptions for stockout emergencies.
E-commerce retailers dominate parcel volume while pharmaceuticals expand at the most rapid clip.
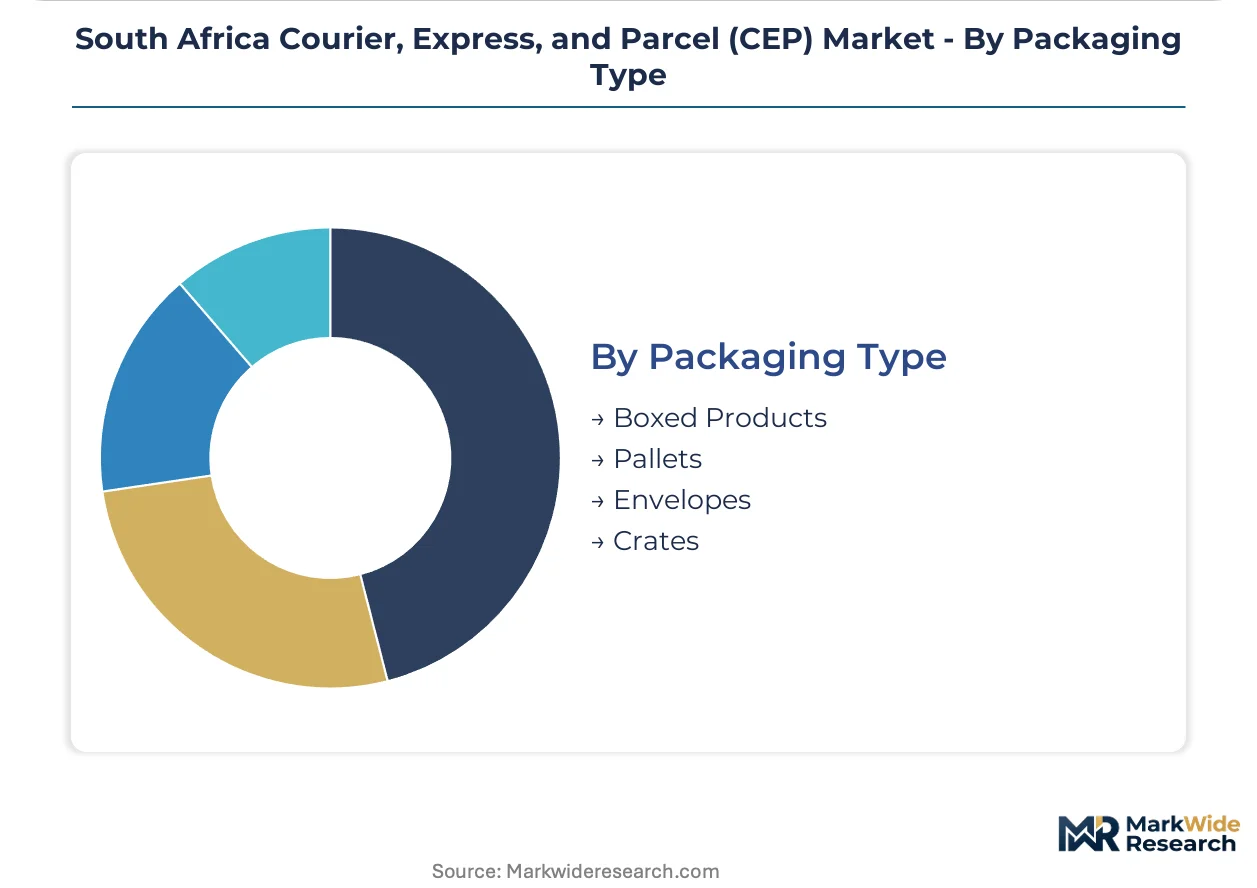
Packaging Type:
Volume-to-weight ratios and handling requirements segment operational investment, with bulk pallet flows contrasting sharply with envelope document streams.
- Boxed Products:Corrugated containers for individual e-commerce parcels and small parts shipments. Automated sortation systems in Gauteng hubs process millions of boxed units daily.
- Pallets:Unitized freight for B2B manufacturing and retail distribution. Forklift-compatible handling enables efficient cross-docking but requires specialized last-mile equipment.
- Envelopes:Document and small-item pouches for financial services and legal sectors. Digital displacement has collapsed this segment's growth trajectory.
- Crates:Rigid containers for fragile or high-value industrial equipment. Renewable energy component logistics for solar and wind projects create specialized crate handling demand.
Boxed products carry the heaviest throughput while pallets retain the strongest B2B pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in Gauteng and Western Cape corridors, where e-commerce density justifies same-day fleet investments, while Eastern Cape and KwaZulu-Natal operators absorb thinner margins on longer transit routes.
Gauteng
Johannesburg and Pretoria metropolitan zones generate the highest parcel concentration in the country. The Department of Transport's fleet electrification mandates accelerate EV charging infrastructure deployment along the N1 and N3 corridors. Sandton's automated sorting hubs process millions of boxed units daily for same-day delivery networks.
Western Cape
Cape Town's Century City retail cluster drives premium express demand for temperature-controlled pharmaceutical shipments. National Energy Regulator of South Africa electricity tariff frameworks shape warehouse automation investment decisions. The Stellenbosch wine district and Atlantis industrial zone create specialized outbound logistics requirements.
KwaZulu-Natal
Durban Container Terminal handles the majority of maritime CEP inbound volume, creating intermodal connectivity for integrators. Cross-border customs modernization at the Lebombo border post accelerates regional express corridors into Mozambique. The Dube TradePort cargo terminal anchors air-ground intermodal operations.
Eastern Cape
Gqeberha and East London automotive manufacturing clusters generate outbound parcel density for just-in-time parts shipments. Provincial logistics corridor development plans aim to redistribute freight flows from congested southern routes. The Coega Special Economic Zone attracts renewable energy component logistics requiring specialized handling.
Free State
Bloemfontein's central positioning enables hub-and-spoke distribution to secondary markets with lower real estate costs. Grid reliability constraints from Eskom's load-shedding schedules complicate electric vehicle charging infrastructure planning. The N1 highway corridor connects Gauteng volume to Northern Cape mining operations.
South Africa Courier, Express, and Parcel (CEP) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated global networks commanding premium express margins while lean last-mile specialists capture township penetration through hyperlocal density. The market structure fragments across asset-heavy integrators, regional road-based operators, and digital freight platforms. Three archetypes dominate: multinational integrators with air-ground networks, domestic specialists with township pickup point density, and algorithmic freight matchers extracting idle capacity. Competitive moves concentrate on fleet electrification partnerships and automated sorting investments.
Among multinational integrators, DHL Group and United Parcel Service of America, Inc. exemplify the premium express archetype through integrated multimodal positioning. The Courier Guy and RAM Hand-to-Hand Couriers represent domestic specialists with hyperlocal network density that national carriers struggle to replicate. Aramex anchors the middle-market regional express segment connecting South Africa to cross-border corridors.
| Leading Market Players |
|---|
| The Courier Guy |
| DHL Group |
| RAM Hand-to-Hand Couriers |
| Aramex |
| United Parcel Service of America, Inc. (UPS) |
| City Logistics (Pty) Ltd. |
| FedEx |
| DPD Laser |
| Postnet South Africa |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts between e-commerce retailers and fleet operators lock in dedicated lane access while insulating volume commitments from diesel price volatility. These arrangements concentrate pricing power with asset-heavy integrators who control Johannesburg-Durban air-ground corridors.
Pricing Analysis
The customization-premium spread between configured same-day routing and standard deferred delivery separates margin pools across service tiers. Three-tier pricing structure across premium express, standard ground, and economy batch consolidation captures divergent buyer willingness-to-pay. Pricing pressure stems from gig-economy platforms compressing last-mile labor costs in Gauteng townships. E-commerce retailers exhibit highest price sensitivity, while pharmaceutical cold-chain shippers absorb premium positioning without volume elasticity.
Supply Chain Analysis
Inbound logistics costs through Durban Container Terminal concentrate vulnerability for sea-air intermodal flows dependent on container availability from China and Southeast Asian manufacturing hubs. The South African CEP supply chain draws from German automotive component suppliers, Chinese e-commerce packaging materials, and Indian pharmaceutical APIs. Single-source port concentration at Durban creates structural risk for integrators. Distribution runs through hub-and-spoke networks anchored at Sandton and Century City automated sorting facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates from the Department of Transport are disrupting capital allocation patterns while compressing traditional diesel-based operating models. This regulatory inflection creates asymmetric opportunity for operators with balance sheet capacity to absorb charging infrastructure capex.
For Market Incumbents: Compound network density advantages through automated sorting investments in Gauteng and Western Cape corridors. Integrators must absorb NERSA electricity tariff volatility through captive renewable generation or long-term power purchase agreements. Defensive positioning requires locking in township pickup point exclusivity before digital freight platforms achieve matching density.
For New Entrants and Emerging Players: Differentiate on algorithmic load consolidation connecting fragmented owner-operator fleets to enterprise shippers. Eastern Cape automotive corridors offer penetrable white-space with lower competitive saturation than Johannesburg-Cape Town lanes. Go-to-market execution should prioritize project-cargo express for renewable energy component logistics requiring specialized handling.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based delivery membership operators with locked-in urban consumer bases. Long-term viability favors asset-light platforms with algorithmic orchestration over capital-intensive fleet ownership. Acquisition targeting should focus on domestic specialists with hyperlocal township density. The signal to watch is NERSA grid upgrade approval timelines along N1 and N3 corridors as electrification inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Department of Transport emissions compliance secures operating license continuity across Johannesburg-Durban lanes. |
| Automated Sorting Investment | Gauteng hub processing capacity captures e-commerce volume concentration from Sandton and Century City retailers. |
| Hyperlocal Pickup Point Expansion | Township penetration density replicates The Courier Guy's model that national carriers struggle to match. |
| Cross-Border Customs Integration | Lebombo and Beitbridge streamlined clearance accelerates regional express corridors into Mozambique and Zimbabwe. |
| Cold-Chain Certification Investment | South African pharmaceutical regulator compliance unlocks biologics and vaccine distribution margin pools. |
Research Methodology
The analysis maps express service tiers, ground-air modal networks, and end-use verticals, each validated through fleet operations directors, e-commerce logistics procurement managers, and pharmaceutical supply chain leads. Primary fieldwork combined with secondary validation from Transnet Freight Rail corridor data, Department of Transport regulatory filings, and NERSA electricity tariff schedules. Bottom-up parcel volume modeling triangulated against top-down GDP-corridor freight projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, delivery mode, end-use vertical, and packaging format. CAGRs derived from trend extrapolation of e-commerce penetration rates, fleet electrification capex cycles, and cross-border customs modernization timelines. Industry-specific forecast inputs incorporated pharmaceutical cold-chain regulatory requirements and automotive just-in-time delivery window specifications.
Forecasts assume regulatory continuity in Department of Transport emissions standards and NERSA grid access frameworks; material policy shifts would require re-modeling. Specific risk factors include Eskom load-shedding severity exceeding baseline assumptions and diesel price volatility diverging from historical bands. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market