
 Airport Bus Market | 2026-2036
Airport Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Bus Market Intelligence
Capital-intensity divergence between electric powertrain specialists and conventional diesel manufacturers is bifurcating competitive dynamics. BYD Motors leverages integrated battery production to control costs across the value chain. Solaris Bus & Coach sustains European market presence through modular platform architectures. MAN Truck & Bus anchors German-speaking markets with established service networks and aftermarket density.
Airport buses are specialized low-floor vehicles designed for tarmac and terminal-zone passenger transport, typically featuring standing-room configurations, wide doors, and reinforced chassis rated for continuous stop-start cycles exceeding 500 daily operations. Their primary purpose is ensuring gate-to-terminal connectivity while complying with strict airside safety protocols. The shuttle segment dominates volume due to recurring procurement cycles at hub airports, while luxury configurations command premium pricing from premium carriers seeking brand differentiation. Electric bus types are capturing the fastest expansion as battery energy density improvements enable 300-kilometer daily duty cycles without midday charging.
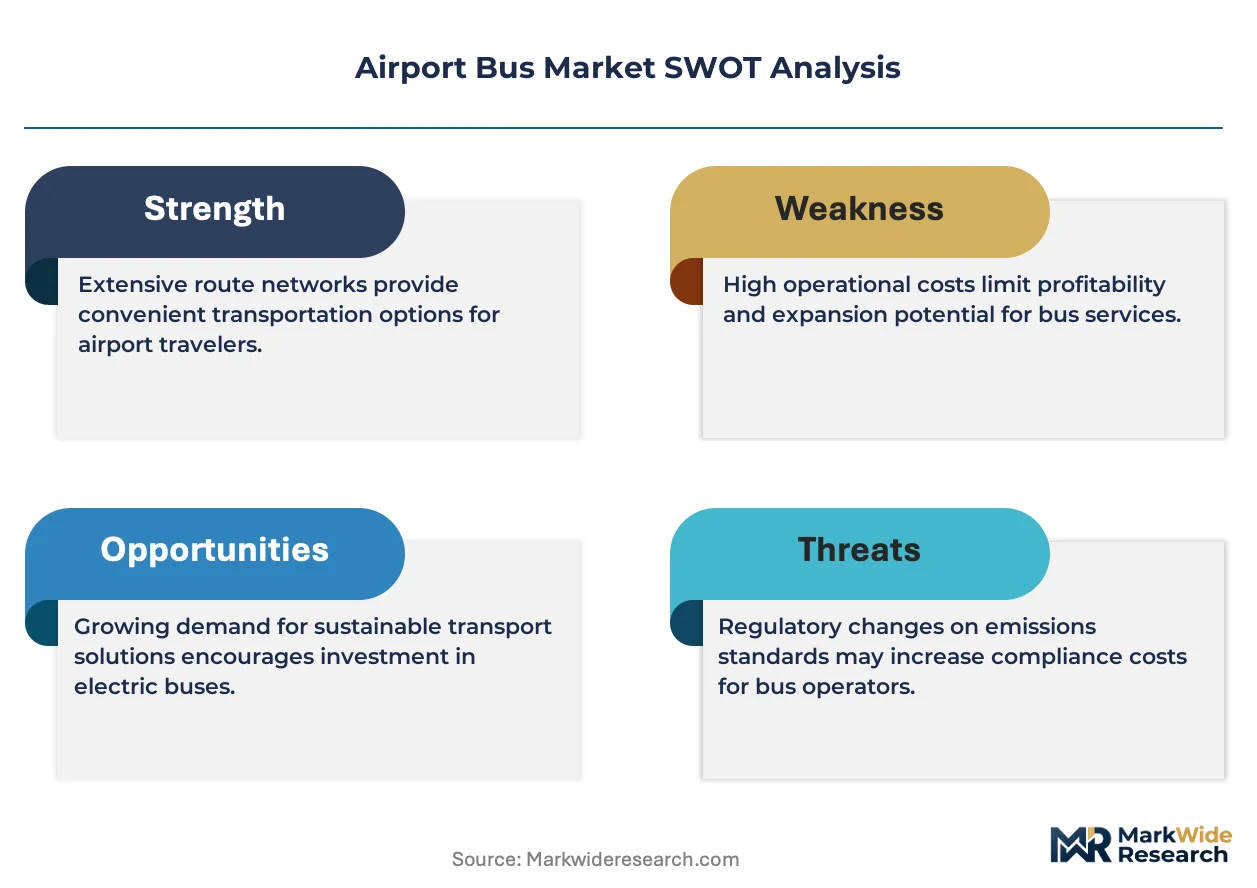
The EU Green Deal and F-Gas Regulation are mandating fleet decarbonization timelines that reshape procurement specifications across European airports. The FAA and EPA jointly govern US airside emissions standards and alternative-fuel vehicle certifications, creating compliance complexity for multi-jurisdiction operators. Stakeholders must monitor battery-swapping infrastructure deployment at major hubs and assess whether captive charging or third-party energy supply better aligns with capital allocation priorities.
Market Dynamics
Airport bus electrification is decomposing traditional procurement frameworks as battery chemistry improvements and EU Green Deal mandates force parallel obsolescence of diesel fleet renewal cycles. This structural pressure reconfigures supplier relationships, capital allocation timelines, and airside infrastructure planning across major hub airports.
Growth Catalysts
- EU Green Deal fleet mandates:Binding decarbonization timelines for ground support equipment at European airports are accelerating zero-emission vehicle procurement specifications and shortening diesel replacement windows.
- Hub airport expansion in China:Massive terminal construction at Beijing Daxing, Chengdu Tianfu, and Shenzhen Bao'an is generating concentrated demand for apron-compatible electric shuttles with 300-kilometer duty cycles.
- Battery energy density gains:Lithium iron phosphate chemistry improvements now enable single-charge operations covering full daily rotation schedules without midday infrastructure investment.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings for cathode active materials compress electric bus margins and complicate long-term fleet cost forecasting for airport procurement teams.
- Charging infrastructure capital intensity:Megawatt-scale depot charging installations require dedicated electrical substations and grid reinforcement that strain municipal utility coordination timelines.
- F-Gas Regulation compliance friction:European thermal management system specifications for battery cooling create certification bottlenecks that extend type-approval durations for new electric platforms.
Strategic Opportunities
- Battery-swapping infrastructure at super-hubs:Automated exchange systems at Dubai International and Singapore Changi eliminate charging downtime and enable smaller battery packs per vehicle.
- Autonomous apron navigation trials:Lidar and V2X convergence is opening closed-loop airside routes for driverless shuttle operations during low-visibility conditions.
- India PLI scheme for electric buses:Domestic production incentives are lowering landed costs for airport authorities at Delhi, Mumbai, and Bangalore seeking fleet electrification.
Industry Challenges
- Airside safety certification complexity:FAA and EASA divergent standards for autonomous vehicle operation on active tarmacs force duplicate testing protocols and delay deployment timelines.
- Legacy fleet interoperability:Mixed diesel-electric operations require dual maintenance training, spare parts inventories, and fueling infrastructure that fragment operational efficiency.
- High-voltage technician scarcity:Specialized electrical system diagnostics and battery pack repair skills command premium wages and constrain service network expansion for electric platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Bus Market |
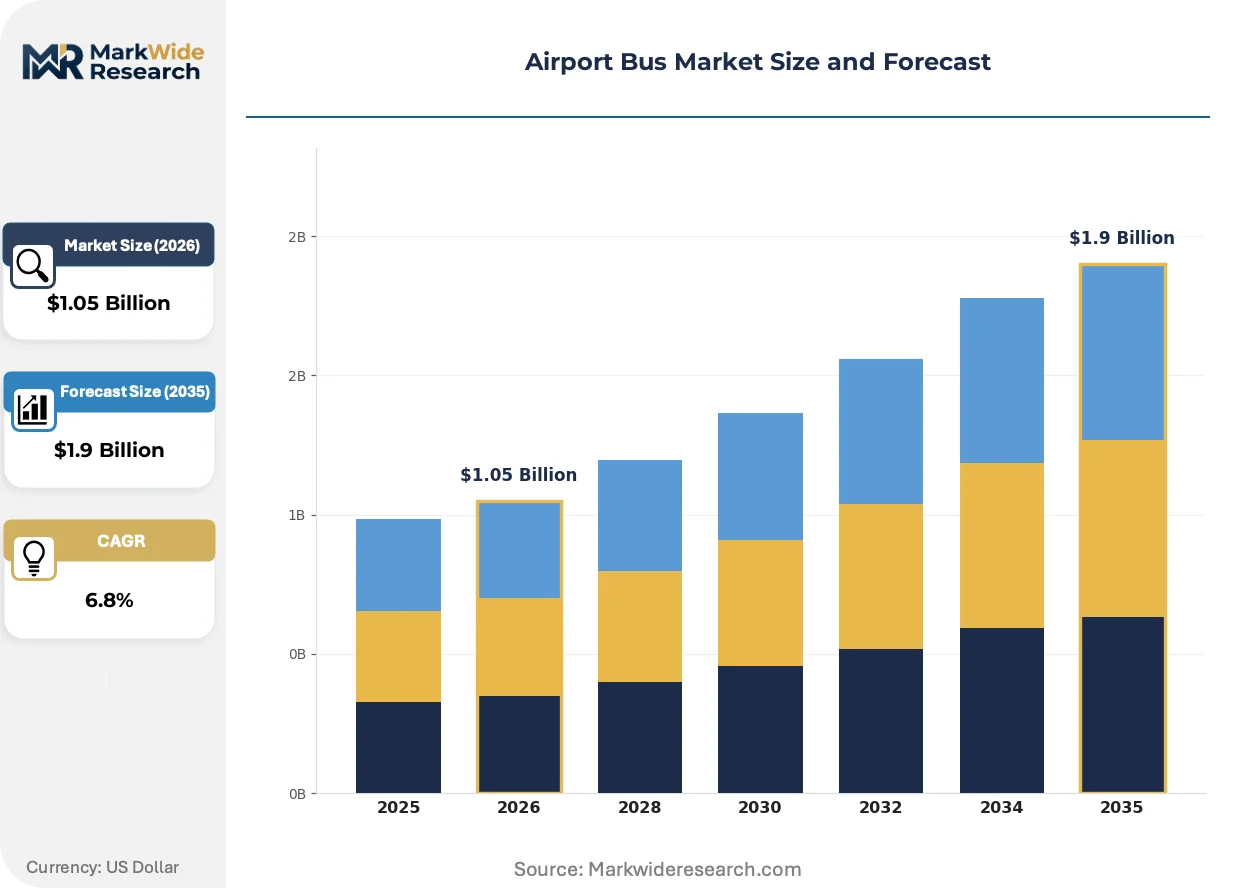
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Standard, Luxury, Shuttle, Double-Decker Customer Type: Business Travelers, Tourists, Airport Staff, Local Residents Service Model: Fixed Route, On-Demand, Scheduled, Charter Fare Structure: Single Ticket, Round Trip, Group Discount, Subscription |
| Companies Covered | Solaris Bus & Coach, MAN Truck & Bus, COBUS Industries, Isuzu Motors, Mallaghan, BYD Motors, Yutong Bus, BMC Otomotiv, AB Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Bus Market Strategic Shifts & Innovations
Solid-state battery prototyping and autonomous navigation testing are converging to redefine airside mobility architecture. These developments compress vehicle lifecycle economics while expanding operational flexibility for 24-hour hub operations.
Solid-state electrolyte technology is decomposing conventional lithium-ion pack architectures in airport bus applications. Prototype vehicles at Amsterdam Schiphol and Seoul Incheon demonstrate 40% energy density improvements over liquid-electrolyte systems. This chemistry transition is compressing total cost of ownership calculations and accelerating fleet replacement decisions at major European and Asian hubs.
The EU F-Gas Regulation is mandating refrigerant phase-downs in thermal management systems for electric airport buses. This policy compresses supplier engineering timelines and forces redesign of battery cooling circuits. German and French airports are responding with accelerated procurement of CO2-based heat pump systems despite 15% capital cost premiums.
Hub airports are consolidating ground transport procurement under single-operator concessions that bundle bus, apron tram, and automated people mover services. This model displaces fragmented multi-vendor arrangements at London Heathrow and Frankfurt. The shift is most visible in Gulf Cooperation Council states where sovereign wealth vehicle operators capture integrated mobility contracts spanning 15-year terms.
Airport Bus Market Segmentation
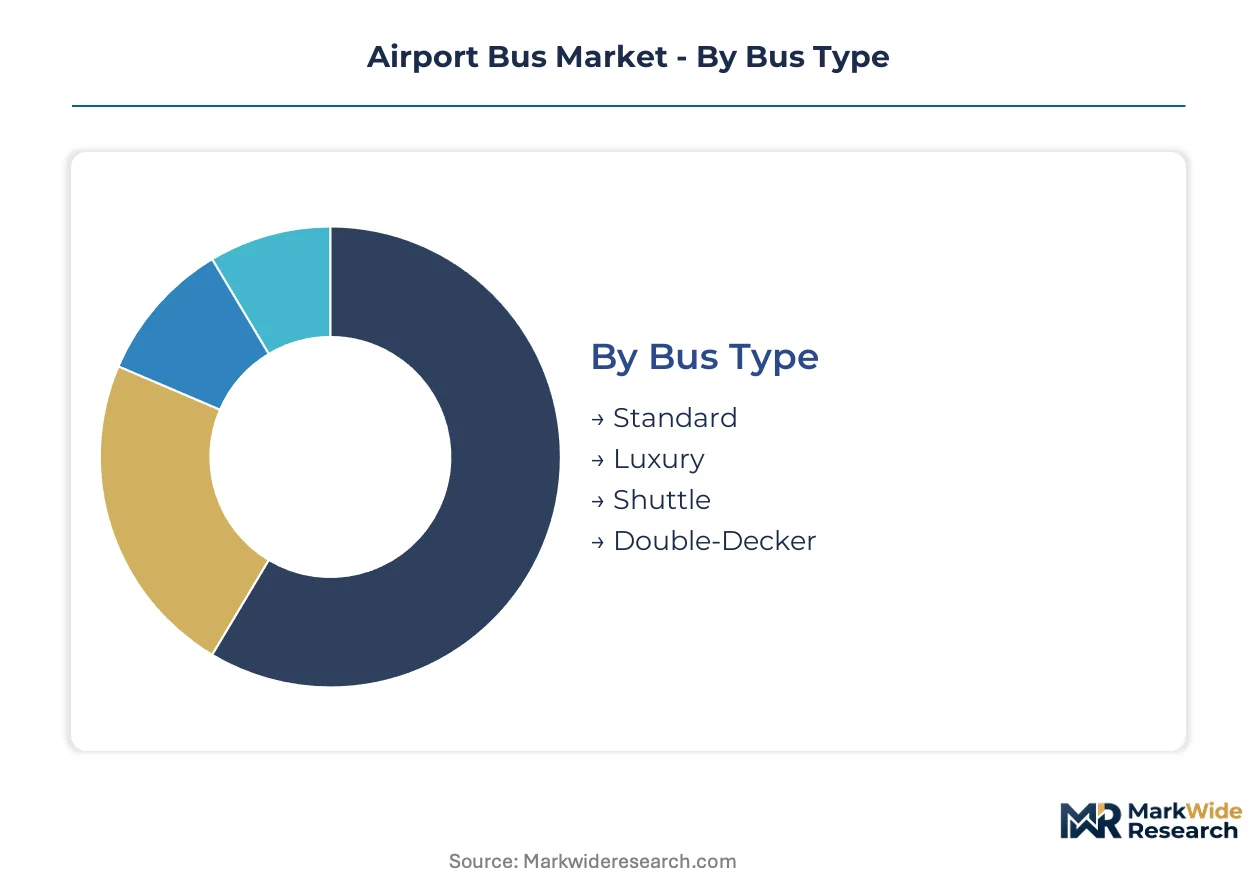
Airport bus procurement specifications diverge sharply across passenger profiles and operational zones. Fleet managers configure vehicle specifications, service frequencies, and fare systems to match distinct movement patterns between terminals, parking structures, and ground transport interchanges.
Bus Type:
FAA and EASA airside certification protocols impose divergent structural requirements on apron-compatible vehicle architectures. The EU Green Deal mandates are accelerating zero-emission specifications for tarmac operations while legacy diesel platforms retain terminal-zone deployment.
- Shuttle:Low-floor standing-room configurations with reinforced chassis rated for 500+ daily stop-start cycles dominate apron-to-terminal connectivity. Demand concentrates at Chinese hub airports including Beijing Daxing and Chengdu Tianfu where electric 300-kilometer duty cycles eliminate midday charging infrastructure.
- Luxury:Premium leather seating, climate-controlled cabins, and extended luggage compartments serve first-class and business-class passenger segments. Gulf Cooperation Council carriers at Dubai International and Qatar's Hamad International deploy these configurations for brand differentiation during long-haul connections.
- Standard:Fixed-seating diesel and hybrid platforms serve cost-sensitive terminal-to-parking routes at secondary airports.
- Double-Decker:High-capacity configurations maximize passenger throughput during peak arrival banks at London Heathrow and Amsterdam Schiphol constrained-gate operations.
Established volume favors Shuttle configurations; emerging adoption favors Luxury specifications as premium carriers expand ground experience investments.
Customer Type:
Movement patterns determine fleet sizing algorithms and route density calculations across divergent passenger profiles.
- Tourists:Luggage-heavy leisure travelers with unpredictable arrival timing drive demand for high-frequency, high-capacity services with expanded baggage storage. European summer seasonal peaks at Barcelona El Prat and Rome Fiumicino strain apron bus deployment schedules.
- Business Travelers:Time-sensitive passengers with minimal luggage prioritize direct terminal-to-premium lounge connectivity. Frankfurt and Munich airports configure dedicated luxury shuttle circuits for Star Alliance hub transfer passengers.
- Airport Staff:Predictable shift-based commuting patterns enable optimized fixed-route scheduling with subscription fare structures.
- Local Residents:Price-sensitive occasional users accessing airport employment or intermodal connections generate off-peak demand variability.
Route density optimization targets Business Travelers for premium yield; fleet capacity planning centers on Tourist volume volatility.
Service Model:
Operational control frameworks range from captive airport authority fleets to third-party concession contracts with divergent capital allocation structures.
- Fixed Route:Predictable terminal-gate-parking circuits with published timetables enable fleet utilization rates exceeding 80% during operating hours. Singapore Changi and Hong Kong International operate integrated fixed-route networks spanning all passenger terminals.
- Scheduled:Timetable-based services with limited deviation authority balance reliability against operational flexibility at mid-size European airports.
- On-Demand:App-dispatched microtransit for premium passengers and accessibility requirements commands per-trip premiums but fragments fleet deployment efficiency.
- Charter:Dedicated aircraft-to-terminal services for VIP delegations and sports team movements generate episodic high-margin revenue.
Operational stability favors Fixed Route deployment; revenue diversification favors On-Demand pilot programs at super-hub airports.
Fare Structure:
Revenue recognition timing and working capital requirements vary substantially across payment collection architectures.
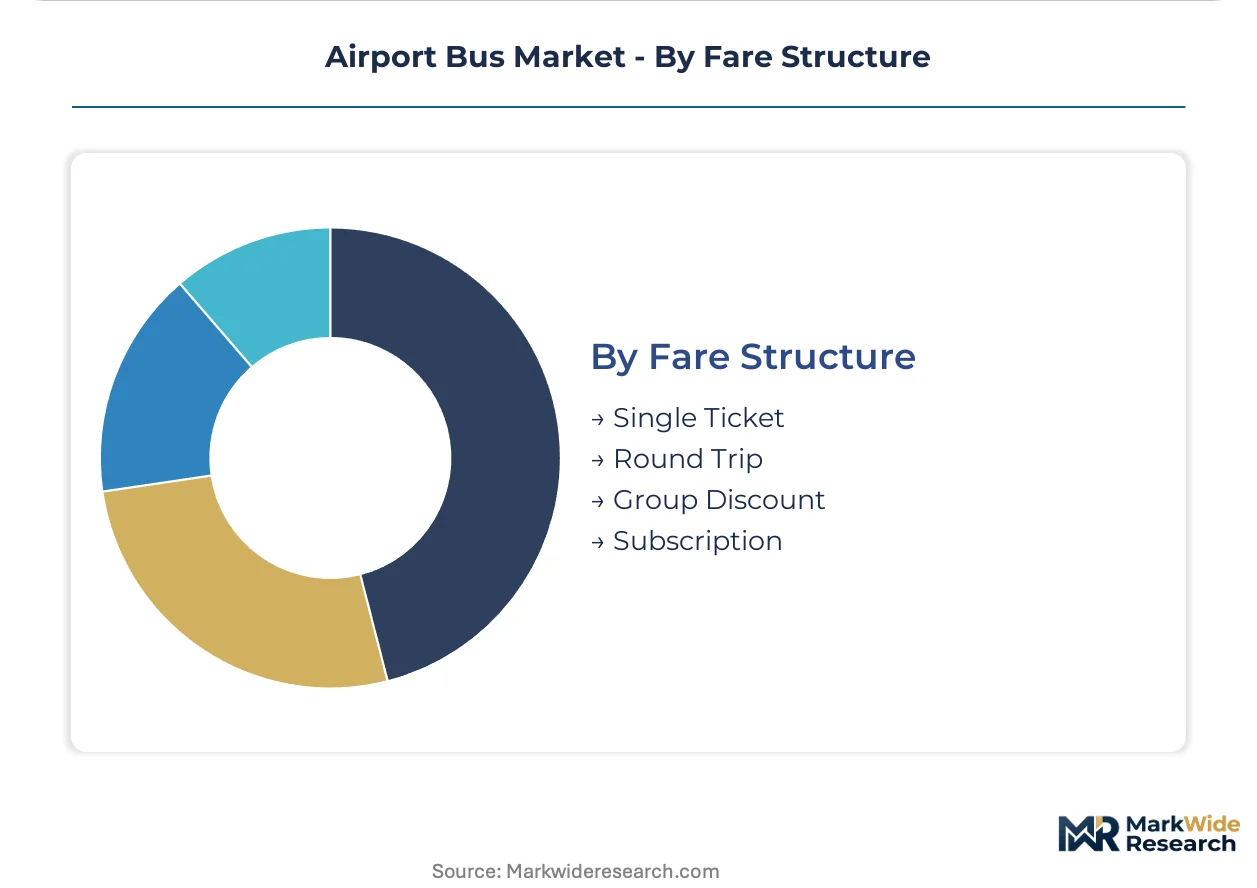
- Single Ticket:Immediate cash or contactless payment at point of boarding minimizes accounts receivable exposure. US airports under FAA ground transport guidelines predominantly deploy this structure for inter-terminal connectivity.
- Subscription:Monthly or annual passes for frequent flyers and airport employees generate predictable recurring revenue streams. Amsterdam Schiphol and Frankfurt offer integrated subscription products bundling bus, rail, and parking access.
- Round Trip:Discounted return-journey pricing captures price-sensitive leisure passengers with confirmed departure schedules.
- Group Discount:Volume pricing for tour operators and corporate travel managers reduces per-passenger yield while guaranteeing load factors.
Cash flow predictability favors Subscription structures; yield maximization favors Single Ticket deployment at high-volume transfer hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through integrated battery supply chains while European manufacturers absorb 15-20% cost premiums from regulatory compliance. This asymmetry shapes procurement patterns across major hub airports.
China
Beijing Daxing and Chengdu Tianfu terminal expansions drive concentrated demand for 300-kilometer duty cycle electric shuttles. MIIT dual carbon goals mandate ground support equipment electrification timelines at all tier-one airports. BYD Motors and Yutong Bus anchor production clusters in Shenzhen and Zhengzhou, supplying domestic hubs and export markets across Southeast Asia.
Germany
Frankfurt and Munich airports configure dedicated luxury shuttle circuits for Star Alliance transfer passengers. EU Green Deal binding decarbonization timelines compress diesel replacement windows to 2027-2030. MAN Truck & Bus anchors manufacturing in Bavaria with established service networks across German-speaking markets.
United States
FAA and EPA joint governance of airside emissions standards creates compliance complexity for multi-jurisdiction operators at Atlanta and Dallas-Fort Worth. IRA alternative-fuel vehicle tax credits offset 30% of electric bus procurement costs for airport authorities. Proterra and BYD Motors supply zero-emission platforms to California and Northeast corridor hubs.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International consolidate ground transport under 15-year integrated mobility concessions. MOHAP procurement guidelines prioritize thermal resilience specifications for 50°C ambient operations. Sovereign wealth vehicle operators capture bundled bus, apron tram, and automated people mover contracts.
India
Delhi Indira Gandhi, Mumbai Chhatrapati Shivaji, and Bangalore Kempegowda airports seek fleet electrification under PLI scheme production incentives. CEA grid integration standards govern megawatt-scale depot charging substations. Tata Motors and Olectra Greentech supply electric platforms to airport authorities with 25% domestic content requirements.
Airport Bus Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with battery-integrated manufacturers commanding supply chain control while European incumbents leverage regulatory relationships and aftermarket density. The market structures around three tiers: integrated battery producers, modular platform specialists, and legacy diesel-hybrid anchors. Consolidation pressure concentrates in the middle tier as electrification mandates force portfolio transitions. Strategic moves center on backward integration into cathode materials and geographic expansion through hub airport concession partnerships.
Among battery-integrated manufacturers, BYD Motors exemplifies cost leadership through captive lithium iron phosphate cell production. European modular specialists include Solaris Bus & Coach, which occupies a position emphasizing platform flexibility across duty cycle specifications. Legacy diesel-hybrid anchors such as MAN Truck & Bus represent established service network density in regulated procurement environments. These three archetypes capture divergent value pools as electrification decomposes traditional fleet renewal frameworks.
| Leading Market Players |
|---|
| Solaris Bus & Coach |
| MAN Truck & Bus |
| COBUS Industries |
| Isuzu Motors |
| Mallaghan |
| BYD Motors |
| Yutong Bus |
| BMC Otomotiv |
| AB Volvo |
| Others |
Cost & Logistics Intelligence
Ninety-day battery pack lead times from cathode material suppliers to final assembly plants concentrate pricing power with integrated cell manufacturers and compress margins for modular platform assemblers. This inventory compression dynamic forces procurement teams at European and Gulf hub airports to accept longer order cycles or pay configured-to-order premiums for apron-compatible electric shuttles.
Pricing Analysis
The customization-premium spread between standard shuttle configurations and tarmac-certified luxury variants runs three-to-one at major hub airports. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification grades for airside operation, with EU Green Deal compliance tiers commanding additional engineering fees. Cost compression in standard diesel-hybrid segments is intensifying because Chinese battery-integrated manufacturers are exporting surplus capacity into secondary airport markets. Business travelers and premium carriers show lowest price sensitivity, while municipal airport authorities in India and Southeast Asia prioritize landed cost minimization above thermal resilience specifications.
Supply Chain Analysis
Lithium carbonate refining capacity chokepoints in Chile and Australia constrain cathode active material flow to cell plants in China and South Korea. Battery pack assembly draws from processed lithium, nickel sulfate, and copper foil inputs, with thermal management systems sourcing CO2 heat pumps from German and French component specialists. Single-source vulnerability concentrates in solid-state electrolyte prototyping facilities serving Amsterdam Schiphol and Seoul Incheon validation programs. Distribution runs through hub airport concession operators who bundle fleet procurement with 15-year service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around EU Green Deal certification timelines and FAA airside safety protocols creates multi-year switching costs for incumbent fleet operators.
For Market Incumbents: Compound aftermarket service density through captive high-voltage technician training programs and regional battery-swapping infrastructure deployment. Battery chemistry transition risk from lithium iron phosphate to solid-state platforms threatens stranded tooling investments; defend by securing exclusive cathode material offtake agreements with Chinese refiners and pre-purchasing grid substation capacity at super-hub locations. For New Entrants and Emerging Players: Autonomous apron navigation validation gaps where incumbents under-serve create entry points for lidar-integrated shuttle specialists. White-space targets include Indian tier-two airports under PLI scheme production incentives and Middle Eastern thermal-resilience specifications above 50°C ambient operation. Penetrate through battery-as-a-service financing models that eliminate upfront capital barriers for municipal airport authorities. For Investors and Strategic Acquirers: Long-term, this sits as a concession-utility play because 15-year integrated mobility contracts at Dubai International and Singapore Changi generate annuity-like revenue visibility with inflation-linked escalators. Acquisition target archetype: modular platform specialists with EASA type-approval certificates and established relationships with Star Alliance hub operators. Watch battery-swapping infrastructure deployment velocity at Beijing Daxing and Chengdu Tianfu as inflection indicator for capital-light operational models displacing depot charging.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell allocation from BYD or CATL for 300-kilometer duty cycle certification. |
| Airside Safety Certification Investment | EASA and FAA dual-type approval opens procurement at transatlantic hub airports with convergent standards. |
| Charging Infrastructure Partnership | Megawatt-scale depot installations with grid operators at Frankfurt and Munich compress utility coordination timelines. |
| Platform Standardization | Modular chassis architectures across shuttle and luxury variants reduce spare parts inventory fragmentation. |
| Geographic Manufacturing Footprint | Production proximity to Zhengzhou and Shenzhen clusters controls landed costs for Southeast Asian export markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airport fleet procurement managers, ground handling concession directors, battery system integration engineers, and thermal management specialists. Secondary validation drew from EU Green Deal implementation progress reports, FAA airside emissions guidance documents, EASA type-approval databases, and MIIT dual carbon goal disclosures. Bottom-up fleet deployment counts at tier-one airports were triangulated against top-down manufacturer shipment records.
Across the analysis window, volume and value outputs reflect modeled segmentation across bus type, service model, and customer profile dimensions, with propulsion architecture as an industry-specific overlay. CAGRs were derived from logistic growth curve fitting to electrification penetration S-curves, incorporating battery energy density improvement trajectories and regulatory mandate enforcement probability weightings.
Forecasts assume regulatory continuity in EU Green Deal decarbonization timelines and FAA-EPA joint governance structures; material policy shifts would require re-modeling fleet replacement acceleration or delay scenarios. Practitioners should keep alternative scenarios live as lithium carbonate price volatility and autonomous vehicle liability frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Trolley Bus Market
Buses
Canada School Bus Market
Buses
Bus Bellows Market
Buses
Europe Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Hydrogen Buses Market
Buses
Bus Chassis Market
Buses
Luxury Bus Market
Buses
Bus Transmission System Market
Buses
Global Bus Market
Buses
North America Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Rental Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Bus Flooring Market
Buses
Intercity Bus Travel Market