
 Qatar Third-Party Logistics (3PL) Market | 2026-2036
Qatar Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Third-Party Logistics (3PL) Market Analytics
Qatar's warehousing capacity is decoupling from port-centric layouts as inland distribution nodes multiply across Mesaieed and Doha Industrial Area. Gulf Warehousing Company anchors domestic cold-chain infrastructure through its pharmaceutical-certified facilities. Maersk leverages integrated container logistics to control ocean-to-warehouse handoffs at Hamad Port. Kuehne + Nagel competes on project cargo specialization serving energy and construction verticals.
Third-Party Logistics encompasses outsourced supply chain management where providers coordinate transportation, warehousing, and inventory management through integrated information systems, typically operating under service-level agreements with defined key performance indicators for order accuracy and delivery windows. Its primary purpose is to reduce capital intensity for shippers while improving network efficiency through scale economies and specialized expertise. Transportation services dominate current revenue as hydrocarbon and construction freight sustain high tonnage movements, while order fulfillment is expanding fastest as e-commerce penetration drives same-day delivery expectations. Cloud-based solutions are reshaping competitive dynamics by enabling real-time inventory visibility that reduces safety stock requirements across retail and healthcare end users.
The Ministry of Public Health enforces cold-chain compliance standards that elevate barrier to entry for pharmaceutical logistics providers, while Qatar Free Zones Authority licensing frameworks shape foreign operator market access through joint venture requirements. Customs regulations administered by the General Authority of Customs mandate pre-arrival documentation that accelerates clearance timelines for digitized freight forwarders. Stakeholders must monitor evolving data localization requirements as the National Cyber Security Agency develops cloud governance frameworks affecting warehouse management system architecture decisions.
Market Dynamics
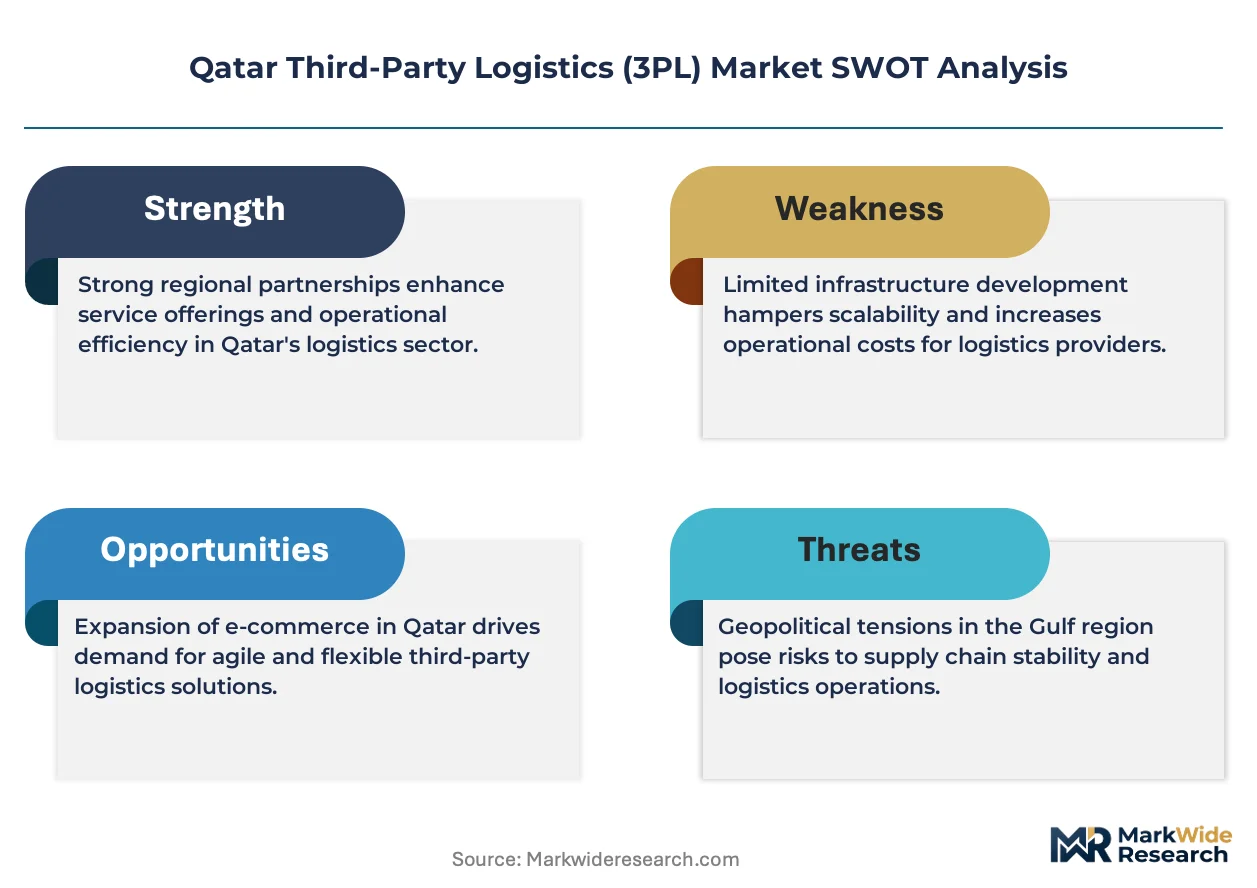
Cold-chain mandates from the Ministry of Public Health are restructuring Qatar's 3PL competitive landscape by forcing capital deployment into pharmaceutical-certified infrastructure and disqualifying generalist operators from high-margin healthcare contracts.
Growth Catalysts
- Free zone licensing frameworks:Qatar Free Zones Authority joint venture requirements are channeling foreign capital into integrated warehousing clusters at Ras Laffan, creating captive demand for bonded logistics services.
- E-commerce fulfillment velocity:Same-day delivery expectations from Doha's retail corridors are compressing order cycle times and expanding contract values for last-mile specialists.
- Hamad Port expansion:Deep-water container terminal capacity additions are reducing ocean-to-inland transit friction and attracting regional transshipment volumes.
Market Restraints
- Specialized labor scarcity:Cold-chain technicians and pharmaceutical logistics certified staff command premium wages that compress operator margins.
- Real estate concentration:Industrial zoned land availability is constrained around Doha and Mesaieed, influring lease rates for ambient and temperature-controlled facilities.
- Energy input volatility:Diesel and electricity cost fluctuations directly impact refrigerated transport unit economics across Qatar's dispersed industrial zones.
Strategic Opportunities
- Healthcare vertical deepening:Ministry of Public Health biologics distribution tenders are opening long-term contract opportunities for GDP-compliant 3PL providers.
- Project cargo specialization:Energy sector construction cycles in Ras Laffan and Mesaieed are generating demand for heavy-lift and oversized freight management.
- Warehouse management system modernization:Cloud-native platforms are enabling mid-tier operators to offer real-time inventory visibility without proprietary infrastructure investment.
Industry Challenges
- Pharmaceutical certification timelines:Ministry of Public Health facility audits and GDP compliance validation extend market entry cycles by 12-18 months for new cold-chain entrants.
- Legacy system integration friction:Enterprise shippers in hydrocarbon and construction verticals operate on fragmented ERP architectures that resist API-based data exchange with 3PL platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Third-Party Logistics (3PL) Market |
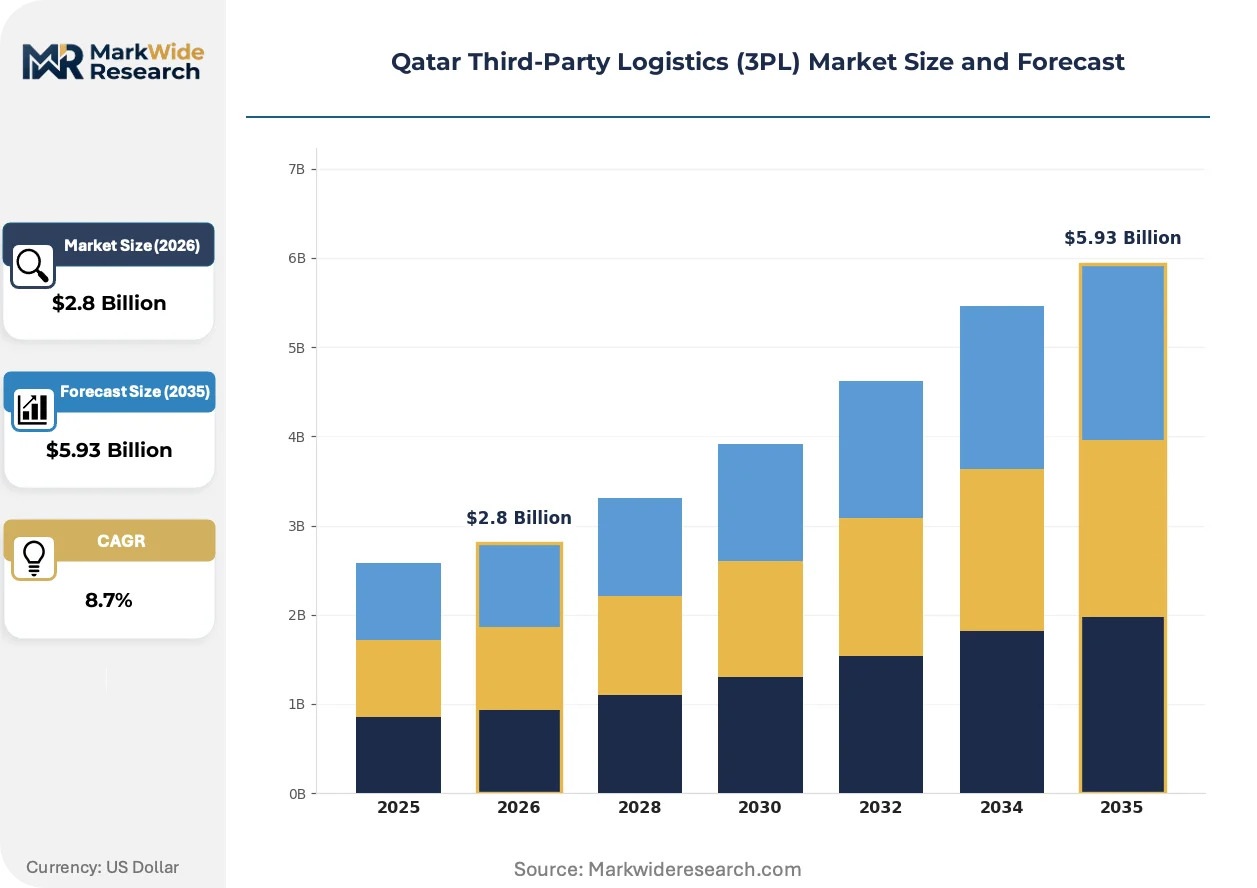
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Order Fulfillment, Freight Forwarding End User: Retail, E-commerce, Automotive, Healthcare Technology: Cloud-based Solutions, Warehouse Management Systems, Tracking Software, Data Analytics Distribution Channel: Direct, Online, Third-party, Freight Brokers |
| Companies Covered | Kuehne + Nagel, Maersk, Gulf Warehousing Company (GWC), CEVA Logistics, Falcon Express Services Qatar, Aramex, BDP International Qatar WLL, Links Shipping, DHL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Third-Party Logistics (3PL) Market Evolving Landscape
Digital infrastructure investments are compressing information asymmetries between shippers and logistics providers, while regulatory mandates are hardening compliance requirements that favor capitalized operators over asset-light intermediaries.
Blockchain-enabled documentation is overtaking paper-based customs workflows at Hamad Port and Doha's air cargo terminals. General Authority of Customs pre-arrival filing requirements are accelerating adoption among freight forwarders serving retail and healthcare importers. This technology is compressing clearance timelines from days to hours and reducing detention cost exposure for containerized cargo.
Ministry of Public Health cold-chain standards are mandating temperature logger integration and automated alert systems across pharmaceutical distribution networks. Facility retrofit requirements are disqualifying generalist warehouses from vaccine and biologics handling. Healthcare 3PL contracts are consolidating toward operators with certified GDP infrastructure in Doha Industrial Area and Mesaieed.
Shippers are unbundling transportation from warehousing contracts and awarding integrated fulfillment mandates to single providers. Retail and healthcare buyers are consolidating vendor relationships to reduce coordination overhead. This pattern is most pronounced among Doha-based e-commerce platforms and hospital procurement departments seeking unified service-level accountability.
Qatar Third-Party Logistics (3PL) Market Segmentation
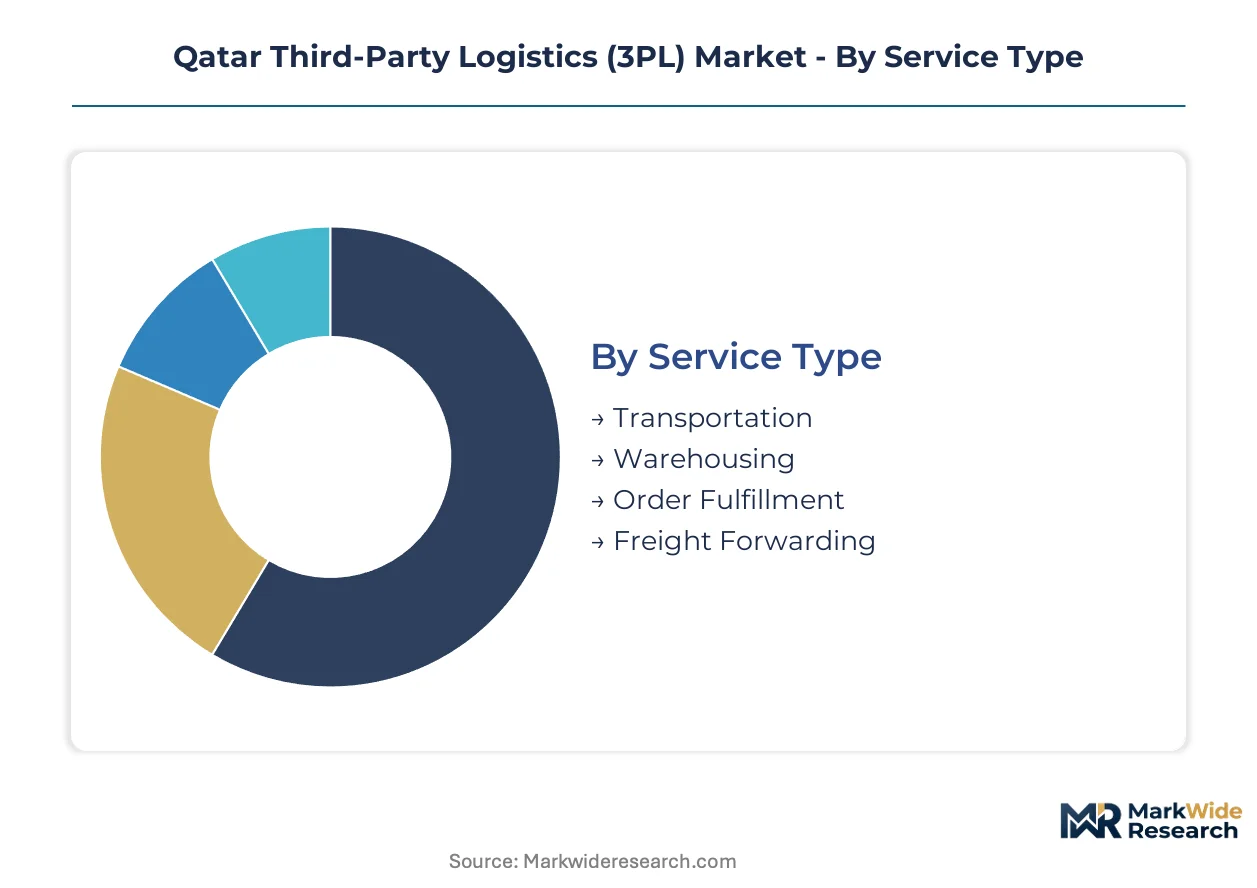
Qatar's 3PL segmentation reflects divergent margin profiles across service types, with cold-chain infrastructure commanding premium pricing while transportation services compete on asset utilization. End-user concentration in hydrocarbon-linked sectors creates volume stability, whereas healthcare and e-commerce segments drive technology upgrade cycles.
Service Type:
Transportation services anchor revenue volume through hydrocarbon and construction freight movements, while warehousing and fulfillment capture expanding margins from certified cold-chain mandates.
- Transportation:Fleet operations span containerized freight from Hamad Port to inland industrial zones, with diesel cost volatility compressing unit economics for ambient cargo movements across Mesaieed and Ras Laffan.
- Warehousing:Temperature-controlled facilities in Doha Industrial Area and Mesaieed carry pharmaceutical certification requirements from the Ministry of Public Health, elevating barrier to entry and lease rate premiums for GDP-compliant operators.
- Order Fulfillment:Same-day delivery mandates from Doha retail corridors are expanding contract values.
- Freight Forwarding:Pre-arrival documentation systems from the General Authority of Customs favor digitized intermediaries.
Mature deployment sits with Transportation. Newer deployment is concentrated in Order Fulfillment.
End User:
Healthcare and e-commerce end users are forcing capital-intensive infrastructure upgrades, while retail and automotive sustain baseline volume through established distribution networks.
- Healthcare:Ministry of Public Health biologics distribution tenders require GDP-certified cold chains, consolidating contracts toward operators with validated temperature monitoring and automated alert systems in Mesaieed facilities.
- E-commerce:Doha-based platforms are compressing delivery windows to same-day service, driving demand for micro-fulfillment nodes and real-time inventory visibility without proprietary warehouse investment.
- Retail:Traditional import-dependent merchants rely on bonded warehousing at Ras Laffan free zones.
- Automotive:Spare parts distribution centers cluster near Doha Industrial Area transport corridors.
Healthcare represents the fastest-growing trajectory. Retail maintains the largest contract base.
Technology:
Cloud-native platforms are displacing legacy warehouse management systems, while tracking software and analytics layers compete on integration depth with shipper ERP architectures.
- Cloud-based Solutions:Subscription models enable mid-tier operators to offer real-time inventory visibility without capital deployment into proprietary server infrastructure, accelerating adoption among healthcare and retail shippers.
- Warehouse Management Systems:Modernization cycles concentrate in pharmaceutical-certified facilities requiring temperature logger integration and automated compliance reporting for Ministry of Public Health audits.
- Tracking Software:GPS and RFID deployment expands across refrigerated transport fleets.
- Data Analytics:Demand forecasting tools penetrate e-commerce fulfillment operations.
Cloud-based Solutions are gaining share fastest. Warehouse Management Systems retain the deepest installed base.
Distribution Channel:
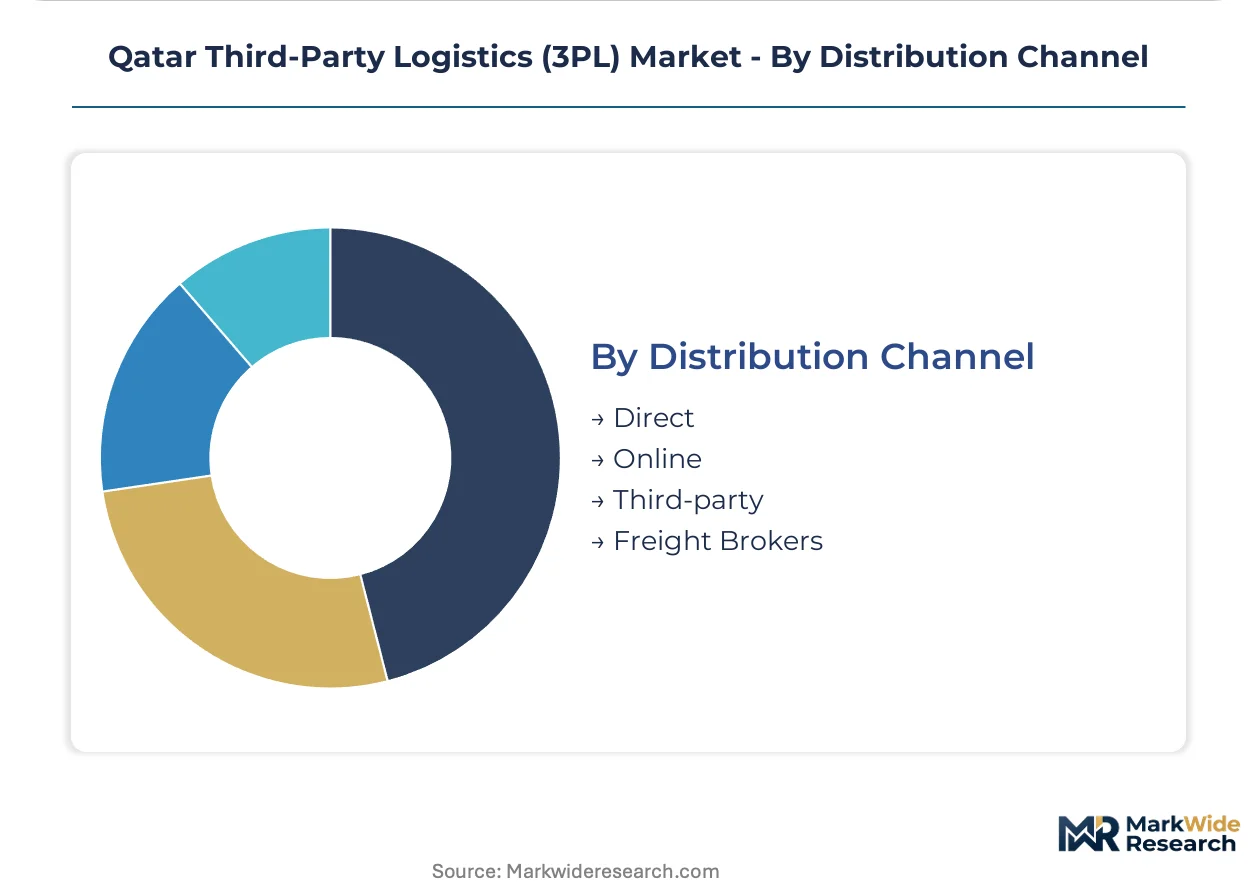
Direct contracting dominates large hydrocarbon and healthcare accounts, while freight brokers and online platforms fragment mid-market access.
- Direct:Energy majors and hospital procurement departments negotiate integrated service-level agreements spanning ocean freight through last-mile delivery, consolidating vendor relationships to reduce coordination overhead.
- Third-party:Intermediaries with Qatar Free Zones Authority joint venture status channel foreign capital into bonded logistics clusters at Ras Laffan, capturing captive demand from import-dependent manufacturers.
- Online:Digital freight marketplaces emerge for spot-rate container movements.
- Freight Brokers:Asset-light intermediaries compete on price for non-refrigerated construction materials.
Direct relationships dominate contract value. Third-party channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's North Field gas reserves anchor industrial logistics demand across the peninsula. Hydrocarbon-linked freight movements concentrate at Ras Laffan and Mesaieed. The Ministry of Public Health's cold-chain mandates are redistributing warehousing investment toward pharmaceutical-certified nodes in Doha Industrial Area.
Al Rayyan
Education City and healthcare cluster expansion are generating biologics distribution demand. The Ministry of Public Health enforces GDP compliance standards for pharmaceutical storage facilities. Cold-chain warehouses near Sidra Medical and Research Center are consolidating vaccine handling contracts.
Doha Industrial Area
E-commerce fulfillment velocity and automotive spare parts distribution are compressing order cycle times. The Qatar Free Zones Authority licensing framework channels foreign capital into bonded logistics clusters. Temperature-controlled facilities here carry pharmaceutical certification requirements that elevate lease rate premiums.
Mesaieed
Petrochemical export volumes and construction materials movements sustain heavy-lift freight demand. The General Authority of Customs mandates pre-arrival documentation that accelerates clearance timelines. Industrial zoned land constraints around the port are inflating ambient storage lease rates.
Ras Laffan
Energy sector construction cycles and project cargo specialization are generating oversized freight management demand. Qatar Free Zones Authority joint venture requirements shape foreign operator market access. Integrated warehousing clusters here capture captive demand from import-dependent manufacturers in the free zone.
Al Wakrah
Hamad Port expansion and deep-water container terminal capacity are reducing ocean-to-inland transit friction. The National Cyber Security Agency's developing cloud governance frameworks affect warehouse management system architecture decisions. Logistics providers here are deploying blockchain-enabled documentation to compress customs clearance timelines.
Qatar Third-Party Logistics (3PL) Market Competitive Landscape
Established operators occupy the premium infrastructure tier; emerging entrants pursue asset-light digital forwarding models. The market structures around capital-intensive cold-chain certification and technology-enabled visibility platforms. Three archetypes dominate: integrated container logistics providers, pharmaceutical-certified warehouse operators, and project cargo specialists. Competitive moves concentrate on facility certification timelines and cloud-native platform partnerships.
Among European-based integrated logistics providers, Kuehne + Nagel and Maersk occupy positions emphasizing ocean-to-warehouse control and container logistics integration. Gulf Warehousing Company anchors the domestic infrastructure tier as a Qatar-based limited liability company representing pharmaceutical-certified facility investment. These three exemplify the divergence between foreign capital deployment under free zone joint ventures and local operator dominance in Ministry of Public Health-regulated cold chains.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Maersk |
| Gulf Warehousing Company (GWC) |
| CEVA Logistics |
| Falcon Express Services Qatar |
| Aramex |
| BDP International Qatar WLL |
| Links Shipping |
| DHL |
| Others |
Value Network & Pricing Analysis
Diesel benchmark fluctuations from Platts Arab Gulf Gasoil cascade through Qatar's 3PL tiers, amplifying cost pass-through friction for refrigerated transport operators while compressing margins for ambient cargo specialists locked into fixed-rate contracts with hydrocarbon majors.
Pricing Analysis
Service bundling separates pharmaceutical-certified cold-chain providers from generalist warehouse operators, with GDP compliance validation and temperature monitoring included in premium contracts while standard freight forwarding remains unbundled. Three-tier pricing structure across premium certification, standard bonded warehousing, and economy construction materials transport dominates contract structures. Pricing pressure stems from diesel cost volatility eroding refrigerated transport unit economics across Mesaieed and Ras Laffan. Hospital procurement departments show lowest price sensitivity due to Ministry of Public Health mandate requirements, while construction materials shippers exhibit highest sensitivity and rapid supplier switching.
Supply Chain Analysis
Qatar Free Zones Authority joint venture requirements are channeling foreign capital into domestic logistics infrastructure, reshaping sourcing patterns for warehouse management systems and cold-chain equipment. Equipment and technology inputs draw from Germany, South Korea, and the United States for pharmaceutical-certified infrastructure. Supply chain risk centers on single-source vulnerability for specialized cold-chain technicians and GDP-certified facility auditors. Distribution runs through bonded clusters at Ras Laffan and Doha Industrial Area, with final-mile delivery concentrated in Doha retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial zoned land scarcity around Doha and Mesaieed props pricing power for incumbent facility operators, constraining new cold-chain capacity additions and extending lease rate premiums through the forecast horizon.
For Market Incumbents: Anticipate margin compression from cloud-native platform entrants offering real-time visibility without proprietary infrastructure investment, and respond by deepening pharmaceutical certification moats through accelerated GDP compliance investments in Doha Industrial Area facilities. Prioritize backward integration into refrigerated transport fleets to capture diesel cost pass-through control. For New Entrants and Emerging Players: Cloud-native warehouse management platforms offer a technology-first wedge into mid-market healthcare shippers seeking inventory visibility without capital deployment. Target e-commerce fulfillment nodes in Al Wakrah where Hamad Port expansion reduces ocean-to-inland transit friction. Pursue joint venture structures under Qatar Free Zones Authority licensing to access bonded logistics demand from import-dependent manufacturers. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical-certified facility operators in Mesaieed where Ministry of Public Health audit backlogs extend market entry timelines for competitors. Long-term viability hinges on cold-chain infrastructure scarcity persisting through healthcare logistics adoption. Monitor biologics distribution tender announcements from the Ministry of Public Health as inflection indicators for contract consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Facility Certification | GDP compliance investments at Gulf Warehousing Company facilities capture Ministry of Public Health vaccine handling contracts. |
| Cloud Platform Partnership | Real-time inventory visibility partnerships enable mid-tier operators to compete without proprietary server infrastructure. |
| Free Zone Joint Venture | Qatar Free Zones Authority licensing structures channel foreign capital into bonded warehousing clusters at Ras Laffan. |
| Refrigerated Fleet Expansion | Diesel cost pass-through control through captive transport assets protects margins across dispersed industrial zones. |
| Blockchain Documentation Deployment | General Authority of Customs pre-arrival filing compliance compresses clearance timelines from days to hours at Hamad Port. |
Research Methodology
Multi-period observation of diesel price indices, industrial lease rates, and pharmaceutical certification timelines anchored the trend analysis, supplemented by interviews with cold-chain operations directors, hospital procurement managers, Qatar Free Zones Authority licensing officers, and customs brokerage heads. Secondary validation drew from General Authority of Customs trade statistics, Ministry of Public Health regulatory filings, Qatar Central Bank infrastructure investment disclosures, and bonded logistics cluster development records. Bottom-up facility capacity assessments and top-down macroeconomic indicators were triangulated to establish market sizing.
Input-output matrices modeled service type, end-user vertical, technology deployment, and distribution channel interactions across the projection horizon. CAGRs were derived from segmented demand forecasting incorporating healthcare logistics adoption curves, e-commerce penetration trajectories, and hydrocarbon construction cycle timing. Forecast inputs included Ministry of Public Health cold-chain mandate enforcement schedules and Hamad Port capacity expansion trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruptions to regional trade flows, abrupt shifts in Qatar Free Zones Authority foreign ownership regulations, and technological obsolescence of warehouse management system architectures. Forecasts reflect documented assumptions about regulatory enforcement continuity and infrastructure investment pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
South America Freight and Logistics Market