
 North America Courier, Express, and Parcel (CEP) Market | 2026-2036
North America Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Courier, Express, and Parcel (CEP) Market Insights
Last-mile delivery margins is narrowing as platform operators absorb fulfillment costs previously passed to merchants. United Parcel Service (UPS) leverages its integrated ground-air network to sustain density economics in suburban zones. FedEx anchors its position through specialized healthcare logistics capabilities with temperature-validated handling. Purolator dominates Canadian cross-border flows with customs-bonded infrastructure along the Windsor-Detroit corridor.
Courier, Express, and Parcel services constitute time-definite logistics solutions encompassing document envelopes, parcel shipments, and freight consignments transported through integrated ground, air, and intermodal networks with guaranteed delivery windows. These services functionally bridge inventory velocity requirements with end-consumer accessibility across distributed supply chains. Same-day delivery commands premium rate structures while standard delivery retains volume leadership across enterprise accounts. Ground transportation anchors cost-efficient parcel movement, though air freight sustains express tier profitability for time-critical healthcare and electronics shipments.
The US Federal Motor Carrier Safety Administration governs commercial driver eligibility and hours-of-service limits directly constraining fleet capacity expansion across interstate routes. Transport Canada enforces parallel commercial vehicle operator regulations affecting cross-border fleet interoperability and safety certification reciprocity. Stakeholders must monitor evolving emissions standards from the US EPA and Environment and Climate Change Canada as zero-emission vehicle mandates penetrate medium-duty delivery fleet procurement cycles.
Market Dynamics
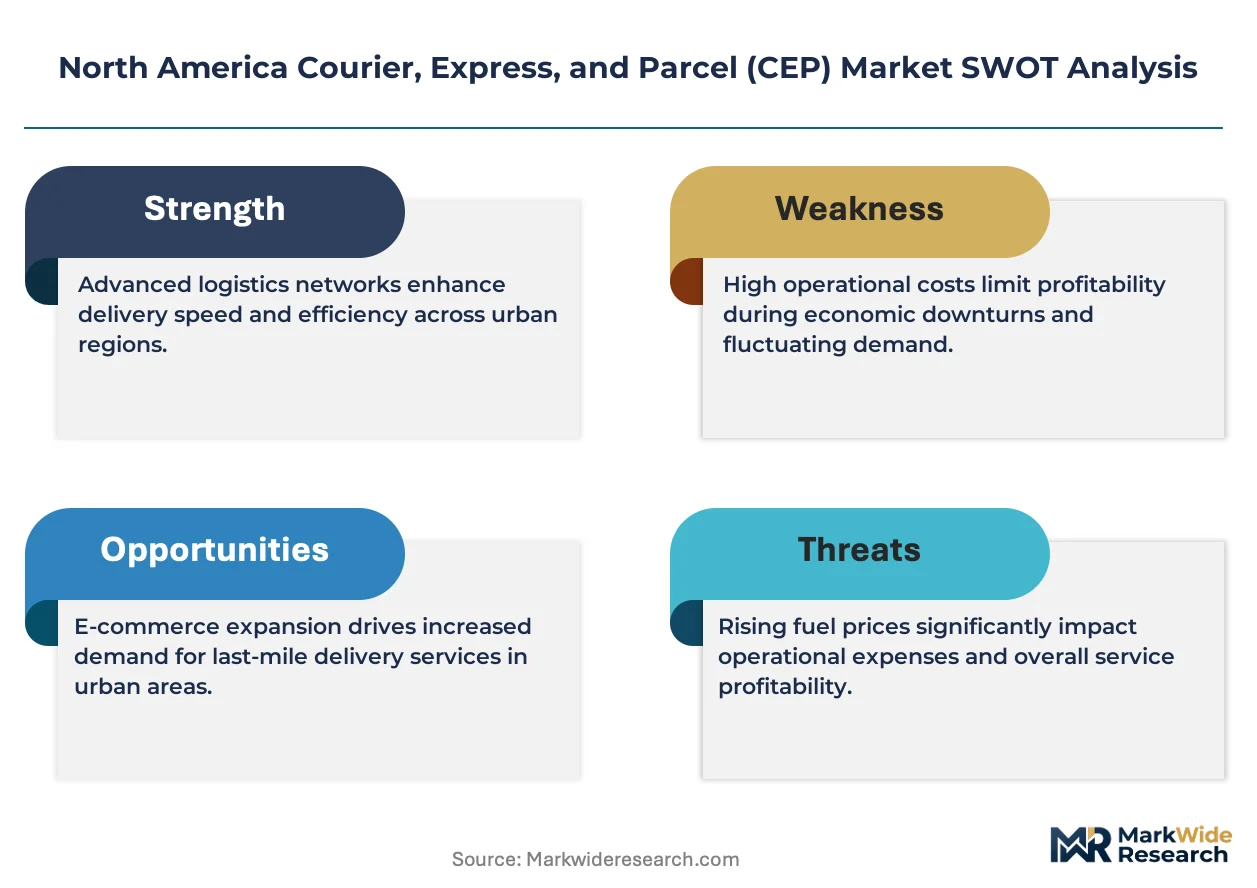
E-commerce fulfillment networks are compressing delivery windows from two-day to same-day service, forcing asset-heavy reinvestment in urban micro-fulfillment nodes and dynamic route optimization systems across the continent.
Growth Catalysts
- Cross-border manufacturing integration:Ontario automotive and electronics clusters ship components through Windsor-Detroit bonded corridors, generating predictable parcel density for integrated ground networks.
- EPA Phase 3 greenhouse gas standards:Medium-duty fleet electrification mandates accelerate zero-emission vehicle procurement, creating aftermarket service opportunities for charging infrastructure and battery logistics.
- Healthcare cold-chain validation:Temperature-sensitive biologics and cell therapies require express tier handling, expanding premium service attach rates across pharmaceutical distribution.
Market Restraints
- Driver availability constraints:FMCSA hours-of-service regulations cap commercial vehicle utilization rates, limiting fleet capacity expansion during peak seasonal demand windows.
- Fuel cost volatility:Diesel price fluctuations directly impact ground transportation margins, compressing earnings on standard delivery tiers where rate competition is intense.
- Customs processing friction:US CBP and CBSA inspection protocols create unpredictable dwell times at border crossings, degrading service reliability for just-in-time manufacturing supply chains.
Strategic Opportunities
- Mexican nearshoring corridors:Manufacturing relocation from Asia to Nuevo León and Baja California generates new northbound parcel flows requiring customs-bonded infrastructure investment.
- Reverse logistics monetization:E-commerce return volumes exceed forward shipment rates in apparel and electronics categories, creating dedicated consolidation and refurbishment service lines.
- Carbon accounting integration:Scope 3 emissions disclosure requirements under evolving EPA and Environment and Climate Change Canada frameworks position low-carbon delivery as a differentiated procurement criterion.
Industry Challenges
- Last-mile labor retention:Driver turnover rates in urban delivery operations exceed transportation industry averages, requiring continuous recruitment investment and route density optimization to maintain service levels.
- Legacy warehouse management system integration:Enterprise shippers operate fragmented technology stacks that resist real-time API connectivity with carrier visibility platforms, delaying automated exception management deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Courier, Express, and Parcel (CEP) Market |
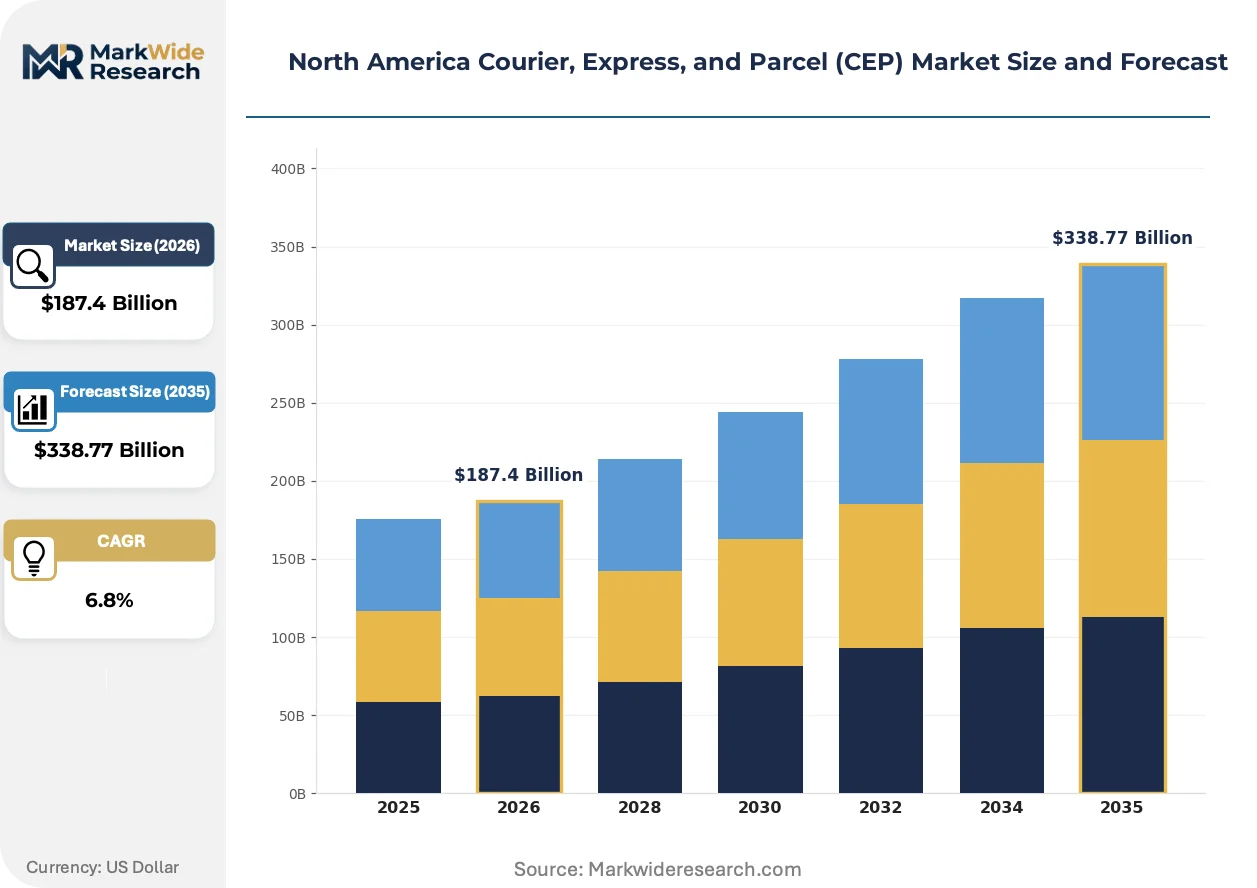
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, International Shipping End User: E-commerce, Retail, Healthcare, Manufacturing Delivery Mode: Air, Ground, Ocean, Intermodal Packaging Type: Boxed, Padded Envelopes, Crates, Customized Packaging |
| Companies Covered | United Parcel Service (UPS), FedEx, DHL Group, United States Postal Service (USPS), OnTrac, Canada Post Corporation, TFI International, Purolator, Aramex, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Courier, Express, and Parcel (CEP) Market Trends and Innovations
Operational technology investment is pivoting from tracking visibility toward predictive intervention, with machine learning models now preempting delivery failures before they trigger customer service escalations.
Dynamic route optimization software is digitizing dispatch decisions across suburban delivery zones. Regional carriers and dedicated fleet operators deploy these systems to compress miles per stop and improve on-time performance. The technology is digitizing how density economics are calculated, enabling real-time resequencing that protects margin structures on low-yield residential routes.
The US EPA's Clean Trucks Plan and parallel Environment and Climate Change Canada regulations mandate progressive NOx and particulate emissions reductions for medium-duty vehicles. Fleet operators must phase out diesel platforms or install costly after-treatment systems. California's Advanced Clean Trucks rule accelerates zero-emission vehicle adoption most aggressively, with CARB compliance timelines forcing early capital deployment ahead of federal mandates.
Shippers now unbundle transportation procurement from warehousing contracts, selecting carriers through spot-market platforms for non-contract lanes. This fragmentation pressures annual rate negotiations and compresses contract durations. Retail and direct-to-consumer verticals exhibit this behavior most prominently, with seasonal volume spikes driving preference for flexible capacity access over committed network relationships.
North America Courier, Express, and Parcel (CEP) Market Segmentation
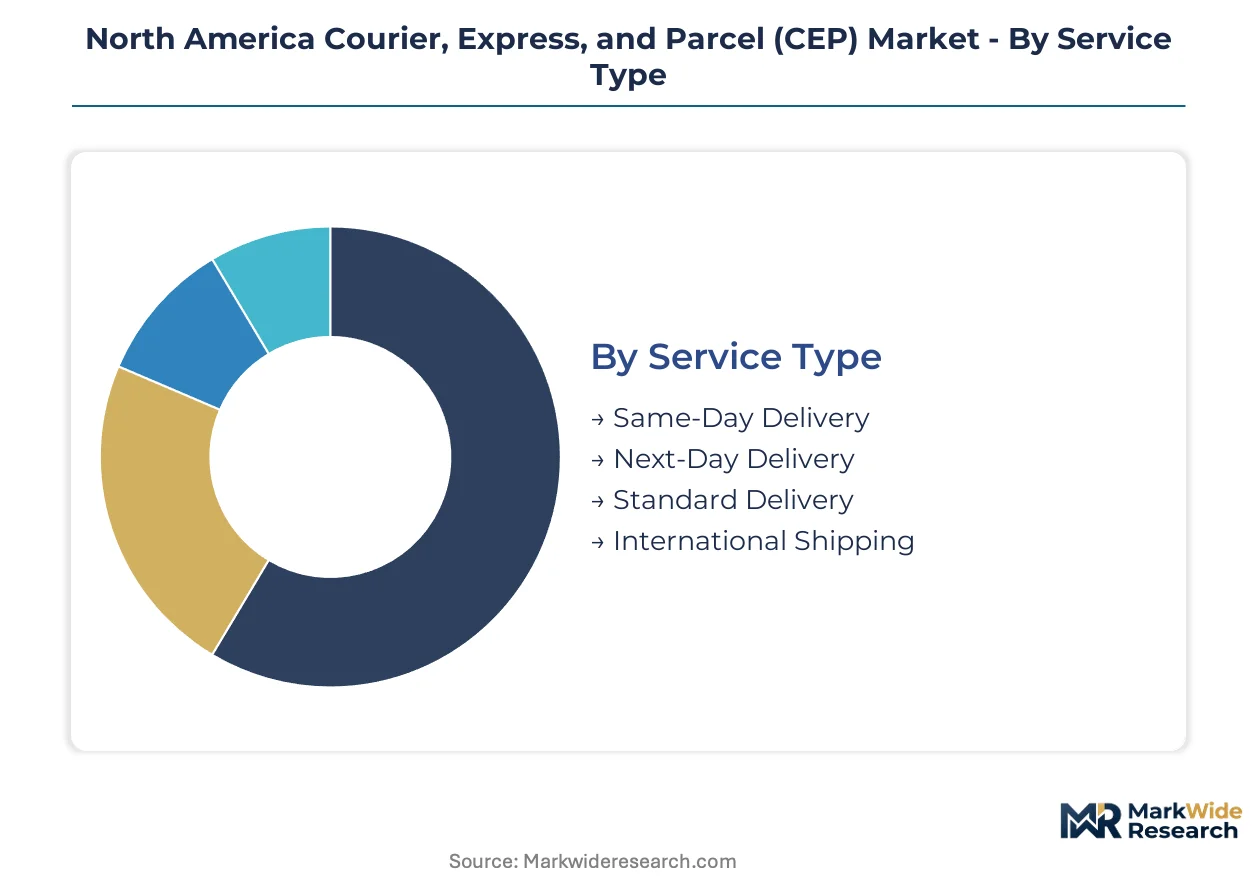
CEP market segmentation reveals how service tiers, customer verticals, and infrastructure modes allocate capital across heterogeneous demand profiles. Distinct operational economics govern each slice, from premium healthcare cold-chain handling to bulk retail ground distribution. Understanding these boundaries informs network design and margin protection strategies.
Service Type:
Mature express tiers coexist with emerging same-day infrastructure as e-commerce compresses delivery windows across North American corridors.
- Same-Day Delivery:Ultra-expedited urban fulfillment requiring micro-fulfillment nodes and dynamic dispatch algorithms. Demand concentrates in dense metropolitan zones—New York, Los Angeles, Toronto—where consumer willingness to absorb premium rates supports dedicated courier fleets.
- Next-Day Delivery:Integrated ground-air network product with guaranteed morning or afternoon windows. E-commerce subscriptions and enterprise procurement contracts anchor volume in this tier, with FedEx and UPS density economics protecting margins.
- Standard Delivery:Cost-optimized ground transportation with 3-5 day windows. Rural and suburban residential delivery dominates this segment, where route density challenges compress carrier profitability.
- International Shipping:Cross-border express and deferred products requiring customs-bonded infrastructure. Ontario-Midwest manufacturing corridors and Mexican nearshoring lanes generate predictable northbound parcel density.
Standard Delivery retains volume leadership; Same-Day Delivery holds the steepest expansion curve.
End User:
Customer-type segmentation maps divergent service requirements onto specialized handling protocols and pricing structures.
- E-commerce:Platform-driven fulfillment with high return rates and residential delivery density challenges. Seasonal volume spikes force flexible capacity procurement through spot-market platforms rather than committed network relationships.
- Retail:Omnichannel replenishment and direct-to-consumer shipments. Store-based fulfillment and ship-from-store models reshape last-mile economics as merchants absorb fulfillment costs previously passed to consumers.
- Healthcare:Temperature-validated cold-chain logistics for biologics, cell therapies, and pharmaceutical distribution. FDA and Health Canada compliance requirements mandate express-tier handling with documented chain-of-custody protocols.
- Manufacturing:Just-in-time component delivery and spare parts logistics. Automotive and electronics clusters in Ontario and the US Midwest generate predictable cross-border parcel flows through bonded Windsor-Detroit corridors.
E-commerce commands the largest revenue pool; Healthcare posts the most aggressive expansion trajectory.
Delivery Mode:
Modal selection reflects the cost-velocity tradeoff governing time-definite logistics across continental distances.
- Air:Express-tier premium product sustaining profitability on time-critical healthcare and electronics shipments. EPA emissions standards and airport slot constraints limit capacity expansion.
- Ground:Cost-efficient parcel movement anchoring standard delivery economics. FMCSA hours-of-service regulations cap commercial vehicle utilization, constraining fleet capacity during peak seasonal windows.
- Ocean:Deferred international freight for non-urgent bulk shipments. Limited relevance in time-definite CEP markets outside international deferred tiers.
- Intermodal:Rail-truck combinations optimizing long-haul density with final-mile flexibility. Cross-border manufacturing corridors leverage intermodal for predictable cost structures.
Ground transportation anchors volume leadership; Air freight maintains the steepest margin profile.
Packaging Type:
Packaging specifications align protective requirements with dimensional weight pricing and automated sortation compatibility.
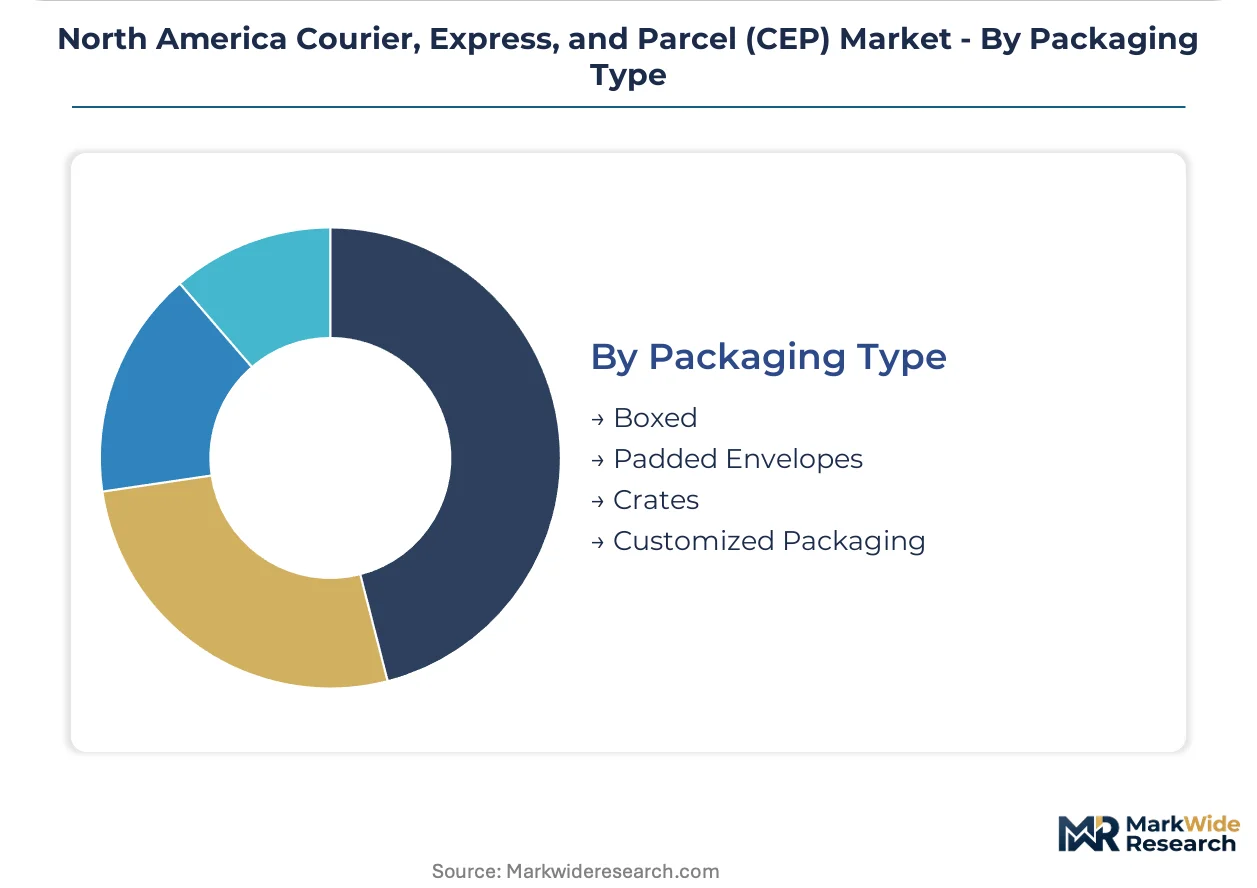
- Boxed:Standard corrugated containers dominating general merchandise and electronics fulfillment. Automated hub sortation systems optimize for rectangular dimensions.
- Padded Envelopes:Lightweight flexible packaging for documents and soft goods. Minimal dimensional weight penalties support cost-efficient small-parcel economics.
- Crates:Rigid protective containers for high-value or fragile industrial shipments. Limited volume but premium rate structures.
- Customized Packaging:Brand-specific or product-optimized designs with embedded tracking and temperature validation. Healthcare and luxury verticals drive adoption.
Boxed packaging retains volume leadership; Customized Packaging gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive standard delivery dominates rural and suburban zones across the continent, while premium express tiers command inelastic demand from healthcare and automotive manufacturing clusters in dense metropolitan corridors.
United States
E-commerce subscription growth and just-in-time manufacturing replenishment drive parcel density in Midwestern distribution hubs. The Federal Motor Carrier Safety Administration enforces hours-of-service limits constraining fleet utilization during peak seasonal windows. The Detroit-Windsor corridor anchors cross-border automotive component flows, with Michigan and Ohio distribution centers processing bonded shipments from Ontario manufacturing clusters.
Canada
Ontario's automotive and electronics manufacturing clusters generate predictable northbound parcel volumes through customs-bonded infrastructure. Transport Canada mandates commercial vehicle operator safety certification reciprocity affecting cross-border fleet interoperability. The Greater Toronto Area concentrates micro-fulfillment investment as retailers compress delivery windows for dense urban populations.
Mexico
Nearshoring relocation to Nuevo León and Baja California generates new express parcel flows requiring customs-bonded infrastructure investment. Mexico's Secretariat of Economy oversees trade facilitation programs accelerating cross-border manufacturing integration. Monterrey industrial parks attract automotive and electronics assembly, creating dedicated logistics corridors linking to Texas distribution hubs.
North America Courier, Express, and Parcel (CEP) Market Competitive Landscape
Integrated network operators and postal incumbents split the market between asset-heavy density economics and last-mile universal service obligations. The structure consolidates around three archetypes: integrated ground-air carriers with hub-and-spoke infrastructure, national postal services with regulatory service mandates, and regional specialists with corridor-specific customs capabilities. Dominant competitive moves include fleet electrification capital deployment and dynamic route optimization technology licensing.
Within the integrated carrier tier, United Parcel Service and FedEx exemplify network density strategies, while Purolator occupies a position representing Canadian cross-border specialization. These anchors illustrate how strategic archetypes align with geographic coverage requirements and customs-bonded infrastructure investment.
| Leading Market Players |
|---|
| United Parcel Service (UPS) |
| FedEx |
| DHL Group |
| United States Postal Service (USPS) |
| OnTrac |
| Canada Post Corporation |
| TFI International |
| Purolator |
| Aramex |
| Others |
Pricing and Supply Chain Analysis
Windsor-Detroit customs-bonded corridors concentrate cross-border parcel capacity, granting Purolator and integrated carriers pricing leverage over Ontario-Midwest manufacturing flows that smaller regional operators cannot match. The US EPA's Clean Trucks Plan and Transport Canada parallel mandates feed equipment procurement costs into rate structures, while FMCSA hours-of-service limits constrain fleet utilization during peak windows.
Pricing Analysis
After-sales service contracts and extended logistics agreements now generate lifetime value exceeding initial shipment margins. Three-tier pricing structure across premium express, standard ground, and economy deferred tiers stratifies around delivery velocity and temperature-validation requirements. Cost compression in standard ground tiers intensifies as e-commerce platforms absorb fulfillment costs previously passed to merchants, making healthcare and automotive manufacturing segments least price-sensitive due to just-in-time reliability demands.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk planning for cross-border CEP operators. Fleet procurement draws from US, Mexican, and Canadian manufacturing clusters for medium-duty electric vehicles and charging infrastructure. Single-source vulnerability concentrates in lithium-ion battery cell supply for zero-emission fleet conversion. Distribution runs through hub-and-spoke sortation facilities anchored by UPS and FedEx integrated networks, with last-mile density economics determining rural route profitability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America CEP market functions as a service-attach opportunity where reverse logistics and carbon accounting services expand faster than base transportation revenue. Cold-chain validation and dynamic route optimization subscriptions represent recurring-revenue layers outpacing hardware-centric fleet growth.
For Market Incumbents:Harden cross-border customs-bonded infrastructure along Windsor-Detroit and emerging Nuevo León-Texas corridors against specialized regional challengers. Invest in zero-emission fleet conversion ahead of EPA Phase 3 mandates to capture aftermarket charging service revenue. Vertical integration into battery logistics and refurbishment operations protects margin structures as electrification accelerates.
For New Entrants and Emerging Players:Mid-market healthcare cold-chain corridors in secondary US metropolitan zones represent the most penetrable entry point for temperature-validated express services. Mexican nearshoring logistics to Nuevo León and Baja California industrial parks offers white-space expansion with lower incumbent density. Go-to-market positioning through carbon accounting integration addresses Scope 3 disclosure requirements under evolving EPA frameworks.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized cold-chain operators with FDA-validated handling protocols and established pharmaceutical relationships. Long-term viability across the analysis window rests on fleet electrification readiness and dynamic routing software deployment. Monitor EPA enforcement timelines and Transport Canada reciprocity agreements as inflection indicators for capital deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Deployment | EPA Phase 3 compliance creates aftermarket service revenue in charging infrastructure. |
| Customs-Bonded Infrastructure Expansion | Windsor-Detroit corridor density protects cross-border pricing power against regional entrants. |
| Dynamic Route Optimization Licensing | Machine learning dispatch systems compress miles per stop in low-yield residential zones. |
| Reverse Logistics Service Launch | E-commerce return volumes exceed forward shipments in apparel and electronics categories. |
| Cold-Chain Validation Certification | FDA and Health Canada compliance mandates anchor premium healthcare logistics margins. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Fleet operations directors, customs brokerage managers, pharmaceutical logistics coordinators, and e-commerce fulfillment executives provided operational perspective. Secondary sources include FMCSA enforcement data, EPA emissions filings, Transport Canada safety certifications, and cross-border trade statistics. Bottom-up parcel volume modeling and top-down macroeconomic triangulation reconcile demand estimates.
Calibration against historical fleet utilization rates and e-commerce penetration benchmarks shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service tier velocity, end-use vertical requirements, delivery mode economics, and packaging type handling complexity. CAGRs derive from trend extrapolation adjusted for regulatory phase-in schedules and fleet replacement cycles. Forecast inputs incorporate EPA Phase 3 adoption curves and Mexican nearshoring investment flows.
Practitioners should monitor FMCSA hours-of-service enforcement actions, EPA zero-emission vehicle mandate acceleration, and US-Mexico-Canada Agreement customs protocol revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Global Drone Logistics and Transportation Market