

End-to-End Multimodal Shipment Visibility Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
End-to-End Multimodal Shipment Visibility Platforms Market Insights
Germany is tilting toward deeper digital infrastructure for freight corridors linking the Rhine-Alpine and North Sea-Baltic TEN-T networks. project44 leverages its carrier connectivity density to sustain API-first integration across European road-rail hubs. FourKites anchors its competitive position through proprietary machine-learning ETA engines that specialize in ocean-container handoffs at Hamburg and Bremerhaven.
End-to-end multimodal shipment visibility platforms constitute software architectures that ingest telemetry from IoT sensors, EDI feeds, AIS maritime signals, and telematics gateways to render unified location and condition data across transport modes, typically processing updates at sub-five-minute intervals for high-velocity decision support. These systems serve primarily to compress dwell times, reduce safety-stock buffers, and automate exception workflows across complex international supply chains. Cloud-based deployment leads solution delivery due to lower integration friction and faster carrier onboarding cycles, while predictive analytics commands widening budget allocation as shippers prioritize arrival-time accuracy over retrospective tracking. Cargo condition monitoring remains comparatively nascent but carries concentrated margin pools in pharmaceutical and perishable verticals where temperature-excursion liability costs escalate.
The EU AI Act and GDPR impose algorithmic transparency and data-localization obligations on platform providers processing carrier and shipper information across member states, directly elevating compliance costs for predictive routing models. ISO 28000 supply-chain security standards and the IMO's maritime cyber-risk framework further condition product roadmaps, particularly for platforms managing ocean-air intermodal handoffs. Stakeholders must weigh whether to build sovereign data-residency architectures or accept third-country transfer risk as regulatory fragmentation between Brussels and national capitals intensifies.
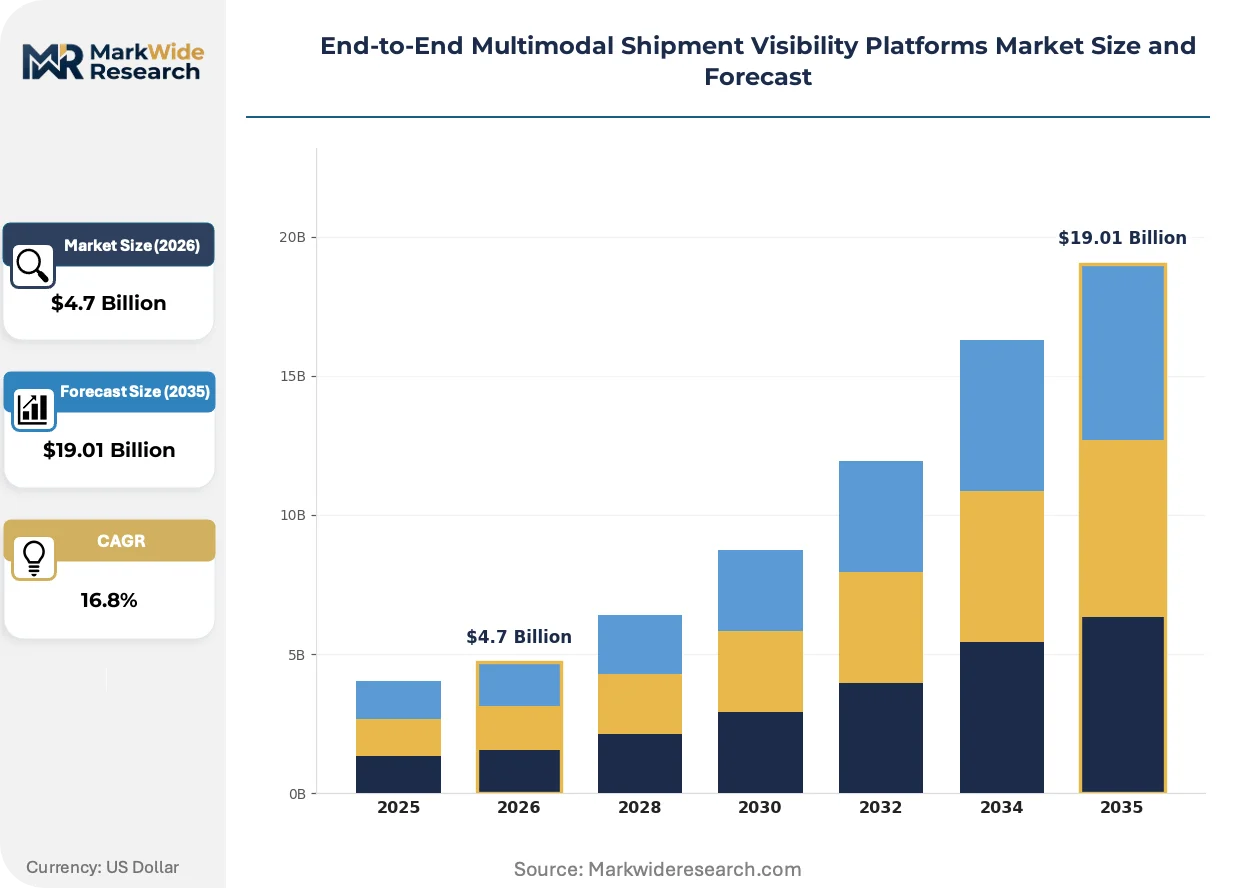
Market Dynamics
EU CSRD emissions-reporting mandates and the AI Act's algorithmic-transparency requirements are forcing platform providers to rearchitect data pipelines and predictive models simultaneously, compressing product-development cycles while elevating compliance spend.
Growth Catalysts
- Rhine-Alpine corridor digitalization:Germany's automotive and chemical shippers are mandating real-time multimodal orchestration across road-rail hubs, pulling visibility platform spend into core logistics budgets.
- EU Green Deal freight mandates:Emissions-tracking requirements for cross-border freight are converting retrospective reporting tools into live decision-support systems.
- Telematics gateway proliferation:IoT sensor density on European rolling stock and maritime containers is collapsing data-acquisition costs for multimodal ETA engines.
Market Restraints
- GDPR data-localization friction:Algorithmic-transparency requirements under the EU AI Act are fragmenting cloud architectures and elevating engineering overhead for predictive-routing models.
- Carrier EDI heterogeneity:Legacy message standards across European road operators create integration bottlenecks that prolong onboarding cycles.
- Maritime cyber-risk compliance:IMO framework obligations for ocean-air handoffs are conditioning product roadmaps and delaying feature releases.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-excursion liability costs in perishable verticals are opening premium-margin pools for cargo-condition monitoring modules.
- North Sea-Baltic TEN-T integration:Digital freight corridors linking Hamburg to Baltic ports remain underpenetrated by unified visibility architectures.
- ISO 28000 security certification:Supply-chain security standards are creating procurement preference shifts among defense and aerospace shippers.
Industry Challenges
- Machine-learning engineering scarcity:Specialized talent for ETA engine development concentrates in Hamburg and Munich, elevating compensation costs.
- Legacy TMS integration complexity:ERP backbone heterogeneity among German mid-market manufacturers prolongs implementation timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End-to-End Multimodal Shipment Visibility Platforms Market Trends and Innovations
Real-time data fusion architectures are compressing decision latencies across European freight networks. Platform providers are racing to unify disparate telemetry streams into actionable workflows.
Digital twin architectures for container movements are collapsing the latency between physical handoffs and system-of-record updates. Automotive shippers in Stuttgart and Wolfsburg are deploying these models to synchronize just-in-sequence production with vessel arrivals. The technology is collapsing safety-stock buffers by enabling sub-hour replanning cycles.
CSRD scope-3 emissions-reporting mandates are forcing granular carbon-accounting modules into visibility platforms. German chemical distributors must now attribute emissions to specific multimodal legs. The regulation is most acute for Rotterdam-Hamburg corridor flows, where shippers are pre-allocating IT budgets to compliance tooling.
Consolidated procurement of visibility services is displacing point-solution contracting. Large European retailers are bundling ocean, road, and rail tracking under single-platform agreements. This concentration is most visible in Benelux distribution hubs, where procurement teams are retiring legacy vessel-tracking contracts.
End-to-End Multimodal Shipment Visibility Platforms Market Segmentation
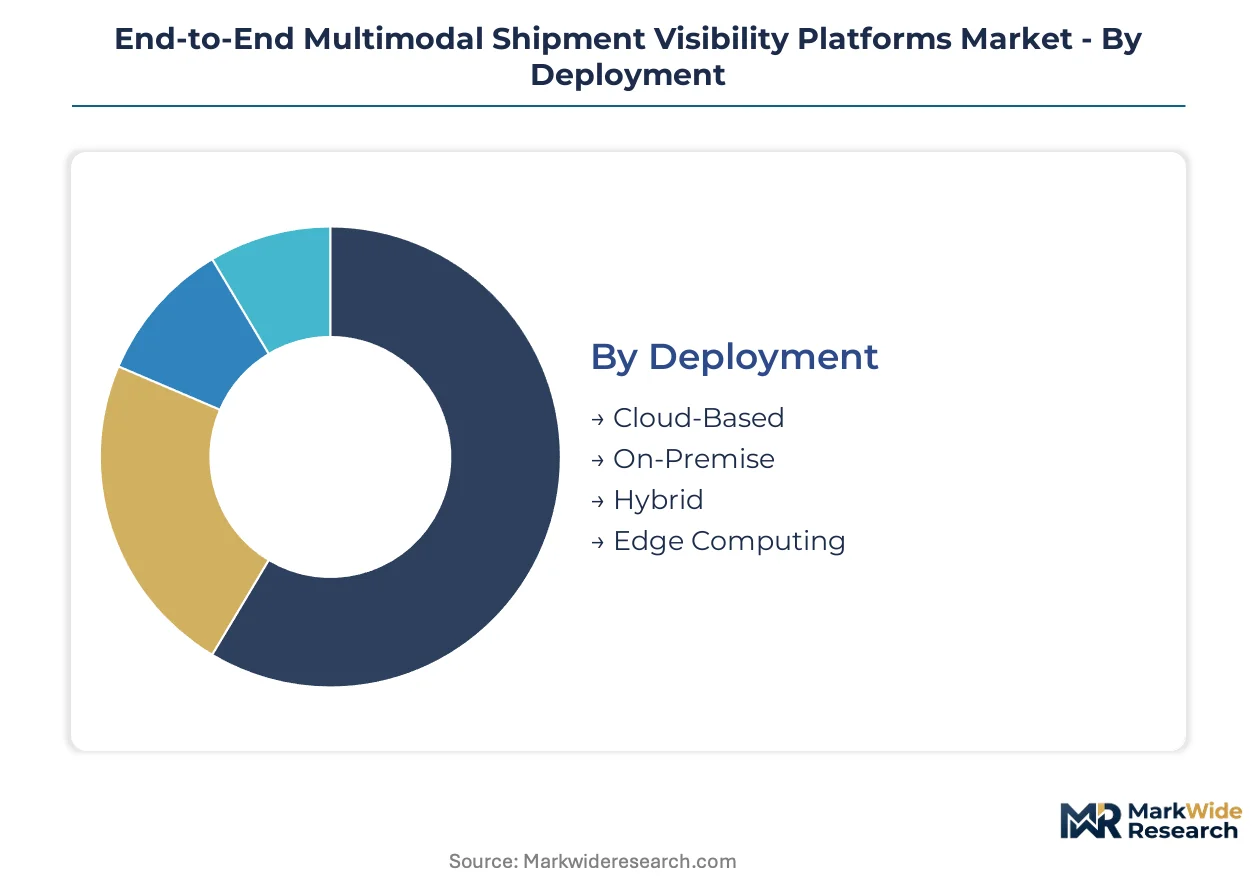
Platform architecture choices determine integration velocity and compliance posture across European freight networks. Deployment mode, solution depth, use case intensity, and end-user operational complexity collectively shape procurement decisions and vendor pricing power.
Deployment:
Cost tier determines infrastructure ownership trade-offs and carrier onboarding friction.
- Cloud-Based:Multi-tenant architectures eliminate server procurement cycles and compress implementation timelines to weeks rather than quarters. German automotive shippers favor this model for rapid scaling across Rhine-Alpine corridor hubs, though GDPR data-residency requirements are forcing providers to maintain EU-sovereign instances.
- On-Premise:Dedicated hardware installations serve defense contractors and aerospace manufacturers subject to ISO 28000 supply-chain security mandates. Hamburg-based chemical distributors deploy these configurations to satisfy audit requirements for sensitive cargo documentation.
- Hybrid:Split architectures isolate predictive analytics workloads on private infrastructure while routing carrier APIs through public cloud gateways. This configuration dominates among mid-market manufacturers balancing compliance with cost discipline.
- Edge Computing:Localized processing nodes at port terminals and rail yards enable sub-second anomaly detection for temperature-sensitive pharmaceuticals. Rotterdam-Hamburg corridor deployments are expanding fastest here.
Cloud-Based commands the established base. The steepest expansion runs through Edge Computing.
Solution Type:
Application depth separates retrospective reporting from predictive decision support.
- Real-Time Tracking:Unified location rendering across road, rail, and ocean modes via fused EDI, AIS, and telematics feeds. Benelux retailers mandate this capability for vendor scorecarding, pulling spend from legacy vessel-only contracts.
- Predictive Analytics:Machine-learning ETA engines trained on Hamburg and Bremerhaven container handoffs compress safety-stock buffers for just-in-sequence manufacturing. EU AI Act algorithmic-transparency rules are elevating engineering overhead for model explainability.
- Route Optimization:Dynamic replanning modules respond to port congestion and rail scheduling disruptions. Stuttgart automotive clusters deploy these tools to synchronize inbound parts flows with assembly line takt times.
- Exception Management:Automated workflow triggers for dwell-time violations and temperature excursions. Pharmaceutical distributors in Munich prioritize this capability to limit liability exposure.
- Cargo Condition Monitoring:IoT sensor integration for temperature, humidity, and shock telemetry. Perishable verticals in the Netherlands generate premium margins here despite smaller addressable volume.
Real-Time Tracking commands the established base. Predictive Analytics is gaining share fastest.
Use Case:
Operational intensity and liability exposure segment platform configuration requirements.
- Last Mile Delivery:Urban congestion algorithms and recipient notification systems dominate e-commerce fulfillment specifications. Dense parcel networks in the Netherlands and Belgium drive standardization here.
- Cold Chain Monitoring:Continuous temperature logging with excursion alerting for pharmaceuticals and fresh produce. German chemical distributors face acute CSRD scope-3 emissions attribution requirements for refrigerated transport legs.
- High-Value Freight:Security-sealed container tracking with geofencing and unauthorized-access alerts. Aerospace and precision manufacturing clusters in Bavaria concentrate demand.
- Bulk Cargo:Vessel hold and rail car volume monitoring for agricultural and mineral commodities. North Sea-Baltic TEN-T corridor flows show rising platform penetration.
- Reverse Logistics:Return authorization and refurbishment routing for electronics and automotive parts. Circular economy mandates in France and Germany are accelerating adoption.
Last Mile Delivery commands the established base. Cold Chain Monitoring is climbing the fastest.
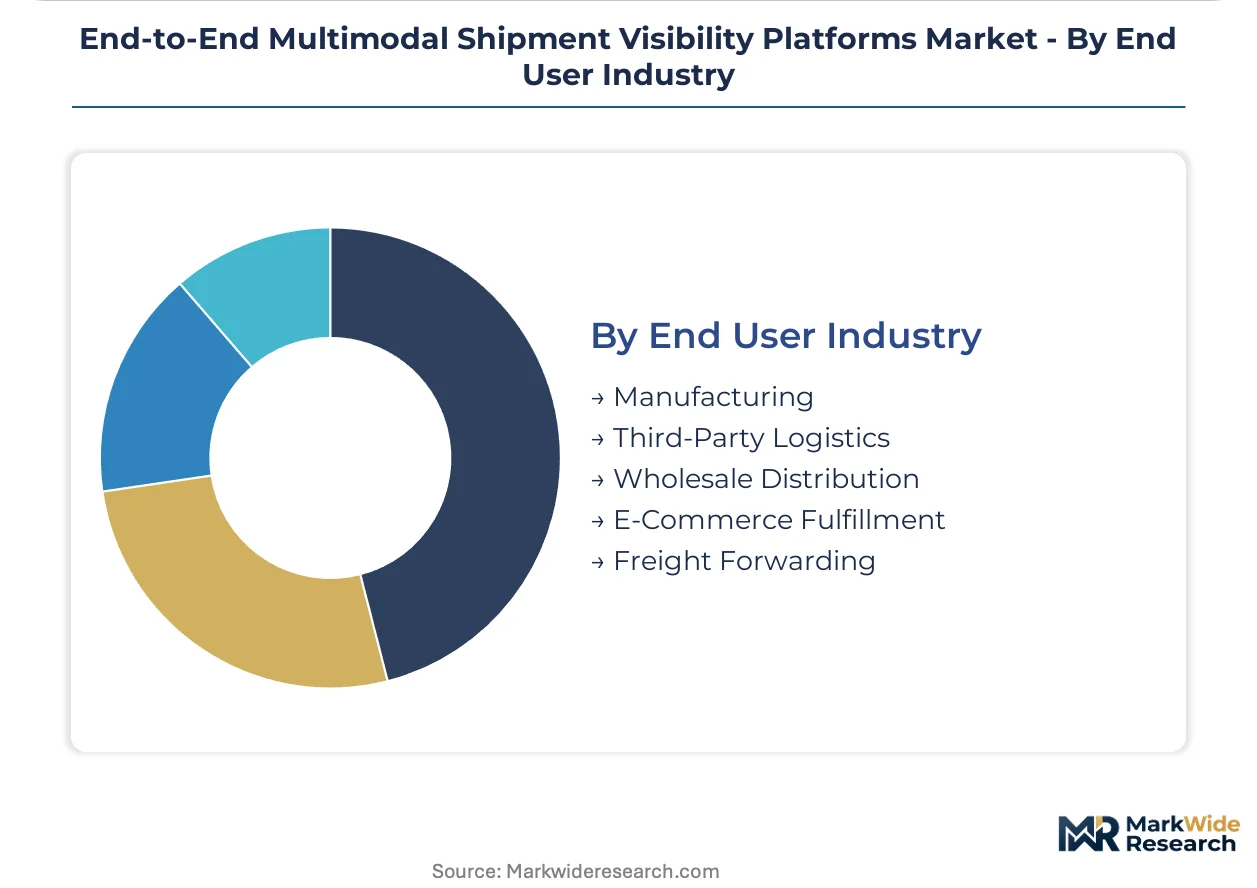
End User Industry:
Customer type shapes integration complexity and procurement centralization.
- Manufacturing:ERP backbone heterogeneity among German mid-market producers prolongs implementation timelines. Automotive OEMs in Wolfsburg and Stuttgart drive the most sophisticated multimodal orchestration requirements.
- Third-Party Logistics:Carrier connectivity density determines competitive position. Providers serving Rhine-Alpine road-rail hubs are consolidating visibility spend into single-platform agreements.
- Wholesale Distribution:Inventory turnover velocity and cross-dock synchronization priorities. Chemical distributors in the Rotterdam-Hamburg corridor face intensifying emissions-reporting obligations.
- E-Commerce Fulfillment:Consumer delivery promise accuracy and returns processing scale. Benelux distribution centers are retiring point-solution tracking contracts in favor of unified architectures.
- Freight Forwarding:Ocean-air intermodal handoff coordination and customs documentation integration. IMO maritime cyber-risk compliance is conditioning product roadmaps for this segment.
Third-Party Logistics commands the established base. E-Commerce Fulfillment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent clusters in Hamburg, Chicago, and Singapore, with carrier API density highest along the Rhine-Alpine and North American Midwest freight corridors. Regulatory divergence between Brussels, Washington, and Beijing is fragmenting cloud architectures and elevating compliance spend for predictive-routing models.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate real-time multimodal orchestration for just-in-sequence manufacturing, pulling visibility platform spend into core logistics budgets. The EU CSRD and EU AI Act impose simultaneous emissions-reporting and algorithmic-transparency obligations on providers processing carrier data. Hamburg anchors the densest concentration of ETA engine development, with machine-learning engineering talent concentrating around port-centric software clusters.
United States
Third-party logistics providers serving Chicago and Dallas-Fort Worth freight hubs are consolidating visibility spend into single-platform agreements, retiring legacy point-solution contracts. The SEC climate disclosure rules and emerging state-level supply-chain transparency laws are elevating compliance tooling requirements. California's pharmaceutical distributors drive premium-margin demand for cargo-condition monitoring modules to limit temperature-excursion liability exposure.
Netherlands
Benelux distribution centers are bundling ocean, road, and rail tracking under unified architectures, with Rotterdam port operators deploying edge-computing nodes for sub-second anomaly detection. The EU Green Deal freight mandates convert retrospective reporting tools into live decision-support systems for cross-border flows. Eindhoven-based electronics manufacturers synchronize inbound component flows with vessel arrivals through digital twin architectures.
Singapore
Maritime trade orchestration platforms serving the Strait of Malacca corridor are expanding predictive analytics capabilities for ocean-air intermodal handoffs. The Maritime and Port Authority's digital port initiative accelerates telematics gateway deployment on regional rolling stock and containers. Jurong-based chemical distributors face intensifying scope-3 emissions attribution requirements for refrigerated transport legs across Southeast Asian networks.
United Kingdom
London-headquartered retailers are retiring legacy vessel-tracking contracts in favor of consolidated procurement covering end-to-end multimodal visibility. Post-Brexit customs complexity elevates demand for automated documentation integration at Felixstowe and Southampton ports. Midlands-based automotive suppliers deploy route optimization modules to synchronize inbound parts flows with assembly line takt times amid just-in-sequence pressure.
End-to-End Multimodal Shipment Visibility Platforms Market Competitive Landscape
API-first connectivity specialists and ERP-embedded platform providers split the market between rapid carrier onboarding and enterprise system integration. The vendor base concentrates around three strategic archetypes: pure-play visibility engines, supply-chain software suites with visibility modules, and logistics service providers with proprietary platforms. Competitive moves center on predictive analytics capability acquisition and geographic expansion into underpenetrated freight corridors.
Within the pure-play tier, project44 and FourKites exemplify API-density strategies, while Shippeo anchors European road-rail specialization. These entities occupy positions shaped by carrier network scale and machine-learning engineering concentration rather than vertical integration depth.
| Leading Market Players |
|---|
| project44 |
| FourKites |
| Shippeo |
| Descartes Systems Group |
| Transporeon |
| e2open |
| Oracle |
| SAP |
| Manhattan Associates |
| Others |
Pricing and Supply Chain Analysis
Hamburg's machine-learning engineering clusters concentrate predictive-analytics development, compressing talent acquisition costs for ETA engine providers while elevating compensation premiums for specialized hires. This geographic supply density shapes vendor pricing power across European multimodal visibility deployments, with GDPR-compliant cloud infrastructure commanding margin premiums over standard SaaS tiers.
Pricing Analysis
EU AI Act algorithmic-transparency mandates dictate the pricing tier structure across predictive-routing modules, forcing vendors to absorb compliance engineering overhead or pass costs through to premium service levels. Three-tier pricing structure across premium, standard, and economy levels separates ISO 28000-certified deployments for defense contractors from mid-market hybrid configurations and basic real-time tracking subscriptions. Cost compression in the standard tier is intensifying because carrier EDI heterogeneity prolongs implementation timelines and elevates integration labor. Third-party logistics providers exhibit the highest price sensitivity due to thin operating margins, while pharmaceutical distributors demonstrate the least sensitivity given temperature-excursion liability exposure.
Supply Chain Analysis
Tariff exposure between China and Germany dominates component sourcing strategies for IoT sensor hardware and edge-computing infrastructure. Supply concentrates in China for telematics gateway manufacturing, Germany for predictive-analytics software engineering, and the Netherlands for Benelux distribution hub deployments. Platform architectures draw from cloud infrastructure services, carrier API connectivity licenses, and machine-learning training data pipelines. Single-source vulnerability persists for specialized ETA engine development talent concentrated in Hamburg and Munich. Distribution runs through direct enterprise sales for large automotive OEMs, channel partners for mid-market manufacturers, and API marketplaces for developer-centric carrier integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement as large European retailers bundle ocean, road, and rail tracking under single-platform agreements, retiring fragmented point-solution contracts and compressing vendor pricing leverage.
For Market Incumbents: Build carrier-connectivity density moats through API-first integration across Rhine-Alpine road-rail hubs before emerging entrants replicate project44's network effects. Acquire specialized machine-learning engineering teams in Hamburg to defend against talent poaching from hyperscalers entering logistics software. Invest in EU-sovereign cloud instances to preempt regulatory fragmentation risks from GDPR data-localization enforcement. For New Entrants and Emerging Players: North Sea-Baltic TEN-T corridor digital freight corridors linking Hamburg to Baltic ports remain underpenetrated by unified visibility architectures, presenting white-space expansion targets. Pharmaceutical cold-chain monitoring modules for temperature-excursion liability management offer premium-margin entry points with lower competitive density than real-time tracking. Pursue partnership-led go-to-market strategies with Rotterdam port operators deploying edge-computing nodes to bypass incumbent carrier network advantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform providers with embedded predictive-analytics workflows, sustaining valuation premiums over project-based implementation services. Acquisition targets should demonstrate proven EU AI Act compliance architecture and established carrier API density in at least one major freight corridor. Monitor CSRD scope-3 emissions-reporting mandate enforcement intensity as the inflection indicator for compliance-tooling budget allocation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Carrier Integration | project44's connectivity density sustains competitive positioning across European road-rail hubs. |
| EU-Sovereign Cloud Deployment | GDPR data-residency requirements elevate engineering overhead but create procurement preference among German automotive OEMs. |
| Predictive Analytics Acquisition | Machine-learning ETA engine specialization concentrates margin capture in Hamburg and Bremerhaven container handoffs. |
| Pharmaceutical Cold-Chain Expansion | Temperature-excursion liability costs in Munich chemical distribution open premium-margin pools for condition monitoring modules. |
| ISO 28000 Security Certification | Supply-chain security standards create procurement preference shifts among Stuttgart aerospace and defense contractors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supply chain directors at German automotive OEMs, platform engineering leads at Rotterdam port operators, procurement officers at Benelux distribution centers, and regulatory compliance specialists navigating EU AI Act implementation. Secondary validation drew from SEC filings of publicly traded logistics technology providers, EU CSRD regulatory guidance documents, customs data on European freight corridor volumes, and ISO 28000 certification registries. Bottom-up segment sizing across deployment modes, solution types, and end-user industries was triangulated against top-down market aggregation from carrier API connectivity metrics and platform vendor revenue disclosures.
Calibration against historical adoption curves in adjacent supply-chain software categories anchored growth rate assumptions across the projection horizon. Segmentation dimensions modeled encompassed deployment architecture, solution depth from real-time tracking through predictive analytics, use case intensity from last-mile delivery through cold-chain monitoring, and end-user operational complexity from third-party logistics through manufacturing ERP integration. CAGRs were derived from logistic diffusion curves fitted to platform penetration rates in comparable enterprise software categories, with freight corridor digitalization spend and CSRD compliance budget pre-allocation serving as industry-specific demand drivers.
Practitioners should monitor EU AI Act enforcement variance across member states and carrier EDI standardization initiative progress for early signals of implementation timeline compression or extension. Forecasts reflect assumptions about regulatory compliance cost pass-through rates and machine-learning engineering talent supply elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.