
 South Korea Third-Party Logistics (3PL) Market | 2026-2036
South Korea Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Third-Party Logistics (3PL) Market Analytics
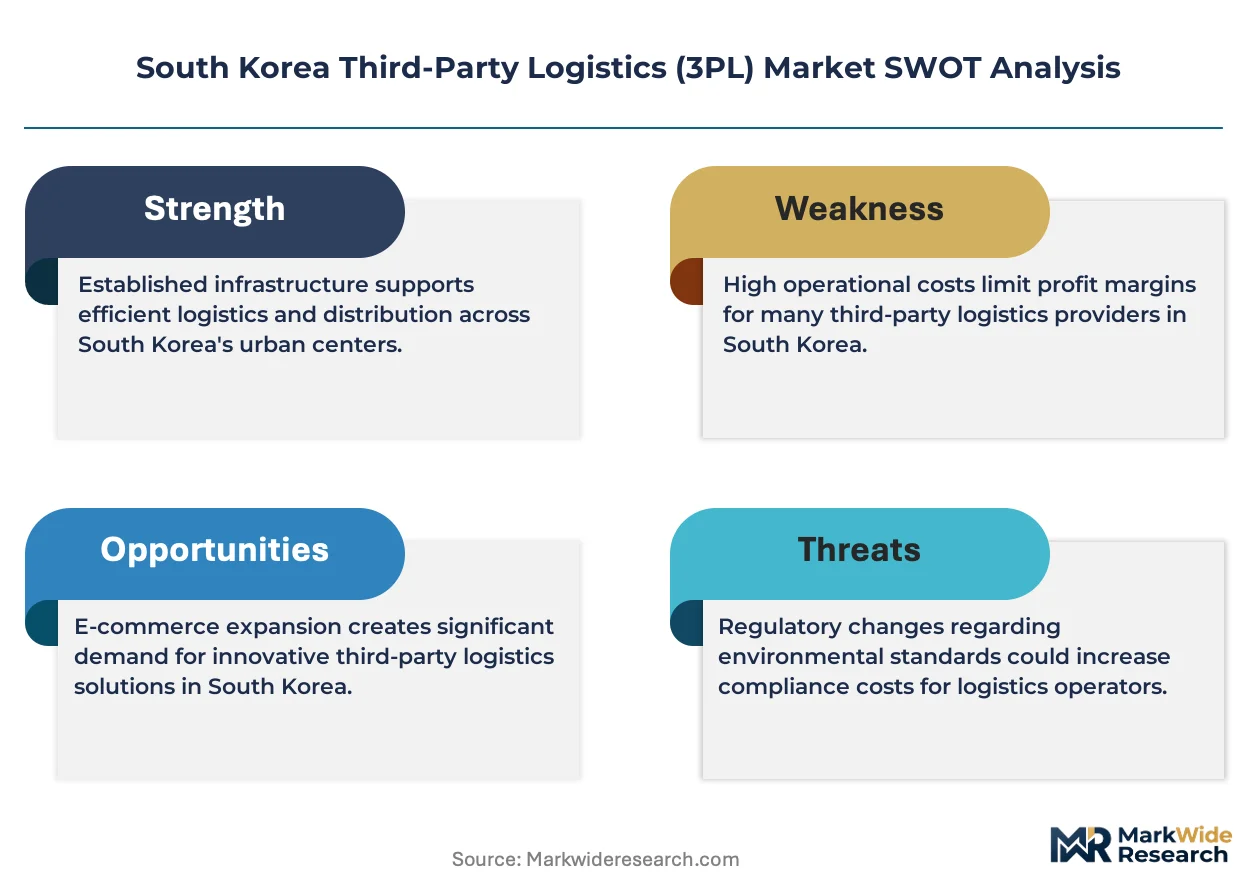
MFDS cold-chain mandates for biopharmaceutical distribution is consolidating compliance costs among smaller fleet operators. CJ Logistics Corporation anchors temperature-controlled warehousing capacity across the Seoul-Inheon corridor. Hyundai Glovis Co. Ltd. dominates automotive parts logistics through captive integration with Hyundai Motor Group. LX Pantos specializes in electronics forwarder services, leveraging Inchon airport customs clearance speed.
Third-Party Logistics (3PL) denotes outsourced supply-chain management encompassing transportation execution, inventory storage, order fulfillment, and freight brokerage under contractual arrangement. Korean 3PL providers operate multi-client distribution centers with racking densities exceeding 15 pallets per square meter to maximize land-scarce facility economics. Transportation and freight forwarding command the largest revenue pools, though warehousing margins expand faster as e-commerce customers accept premium rates for same-day fulfillment. E-commerce customer-type contracts outpace manufacturer segments in volume growth, reflecting Coupang and Naver Shopping fulfillment outsourcing.
MFDS enforces Good Distribution Practice for pharmaceutical logistics, while the Ministry of Environment implements K-ETS carbon allocation rules affecting diesel fleet operators. KSA and KOSHA standards govern warehouse automation safety and worker certification for robotic material-handling systems. Stakeholders must weigh automation capex against labor availability constraints in the Busan-Ulsan manufacturing belt.
Market Dynamics
E-commerce fulfillment density across the Seoul metropolitan corridor is compressing delivery windows from next-day to same-day, forcing 3PL operators to reconfigure warehouse networks and fleet deployment patterns around micro-fulfillment nodes.
Growth Catalysts
- MFDS cold-chain mandates:Biopharmaceutical distribution rules are consolidating demand for temperature-certified warehousing among specialized operators capable of Good Distribution Practice compliance.
- Gyeonggi Province logistics cluster:Concentration of fulfillment centers around Incheon Port creates intermodal efficiency gains for container-to-last-mile transitions.
- Automotive electrification:Battery component logistics requires hazardous-material handling certification that captive 3PL networks are scaling to serve Hyundai Motor Group suppliers.
Market Restraints
- Diesel fleet K-ETS carbon costs:Ministry of Environment allocation rules impose input cost volatility on road freight operators without pass-through mechanisms in contracted rates.
- Seoul-Incheon land scarcity:Industrial zoned land concentration limits greenfield warehouse development, forcing brownfield retrofit capex at 40-60% premium.
- Robotic systems technical limitation:KSA and KOSHA certification timelines for automated material-handling equipment extend deployment cycles beyond customer contract windows.
Strategic Opportunities
- Busan-Ulsan manufacturing belt automation:Labor availability constraints in heavy industry zones create white space for autonomous yard-management system deployment.
- MFDS regulatory tailwind:Expanding pharmaceutical export volume from Songdo biotech cluster drives demand for temperature-controlled air freight forwarding through Incheon International Airport.
- Cross-border e-commerce channel innovation:Naver Shopping and Coupang fulfillment outsourcing models enable 3PL penetration of direct-to-consumer customs clearance services previously captive to platforms.
Industry Challenges
- Warehouse automation skill gap:KOSHA-certified technician scarcity delays robotic system commissioning and maintenance response times.
- Legacy WMS integration complexity:Tier-2 manufacturers in the Daegu-Gyeongbuk textile belt operate on-premise ERP systems requiring custom API development for 3PL visibility portals.
- Same-day fulfillment capex intensity:Micro-fulfillment node density requirements demand fleet duplication without proportional revenue per stop increases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Third-Party Logistics (3PL) Market |
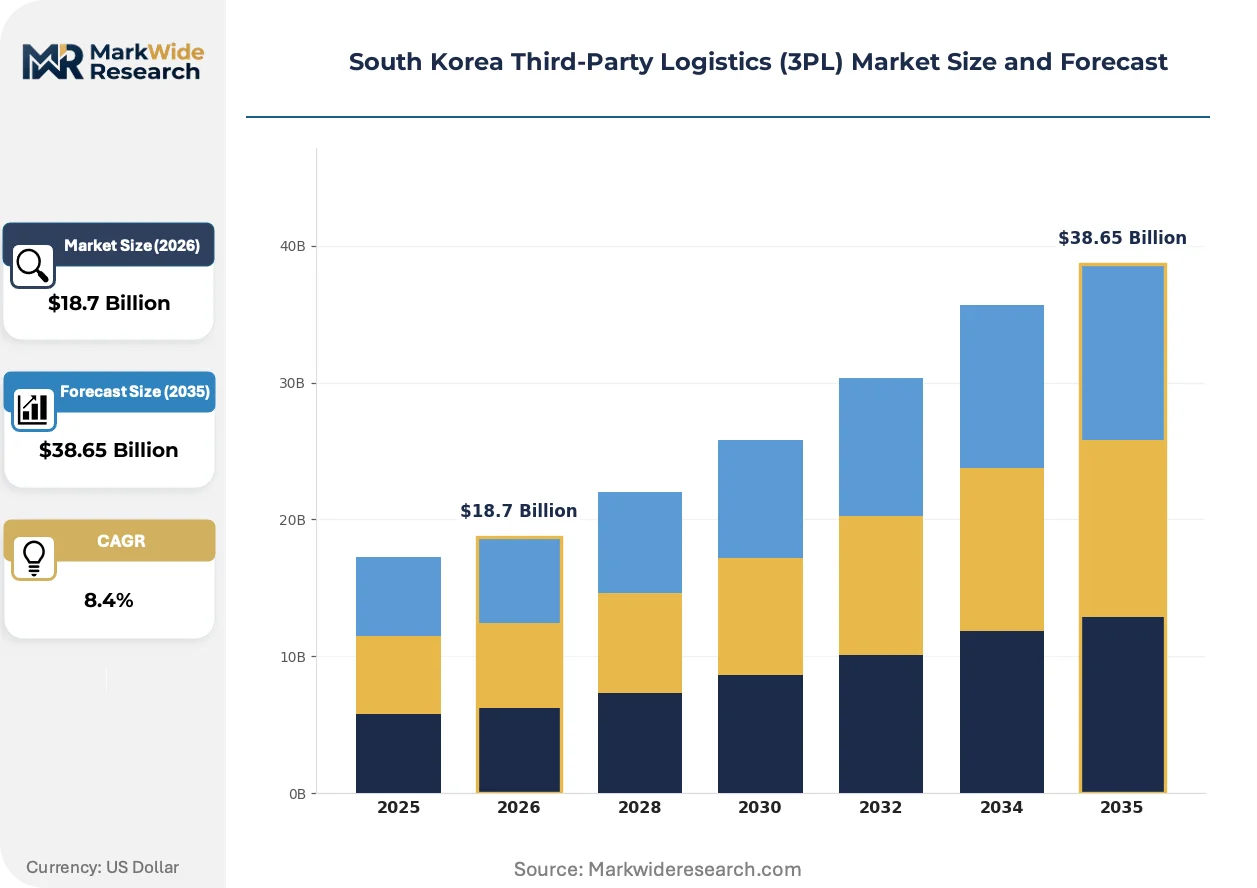
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding Customer Type: E-commerce, Retailers, Manufacturers, Healthcare Technology: WMS, TMS, IoT, Blockchain End User: Automotive, Electronics, Pharmaceutical, Food & Beverage |
| Companies Covered | Kuehne + Nagel International AG, Daewoo Logistics, CJ Logistics Corporation, Lotte Global Logistics, SEBANG, Hyundai Glovis Co. Ltd., DSV A/S, Yusen Logistics, LX Pantos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Third-Party Logistics (3PL) Market Evolving Landscape
Autonomous mobile robots and AI-driven demand forecasting are compressing the physical-digital boundary in Korean warehousing, while regulatory carbon accounting and buyer procurement centralization reshape competitive requirements.
Autonomous mobile robots equipped with computer vision navigation are decentralizing warehouse labor deployment across the Seoul metropolitan fulfillment corridor. E-commerce operators including Coupang and Naver Shopping are adopting AMR fleets at pilot-to-scale velocity of 18-24 months per facility. This technology is decentralizing picking operations from fixed-zone human assignments to dynamic task allocation, compressing order cycle times without proportional headcount expansion.
MFDS enforcement of serialized pharmaceutical track-and-trace requirements is mandating warehouse management system upgrades with lot-level visibility. The regulation imposes data retention and temperature logging standards that disqualify non-compliant operators from biopharmaceutical contracts. Cold-chain 3PL providers are responding with blockchain-integrated inventory systems to automate compliance documentation for export shipments.
Consolidated procurement by electronics manufacturers is compressing 3PL contract durations and expanding performance-based penalty clauses. Samsung and LG affiliates are unbundling transportation from warehousing to source specialized providers for each function. This pattern is most visible in the Gyeonggi-Incheon corridor where electronics forwarders compete on customs clearance speed rather than asset ownership breadth.
South Korea Third-Party Logistics (3PL) Market Segmentation
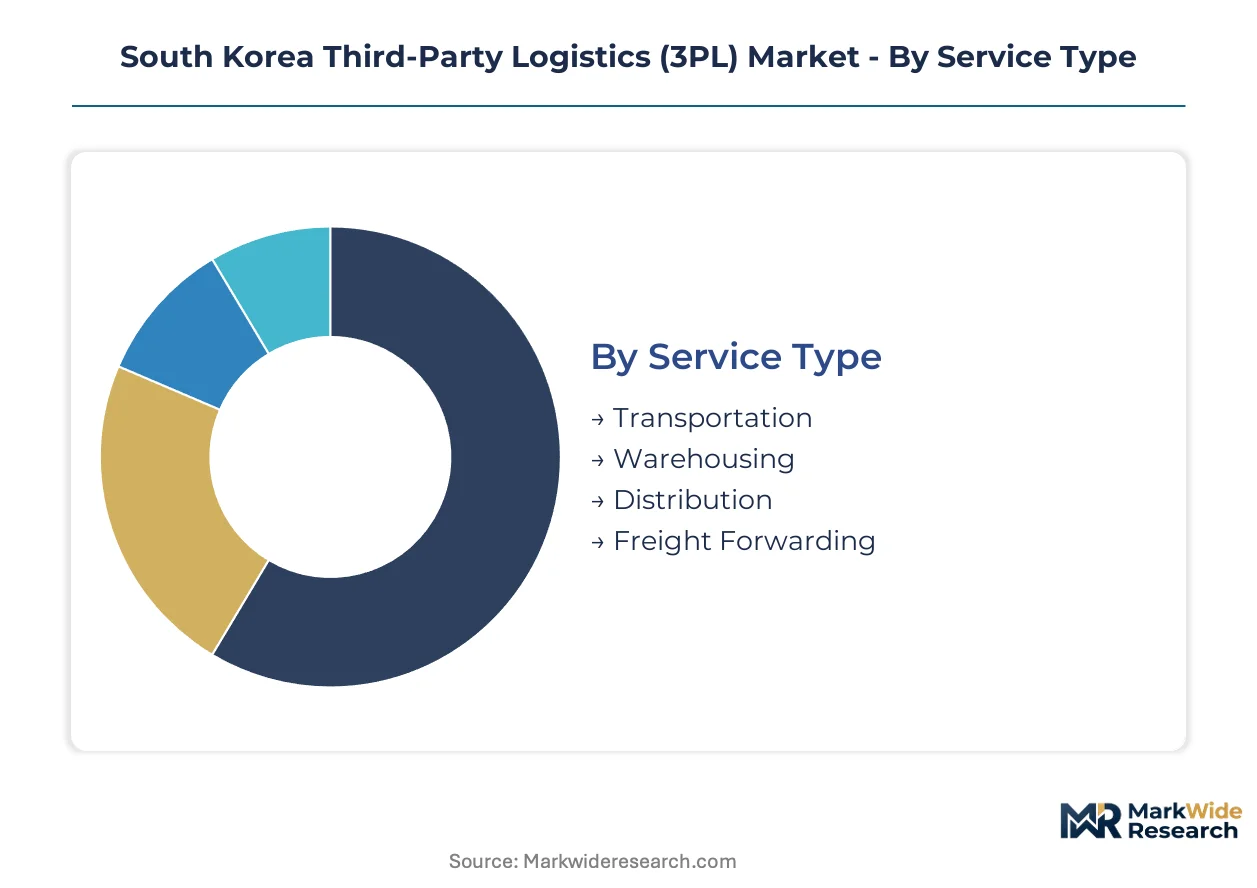
Service specialization and customer concentration patterns in South Korea's 3PL market reveal divergent margin profiles and capex requirements across operational models. Segmentation clarity enables operators to align asset deployment with the compressed delivery windows and regulatory compliance demands reshaping competitive economics.
Service Type:
Transportation and warehousing functions concentrate revenue in distinct operational footprints across the Seoul-Incheon corridor and Busan-Ulsan belt.
- Transportation:Road freight execution dominates revenue pools through diesel fleet networks serving manufacturer supply chains. Demand clusters in Gyeonggi Province for container drayage and last-mile e-commerce delivery, though K-ETS carbon allocation rules inject cost volatility without guaranteed rate pass-through.
- Warehousing:Multi-client distribution centers with racking densities exceeding 15 pallets per square meter maximize land-scarce facility economics in Seoul metropolitan zones. E-commerce customers accept premium rates for same-day fulfillment, expanding margins faster than transportation segments.
- Distribution:Value-added services including kitting, labeling, and returns processing attach to core storage contracts. Pharmaceutical and electronics verticals drive compliance-heavy requirements around lot-level traceability.
- Freight Forwarding:Customs brokerage and international documentation services concentrate around Incheon International Airport and Incheon Port. Electronics forwarders compete on clearance speed rather than asset ownership breadth.
Today's leader: Transportation. Tomorrow's challenger: Warehousing.
Customer Type:
Contract structures and volume predictability vary sharply between platform-driven e-commerce and traditional manufacturer relationships.
- E-commerce:Coupang and Naver Shopping fulfillment outsourcing compresses delivery windows from next-day to same-day, forcing micro-fulfillment node deployment. Volume growth outpaces manufacturer segments, though capex intensity per revenue dollar remains elevated.
- Retailers:Department store and hypermarket chains source integrated warehousing and transportation under multi-year agreements. Seasonal demand spikes require flexible labor arrangements in Seoul metropolitan distribution zones.
- Manufacturers:Samsung and LG affiliates unbundle transportation from warehousing to source specialized providers for each function. Contract durations compress as procurement centralization expands performance-based penalty clauses.
- Healthcare:MFDS Good Distribution Practice mandates consolidate demand among temperature-certified operators capable of pharmaceutical compliance. Biopharmaceutical export growth from Songdo biotech cluster drives cold-chain investment.
E-commerce contracts are expanding most quickly; healthcare delivers the steepest margin premiums.
Technology:
Digital infrastructure investments separate Tier-1 operators from asset-heavy competitors in customer acquisition and retention.
- WMS:Warehouse management system upgrades with lot-level visibility become mandatory under MFDS pharmaceutical track-and-trace enforcement. Legacy on-premise ERP integration challenges persist for Tier-2 manufacturers in Daegu-Gyeongbuk textile zones.
- TMS:Transportation management systems optimize fleet routing against Seoul metropolitan congestion patterns. Real-time visibility portals differentiate 3PL offerings for electronics manufacturers with just-in-time production schedules.
- IoT:Sensor networks enable temperature logging and asset tracking for cold-chain compliance. Battery component logistics for automotive electrification requires hazardous-material handling certification integrated with IoT monitoring.
- Blockchain:Distributed ledger systems automate compliance documentation for pharmaceutical export shipments. Adoption remains concentrated among cold-chain specialists serving MFDS-regulated distribution.
WMS anchors current competitive positioning; blockchain adoption trails operational necessity.
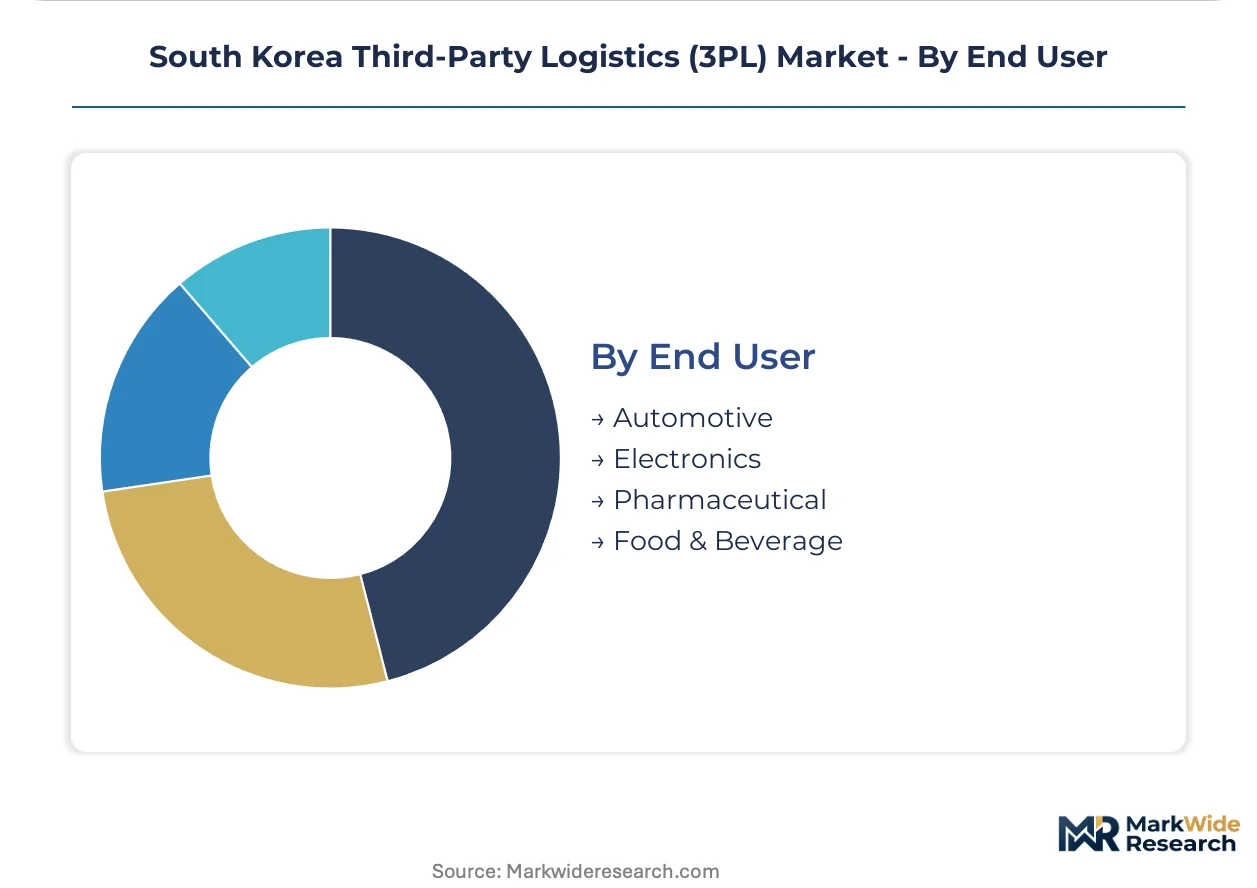
End User:
Vertical specialization requirements dictate facility certification, labor skill profiles, and geographic proximity to production clusters.
- Automotive:Hyundai Glovis captive integration with Hyundai Motor Group dominates battery component and finished vehicle logistics. Hazardous-material handling certification scales across supplier networks as electrification accelerates.
- Electronics:Semiconductor and display panel distribution demands cleanroom-capable warehousing and precision handling. Gyeonggi-Incheon corridor concentration enables customs clearance speed competition among forwarders.
- Pharmaceutical:MFDS cold-chain mandates disqualify non-compliant operators from biopharmaceutical contracts. Temperature-controlled air freight forwarding through Incheon International Airport serves expanding export volume.
- Food & Beverage:Fresh and frozen distribution requires multi-temperature zone facilities with rapid throughput. Retail consolidation drives centralized distribution center models replacing direct store delivery.
Electronics commands current volume concentration; pharmaceutical verticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics technicians and KOSHA-certified automation specialists concentrate in the Seoul Capital Area and Busan-Ulsan manufacturing belt, anchoring operational capacity for temperature-controlled and hazardous-material handling services.
Seoul Capital Area
E-commerce fulfillment density and biopharmaceutical export growth drive demand for micro-fulfillment nodes and cold-chain warehousing. MFDS enforces Good Distribution Practice certification for pharmaceutical logistics operators. The Gyeonggi Province logistics cluster surrounding Incheon Port consolidates container-to-last-mile transitions with intermodal efficiency gains.
Busan-Ulsan
Automotive electrification and battery component logistics require hazardous-material handling certification scaling across Hyundai Motor Group supplier networks. The Ministry of Environment implements K-ETS carbon allocation rules affecting diesel fleet operators in this heavy industry zone. Labor availability constraints create white space for autonomous yard-management system deployment at port-adjacent facilities.
Daegu-Gyeongbuk
Textile and electronics manufacturing supply chains demand legacy WMS integration for Tier-2 producers operating on-premise ERP systems. KSA standards govern warehouse automation safety and worker certification for robotic material-handling systems. Industrial zones in this region retrofit brownfield facilities at premium capex due to land scarcity pressures.
Daejeon-Sejong
Government administrative concentration and Songdo biotech cluster proximity position this region for pharmaceutical distribution compliance services. MFDS cold-chain mandates consolidate demand among temperature-certified operators capable of serialized track-and-trace documentation. Temperature-controlled air freight forwarding through nearby Incheon International Airport serves expanding biopharmaceutical export volume.
Gwangju-Honam
Food and beverage distribution networks require multi-temperature zone facilities with rapid throughput for fresh and frozen cargo. Retail consolidation drives centralized distribution center models replacing direct store delivery in this agricultural processing region. Regional logistics providers face skill gaps in KOSHA-certified technician availability for automated system maintenance.
South Korea Third-Party Logistics (3PL) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Korea's 3PL market, creating a tiered structure where captive automotive logistics networks coexist with independent e-commerce fulfillment operators. Market concentration varies by vertical, with electronics forwarding and pharmaceutical cold-chain segments showing tighter specialization requirements than general freight brokerage. Three archetypes dominate: conglomerate-affiliated providers leveraging parent company supply relationships, independent specialists competing on customs clearance speed and compliance certification, and global forwarders anchoring international air and ocean freight corridors. Competitive moves center on automation capex deployment for same-day fulfillment density and strategic partnerships for pharmaceutical cold-chain certification.
Among conglomerate-affiliated operators, CJ Logistics Corporation and Hyundai Glovis Co. Ltd. exemplify the captive-to-independent spectrum, with the former anchoring temperature-controlled warehousing capacity and the latter representing automotive parts logistics integration. LX Pantos occupies a position within the electronics forwarder specialization tier, competing on Incheon airport customs clearance velocity rather than asset breadth. These three entities represent distinct strategic postures: compliance-heavy vertical integration, captive manufacturing supply chain lock-in, and speed-focused customs brokerage specialization.
| Leading Market Players |
|---|
| Kuehne + Nagel International AG |
| Daewoo Logistics |
| CJ Logistics Corporation |
| Lotte Global Logistics |
| SEBANG |
| Hyundai Glovis Co. Ltd. |
| DSV A/S |
| Yusen Logistics |
| LX Pantos |
| Others |
Value Network & Pricing Analysis
Diesel benchmark fluctuations cascade through South Korea's 3PL sector, compressing margins for road freight operators while amplifying pricing power for temperature-certified warehousing providers serving MFDS-regulated pharmaceutical distribution.
Pricing Analysis
Bundled transportation-warehousing contracts versus unbundled specialized sourcing splits the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-certified cold-chain operators from general freight brokers and economy last-mile providers. Price differentiation hinges on K-ETS carbon pass-through capability and Incheon corridor proximity. Cost compression in standard-tier road freight is intensifying because diesel fleet operators lack guaranteed rate adjustment mechanisms. E-commerce platforms demonstrate highest price sensitivity; pharmaceutical manufacturers accept premium rates for compliance assurance.
Supply Chain Analysis
Returns processing and reverse logistics flows from Coupang and Naver Shopping fulfillment networks are reshaping node configuration economics across the Seoul metropolitan corridor. Component sourcing draws from China for automation equipment, Germany for precision handling systems, and domestic Korean manufacturers for fleet vehicles. Battery component logistics for automotive electrification rests on hazardous-material handling certification scaling. Single-source vulnerability concentrates in Incheon Port container throughput for electronics forwarders. Distribution runs through multi-client distribution centers with micro-fulfillment node satellite deployment for same-day service coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through automation capex absorption and premium-tier healthcare logistics certification, with K-ETS carbon cost pass-through emerging as the critical cost-down differentiator.
For Market Incumbents: Deploy autonomous mobile robot fleets to compress order cycle times without proportional headcount expansion. CJ Logistics Corporation and Hyundai Glovis should deepen backward integration into temperature-controlled warehousing capacity and battery component handling certification respectively. Threat substitution from platform-owned fulfillment networks demands defensive positioning through MFDS compliance moats. For New Entrants and Emerging Players: Premium-to-economy pricing gaps in pharmaceutical cold-chain services open white-space entry points. Target the Busan-Ulsan manufacturing belt for autonomous yard-management deployment where labor scarcity constrains incumbent response. MFDS Good Distribution Practice certification investment offers the most penetrable go-to-market angle for specialized cold-chain positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with electronics forwarders possessing Incheon airport customs clearance velocity advantages. Long-term viability over the next decade favors operators combining WMS platform depth with vertical-specific compliance certification. Acquisition target archetype: mid-cap specialists with KOSHA-certified automation technician benches. Monitor K-ETS carbon allocation rule amendments for margin structure inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Cold-Chain Certification Investment | Good Distribution Practice compliance unlocks biopharmaceutical contract access at premium rate tiers. |
| Autonomous Mobile Robot Fleet Deployment | AMR pilot-to-scale velocity of 18-24 months compresses fulfillment cycle times for e-commerce density. |
| Micro-Fulfillment Node Network Expansion | Same-day service coverage demands fleet duplication across Seoul-Incheon corridor land-constrained zones. |
| Backward Integration into Temperature-Controlled Warehousing | Captive cold-chain capacity secures pharmaceutical export volume from Songdo biotech cluster growth. |
| K-ETS Carbon Pass-Through Mechanism Development | Contract rate adjustment clauses defend diesel fleet margins against Ministry of Environment allocation volatility. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down transportation fleet capacity tracking forms the analytical core. Primary interviews with warehouse operations directors, MFDS regulatory compliance officers, automotive procurement leads, and pharmaceutical supply chain managers combined with secondary validation from Korea Customs Service trade data, Ministry of Land, Infrastructure and Transport freight statistics, SEC filings of listed logistics providers, and MFDS Good Distribution Practice registry records. Triangulation across stakeholder perspectives and documentary sources ensures segment-level accuracy.
Historical trendline analysis of service-type revenue pools and customer-type contract structures anchored the projection framework. Segmentation dimensions modeled include service specialization, customer vertical, technology adoption tier, and geographic cluster concentration across the analysis window. CAGRs were derived from capacity deployment trajectories, regulatory compliance cost curves, and e-commerce fulfillment outsourcing velocity. Industry-specific forecast inputs incorporated K-ETS carbon price assumptions and AMR adoption S-curves.
Caveats apply where MFDS regulatory enforcement intensity, K-ETS allocation rule amendments, or platform vertical integration decisions could materially shift the outlook. Forecasts reflect assumptions around labor availability constraints and land scarcity premiums in core logistics corridors. Practitioners should monitor AMR commissioning timelines and KOSHA certification backlog durations for early capacity constraint signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
South America Freight and Logistics Market