
 Russia Courier Service Market | 2026-2036
Russia Courier Service Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Courier Service Market Insights
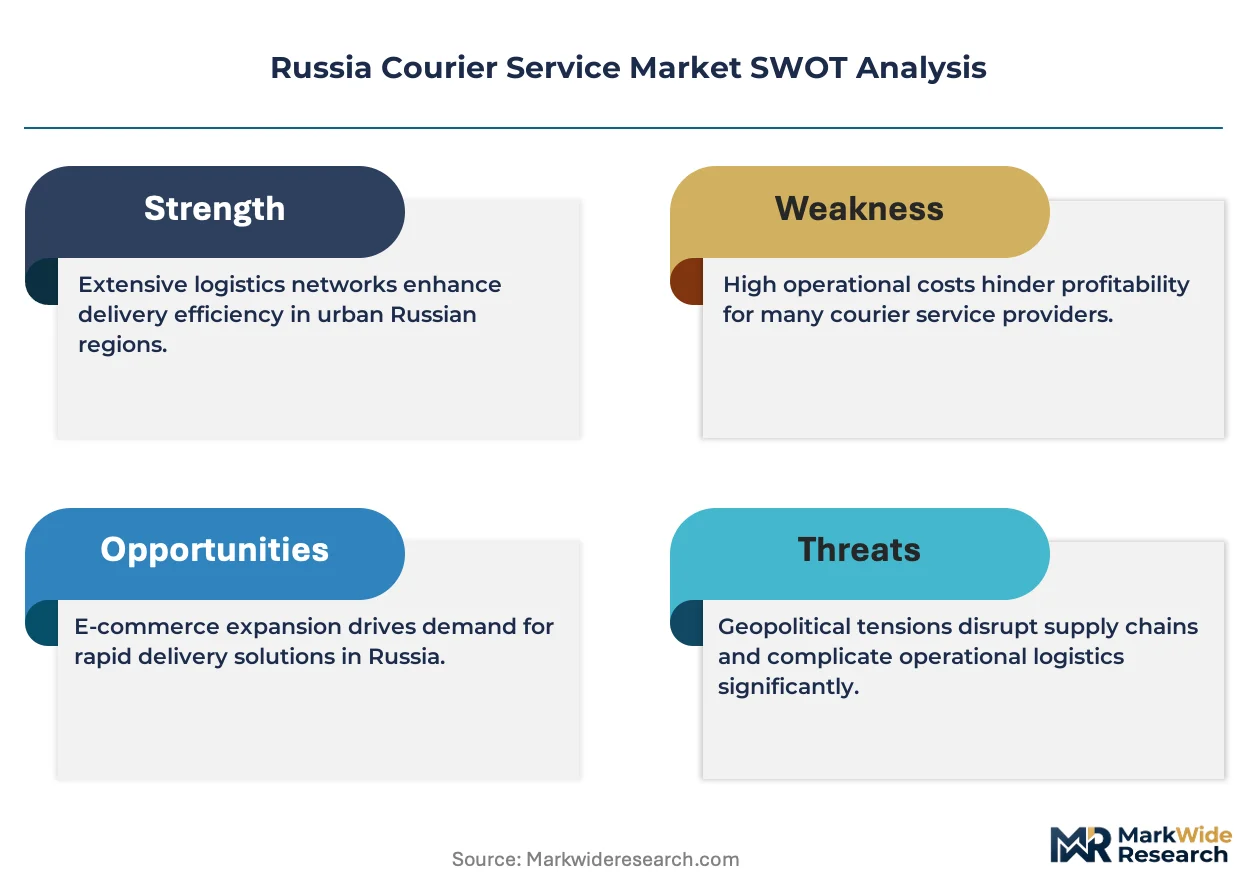
Last-mile distribution in Russian metropolitan corridors is fragmenting as digital retail volumes force carriers to rebuild hub-and-spoke networks around fulfillment speed rather than cost alone. Russian Post anchors universal coverage through its inherited postal infrastructure, leveraging over 40,000 access points to sustain rural reach that private competitors cannot replicate. SDEK-Global LLC competes aggressively in cross-border e-commerce logistics, specializing in customs brokerage integration that reduces clearance friction for Chinese-origin parcels. Yandex controls urban same-day velocity through its superapp ecosystem, extending grocery, food, and retail delivery into unified rider pools that optimize asset utilization across demand peaks.
Russia courier service encompasses the commercial movement of documents, parcels, and palletized freight through integrated ground, air, and express networks, with delivery commitments ranging from same-day to standard multi-day transit based on distance and service tier. Temperature-controlled vehicles and real-time GPS tracking constitute critical technical infrastructure for pharmaceutical and high-value shipments. Same-day delivery commands premium pricing and absorbs disproportionate technology investment, while standard delivery retains the largest volume base among price-sensitive e-commerce consignments. International shipping faces structural compression from sanctions-related payment and routing restrictions, redirecting carrier investment toward domestic lane density and intra-Eurasian rail-sea alternatives. Document and parcel categories dominate package type volumes, though palletized freight generates superior unit economics for B2B manufacturing and retail replenishment flows.
The Russian Federal Antimonopoly Service and the Ministry of Transport jointly shape market access through tariff transparency mandates and infrastructure usage rules for shared rail and air cargo terminals. Russia's technical regulations on vehicle emissions and driver working hours directly affect fleet renewal costs and last-mile labor availability in dense urban zones. Stakeholders must monitor regulatory adjustments to cross-border data transmission and customs digitization, as these determine whether integrated tracking and automated clearance remain operational advantages or become baseline compliance requirements.
Market Dynamics
Last-mile fulfillment networks across Russian metropolitan corridors are fragmenting as digital retail volumes force carriers to rebuild hub-and-spoke systems around velocity rather than cost optimization alone.
Growth Catalysts
- E-commerce penetration:Digital retail volumes in Moscow and Saint Petersburg are pulling investment into same-day delivery infrastructure, creating density economies that sustain premium service tiers.
- Customs digitization:Automated clearance protocols for cross-border parcels are reducing dwell times at Eurasian rail terminals, accelerating intra-continental freight flows.
- Rural postal infrastructure:Russian Post's inherited access point network of over 40,000 locations provides universal coverage that private competitors cannot economically replicate.
Market Restraints
- Payment routing restrictions:Sanctions-related financial channel compression is forcing carriers to abandon Western payment rails, increasing transaction friction for international consignments.
- Fleet renewal costs:Russia's vehicle emissions regulations are accelerating replacement cycles for urban delivery vehicles, squeezing operating margins for mid-sized carriers.
- Rail terminal access concentration:Shared cargo infrastructure at major Eurasian transit points creates bottlenecks during peak seasonal volumes, limiting throughput scalability.
Strategic Opportunities
- Temperature-controlled pharmaceutical logistics:Cold chain infrastructure gaps in secondary Russian cities present white space for specialized carriers serving biologic and vaccine distribution.
- Superapp ecosystem integration:Unified rider pools spanning grocery, food, and retail delivery are optimizing asset utilization across demand peaks in dense urban zones.
- Intra-Eurasian rail-sea alternatives:Redirected investment toward domestic lane density and multimodal corridors is opening new routing options bypassing traditional Western hubs.
Industry Challenges
- Driver working hour compliance:Russia's regulations on driver working hours are constraining last-mile labor availability in dense urban zones during peak delivery windows.
- Cross-border data transmission protocols:Evolving requirements for integrated tracking and automated clearance are forcing carriers to reconfigure IT infrastructure mid-investment cycle.
- Hub-and-spoke reconfiguration:Legacy sorting facilities designed for cost-optimized multi-day transit require capital-intensive retrofitting to handle same-day velocity requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Courier Service Market |
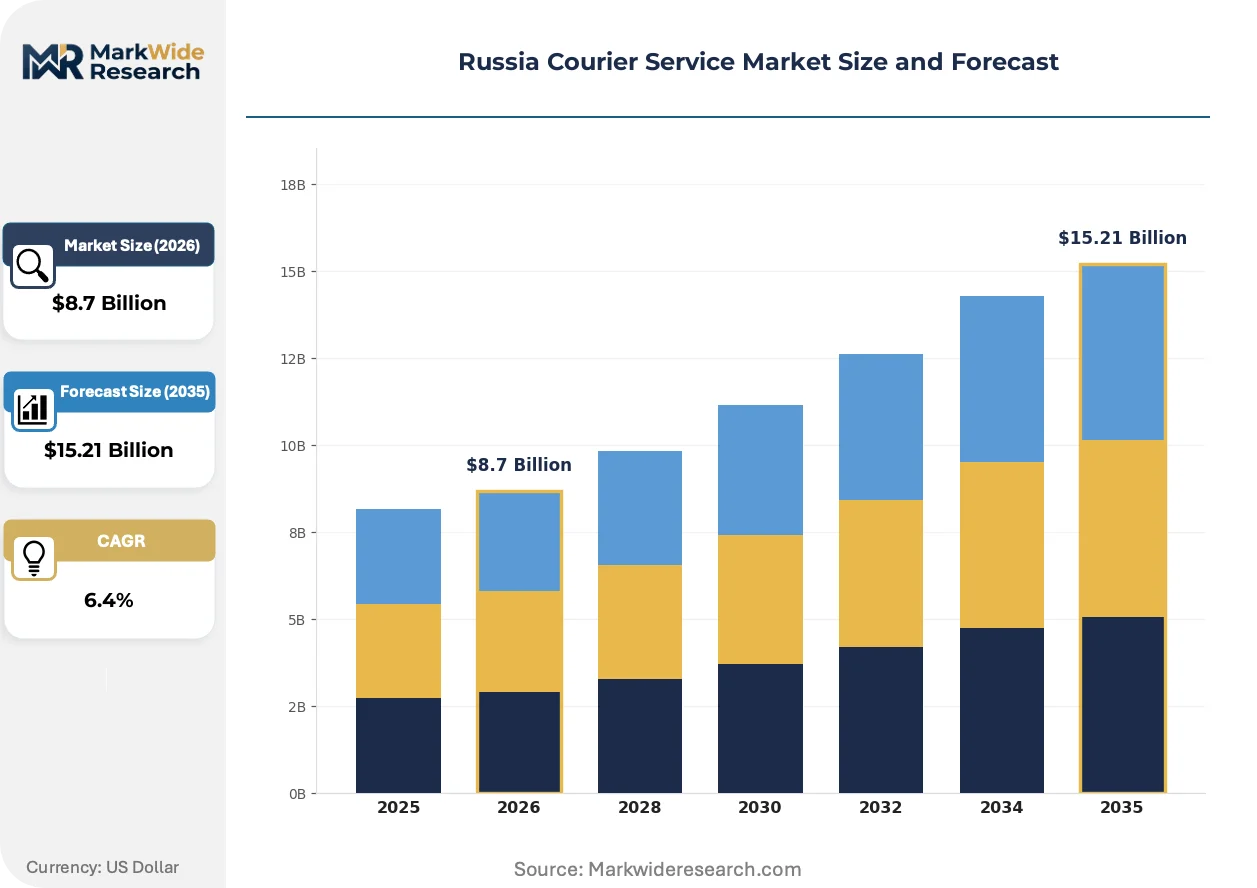
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, International Shipping, Standard Delivery End User: E-commerce, Retail, Healthcare, Government Delivery Mode: Ground, Air, Sea, Express Package Type: Document, Parcel, Pallet, Bulk |
| Companies Covered | Russian Post, SDEK-Global LLC, Delovye Linii Group, DHL Group, Pony Express, Boxberry, Major Express, Yandex, SberLogistics LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Courier Service Market Trends and Innovations
Real-time visibility systems and automated sorting infrastructure are compressing fulfillment timelines while regulatory pressure on emissions and labor practices is reshaping fleet composition across Russian logistics corridors.
Artificial intelligence-driven route optimization is digitizing dispatch decisions across urban delivery networks. Major e-commerce platforms are deploying machine learning algorithms to predict demand spikes and pre-position inventory within two-hour delivery radii. This capability is digitizing the traditional trade-off between inventory carrying costs and fulfillment speed.
Russia's Federal Antimonopoly Service has imposed tariff transparency mandates on shared rail and air cargo terminals, requiring carriers to publish standardized pricing for infrastructure access. The industrial consequence is reduced information asymmetry between incumbent and challenger carriers at bottleneck facilities. Temperature-controlled pharmaceutical shipments are most affected, as specialized cold storage terminal slots now carry published reservation protocols.
Consolidation of purchasing power among large digital retail platforms is compressing carrier margins through volume-based rate negotiations. Third-party logistics providers serving marketplace sellers are losing pricing autonomy as platform-owned fulfillment networks internalize high-velocity delivery. This concentration is most visible in Moscow, where unified superapp ecosystems now control majority share of same-day grocery and retail delivery volumes.
Russia Courier Service Market Segmentation
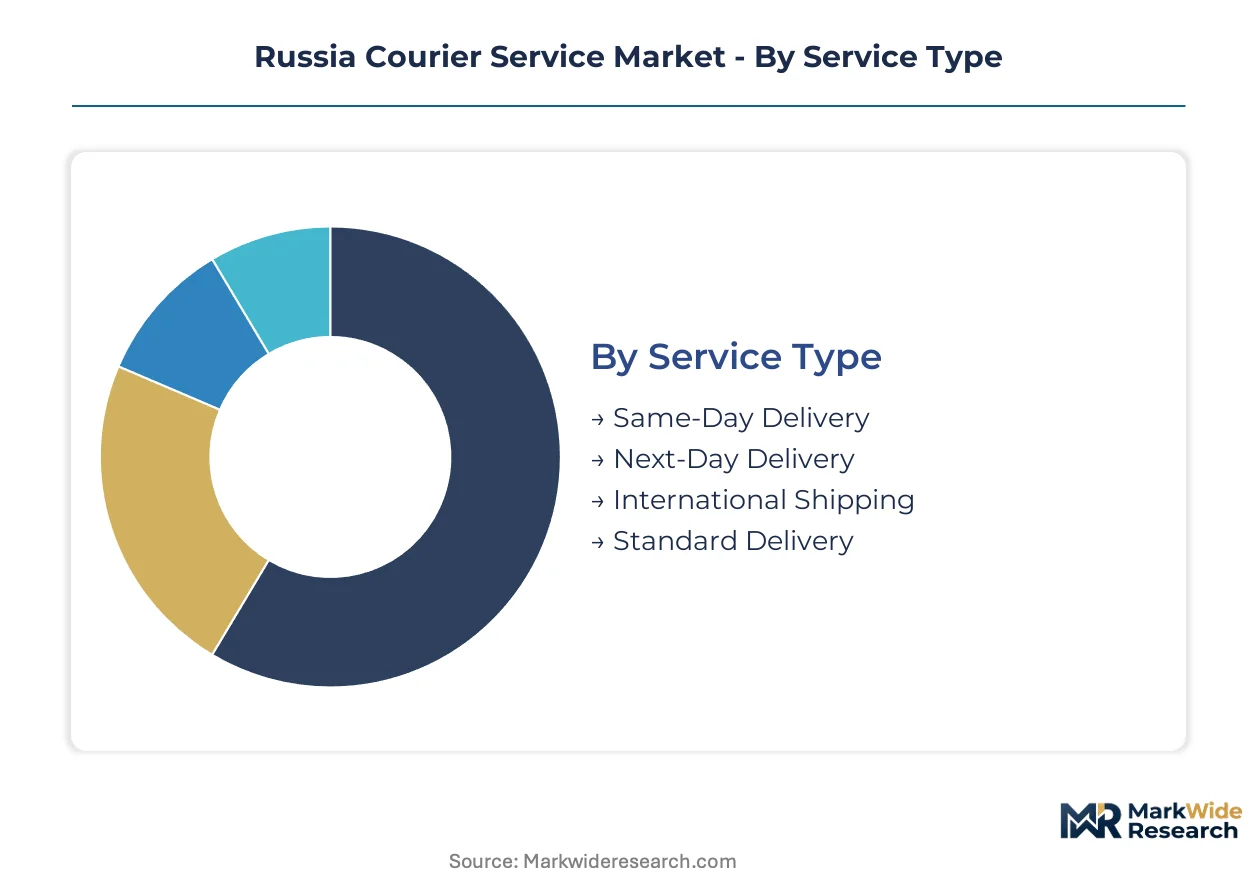
Segmentation in Russia's courier market reveals how service tiers, customer verticals, and infrastructure modes allocate capital and operating leverage across dramatically different margin profiles. Each dimension exposes distinct competitive dynamics that determine carrier positioning.
Service Type:
Cost tier differentiation separates premium velocity commitments from economy multi-day transit, with technology intensity and labor deployment scaling inversely with delivery windows.
- Same-Day Delivery:Requires real-time GPS tracking, dynamic route optimization, and dedicated urban rider pools to fulfill sub-four-hour commitments. Moscow and Saint Petersburg concentrate demand where superapp ecosystems absorb disproportionate technology investment.
- Next-Day Delivery:Balances hub-and-spoke sorting efficiency with overnight line-haul capacity, serving regional e-commerce platforms seeking competitive parity without same-day infrastructure costs.
- International Shipping:Faces structural compression from sanctions-related payment routing restrictions and customs friction, forcing carriers toward intra-Eurasian rail-sea alternatives bypassing traditional Western hubs.
- Standard Delivery:Retains volume dominance among price-sensitive consignments, leveraging Russian Post's inherited rural access point network of over 40,000 locations for universal coverage.
Same-Day Delivery holds installed capacity. Next-Day Delivery is rotating up the share rankings.
End User:
Application verticals impose divergent service specifications, with temperature control, chain-of-custody documentation, and regulatory compliance creating specialized capability moats.
- E-commerce:Platforms internalize fulfillment networks to compress last-mile timelines, consolidating purchasing power and compressing third-party carrier margins through volume-based rate negotiations.
- Healthcare:Biologic and vaccine distribution demands validated cold chain infrastructure with continuous temperature monitoring, presenting white space opportunities in secondary Russian cities where specialized capacity remains underdeveloped.
- Retail:Omnichannel replenishment flows require B2B palletized freight coordination alongside consumer parcel delivery, favoring carriers with unified ground fleet deployment.
- Government:Procurement mandates prioritize universal coverage and tariff transparency, aligning with Russian Post's statutory service obligations and Federal Antimonopoly Service oversight.
E-commerce dominates volume throughput. Healthcare is expanding most quickly as pharmaceutical cold chain requirements intensify.
Delivery Mode:
Infrastructure modality determines capital intensity, geographic reach, and exposure to shared terminal bottlenecks across Russia's vast territory.
- Ground:Line-haul trucking and last-mile van fleets constitute the backbone of domestic distribution, with fleet renewal costs accelerating under Russia's vehicle emissions regulations.
- Air:Express cargo networks concentrate at Moscow Sheremetyevo and Domodedovo hubs, facing capacity constraints during peak seasonal volumes and sanctions-related routing restrictions.
- Sea:Containerized freight through Vladivostok and Saint Petersburg ports serves cross-border e-commerce logistics, with SDEK-Global LLC specializing in customs brokerage integration for Chinese-origin parcels.
- Express:Dedicated time-definite networks combine multimodal assets under unified tracking systems, commanding premium pricing for high-velocity commitments.
Ground maintains the deepest lane density. Express is climbing the fastest as same-day velocity requirements reshape network design.
Package Type:
Volume and handling characteristics stratify unit economics, with dimensional weight pricing and specialized equipment requirements segmenting carrier specialization.
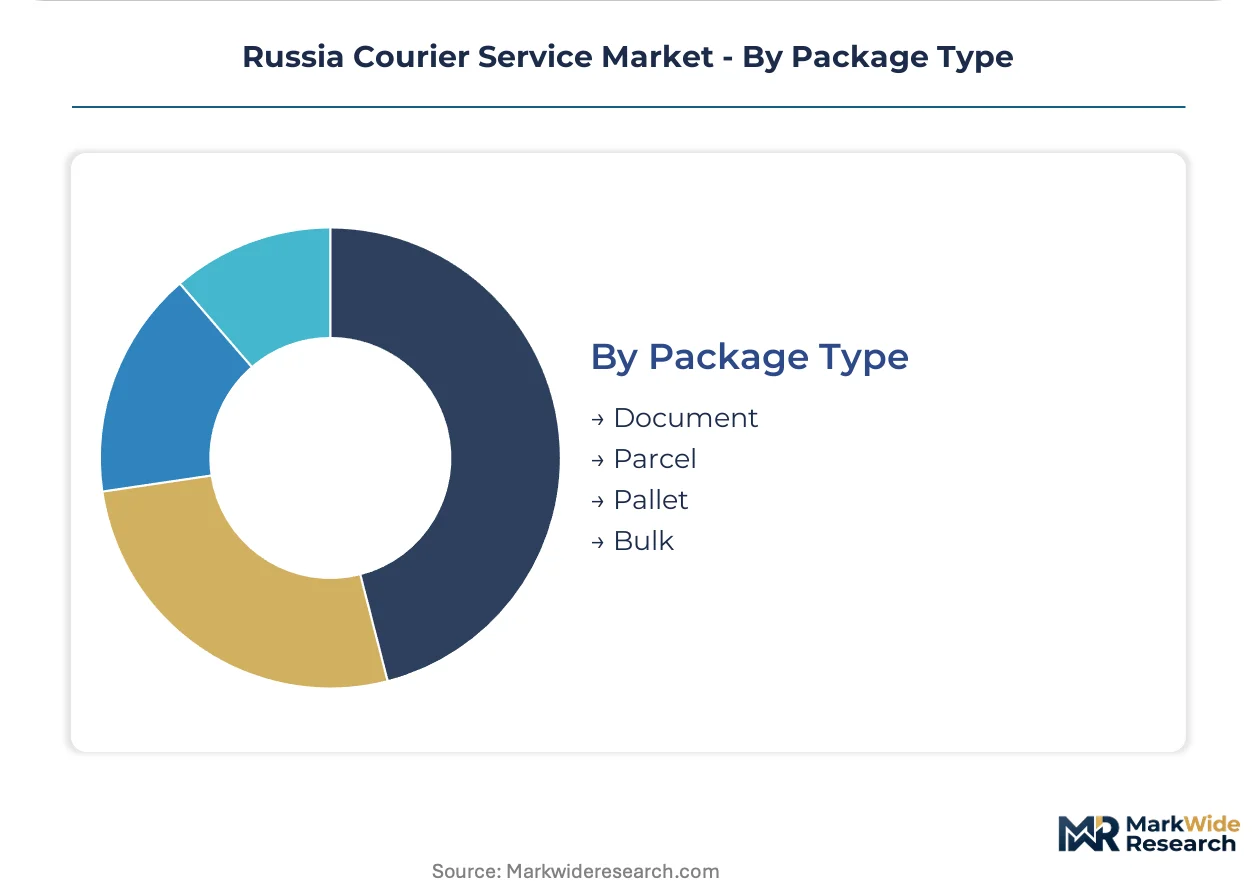
- Document:Lightweight administrative shipments with high security and chain-of-custody requirements, concentrated in financial services and legal sectors.
- Parcel:Consumer e-commerce consignments dominate absolute volume, absorbing automated sorting infrastructure investment and real-time visibility system deployment.
- Pallet:B2B manufacturing and retail replenishment flows generate superior unit economics through consolidated freight consolidation and scheduled delivery windows.
- Bulk:Uncontainerized freight requiring specialized handling equipment, serving industrial and construction material distribution with lower frequency but higher revenue per shipment.
Parcel commands the greatest infrastructure investment. Pallet is gaining share fastest as B2B shippers consolidate freight procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Siberian Railway and Baikal-Amur Mainline underwrite Russia's east-west freight backbone, positioning the country as a Eurasian logistics pivot despite sanctions-constrained western corridors.
Central Federal District
Moscow's same-day delivery density attracts superapp ecosystem investment and dedicated urban rider pools. The Federal Antimonopoly Service monitors tariff transparency at shared cargo terminals to preserve competitive access. The Moscow Oblast corridor concentrates automated sorting infrastructure and real-time GPS tracking deployment for pharmaceutical cold chain shipments.
Northwestern Federal District
Saint Petersburg's port infrastructure anchors Baltic Sea containerized freight flows for cross-border e-commerce logistics. The Ministry of Transport enforces infrastructure usage rules for shared air cargo terminals at Pulkovo Airport. The Leningrad Oblast cluster specializes in customs brokerage integration for Chinese-origin parcel clearance.
Siberian Federal District
Novosibirsk's rail hub status positions the region for intra-Eurasian multimodal alternatives bypassing traditional western routing. Vehicle emissions regulations accelerate fleet renewal costs for last-mile operators serving dispersed population centers. The Novosibirsk metropolitan zone develops temperature-controlled pharmaceutical distribution capacity for biologic shipments.
Far Eastern Federal District
Vladivostok's deep-water port facilities handle containerized freight from Asia-Pacific manufacturing centers. The central bank's payment routing oversight affects transaction friction for international consignments through eastern corridors. The Primorsky Krai logistics cluster specializes in rail-sea intermodal handoffs for e-commerce platform fulfillment.
Ural Federal District
Yekaterinburg's geographic midpoint location supports hub-and-spoke reconfiguration for next-day delivery coverage across Russia's width. Driver working hour regulations constrain labor availability during peak delivery windows in dense urban zones. The Sverdlovsk Oblast industrial base generates B2B palletized freight demand for manufacturing and retail replenishment flows.
Russia Courier Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in customs brokerage and cold chain infrastructure. The vendor base clusters around three concentration nodes: universal postal coverage, superapp urban velocity, and cross-border customs integration. Strategic archetypes include state-anchored universal service providers, digitally native urban logistics platforms, and specialized customs brokerage operators. Competitive moves concentrate on hub-and-spoke network reconfiguration and unified rider pool optimization across demand peaks.
Among Russia-based operators, Russian Post exemplifies the universal coverage archetype through its inherited access point network, while Yandex occupies a position within the superapp ecosystem tier integrating grocery, food, and retail delivery. SDEK-Global LLC represents the cross-border specialization vector with customs brokerage capabilities for Eurasian freight corridors.
| Leading Market Players |
|---|
| Russian Post |
| SDEK-Global LLC |
| Delovye Linii Group |
| DHL Group |
| Pony Express |
| Boxberry |
| Major Express |
| Yandex |
| SberLogistics LLC |
| Others |
Pricing and Supply Chain Analysis
Moscow's automated sorting hubs concentrate capacity for same-day delivery commitments, compressing margins for carriers without superapp ecosystem integration while elevating pricing power for platform-owned fulfillment networks. The Federal Antimonopoly Service's tariff transparency mandates at shared rail terminals constrain incumbent pricing discretion, redirecting competitive leverage toward volume-scale negotiations with large e-commerce platforms.
Pricing Analysis
Volume-discount tiering separates superapp-integrated carriers commanding premium rates for sub-four-hour delivery from mid-sized operators competing on standard multi-day transit economics. Pricing stratifies across premium velocity, standard hub-and-spoke, and economy postal tiers, with differentiation driven by real-time tracking capability and dedicated rider pool access. Cost compression in standard delivery intensifies as platform consolidation squeezes third-party logistics margins through centralized procurement. Price-sensitive marketplace sellers exhibit highest elasticity, while healthcare and pharmaceutical shippers absorb premium rates for validated cold chain custody.
Supply Chain Analysis
Extended payment terms from large e-commerce platforms strain working capital for mid-sized carriers, forcing reliance on supply-chain finance facilities anchored by platform receivables. Fleet assets and sorting infrastructure concentrate manufacturing in China, Germany, and South Korea, with domestic assembly constrained by emissions compliance costs. Diesel-powered last-mile vehicles, automated sorting hardware, and temperature-controlled van bodies constitute critical input dependencies. Single-source vulnerability runs through Chinese-origin line-haul equipment subject to sanctions-related trade friction. Distribution runs through hub-and-spoke networks reconfigured around velocity requirements rather than pure cost optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's courier market fragments across service velocity tiers, with e-commerce platform internalization of fulfillment creating defensive moats for integrated players while opening white space for specialized customs and cold chain operators.
For Market Incumbents: Pre-empt platform disintermediation by deepening captive rider pool density in Moscow and Saint Petersburg, while securing long-term terminal access agreements at Eurasian rail hubs before Federal Antimonopoly Service allocation rules harden. Incumbents lacking superapp integration face substitution by Yandex and SberLogistics ecosystem bundling. Priority lever: backward integration into automated sorting technology to preserve unit economics against volume-based rate compression. For New Entrants and Emerging Players: Secondary Russian cities beyond the Central Federal District present underpenetrated cold chain infrastructure gaps for pharmaceutical logistics specialization. Novosibirsk and Yekaterinburg metropolitan zones lack validated temperature-controlled distribution capacity for biologic shipments. Most penetrable entry vector: customs brokerage integration for Chinese-origin parcel clearance through Vladivostok and Saint Petersburg corridors, replicating SDEK-Global's Eurasian rail-sea positioning. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because platform-owned fulfillment networks will absorb price-insensitive same-day volumes, leaving specialized customs and pharmaceutical logistics as residual acquisition targets. Target archetype: mid-sized carriers with terminal access rights at bottleneck rail facilities and cold chain certification for healthcare verticals. Signal to watch: Federal Antimonopoly Service enforcement intensity at shared cargo terminals as indicator of competitive access preservation.| Strategic Initiative | Industry Significance |
|---|---|
| Superapp Ecosystem Integration | Yandex and SberLogistics unify grocery, food, and retail delivery pools to optimize asset utilization across demand peaks. |
| Cold Chain Infrastructure Expansion | Temperature-controlled pharmaceutical distribution addresses biologic shipment gaps in Novosibirsk and secondary cities. |
| Customs Brokerage Specialization | SDEK-Global's Chinese-origin parcel clearance integration reduces dwell times at Eurasian rail terminals. |
| Hub-and-Spoke Network Reconfiguration | Legacy sorting facilities require capital-intensive retrofitting to handle same-day velocity commitments in Moscow. |
| Rail Terminal Access Securement | Long-term agreements at shared cargo infrastructure preserve competitive positioning under Federal Antimonopoly Service oversight. |
Research Methodology
A spread of perspectives from e-commerce platform logistics directors, courier fleet operations managers, pharmaceutical distribution specialists, and Federal Antimonopoly Service regulatory affairs leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Russian Ministry of Transport infrastructure usage filings, customs digitization protocol documents, and carrier tariff disclosure records. Bottom-up segment sizing triangulated against top-down macroeconomic freight volume indicators.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across service velocity tiers, end-use verticals, infrastructure modalities, and package handling characteristics. CAGRs derived from trend extrapolation of e-commerce penetration rates, fleet renewal cost trajectories, and regulatory compliance burden assessments. Industry-specific forecast inputs included superapp ecosystem expansion timelines and cold chain infrastructure investment pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-owned fulfillment networks or state-backed postal consolidators would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
India Cold Chain Logistics Market