
 Canada Road Freight Transport Market | 2026-2036
Canada Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Road Freight Transport Market Outlook
Subscription-based fleet management software is consolidating control over how carriers price and schedule capacity. TFI International leverages its asset-light model to sustain margins across fragmented lanes. Mullen Group anchors specialized hauling in energy and construction verticals through its partnership network. Bison Transport differentiates with advanced driver-assist platforms that reduce insurance exposure on long-haul routes.
Canada road freight transport encompasses the movement of goods by motor vehicle across federal and provincial highway networks, utilizing power units rated from light-duty vans to Class 8 tractors pulling trailers up to 53 feet in length, with gross vehicle weights governed by provincial permit regimes and the federal Motor Vehicle Transport Act. The sector functions as the dominant surface mode for domestic trade, handling raw materials, finished goods, and temperature-sensitive commodities between manufacturing plants, distribution centers, and retail endpoints. Full truckload operations capture the largest revenue pool, reflecting the geographic span between Prairie agricultural origins and Great Lakes manufacturing clusters. Less than truckload networks are expanding fastest in urban corridors, driven by inventory-light fulfillment strategies among retail and e-commerce end users. Refrigerated trucks command premium pricing, as frozen and fresh food chains require continuous cold-chain integrity across provincial temperature zones.
Transport Canada enforces commercial vehicle safety standards through the National Safety Code, while provincial regulators in Ontario and Alberta administer weight-distance permits and emissions testing protocols that directly affect fleet operating costs and route planning. Health Canada and the Canadian Food Inspection Agency mandate sanitary transport rules for food-grade and pharmaceutical cargo, restricting market access for carriers lacking certified refrigerated equipment or documented chain-of-custody systems. Stakeholders must track how federal clean fuel regulations and provincial zero-emission vehicle mandates reshape capital allocation between diesel replacement cycles and alternative powertrain trials.
Market Dynamics
Federal carbon pricing and provincial clean fuel standards are compressing diesel fleet replacement cycles while e-commerce fulfillment networks absorb capacity from traditional retail lanes across Ontario and Quebec.
Growth Catalysts
- E-commerce fulfillment expansion:Inventory-light retail strategies in the Greater Toronto Area and Montreal corridor are generating sustained demand for less-than-truckload capacity and last-mile injection points.
- Cross-border trade corridors:US-Canada freight lanes through Ontario and British Columbia continue to generate the highest tonnage volumes, driven by integrated automotive and agricultural supply chains.
- Federal Clean Fuel Regulations:Ottawa's escalating carbon intensity requirements are accelerating carrier investment in lower-emission powertrains and renewable diesel blending infrastructure.
Market Restraints
- Diesel price volatility:Fuel constitutes 25-35% of operating costs for long-haul operators, with Prairie-based carriers exposed to wider price spreads than Ontario-based competitors.
- Driver supply concentration:The demographic pipeline for commercial driver's license holders remains thinnest in Atlantic Canada, constraining fleet expansion in that region.
- Weight-distance permit fragmentation:Provincial permit regimes in Ontario, Quebec, and Alberta create route planning friction and compliance cost stacking for multi-jurisdictional operators.
Strategic Opportunities
- Alberta energy corridor specialization:Oilfield services and construction equipment hauling remain underpenetrated by asset-light platforms, favoring specialized heavy-haul operators.
- Refrigerated fleet electrification:Health Canada sanitary transport rules create certification barriers that early movers in battery-electric reefers can exploit for premium pricing.
- Telematics-insurance convergence:Advanced driver-assist platforms are enabling usage-based coverage models that reduce exposure on Trans-Canada Highway routes.
Industry Challenges
- Technician skill gaps:Maintenance facilities lack sufficient capacity for high-voltage powertrain servicing, delaying alternative-fuel vehicle deployment timelines.
- Legacy dispatch system integration:Fleet management software migration creates operational friction for mid-sized carriers running mixed-age tractor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Road Freight Transport Market |
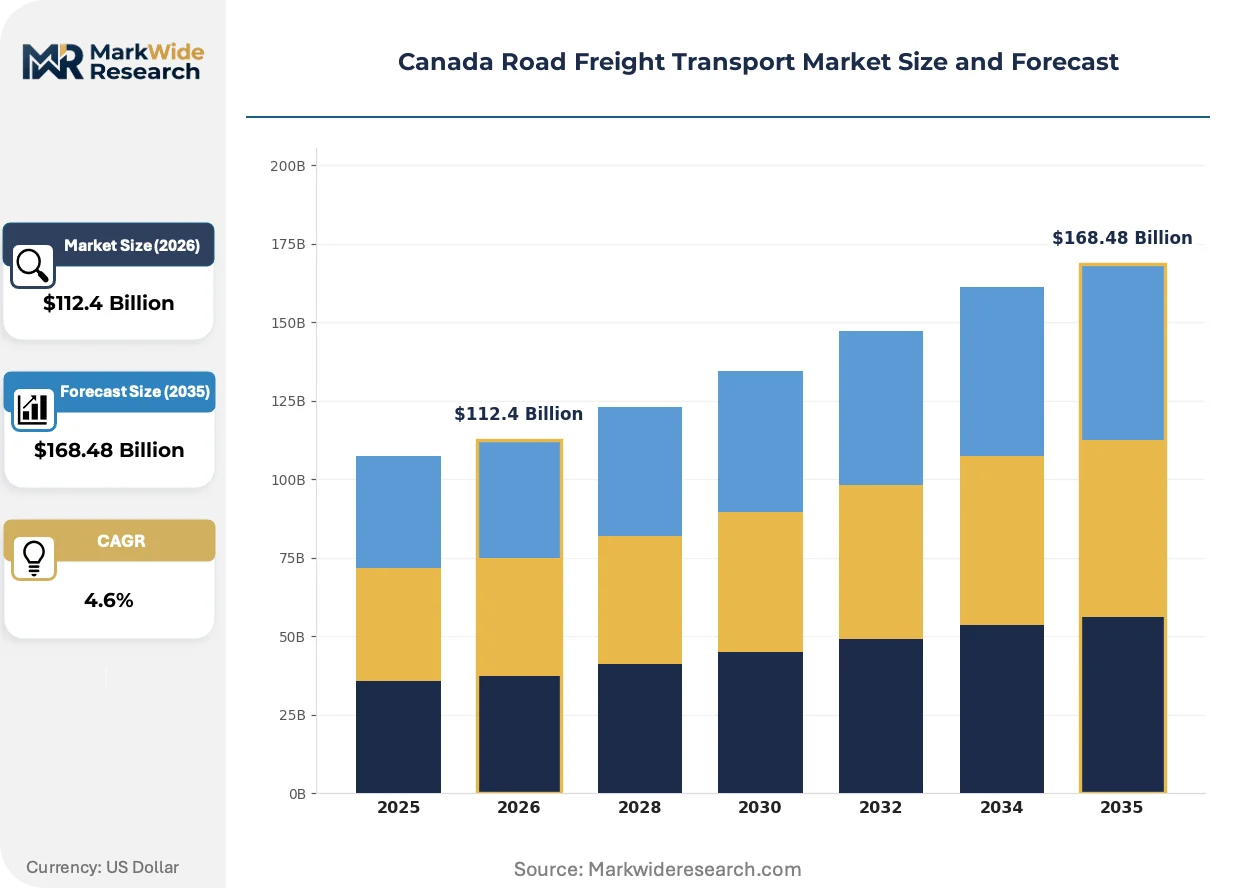
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $168.48 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Expedited Shipping, Specialized Freight Vehicle Type: Flatbed Trucks, Refrigerated Trucks, Tanker Trucks, Box Trucks End User: Retail, Manufacturing, Agriculture, Construction Delivery Model: Direct Delivery, Scheduled Delivery, Intermodal Delivery, Same-Day Delivery |
| Companies Covered | Bison Transport, Canada Cartage, TFI International, Pride Group Logistics, Trimac, Mullen Group, Consolidated Fastfrate, Groupe Robert, Day & Ross, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Road Freight Transport Market Strategic Shifts
Digital freight matching platforms and predictive load algorithms are compressing traditional broker margins while reshaping how capacity is priced and committed across provincial networks.
Telematics-driven fleet management software is consolidating control over carrier pricing and scheduling decisions. Large shippers in the automotive and food processing verticals are mandating API-connected visibility platforms as a condition of contract award. This technology compression is squeezing smaller brokers who lack capital for platform development.
Transport Canada's National Safety Code amendments are tightening electronic logging device enforcement and driver fatigue monitoring requirements. Carriers operating across provincial borders must now harmonize compliance systems to Ontario and Alberta testing protocols. The regulatory burden falls heaviest on owner-operators lacking dedicated safety departments.
Shippers are unbundling transportation management from warehousing contracts, creating standalone procurement events for dedicated fleet capacity. Retail and grocery end-users in the Greater Toronto Area are driving this shift, seeking direct control over inbound freight flows. The separation of services is most visible in temperature-controlled lanes where cold-chain liability remains concentrated with carriers.
Canada Road Freight Transport Market Segmentation
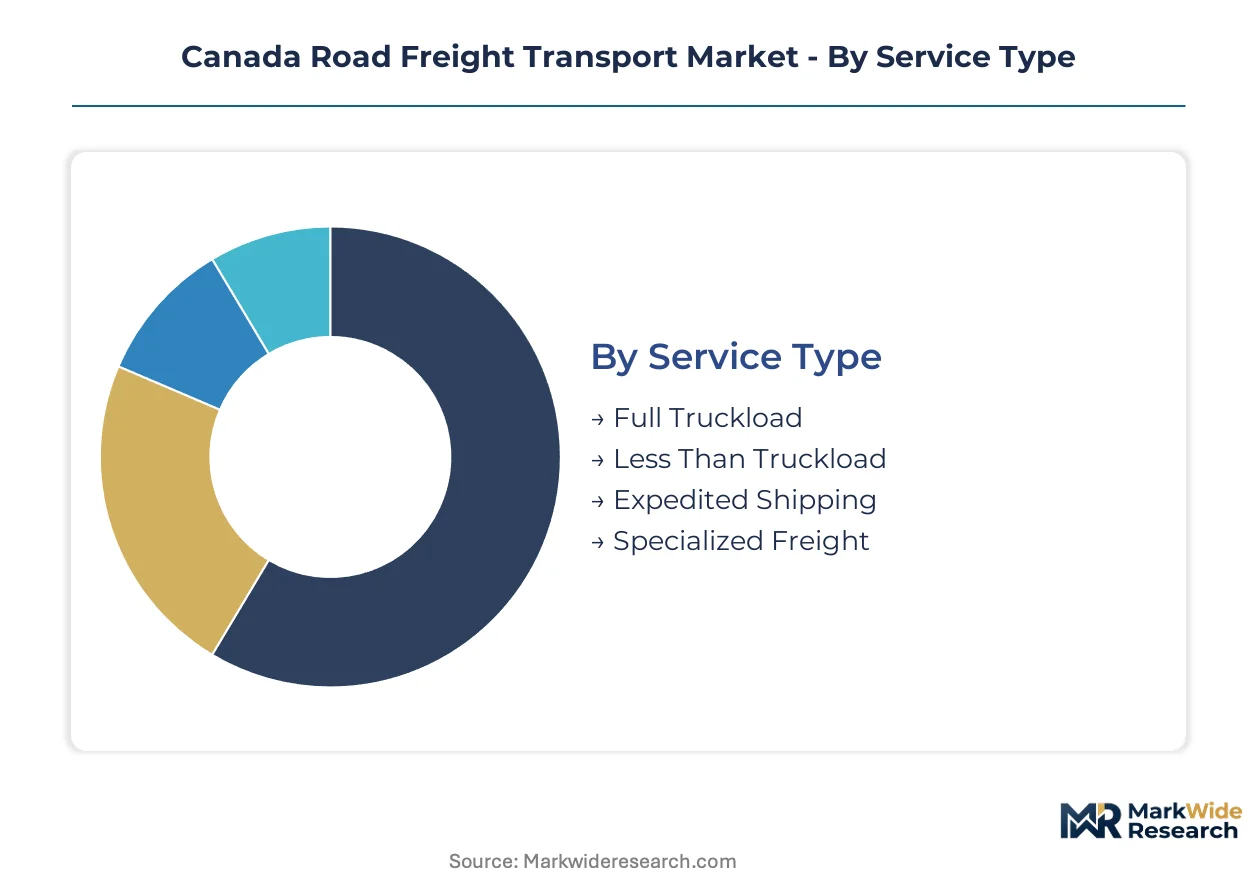
Canada's road freight market fragments across service tiers, equipment specifications, and delivery velocity requirements that shape carrier capital allocation and shipper procurement strategies. Understanding these segment boundaries clarifies where pricing power concentrates and where capacity commoditization erodes margins.
Service Type:
Shippers select service tiers based on inventory carrying cost trade-offs against transportation spend, with route density and load consolidation economics driving the decision calculus.
- Full Truckload:Dedicated tractor-trailer units haul single-shipper cargo from Prairie agricultural origins to Great Lakes manufacturing clusters. Demand concentrates in cross-border US-Canada corridors through Ontario, where automotive and food processing supply chains require high-frequency, scheduled capacity.
- Less Than Truckload:Consolidated multi-shipper shipments move through hub-and-spoke terminal networks, with inventory-light retail strategies in the Greater Toronto Area and Montreal corridor absorbing capacity from traditional retail lanes. E-commerce fulfillment networks are expanding fastest in this segment.
- Expedited Shipping:Time-definite delivery for just-in-line manufacturing and medical supply chains, commanding premium rates for guaranteed transit windows.
- Specialized Freight:Heavy-haul and project cargo requiring permits, escorts, and route engineering for oversized equipment in Alberta energy corridors.
Volume sits with Full Truckload; growth tilts toward Less Than Truckload.
Vehicle Type:
Fleet composition decisions hinge on cargo protection requirements, with temperature sensitivity and hazardous material rules creating equipment specialization barriers.
- Flatbed Trucks:Open-deck trailers haul construction materials, machinery, and agricultural equipment that cannot fit enclosed dimensions. Demand clusters in Alberta oilfield services and Prairie grain handling operations where load dimensions vary seasonally.
- Refrigerated Trucks:Insulated van trailers with integrated refrigeration units maintain cold-chain integrity for frozen and fresh food distribution. Health Canada sanitary transport rules restrict market access to carriers with certified equipment, creating pricing premiums in Ontario-Quebec food processing lanes.
- Tanker Trucks:Cylindrical trailers transport liquid bulk commodities including fuel, chemicals, and food-grade oils under federal and provincial hazardous materials protocols.
- Box Trucks:Straight trucks with enclosed cargo areas serve urban last-mile delivery and light manufacturing feedstock movement in dense metropolitan zones.
Revenue concentrates in Refrigerated Trucks; fleet investment is accelerating fastest in electrified variants of this segment.
End User:
Vertical demand patterns determine lane stability, with seasonal agricultural cycles contrasting against year-round manufacturing rhythms.
- Retail:Distribution center replenishment and store delivery networks, with e-commerce fulfillment driving fragmentation toward smaller, more frequent shipments.
- Manufacturing:Inbound raw materials and outbound finished goods movements, dominated by automotive parts and food processing supply chains in Ontario.
- Agriculture:Seasonal grain, livestock, and equipment hauling from Prairie production zones to export terminals and domestic processors.
- Construction:Building materials, aggregates, and heavy equipment transport tied to residential and infrastructure project cycles.
Manufacturing anchors baseline volume; Retail is expanding most quickly through omnichannel fulfillment requirements.
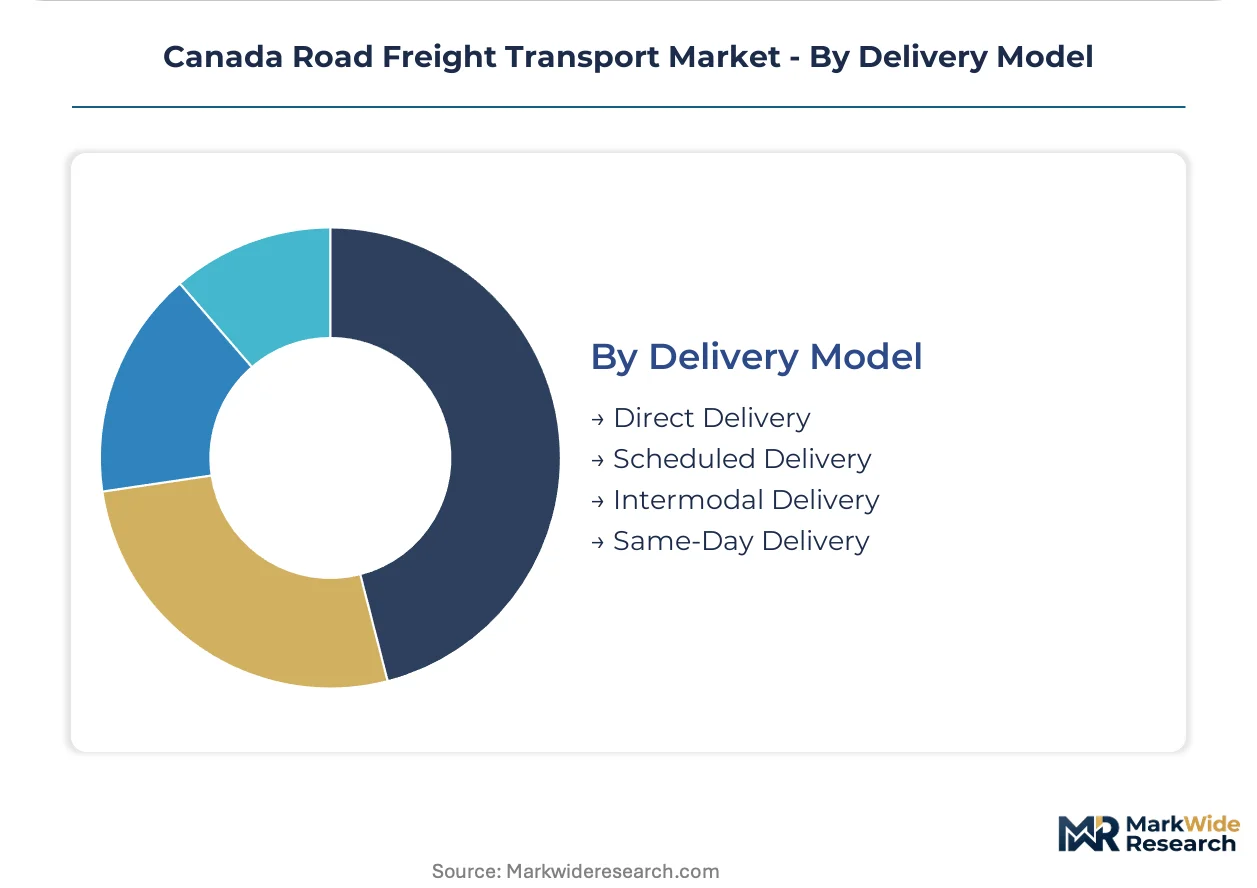
Delivery Model:
Speed premiums and visibility requirements differentiate service offerings, with technology integration becoming a contract qualification threshold.
- Direct Delivery:Point-to-point shipment without intermediate handling, preferred for high-value or time-sensitive cargo where chain-of-custody documentation is critical.
- Scheduled Delivery:Recurring lane assignments with fixed departure windows, supporting manufacturing lean inventory strategies.
- Intermodal Delivery:Truck-rail-truck combinations for long-haul density, with Vancouver and Prince Rupert port connections driving container drayage demand.
- Same-Day Delivery:Urban corridor sprint capacity for pharmaceutical, medical, and high-urgency retail fulfillment in Toronto, Montreal, and Vancouver metropolitan areas.
Scheduled Delivery holds the largest contract value; Same-Day Delivery shows the steepest expansion trajectory as urban fulfillment networks densify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Canada generates heavy-haul demand from resource extraction while Ontario and Quebec absorb the majority of cross-border manufacturing freight. The Prairie Provinces ship bulk agricultural commodities eastward to Great Lakes processors.
Ontario
Automotive parts shipments and food processing supply chains dominate tonnage flows through the Windsor-Detroit corridor. Transport Canada enforces National Safety Code standards that harmonize driver fatigue rules with US Federal Motor Carrier Safety Administration protocols. The Greater Toronto Area functions as the primary e-commerce fulfillment hub, with last-mile networks expanding into suburban distribution nodes.
Quebec
Montreal's port connections generate container drayage demand while provincial clean fuel standards accelerate fleet electrification trials. The provincial transport ministry administers weight-distance permits that create compliance friction for carriers crossing into Ontario. Quebec City and Montreal corridors concentrate refrigerated trucking capacity serving food processing clusters.
Alberta
Oilfield services and construction equipment hauling sustain specialized heavy-haul operators across the Calgary-Edmonton corridor. Federal carbon pricing compresses diesel fleet replacement cycles for operators serving energy sector customers. Fort McMurray and Grande Prairie anchor project cargo movements tied to oil sands and pipeline construction cycles.
British Columbia
Vancouver and Prince Rupert port connections drive intermodal container volumes moving eastward to Prairie distribution centers. Provincial zero-emission vehicle mandates push terminal operators toward electric yard tractors and short-haul battery deployment. The Trans-Canada Highway corridor through Kamloops and Revelstoke carries the highest long-haul insurance exposure in the country.
Atlantic Canada
Seasonal agricultural exports and fish processing shipments generate irregular demand patterns across Nova Scotia and New Brunswick. The demographic pipeline for commercial driver's license holders remains thinnest in this region, constraining fleet expansion. Halifax functions as the primary deep-water port connection for European trade lanes.
Canada Road Freight Transport Market Competitive Environment
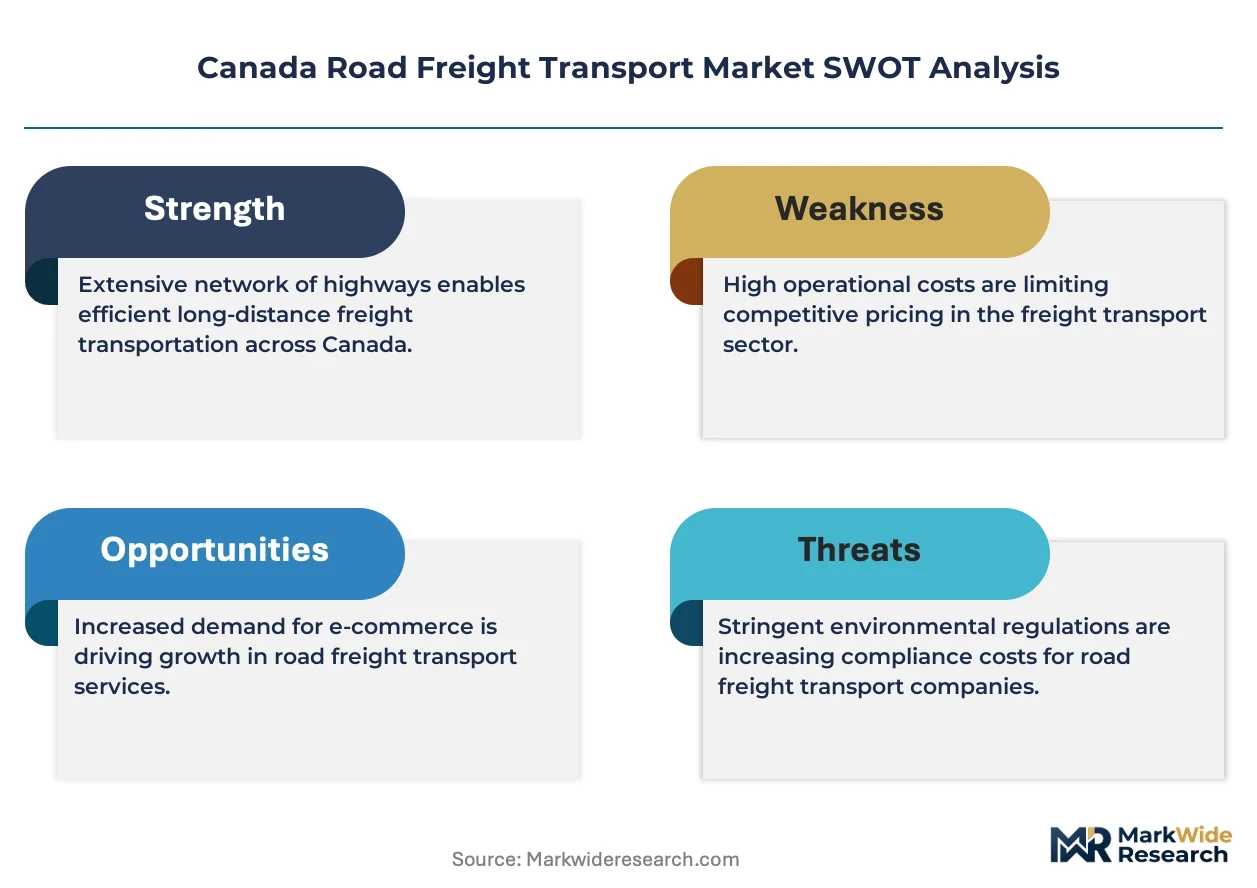
Capital-heavy asset owners compete with asset-light network orchestrators for control of freight pricing and scheduling decisions. The market fragments across specialized heavy-haul operators, diversified national carriers, and regional last-mile specialists. Strategic archetypes include integrated logistics platforms, energy corridor specialists, and technology-enabled safety differentiators. Consolidation pressure concentrates on mid-sized carriers lacking scale for fleet management software investment or alternative powertrain trials.
Among diversified national carriers, TFI International exemplifies the asset-light model that sustains margins across fragmented lanes. Mullen Group anchors specialized hauling in energy and construction verticals through its partnership network. Bison Transport occupies a position within the technology-enabled tier, differentiating through advanced driver-assist platforms that reduce insurance exposure on long-haul routes.
| Leading Market Players |
|---|
| Bison Transport |
| Canada Cartage |
| TFI International |
| Pride Group Logistics |
| Trimac |
| Mullen Group |
| Consolidated Fastfrate |
| Groupe Robert |
| Day & Ross |
| Others |
Value Chain & Pricing Dynamics
Horizontal consolidation among asset-light fleet operators anchors both supply positioning and pricing power across Ontario-Quebec corridors. Carriers integrating dispatch software with shipper procurement platforms capture contract premiums while compressing broker margins in fragmented lanes.
Pricing Analysis
Margin tightening in less-than-truckload tiers reflects e-commerce fulfillment networks absorbing capacity from traditional retail lanes. Contract-based long-term offtake dominates scheduled delivery lanes, with price differentiation hinging on Health Canada cold-chain certification and API-connected visibility platforms. Cost-down pressure on owner-operators accelerates because federal carbon pricing compresses diesel fleet replacement cycles. Small carriers running mixed-age tractor fleets show highest price sensitivity; large automotive shippers with dedicated procurement teams show least.
Supply Chain Analysis
Tractor and trailer manufacturing rests on US, Mexico, and China production clusters for chassis components and refrigeration units. Diesel engine supply draws from Cummins and Detroit Diesel facilities in Indiana and North Carolina, while battery-electric powertrain components source from South Korean and Chinese cell producers. Single-source vulnerability concentrates in semiconductor chips for telematics and driver-assist platforms. Distribution runs through OEM dealer networks and independent maintenance facilities across provincial highway corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management software investment requirements are forcing weaker carriers toward acquisition or exit, consolidating control among scaled platforms.
For Market Incumbents: Lock in cross-border contract renewals through Transport Canada National Safety Code compliance automation before US Federal Motor Carrier Safety Administration harmonization tightens. Acquire refrigerated fleet capacity in Montreal and Toronto corridors to exploit Health Canada sanitary transport certification barriers. Vertical integration into last-mile urban nodes defends margin position against digital freight matching platforms.
For New Entrants and Emerging Players: Launch via specialized heavy-haul partnerships in Alberta energy corridors where asset-light platforms remain underpenetrated. Target oilfield services and construction equipment hauling segments lacking technology-enabled safety differentiation. Pursue telematics-insurance convergence as the go-to-market angle for usage-based coverage models on Trans-Canada Highway routes.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-sized carriers with 50-150 tractor fleets lacking capital for alternative powertrain trials. Long-term viability favors operators with established cross-border US-Canada lane density and integrated dispatch platforms. Watch federal clean fuel regulation enforcement intensity as the signal for accelerated consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Powertrain Deployment | Battery-electric and hydrogen trials in Ontario and Quebec position carriers for provincial zero-emission mandates. |
| Fleet Management Software Integration | API-connected visibility platforms satisfy automotive and food processing shipper procurement requirements. |
| Cold-Chain Certification Investment | Health Canada sanitary transport compliance unlocks premium pricing in temperature-controlled lanes. |
| Cross-Border Lane Density Expansion | Windsor-Detroit corridor concentration captures automotive parts and integrated supply chain volumes. |
| Telematics-Insurance Partnership | Advanced driver-assist data reduces exposure on high-risk Trans-Canada Highway segments. |
Study Parameters
Transport Canada enforcement bulletins, provincial weight-distance permit registries, and carrier financial disclosures formed the secondary backbone for this analysis. Primary interviews with fleet operations directors, shipper procurement managers, insurance underwriters, and maintenance facility operators validated capacity and pricing assumptions. Bottom-up and top-down triangulation cross-checked tractor fleet counts against tonnage flow estimates through provincial border crossings.
Bottom-up modeling aggregated carrier-level capacity and utilization rates across service type, vehicle configuration, and end-use verticals. Segmentation dimensions included full truckload versus less-than-truckload service tiers, refrigerated versus dry van equipment, and cross-border versus domestic lane orientation. CAGRs derived from historical tonnage growth rates adjusted for e-commerce fulfillment network expansion and federal carbon pricing impacts. Forecast inputs incorporated federal Clean Fuel Regulations compliance costs and provincial zero-emission vehicle mandate timelines.
The model assumes a particular technology adoption path; alternative pathways for battery-electric reefers would alter the outlook if high-voltage technician training capacity expands faster than projected. Forecasts reflect assumptions about diesel price volatility and driver supply concentration in Atlantic Canada. A small set of triggers—carbon pricing enforcement intensity, US-Canada trade corridor policy shifts, and telematics platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market