
 China International Courier, Express, and Parcel (CEP) Market | 2026-2036
China International Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
China International Courier, Express, and Parcel (CEP) Market Insights
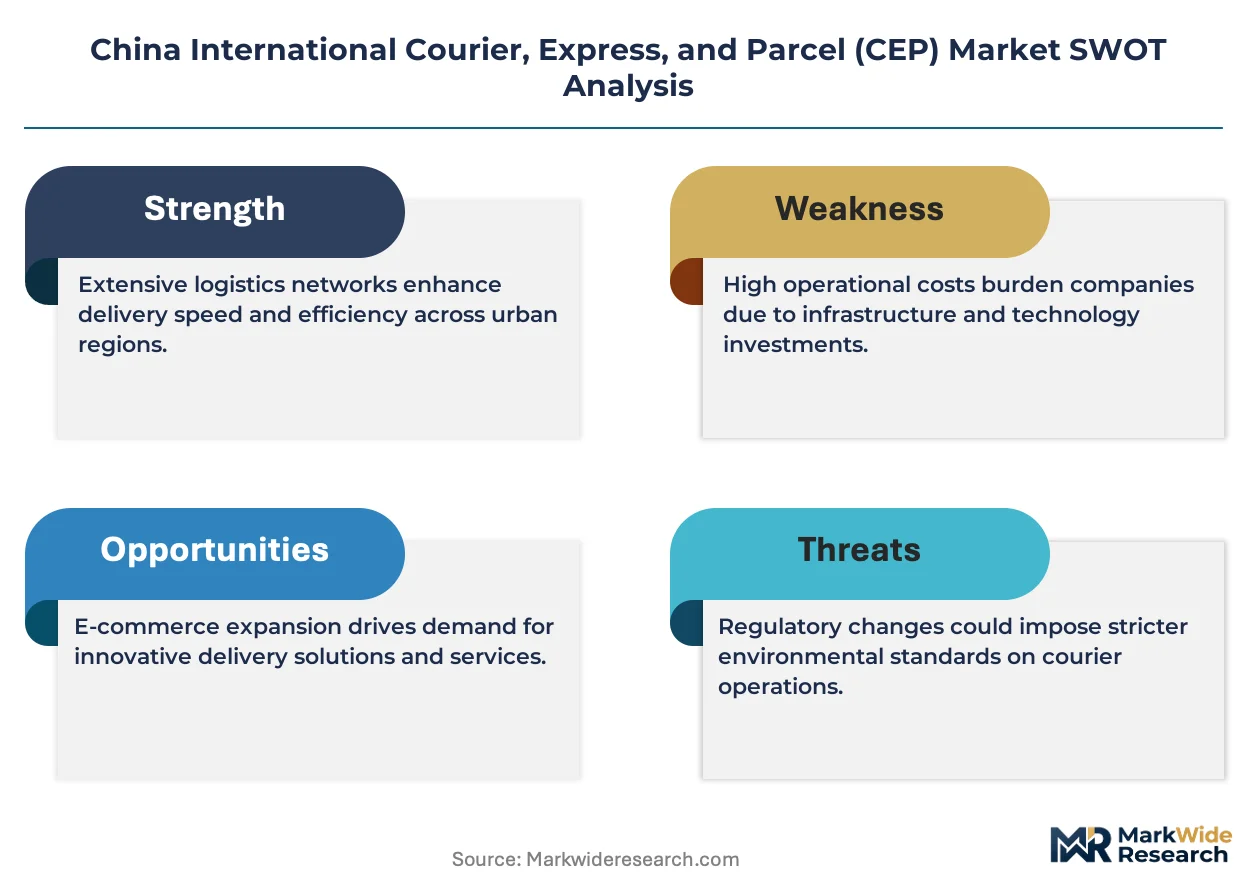
A capital-intensity divergence between asset-heavy integrators and platform-reliant networks is unwinding competitive assumptions across China's international CEP sector. SF Holding leverages its owned freighter fleet and bonded warehouse network to anchor premium cross-border express corridors into Southeast Asia and Europe. ZTO Express sustains cost leadership through hub-and-spoke automation and deep franchisee density, while DHL International GmbH navigates regulatory complexity via licensed joint ventures that secure customs-clearance advantages at major Chinese ports.
China international courier, express, and parcel services constitute time-definite logistics solutions encompassing document envelopes, individual parcels, and palletized freight moved across customs jurisdictions via air, ocean, and land corridors, with transit commitments ranging from same-day to economy standard spanning 3–10 business days. The primary commercial purpose centers on enabling Chinese manufacturers and e-commerce sellers to fulfill orders directly to overseas consumers and businesses with trackable, duty-structured delivery. Express Delivery commands premium tariff tiers and captures disproportionate margin pools on high-value electronics and fashion exports, while E-commerce as a delivery model is reshaping volume composition as platforms embed logistics into checkout workflows. Automated Sorting within the technology dimension is concentrating capital deployment as operators seek throughput gains at hub facilities processing millions of international parcels nightly.
China's MIIT sets telecommunications and data-localization standards that constrain foreign operators' track-and-trace architectures, while SAMR enforces antitrust scrutiny on platform-exclusive logistics arrangements that affect merchant choice. The country's GB standards for packaging recyclability and MEE emissions rules for commercial vehicle fleets are tightening operational compliance costs for cross-border parcel movements. Stakeholders must monitor how customs digitization initiatives and carbon-border adjustment mechanisms abroad reshape cost structures and routing decisions for China-originated international shipments.
Market Dynamics
China's dual carbon goals are compressing fleet replacement timelines and forcing capital reallocation toward electric vehicle infrastructure and automated sorting systems across the Yangtze River Delta corridor.
Growth Catalysts
- Cross-border e-commerce expansion:Chinese merchants are building direct-to-consumer fulfillment networks in Southeast Asia and Europe, pulling parcel volumes through dedicated express corridors.
- MIIT data-localization standards:Domestic compliance requirements for track-and-trace architectures favor operators with localized server infrastructure and bonded warehouse digitization.
- Automated sorting deployment:Hub-and-spoke automation at Shanghai Pudong and Hangzhou Xiaoshan airports is compressing per-parcel handling costs for international express flows.
Market Restraints
- Aviation fuel cost volatility:Freighter operators face margin compression from jet fuel price swings that resist full pass-through on contracted lanes.
- Customs clearance concentration:Licensed joint venture requirements at Ningbo-Zhoushan and Shenzhen ports create bottleneck dependencies for foreign operators.
- GB packaging recyclability mandates:Compliance with national packaging standards adds material cost premiums for cross-border parcel movements.
Strategic Opportunities
- Central and Western China penetration:Chengdu and Chongqing offer underdeveloped export parcel infrastructure with growing manufacturing bases for European rail corridors.
- Carbon-border adjustment alignment:MEE emissions rules for commercial fleets position early EV adopters to capture preferential routing into EU markets.
- Blockchain-customs convergence:Integration of distributed ledger systems with SAMR digitization initiatives promises pre-clearance acceleration for high-volume shippers.
Industry Challenges
- Freighter pilot certification scarcity:Qualified flight crew availability constrains fleet expansion timelines for owned-aircraft operators.
- Legacy warehouse management integration:Bonded facility operators face system fragmentation when connecting automated sorting to customs declaration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China International Courier, Express, and Parcel (CEP) Market |
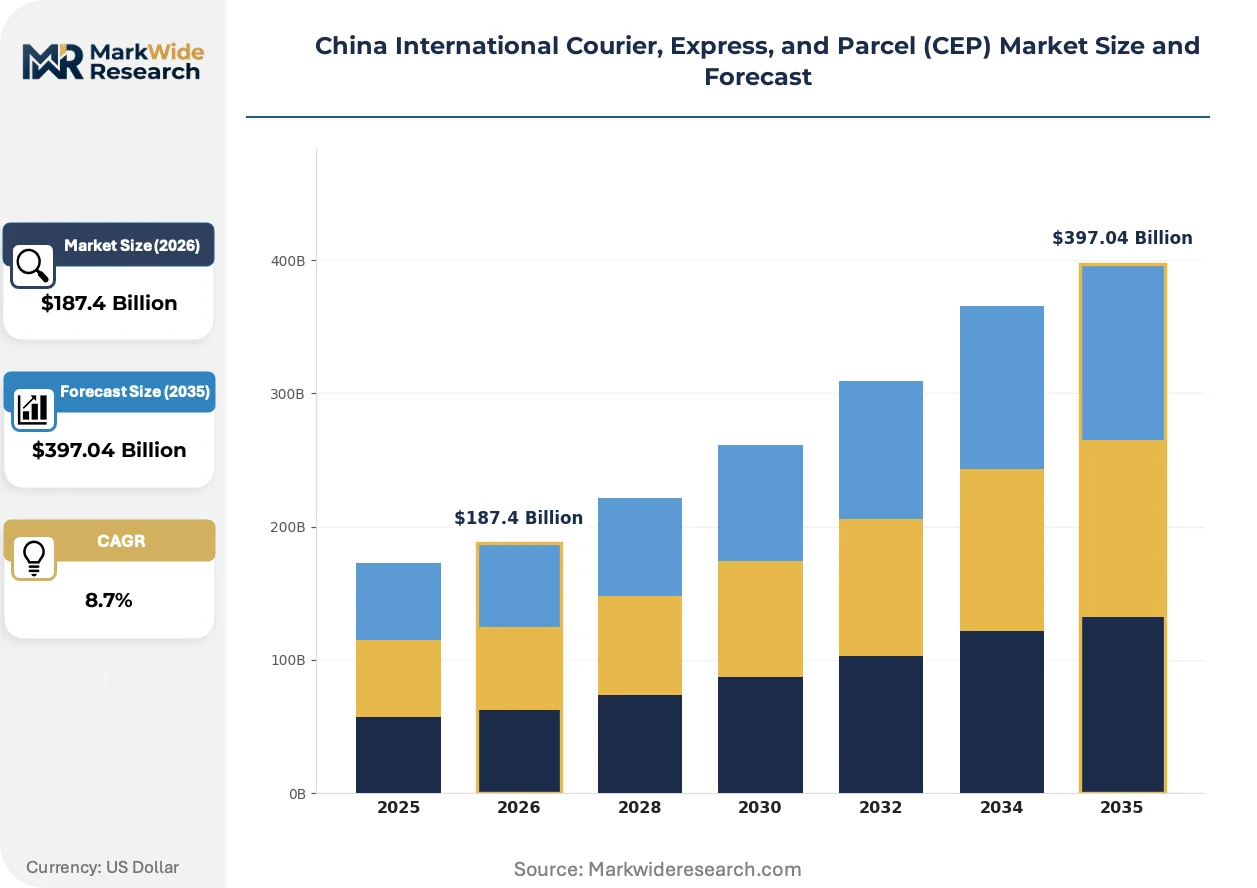
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Shipping, Same-Day Delivery, Next-Day Delivery Delivery Model: Business-to-Business, Business-to-Consumer, Consumer-to-Consumer, E-commerce Packaging Type: Parcel, Document, Pallet, Custom Packaging Technology: Track & Trace, Automated Sorting, Drone Delivery, IoT Solutions |
| Companies Covered | SF Holding, ZTO Express, China Postal Express & Logistics Co. Ltd, STO Express Co. Ltd, YTO Express Group Co. Ltd, Yunda Holdings, Kerry EAS Logistics Ltd, FedEx, DHL International GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China International Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital infrastructure investments are fragmenting traditional hub economics while regulatory pressure on emissions and data sovereignty reshapes operator technology roadmaps.
Automated robotic sorting is decomposing labor-intensive hub operations across Shanghai and Hangzhou facilities. Third-party logistics providers and platform-owned networks are deploying vision-guided parcel handling at throughput rates exceeding manual processing capacity. This compression of unit handling costs is decomposing the historical cost advantage of franchisee-dependent networks in high-volume export corridors.
MEE commercial vehicle emissions rules are accelerating electric freight vehicle procurement timelines for last-mile and airport feeder operations. Fleet operators face total-cost-of-ownership recalculations as battery-electric truck availability expands from urban delivery to longer-haul port connections. Express operators with captive charging infrastructure at bonded warehouses capture preferential customs processing slots in Shanghai and Shenzhen pilot zones.
Merchant procurement of logistics services is consolidating around platform-embedded checkout workflows. Cross-border e-commerce sellers are abandoning standalone freight contracts in favor of integrated fulfillment solutions offered by marketplace operators. This channel shift concentrates volume allocation decisions within Hangzhou and Shenzhen platform headquarters, displacing traditional freight forwarder relationships in consumer electronics and fashion verticals.
China International Courier, Express, and Parcel (CEP) Market Segmentation
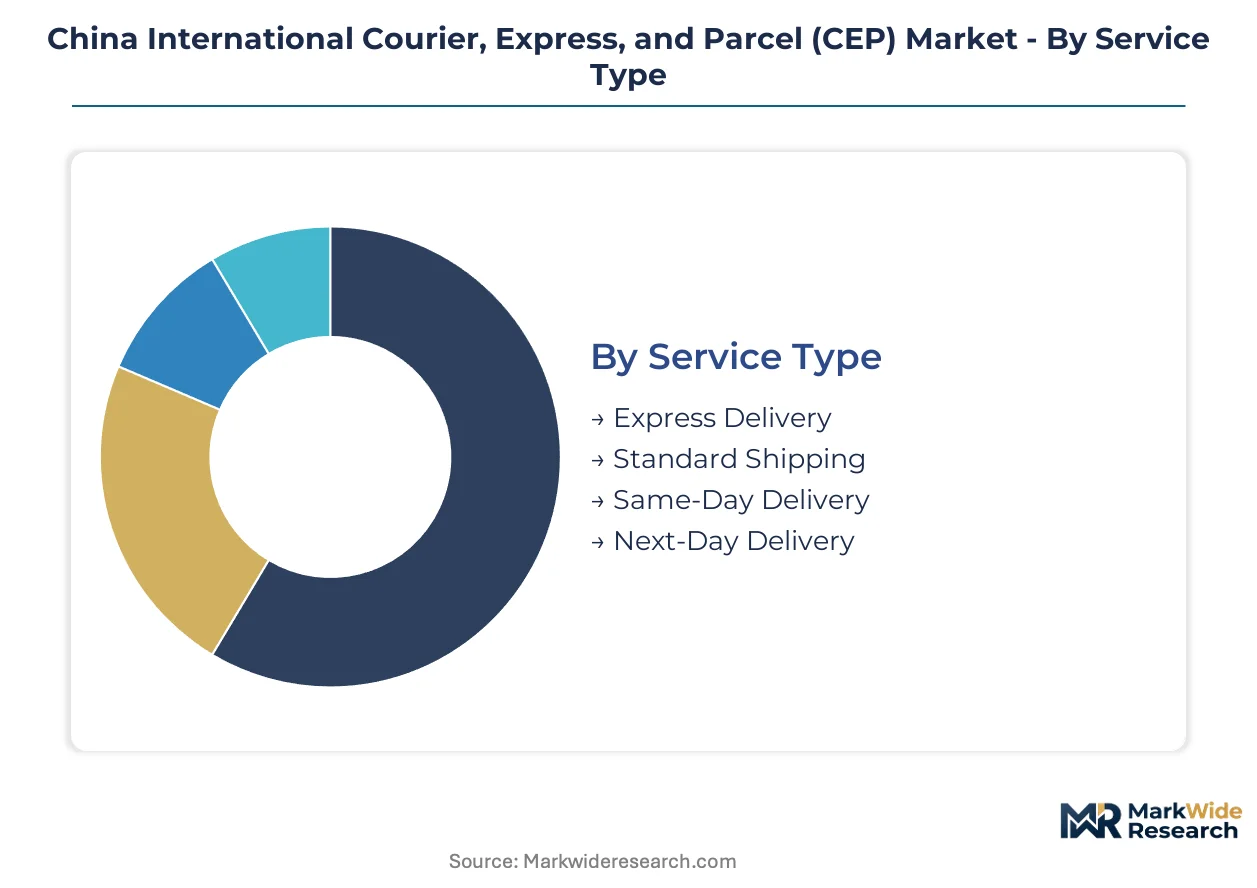
Segmentation in China's international CEP market determines tariff structures, capital deployment, and regulatory compliance pathways. Service tier and delivery model classifications shape customs clearance procedures and carbon intensity calculations under MEE emissions rules.
Service Type:
MIIT data-localization standards differentiate service tiers through track-and-trace architecture requirements and bonded warehouse digitization mandates.
- Express Delivery:Time-definite air freight with dedicated freighter capacity and pre-cleared customs corridors. Electronics and fashion exports from Shanghai Pudong and Hangzhou Xiaoshan concentrate here, with SAMR antitrust scrutiny affecting platform-exclusive arrangements.
- Standard Shipping:Economy ocean and land corridors with 5–10 day transit commitments. Cost-sensitive manufacturing exports from Suzhou industrial parks favor this tier, though aviation fuel pass-through limitations constrain margin recovery.
- Same-Day Delivery:Ultra-time-definite service requiring captive air feeder networks and bonded facility proximity.
- Next-Day Delivery:Premium overnight service leveraging automated sorting at Yangtze River Delta hubs.
Express Delivery handles the majority of throughput; Same-Day Delivery is expanding most quickly on share.
Delivery Model:
Customer relationship structures determine platform integration depth and fulfillment network ownership economics.
- E-commerce:Platform-embedded checkout workflows consolidating volume allocation within Hangzhou and Shenzhen headquarters. Cross-border sellers abandon standalone freight contracts for integrated solutions, displacing traditional forwarder relationships in consumer electronics.
- Business-to-Business:Contracted lane structures with palletized freight and customs-bonded warehousing for manufacturing supply chains.
- Business-to-Consumer:Direct merchant-to-buyer shipments with duty-structured delivery and trackable last-mile handoff.
- Consumer-to-Consumer:Individual sender arrangements with higher per-unit handling costs and fragmented customs documentation.
E-commerce commands the dominant volume position; Business-to-Consumer shows the steepest expansion trajectory.
Packaging Type:
GB standards for packaging recyclability impose material cost premiums that vary by shipment configuration.
- Parcel:Individual cartons and polybags constituting the core international CEP volume. Cross-border e-commerce merchants in the Yangtze River Delta generate concentrated flows through automated sorting facilities at Shanghai and Hangzhou airports.
- Document:Lightweight envelopes with expedited customs clearance and reduced dimensional weight calculations.
- Pallet:Consolidated freight units for Business-to-Business manufacturing supply chains with bonded warehouse staging.
- Custom Packaging:Branded or protective configurations for high-value electronics and luxury goods requiring specialized handling protocols.
Parcel moves the largest absolute volumes; Custom Packaging is climbing the fastest on revenue per unit.
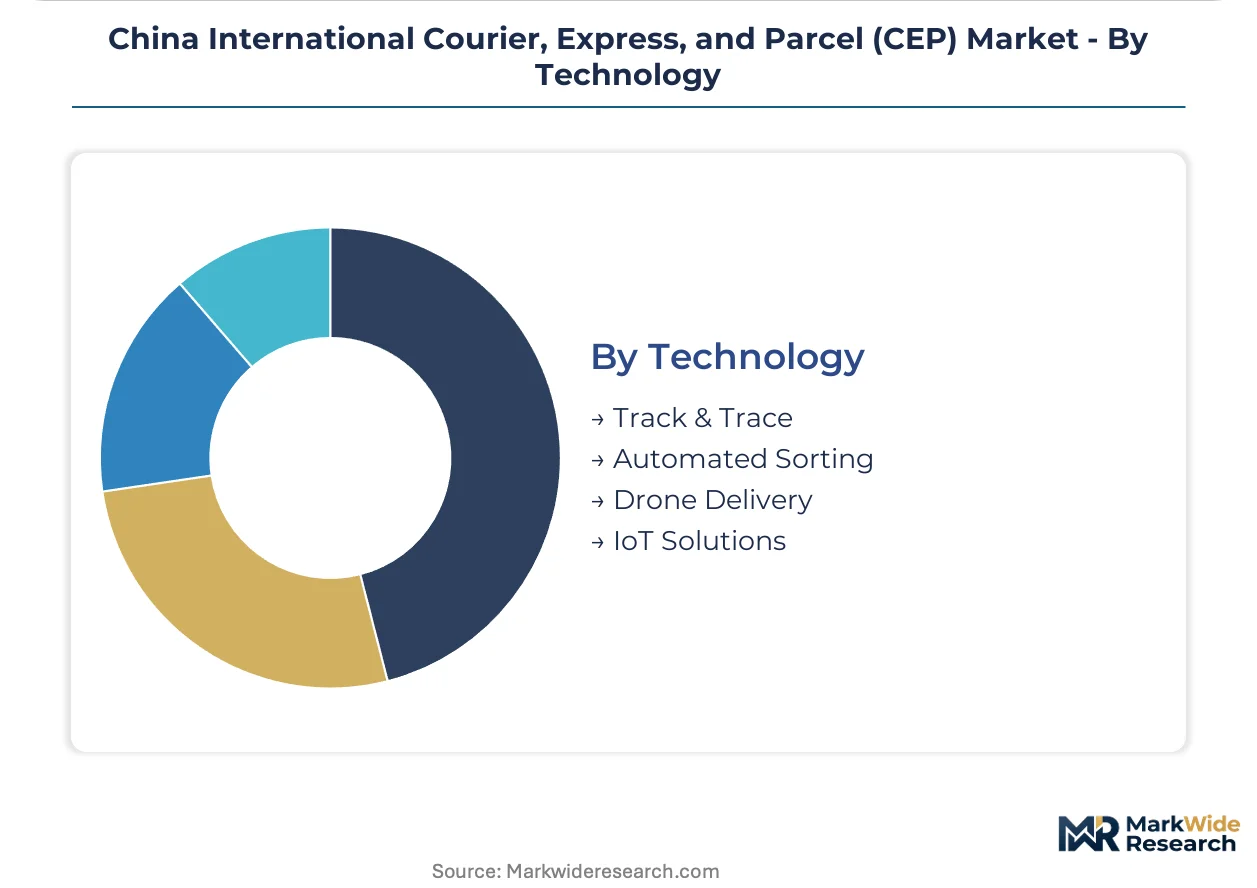
Technology:
Capital deployment intensity separates operators with captive infrastructure from platform-reliant networks.
- Automated Sorting:Vision-guided robotic handling at throughput rates exceeding manual capacity. Hub operations at Shanghai Pudong and Hangzhou Xiaoshan compress per-parcel costs and decompose franchisee-dependent network advantages in high-volume export corridors.
- Track & Trace:MIIT-compliant data-localization architectures with localized server infrastructure and bonded warehouse digitization.
- IoT Solutions:Sensor-enabled cargo monitoring for temperature-sensitive and high-value shipments across multimodal corridors.
- Drone Delivery:Last-mile automation pilot programs constrained by airspace regulations and payload limitations.
Automated Sorting absorbs the dominant capital share; IoT Solutions is gaining share fastest in premium service tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Yangtze River Delta while cost advantages persist in Central and Western China, creating a two-tier geography for international parcel economics.
Yangtze River Delta
Shanghai, Hangzhou, and Suzhou generate concentrated export parcel flows through automated sorting hubs at Pudong and Xiaoshan airports. MIIT data-localization standards favor operators with localized server infrastructure in this corridor. Bonded warehouse digitization at Shanghai Free Trade Zone compresses customs clearance timelines for electronics and fashion exports.
Pearl River Delta
Shenzhen and Guangzhou anchor cross-border e-commerce fulfillment with platform headquarters driving volume allocation decisions. SAMR antitrust scrutiny affects logistics arrangements for consumer electronics merchants. Licensed joint venture requirements at Shenzhen ports create customs-clearance dependencies for foreign operators serving Southeast Asian corridors.
Beijing-Tianjin-Hebei
Capital-region demand centers on document and high-value parcel express services for corporate headquarters and government procurement. MEE emissions rules for commercial vehicle fleets accelerate electric freight vehicle procurement for airport feeder operations. Bonded logistics parks at Tianjin Port serve European rail corridor connections.
Sichuan-Chongqing
Chengdu and Chongqing offer underdeveloped export parcel infrastructure with growing manufacturing bases for European rail corridors. Dual carbon goals compress fleet replacement timelines for logistics operators establishing presence in this western hub. Chongqing's bonded port zone attracts automated sorting investments for Central Asian and European overland routes.
Shandong Peninsula
Qingdao and Yantai concentrate automotive and machinery exports requiring palletized freight and customs-bonded warehousing. GB standards for packaging recyclability add material cost premiums for cross-border parcel movements from this industrial base. Port automation investments at Qingdao compete with Yangtze River Delta hubs for Northeast Asian express volumes.
China International Courier, Express, and Parcel (CEP) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's international CEP sector. Asset-heavy integrators with owned freighter fleets and bonded warehouse networks compete against platform-reliant networks leveraging hub-and-spoke automation and franchisee density. The market structure fragments across three strategic archetypes: captive infrastructure operators, franchise-dependent scale players, and licensed joint venture specialists. Dominant competitive moves include automated sorting deployment at Yangtze River Delta hubs and electric vehicle fleet procurement aligned with MEE emissions rules.
Within the captive infrastructure tier, SF Holding exemplifies asset-heavy positioning through owned freighter capacity and bonded warehouse networks. ZTO Express occupies a position representing cost leadership through hub-and-spoke automation and deep franchisee density. DHL International GmbH sits within the licensed joint venture archetype, navigating regulatory complexity through partnerships securing customs-clearance advantages at major Chinese ports.
| Leading Market Players |
|---|
| SF Holding |
| ZTO Express |
| China Postal Express & Logistics Co. Ltd |
| STO Express Co. Ltd |
| YTO Express Group Co. Ltd |
| Yunda Holdings |
| Kerry EAS Logistics Ltd |
| FedEx |
| DHL International GmbH |
| Others |
Pricing and Supply Chain Analysis
Freighter fleet utilization rates at Shanghai Pudong and Hangzhou Xiaoshan anchor both supply concentration and price floors across China's international CEP corridors. Scale economies in automated sorting infrastructure compress per-parcel handling costs while simultaneously raising capital barriers that protect incumbent pricing power against franchisee-dependent challengers.
Pricing Analysis
The customization-premium spread between configured-to-order express services and standard economy shipping widens as platform-embedded checkout workflows consolidate volume allocation decisions. Three-tier pricing structure across premium, standard, and economy levels captures divergent service commitments, with Express Delivery commanding tariff premiums on high-value electronics and fashion exports. Cost compression in Standard Shipping intensifies because aviation fuel pass-through limitations constrain margin recovery on ocean and land corridors. Cross-border e-commerce merchants show highest price sensitivity, while time-definite manufacturing supply chains demonstrate lowest elasticity.
Supply Chain Analysis
Port congestion at Ningbo-Zhoushan and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for bonded warehouse replenishment. Supply concentration rests on China, South Korea, and Japan for automated sorting equipment and electric freight vehicle components, with specialized aviation fuel sourcing tethered to Singapore and Middle Eastern refining hubs. Single-source vulnerability in licensed joint venture customs clearance at Shenzhen ports creates bottleneck dependencies for foreign operators. Distribution runs through hub-and-spoke networks anchored at Yangtze River Delta airports with last-mile fragmentation into franchisee-operated terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping China's international CEP sector as merchant procurement consolidates around integrated fulfillment solutions that embed logistics into checkout workflows, displacing traditional freight forwarder relationships through interoperability mandates from Hangzhou and Shenzhen headquarters.
For Market Incumbents: Consolidate captive infrastructure advantages by deepening electric vehicle fleet deployment at bonded warehouses to capture preferential customs processing slots in Shanghai and Shenzhen pilot zones. Expand automated sorting capacity at Xiaoshan and Pudong facilities to compress unit costs below franchisee-dependent network thresholds. Platform-owned logistics networks represent the primary substitution threat; vertical integration into charging infrastructure secures regulatory alignment with MEE emissions rules.
For New Entrants and Emerging Players: GB standards certification fast-track for packaging recyclability compliance opens procurement channels with cross-border e-commerce merchants facing material cost premium pressures. Central and Western China penetration offers underdeveloped export parcel infrastructure with growing manufacturing bases for European rail corridors from Chengdu and Chongqing. Blockchain-customs convergence with SAMR digitization initiatives provides a differentiated go-to-market angle for pre-clearance acceleration services.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with platform-embedded checkout workflows and captive bonded warehouse networks. Long-term viability over the analysis window favors asset-heavy integrators with owned freighter capacity over franchisee-dependent scale players facing automation-driven cost compression. The acquisition target archetype combines automated sorting infrastructure with EV fleet deployment aligned to dual carbon goals. Carbon-border adjustment mechanism implementation in EU markets serves as the critical inflection indicator for preferential routing advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Deployment | Vision-guided robotic handling at Shanghai Pudong compresses per-parcel costs below manual franchisee networks. |
| Electric Vehicle Fleet Procurement | Captive charging infrastructure at bonded warehouses secures preferential customs processing slots under MEE rules. |
| Platform Integration Partnership | Embedded checkout workflows in Hangzhou headquarters consolidate volume allocation away from standalone freight contracts. |
| Licensed Joint Venture Expansion | Customs-clearance advantages at Ningbo-Zhoushan and Shenzhen ports navigate regulatory complexity for foreign operators. |
| Blockchain-Customs Convergence | Distributed ledger integration with SAMR digitization initiatives accelerates pre-clearance for high-volume cross-border shippers. |
Research Methodology
A standing panel of express operations directors, bonded warehouse managers, cross-border e-commerce logistics procurement leads, and MIIT compliance officers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from customs digitization policy filings, SAMR antitrust disclosure records, MEE emissions compliance databases, and Yangtze River Delta port authority throughput statistics. Bottom-up parcel volume modeling and top-down market sizing triangulated against operator capacity disclosures.
Consistency checks validated volume and value outputs against external benchmarks including aviation fuel price indices, freighter fleet deployment registries, and automated sorting equipment installation records across the projection horizon. The analytical framework modeled service type, delivery model, packaging configuration, and technology adoption dimensions alongside regional regulatory cluster variations. CAGRs derived from logistic curve penetration analysis of automated infrastructure deployment and EV fleet replacement timelines, with cross-border e-commerce growth rates and dual carbon policy compliance schedules as industry-specific forecast inputs.
Underlying assumptions cover MIIT data-localization standard enforcement continuity, aviation fuel price band stability, and licensed joint venture regulatory framework persistence, with deviation risk concentrated in carbon-border adjustment mechanism implementation timing and customs digitization initiative acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Malaysia Road Freight Transport Market