
 Australia Freight Forwarding Market | 2026-2036
Australia Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Freight Forwarding Market Insights
Modular service bundling is shifting buyer choice across the Australia freight forwarding sector as importers and exporters unbundle single-carrier contracts into multi-leg, multi-modal arrangements. DHL Group leverages its integrated air-ocean network to dominate time-sensitive pharmaceutical lanes into Sydney and Melbourne. Kuehne + Nagel anchors its position through specialized project cargo expertise serving Western Australia's LNG and mining infrastructure. DB Schenker competes on rail-road intermodal density along the Melbourne-Brisbane corridor.
Freight forwarding comprises the coordination and facilitation of cargo movement across international and domestic supply chains through carrier negotiation, customs brokerage, documentation management, and cargo consolidation, typically operating under FIATA-standardized bills of lading and multimodal transport contracts. The primary commercial purpose centers on reducing shipper logistics complexity while optimizing cost-to-service ratios across volatile capacity markets. Ocean freight retains the largest revenue pool given Australia's island geography and bulk commodity export base, though air freight captures disproportionate margin concentration in temperature-controlled pharmaceuticals and high-value electronics. Digital platforms represent the fastest-growing technology segment as real-time visibility becomes a baseline procurement requirement rather than a premium add-on.
The National Heavy Vehicle Regulator enforces chain-of-responsibility laws that reshape liability allocation across consigners, packers, and transport operators, while the Australian Border Force's Trusted Trader program accelerates customs clearance for accredited forwarders. Biosecurity regulations administered by the Department of Agriculture impose strict pre-shipment treatment requirements on wooden packaging and agricultural cargo entering Australian ports. Stakeholders must monitor how the Safeguard Mechanism reforms alter carbon accounting for road and rail freight contracts.
Market Dynamics
Modular service bundling is fragmenting long-term carrier contracts across Australian freight forwarding as importers and exporters disaggregate single-provider agreements into multi-modal, multi-leg arrangements governed by dynamic spot-market pricing.
Growth Catalysts
- Heavy Vehicle National Law reform:Chain-of-responsibility obligations now extend liability to consigners and packers, creating compliance-driven demand for accredited forwarders with integrated audit capabilities.
- Queensland resource corridor expansion:Coal and LNG terminal throughput at Gladstone Port is concentrating logistics demand along dedicated heavy-haul routes into the Bowen Basin.
- Cold-chain infrastructure:Mining exporters are retrofitting reefer capacity for perishable commodities, opening temperature-controlled lanes previously served by general cargo operators.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations compress margins for road-dominant operators serving Melbourne-Brisbane intermodal corridors.
- Biosecurity treatment mandates:Department of Agriculture pre-shipment requirements for wooden packaging and agricultural cargo add processing delays at Australian port entry points.
- Rail capacity concentration:Limited track infrastructure between Pilbara mining zones and Fremantle Port creates bottleneck risk for Western Australia bulk exports.
Strategic Opportunities
- Trusted Trader program acceleration:Australian Border Force accreditation offers expedited customs clearance, enabling forwarders to capture premium pricing for time-sensitive pharmaceutical lanes.
- Digital platform convergence:Real-time visibility systems are merging with predictive analytics, creating integrated cargo-tracking offerings for Sydney and Melbourne metropolitan distribution.
- Safeguard Mechanism carbon accounting:Emissions measurement requirements for road and rail contracts favor forwarders with verified low-carbon transport options.
Industry Challenges
- Intermodal integration complexity:Legacy port community systems in Brisbane and Fremantle resist API connectivity with newer cloud-based freight management platforms.
- Specialized project cargo expertise scarcity:LNG and mining infrastructure logistics require heavy-lift certification that few Australian operators maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Freight Forwarding Market |
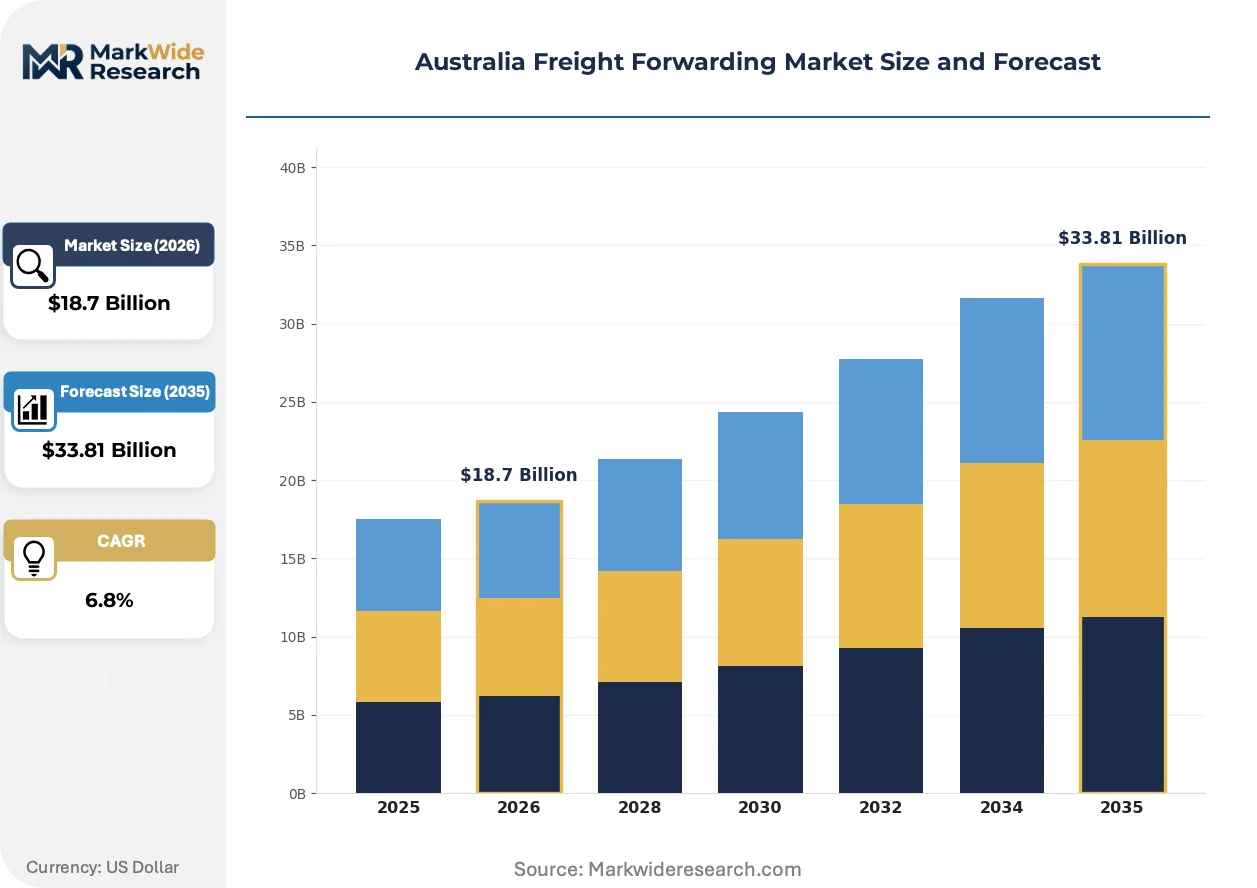
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ocean Freight, Air Freight, Rail Freight, Road Freight Customer Type: Importers, Exporters, Manufacturers, Retailers Delivery Mode: Door-to-Door, Port-to-Port, Port-to-Door, Door-to-Port Technology: Track and Trace, Automated Billing, Digital Platforms, Cargo Monitoring |
| Companies Covered | DB Schenker, DHL Group, Kuehne + Nagel, BCR Australia, Think Global Logistics, Stockwell International, Magellan Logistics, CargoMaster, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Freight Forwarding Market Trends and Innovations
Digital visibility platforms are converging with automated documentation systems across Australian freight forwarding, compressing the traditional information lag between shipper and carrier into near-real-time coordination.
Blockchain-enabled bills of lading are converging with smart contract settlement mechanisms, allowing mining and agricultural exporters to automate payment release upon verified container discharge. Major commodity shippers in Western Australia and Queensland are piloting these systems for high-volume iron ore and grain lanes. This convergence is compressing working capital cycles and reducing documentary discrepancy disputes that previously tied up cargo release.
The National Heavy Vehicle Regulator's chain-of-responsibility enforcement is tightening liability allocation across consigners, packers, and transport operators, forcing forwarders to maintain auditable compliance documentation. Road freight contracts now require explicit safety management system attestations. Queensland resource corridors and New South Wales interstate routes face the strictest audit frequency, with operators investing in telematics to demonstrate fatigue management compliance.
Shippers are unbundling long-term carrier contracts into modular, spot-market components, replacing annual rate agreements with dynamic procurement across air, ocean, and rail legs. Pharmaceutical importers around Sydney Airport and Melbourne's Port Phillip zone are driving this fragmentation, seeking cost optimization through competitive tendering of individual transport segments. This pattern concentrates among temperature-sensitive cargo owners with sufficient shipment volume to justify internal logistics coordination overhead.
Australia Freight Forwarding Market Segmentation
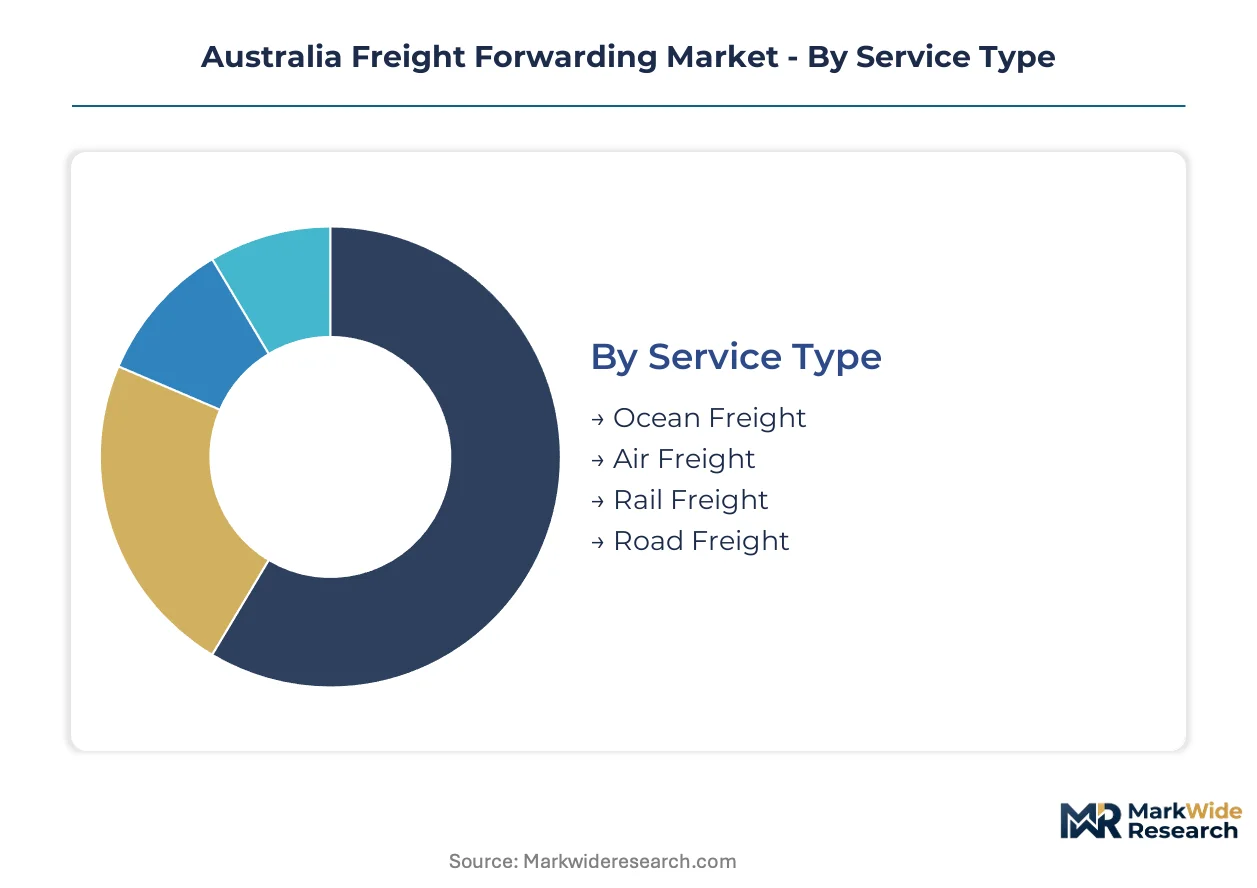
Freight forwarding in Australia fragments across service modes, customer profiles, delivery configurations, and technology stacks. Each dimension carries distinct margin profiles and regulatory exposure that shape procurement decisions across mining, pharmaceutical, and retail supply chains.
Service Type:
Ocean freight dominates tonnage volumes while air freight commands premium margins; rail and road split intermodal responsibilities across resource corridors and metropolitan distribution zones.
- Ocean Freight:Full-container-load and breakbulk operations move Australia's iron ore, coal, and agricultural exports through Gladstone, Fremantle, and Port Botany. Mining exporters in Western Australia's Pilbara and Queensland's Bowen Basin concentrate demand here, though port congestion and biosecurity treatment mandates create scheduling uncertainty.
- Air Freight:Temperature-controlled pharmaceutical shipments and high-value electronics utilize Sydney and Melbourne airports for time-sensitive lanes. Cold-chain certification requirements and Australian Border Force Trusted Trader accreditation filter operator participation, compressing the qualified vendor pool.
- Rail Freight:Bulk commodity movements and intermodal containers traverse the Melbourne-Brisbane corridor and Pilbara port linkages. Track capacity constraints between mining zones and Fremantle create bottleneck risk during peak export windows.
- Road Freight:Final-mile distribution and heavy-haul resource corridor movements operate under National Heavy Vehicle Regulator chain-of-responsibility enforcement. Diesel cost volatility and fatigue management compliance costs pressure operator margins.
Mature deployment sits with ocean freight. Newer deployment is concentrated in integrated rail-road intermodal solutions.
Customer Type:
Volume concentration differs from margin concentration—exporters drive bulk tonnage while importers generate higher per-shipment service fees through customs complexity and last-mile coordination.
- Exporters:Mining and agricultural commodity shippers in Western Australia and Queensland dominate tonnage, requiring project cargo expertise and heavy-lift capabilities for LNG infrastructure components. Their procurement emphasizes cost-per-ton optimization over speed.
- Importers:Pharmaceutical distributors and electronics retailers around Sydney and Melbourne prioritize customs clearance velocity and temperature integrity. Australian Border Force accreditation and cold-chain audit capabilities differentiate forwarder selection.
- Manufacturers:Just-in-time component supply chains for automotive and industrial equipment seek multi-modal coordination with predictive visibility. Their demand concentrates along Melbourne-Brisbane manufacturing corridors.
- Retailers:Seasonal inventory surges and e-commerce fulfillment drive fragmented, high-frequency shipments requiring flexible capacity sourcing across spot markets.
Established relationships anchor exporter-forwarder contracts. Retailer demand is expanding fastest through modular spot-market procurement.
Delivery Mode:
Control point selection determines liability handoff and documentation complexity, with door-to-door arrangements capturing integrated margin pools.
- Door-to-Door:End-to-end coordination from shipper facility to consignee premises, consolidating customs brokerage, inland transport, and terminal handling under single forwarder accountability. Pharmaceutical and high-value electronics shippers favor this mode for compliance simplicity.
- Port-to-Port:Traditional ocean freight contracting where shipper and consignee arrange separate inland legs. Bulk commodity exporters with captive logistics capabilities prefer this structure for cost transparency.
- Port-to-Door:Import-focused configuration where forwarder assumes responsibility after vessel discharge, managing customs clearance and inland distribution to metropolitan warehouses.
- Door-to-Port:Export configuration common in agricultural and mining supply chains, with forwarder coordinating inland collection and terminal handoff before ocean leg commencement.
Port-to-port contracting retains volume leadership. Door-to-door adoption is climbing fastest among temperature-sensitive cargo owners.
Technology:
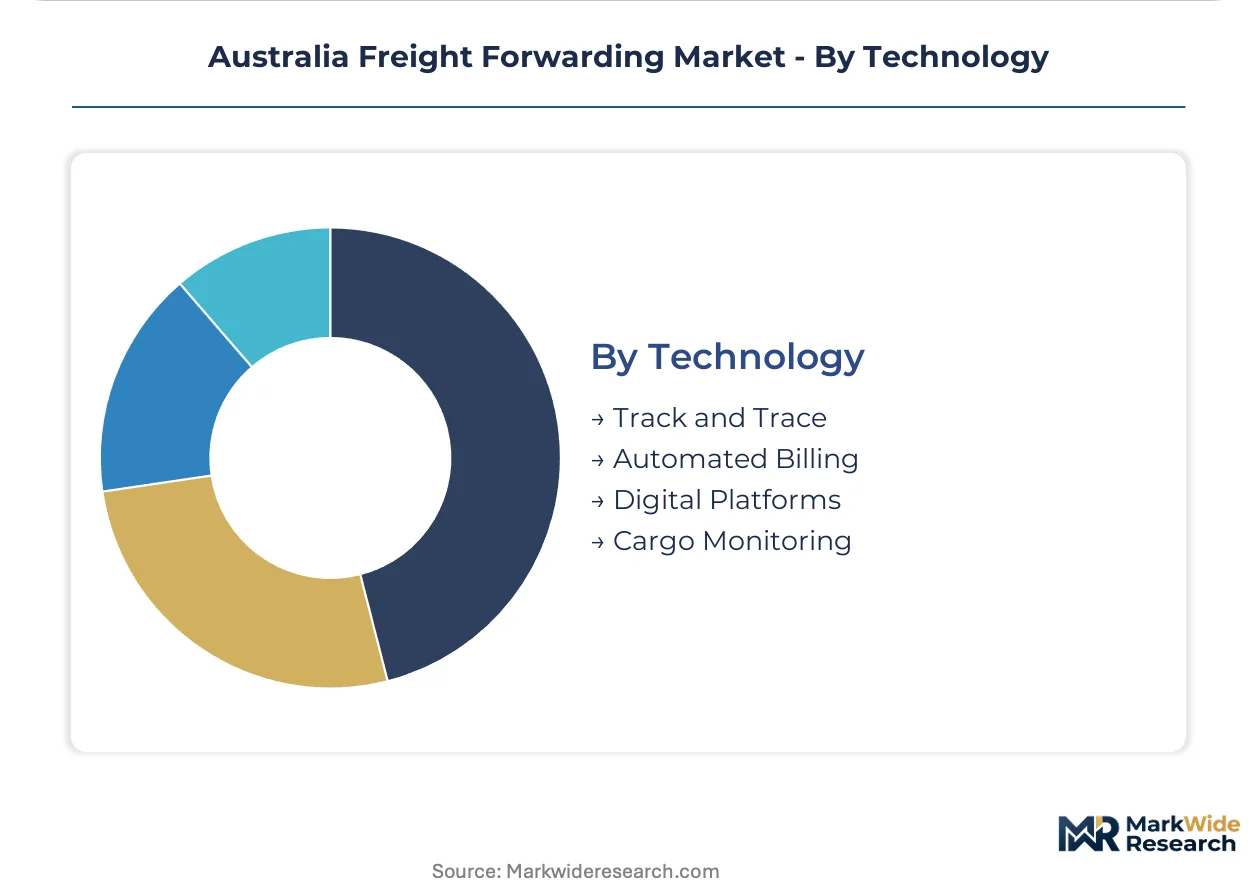
Digital capability stratification separates premium forwarders from commodity operators, with real-time visibility now a baseline procurement requirement rather than differentiation.
- Digital Platforms:Cloud-based freight management systems integrating carrier booking, documentation, and customs filing through unified interfaces. Mining exporters in Queensland pilot blockchain-enabled smart contracts for iron ore and grain lanes to automate payment release.
- Track and Trace:GPS and RFID-enabled cargo monitoring providing location and condition data across multimodal legs. Pharmaceutical cold-chain compliance demands this capability for temperature excursion documentation.
- Cargo Monitoring:Sensor-based environmental tracking of humidity, shock, and temperature for sensitive shipments. Integration with automated alert systems enables proactive intervention during transit deviations.
- Automated Billing:Rate engine and invoice reconciliation systems reducing manual processing overhead for high-shipment-volume accounts. Retailers and manufacturers with frequent lane activity prioritize this efficiency.
Track and trace deployment is most mature. Digital platform convergence with predictive analytics represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's resource corridors function as Australia's primary freight forwarding concentration zone, with Gladstone Port's coal and LNG terminal throughput driving dedicated heavy-haul infrastructure investment along the Bruce Highway and Moura rail link.
New South Wales
Sydney Airport's pharmaceutical import volumes and Port Botany's container throughput anchor demand for temperature-controlled and customs-accelerated forwarding services. The Australian Border Force's Trusted Trader program accreditation requirements filter operator participation in metropolitan distribution. Western Sydney's logistics precincts concentrate cold-chain infrastructure serving healthcare distributors.
Victoria
Melbourne's Port Phillip zone handles Australia's largest container volumes, with manufacturing corridors to Brisbane generating intermodal rail-road demand. The National Heavy Vehicle Regulator enforces chain-of-responsibility compliance across the Hume Highway freight corridor. Dandenong South industrial estates host pharmaceutical and electronics importers requiring door-to-door coordination.
Queensland
Gladstone Port's coal and LNG export expansion concentrates project cargo and bulk commodity forwarding demand along dedicated heavy-haul routes into the Bowen Basin. The Heavy Vehicle National Law reform tightens liability allocation for consigners operating in resource corridors. Mackay and Rockhampton function as logistics staging points for mining infrastructure components.
Western Australia
Pilbara iron ore exports and Fremantle Port's bulk handling drive ocean freight dominance, though limited rail capacity creates bottleneck risk during peak export windows. The Department of Agriculture administers strict biosecurity treatment mandates for wooden packaging entering the state. Kwinana industrial area concentrates LNG project cargo requiring heavy-lift certification.
South Australia
Adelaide's manufacturing and agricultural export base generates fragmented forwarding demand across grain lanes and automotive component supply chains. Interstate rail connections to Melbourne and Perth face capacity competition from bulk mineral exports. Port Adelaide's container terminal expansion targets transshipment volumes from regional South Australian producers.
Australia Freight Forwarding Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service segments. The market structure concentrates around integrated global networks, regional project cargo experts, and domestic metropolitan distributors. Three archetypes dominate: multinational integrators with air-ocean density, mining corridor specialists with heavy-lift capabilities, and digital-native platforms with spot-market procurement tools. Competitive moves center on rail-road intermodal capacity expansion and blockchain-enabled documentation automation.
Within the multinational integrator tier, DHL Group and Kuehne + Nagel occupy positions defined by network scale and vertical specialization. DB Schenker anchors the intermodal density segment along east coast corridors. Among Australian-owned operators, BCR Australia and Magellan Logistics exemplify the domestic specialist archetype serving resource and metropolitan lanes.
| Leading Market Players |
|---|
| DB Schenker |
| DHL Group |
| Kuehne + Nagel |
| BCR Australia |
| Think Global Logistics |
| Stockwell International |
| Magellan Logistics |
| CargoMaster |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
Diesel price index movements cascade through Australian freight forwarding tiers, compressing margins for road-dominant operators while concentrating pricing power with rail-intermodal providers along the Melbourne-Brisbane corridor.
Pricing Analysis
Margin tightening in standard freight tiers reflects diesel cost volatility and spot-market procurement fragmentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by Australian Border Force Trusted Trader accreditation and cold-chain certification. Pharmaceutical importers around Sydney Airport exhibit lowest price sensitivity due to compliance complexity, while agricultural exporters in Queensland demonstrate highest sensitivity to per-ton freight rates.
Supply Chain Analysis
Driver availability constraints in Australian mining corridors and metropolitan distribution zones concentrate operational risk for road freight operators. Equipment manufacturing draws from China, Germany, and Japan for chassis and refrigeration units. Supply chain vulnerability rests on single-source dependency for specialized heavy-lift certification training. Distribution runs through port-centric consolidation hubs at Gladstone, Fremantle, and Port Botany before final-mile road deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia freight forwarding market functions as a cost-of-compliance arena where National Heavy Vehicle Regulator chain-of-responsibility enforcement erects defensible moats around accredited operators with integrated audit capabilities.
For Market Incumbents: Deepen telematics investment across Queensland resource corridors to demonstrate fatigue management compliance under intensifying NHVR audit frequency. Expand rail-road intermodal density along the Melbourne-Brisbane corridor to offset diesel cost volatility eroding pure-road margins. Secure heavy-lift certification in-house to defend against project cargo specialists poaching Western Australia LNG infrastructure contracts. For New Entrants and Emerging Players: Australian Border Force Trusted Trader program acceleration opens a window for digital-native platforms to capture pharmaceutical import lanes through expedited customs clearance premiums. Target temperature-controlled metropolitan distribution around Sydney Airport and Melbourne's Port Phillip zone where incumbent service gaps persist. Lead with API-first freight management systems to bypass legacy port community system integration barriers plaguing Brisbane and Fremantle. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic specialists with heavy-lift capabilities in Western Australia and Queensland mining corridors where project cargo expertise scarcity concentrates pricing power. Long-term viability hinges on carbon accounting readiness under Safeguard Mechanism reforms reshaping contract structures. Monitor diesel price trajectory and rail capacity expansion announcements as inflection signals for intermodal competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Compliance Integration | NHVR audit requirements drive telematics adoption for fatigue management documentation across Queensland heavy-haul routes. |
| Rail-Road Intermodal Expansion | Melbourne-Brisbane corridor density investments offset diesel volatility and satisfy carbon accounting demands under Safeguard Mechanism reforms. |
| Trusted Trader Accreditation | Australian Border Force program enables premium pricing capture in pharmaceutical lanes through expedited Sydney and Melbourne customs clearance. |
| Blockchain Documentation Automation | Smart contract settlement for iron ore and grain lanes compresses working capital cycles for Queensland and Western Australia mining exporters. |
| Heavy-Lift Certification Investment | In-house project cargo capabilities defend LNG infrastructure contracts against Kuehne + Nagel specialization in Western Australia's Kwinana industrial zone. |
Research Methodology
Document review covered Australian Bureau of Statistics trade data, NHVR compliance bulletins, and Australian Border Force Trusted Trader program documentation, complemented by interviews with freight forwarding operations directors, mining company logistics managers, pharmaceutical supply chain leads, and rail intermodal planners. Secondary validation drew from Department of Agriculture biosecurity advisories, Infrastructure Australia corridor assessments, and industry association freight volume surveys. Bottom-up shipment volume modeling and top-down market sizing triangulated across these inputs.
Historical freight volume trends were cross-referenced against expert panel input on capacity expansion timelines and regulatory implementation schedules. Segmentation modeling spanned service mode, customer type, delivery configuration, and technology adoption across the analysis window. CAGRs were derived from trend extrapolation adjusted for corridor-specific infrastructure constraints and compliance cost trajectories. Forecast inputs incorporated diesel price sensitivity coefficients and rail capacity utilization thresholds.
Caveats apply where Heavy Vehicle National Law enforcement intensity, biosecurity treatment mandate expansion, or Safeguard Mechanism carbon accounting scope revisions could materially shift the outlook. Material deviation in these regulatory triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Middle East Freight Forwarding Market