
 Freight Brokerage Market | 2026-2036
Freight Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Brokerage Market Analysis
Asset-light brokerage models is tilting competitive dynamics toward technology-enabled intermediaries with minimal owned fleet exposure. C.H. Robinson Worldwide leverages its proprietary Navisphere platform to sustain North American freight matching density. Landstar System anchors its position through an independent contractor network that controls variable capacity costs across irregular route operations. J.B. Hunt Transport Services differentiates via integrated intermodal assets that extend brokerage reach into rail-served lanes.
Freight brokerage denotes the commercial arrangement where licensed intermediaries coordinate cargo movement between shippers and authorized motor carriers without assuming direct possession of goods, typically earning margin spreads of 10-18% on contracted lane rates while managing liability through broker surety bonds and contingent cargo insurance. Its primary purpose is to optimize load-to-carrier matching efficiency across fragmented trucking supply. Full Truckload brokerage dominates transaction volume but faces margin compression from digital freight matching platforms, while Less Than Truckload segments retain stronger pricing power through consolidation complexity. Intermodal offerings represent the fastest-expanding margin pool as rail fuel surcharges and chassis availability create broker value in mode-shifting decisions.
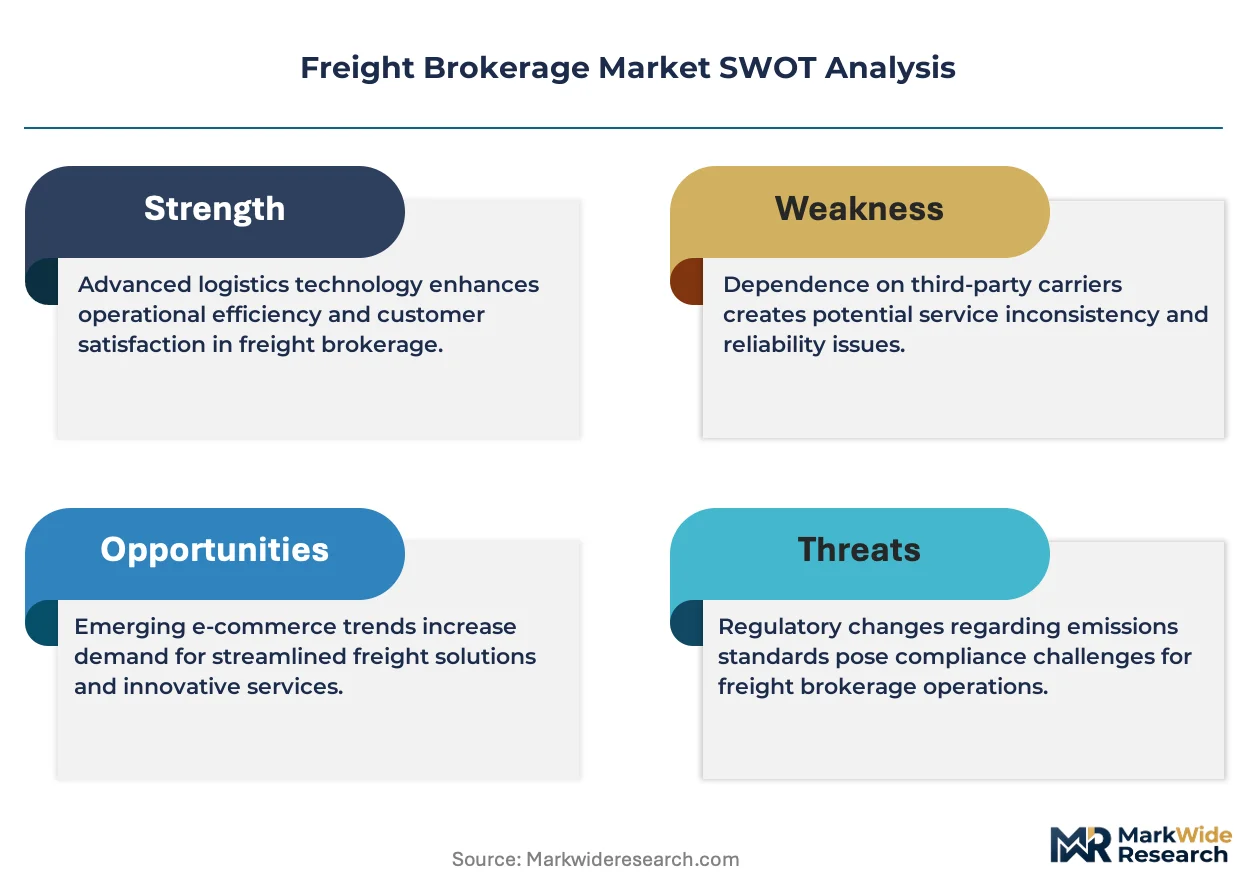
The US Federal Motor Carrier Safety Administration enforces broker authority and surety bond requirements that filter low-capital entrants, while the EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles indirectly elevate demand for optimized load consolidation. The EU Green Deal's Fit for 55 transport decarbonization targets are reshaping European cross-border freight matching priorities. Stakeholders must monitor how autonomous trucking pilots and associated liability frameworks recalibrate the broker's intermediary function.
Market Dynamics
Digital freight matching platforms are compressing traditional brokerage margins by automating load-carrier pairing that once required human intermediaries. The US Federal Motor Carrier Safety Administration's electronic logging device mandate continues to reshape how brokers verify carrier compliance and available hours of service.
Growth Catalysts
- E-commerce fulfillment networks:Retailers expanding direct-to-consumer operations require flexible capacity sourcing that asset-light brokers provide across peak seasonal windows.
- EPA Phase 3 greenhouse gas standards:Heavy-duty vehicle emissions rules are elevating demand for optimized load consolidation and mode-shifting advisory services.
- Intermodal chassis pools:Rail-served lane coordination creates broker value where container availability and fuel surcharge complexity deter direct shipper-carrier contracting.
Market Restraints
- Carrier supply concentration:Small fleet operators control the majority of US trucking capacity, creating matching inefficiencies and rate volatility during demand spikes.
- Surety bond requirements:The US Federal Motor Carrier Safety Administration's $75,000 broker authority threshold filters low-capital entrants and limits price competition.
- Diesel price volatility:Fuel cost swings compress spot market margins and complicate contracted lane rate negotiations between shippers and carriers.
Strategic Opportunities
- Cross-border Mexico-US lanes:Nearshoring manufacturing shifts are expanding demand for bilingual brokerage services with customs documentation expertise.
- Autonomous trucking liability frameworks:Emerging federal and state regulations around self-driving commercial vehicles will recalibrate the broker's intermediary risk function.
- API-first carrier onboarding:Real-time insurance verification and safety score integration reduces friction in independent contractor network expansion.
Industry Challenges
- Driver recruitment pipelines:Fleet operators face persistent shortages of qualified commercial drivers, constraining broker access to contracted capacity during volume surges.
- Legacy TMS integration:Shipper enterprise systems often lack standardized data formats, complicating automated load tendering and proof-of-delivery reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Brokerage Market |
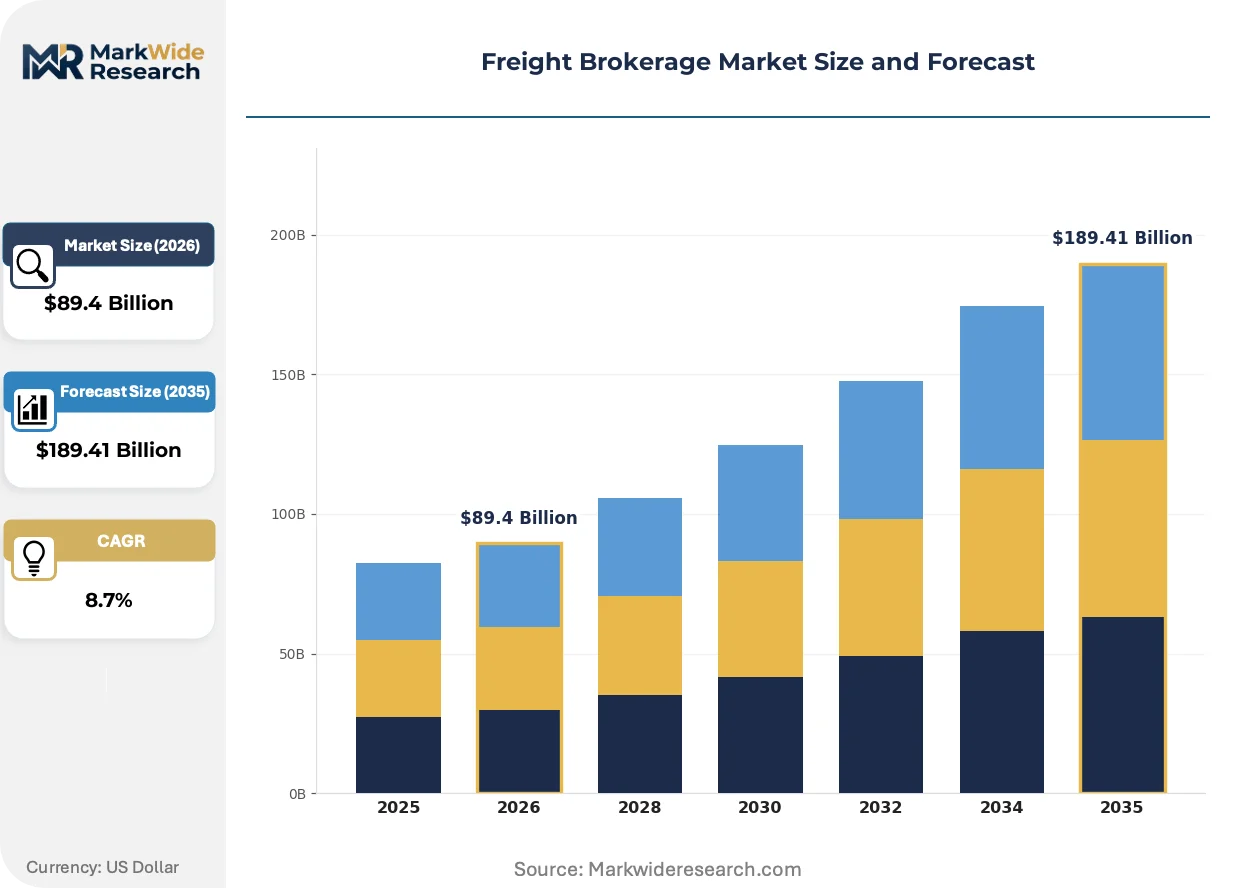
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $189.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Intermodal, Expedited Client Type: Retailers, Manufacturers, Distributors, E-Commerce Technology: Transportation Management System, Real-Time Tracking, Route Optimization, Electronic Data Interchange Offering: Standard Brokerage, Asset-Based Services, Freight Forwarding, Consulting |
| Companies Covered | WWEX Group, Landstar System, C.H. Robinson Worldwide, ArcBest Corp., MODE Global, Total Quality Logistics, Arrive Logistics, Hub Group, J.B. Hunt Transport Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Brokerage Market Emerging Trajectories
Freight brokerage is undergoing platformization as algorithmic pricing and automated carrier matching displace traditional phone-and-email dispatch models. Three developments are restructuring competitive positioning across the intermediation layer.
Dynamic pricing engines are migrating from large asset-based carriers to independent software vendors serving the long tail of small and mid-sized brokerages. Third-party logistics providers with limited proprietary technology are adopting white-label freight matching platforms to preserve shipper relationships. This technology diffusion is compressing the margin advantage that historically accrued to scale-intensive proprietary networks.
The EU Green Deal's Fit for 55 transport decarbonization targets are reshaping European cross-border freight matching priorities. Emissions trading system costs and modal shift incentives are elevating broker value in rail-road intermodal coordination. German and Dutch logistics corridors are experiencing the most pronounced demand for carbon-intensity data integration in load tendering workflows.
Shippers are consolidating procurement relationships around full-service logistics platforms that bundle brokerage with managed transportation and visibility analytics. Mid-sized manufacturers are abandoning fragmented spot market purchasing in favor of contracted minimum volume commitments with technology-enabled intermediaries. This concentration pattern is most visible in the Dallas-Fort Worth and Chicago logistics corridors where e-commerce fulfillment density supports integrated service economics.
Freight Brokerage Market Segmentation
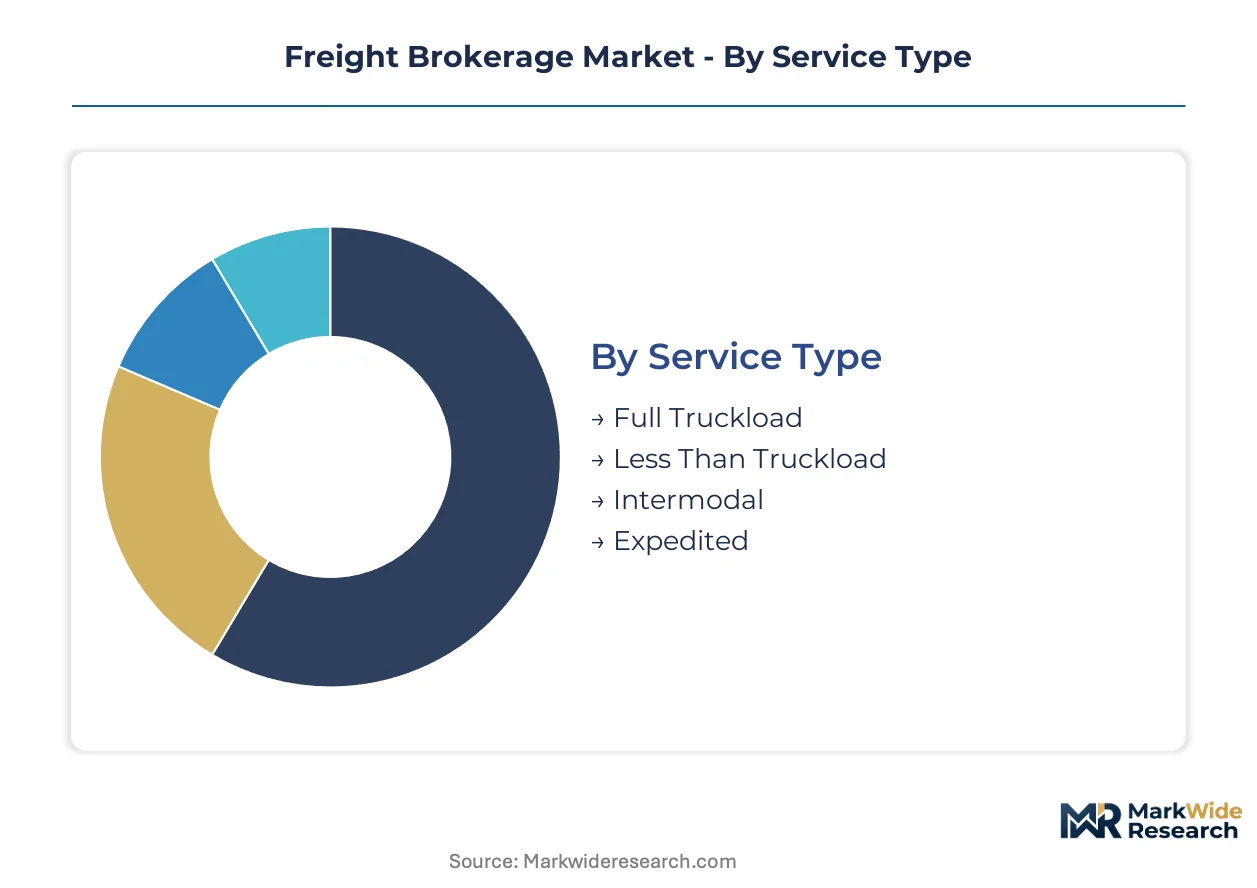
Segmentation in freight brokerage reveals how intermediaries capture value across divergent service intensities and technology dependencies. Each category exposes distinct margin structures and customer stickiness profiles that determine competitive durability.
Service Type:
After-sales service intensity varies sharply across service types, with irregular-route operations demanding sustained carrier relationship management versus scheduled lane brokerage.
- Full Truckload:Dominates transaction volume through dedicated trailer allocation for single-shipper cargo. Dallas-Fort Worth corridor retailers drive concentration as e-commerce fulfillment networks require surge capacity during peak windows.
- Less Than Truckload:Consolidates multiple shipper freight into shared trailer space, requiring sophisticated terminal network coordination. Chicago logistics corridor manufacturers sustain pricing power through consolidation complexity that resists pure platform disintermediation.
- Intermodal:Rail-truck mode combinations create broker value in fuel surcharge management and chassis pool access.
- Expedited:Time-definite capacity sourcing commands premium spreads through dedicated team-driver networks.
By volume, Full Truckload leads. By growth pace, Intermodal is climbing the fastest as rail fuel efficiency advantages expand mode-shift advisory demand.
Client Type:
Cost tier stratification separates enterprise shippers with contracted minimum commitments from spot-market participants exposed to rate volatility.
- Retailers:Seasonal demand peaks and omnichannel fulfillment complexity drive reliance on flexible brokerage relationships. United States big-box chains concentrate procurement around integrated logistics platforms bundling brokerage with visibility analytics.
- E-Commerce:Direct-to-consumer networks require granular last-mile coordination that asset-light intermediaries provision through independent contractor capacity pools.
- Manufacturers:Just-in-time production schedules demand contracted lane reliability over spot market flexibility.
- Distributors:Inventory replenishment cycles favor recurring route density over irregular expedited sourcing.
Retailers generate the highest brokerage revenue concentration. E-Commerce is expanding most quickly as fulfillment network decentralization multiplies touchpoints.
Technology:
Application maturity separates legacy EDI-dependent operations from API-first platforms enabling real-time carrier onboarding.
- Transportation Management System:Core software infrastructure automating load tendering, carrier selection, and freight audit processes. United States mid-sized manufacturers are abandoning fragmented spot purchasing for TMS-embedded contracted commitments.
- Real-Time Tracking:GPS and telematics integration provides shipment visibility that reduces claims disputes and improves dock scheduling.
- Route Optimization:Algorithmic sequencing of pickup and delivery stops to minimize empty miles and hours-of-service violations.
- Electronic Data Interchange:Legacy standardized document exchange persists among established shipper-carrier relationships despite API migration pressures.
TMS platforms anchor technology spending. Real-Time Tracking is gaining share fastest as shipper procurement consolidates around visibility-centric service bundles.
Offering:
Margin structure differentiates pure brokerage spreads from asset-heavy integrated services with captive capacity control.
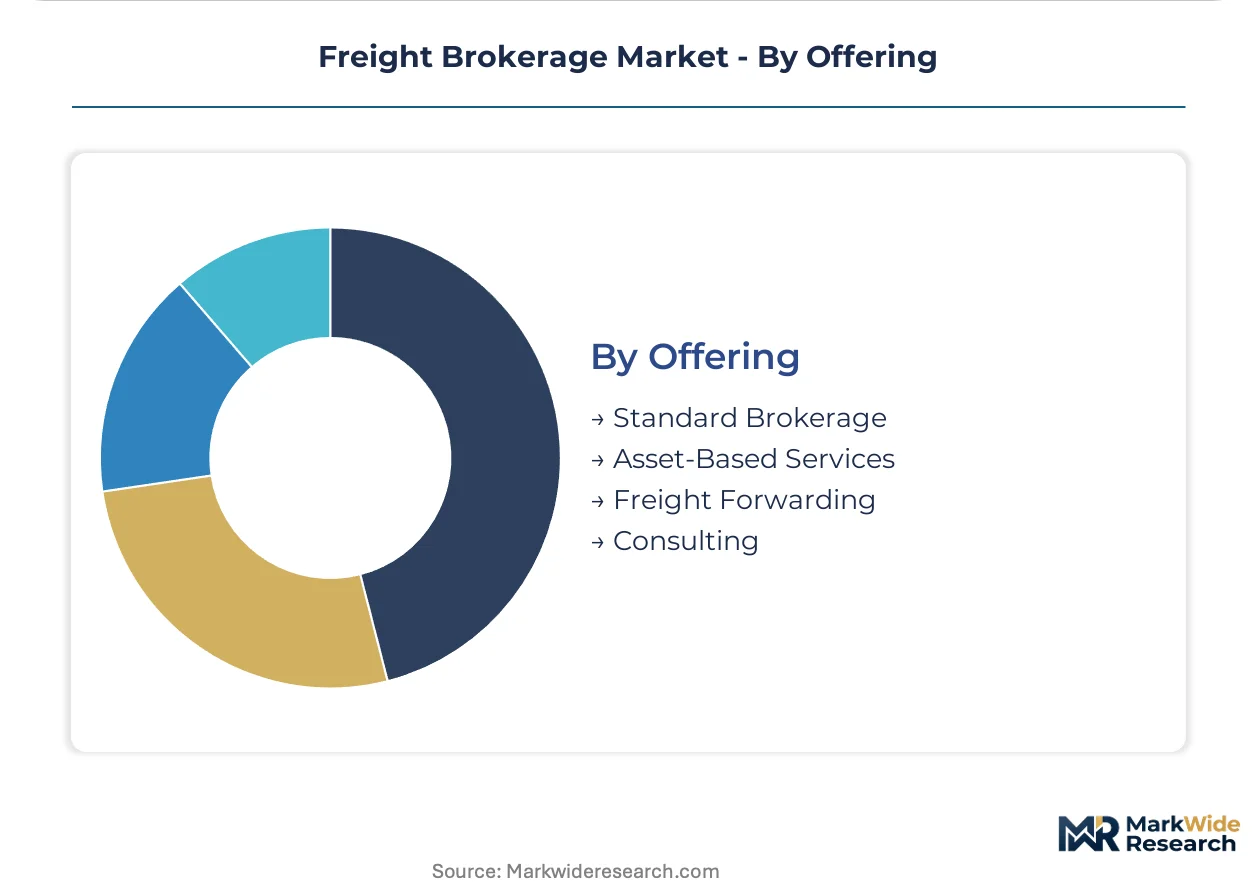
- Standard Brokerage:Licensed intermediation earning 10-18% margin spreads without fleet ownership or cargo possession. United States Federal Motor Carrier Safety Administration surety bond requirements filter low-capital entrants and sustain incumbent pricing power.
- Asset-Based Services:Owned tractor-trailer fleets combined with brokerage operations create lane density advantages in rail-served corridors.
- Freight Forwarding:International documentation and customs clearance expertise extends brokerage into cross-border Mexico-US lanes.
- Consulting:Mode-shift advisory and network design services capture fees from EPA Phase 3 compliance-driven consolidation optimization.
Standard Brokerage commands the widest shipper adoption. Freight Forwarding shows the steepest expansion trajectory as nearshoring manufacturing shifts multiply cross-border documentation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Motor Carrier Safety Administration's electronic logging device mandate and the EU Green Deal's Fit for 55 targets are reshaping compliance requirements and modal shift incentives across major freight corridors. National regulators in each market are layering emissions standards onto traditional safety frameworks. Logistics demand clusters around specific industrial corridors and manufacturing zones.
United States
E-commerce fulfillment networks and automotive manufacturing supply chains drive brokerage demand across the Dallas-Fort Worth and Chicago logistics corridors. The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles elevate demand for optimized load consolidation advisory services. The Dallas-Fort Worth metro anchors North American freight matching density as third-party logistics intermediaries expand capacity sourcing for seasonal retail peaks.
Germany
Industrial manufacturing exports and chemical processing logistics sustain demand for intermodal rail-road coordination across the Rhine-Ruhr corridor. The EU Green Deal's Fit for 55 transport decarbonization targets reshape cross-border freight matching priorities through emissions trading system costs. The Port of Hamburg and surrounding logistics zones concentrate brokerage activity where container availability and fuel surcharge complexity create intermediary value.
China
Domestic consumption growth and manufacturing supply chain reconfiguration expand demand for flexible capacity sourcing across the Yangtze River Delta. The Ministry of Ecology and Environment's dual carbon goals elevate broker value in mode-shifting and consolidation optimization services. Shanghai and the surrounding Jiangsu-Zhejiang manufacturing belt concentrate digital freight matching platform adoption as algorithmic pricing displaces traditional dispatch models.
Mexico
Nearshoring manufacturing shifts and automotive assembly supply chains expand demand for bilingual brokerage services with customs documentation expertise. The Secretariat of Economy's trade facilitation programs intersect with USMCA compliance requirements at border crossings. The Nuevo León and Bajío Region industrial corridors concentrate cross-border freight activity where documentation complexity deters direct shipper-carrier contracting.
Netherlands
Rotterdam port logistics and European distribution hub operations sustain demand for multimodal coordination across the Randstad region. The EU Green Deal's modal shift incentives elevate broker value in rail-road intermodal advisory services. The Amsterdam-Rotterdam-Antwerp logistics corridor experiences pronounced demand for carbon-intensity data integration in load tendering workflows.
Freight Brokerage Market Vendor Landscape
On the supply side, the industry is consolidating around technology-enabled intermediaries with proprietary matching platforms and asset-light operating models. Tiered competitive positioning separates scale-intensive networks with density advantages from specialized regional brokers serving niche corridors. Dominant competitive moves include strategic technology licensing partnerships and geographic expansion through independent contractor network aggregation.
Within the asset-light technology tier, C.H. Robinson Worldwide and Landstar System exemplify divergent approaches to carrier relationship architecture. C.H. Robinson occupies a position anchored by proprietary platform density across North American lanes. Landstar represents the independent contractor network model that controls variable capacity costs. J.B. Hunt Transport Services sits within the integrated intermodal segment where captive rail assets extend brokerage reach into mode-shifting decisions.
| Leading Market Players |
|---|
| WWEX Group |
| Landstar System |
| C.H. Robinson Worldwide |
| ArcBest Corp. |
| MODE Global |
| Total Quality Logistics |
| Arrive Logistics |
| Hub Group |
| J.B. Hunt Transport Services |
| Others |
Supply Flow & Price Mechanics
Dallas-Fort Worth logistics corridors concentrate third-party capacity sourcing power that filters downstream to contracted lane rate negotiations. Small fleet operators control the majority of US trucking supply, creating bid-ask spreads that brokers capture through matching density advantages.
Pricing Analysis
Certification level through FMCSA broker authority and surety bond compliance creates the primary spread between established intermediaries and marginal entrants. Three-tier pricing structure across premium, standard, and economy levels reflects carrier safety score tiers and insurance coverage depth. Cost compression in spot market transactions is intensifying because digital freight matching platforms automate load-carrier pairing previously requiring human negotiation. Mid-sized manufacturers with TMS-embedded contracted commitments demonstrate the least price sensitivity, while fragmented spot market participants face the greatest exposure to rate volatility.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates cross-border lane risk profiles as nearshoring manufacturing shifts accelerate. Brokerage supply draws from independent contractor networks concentrated in the United States, Mexico, and Canada, with chassis pool availability and rail fuel surcharge complexity creating intermediary value. Diesel price volatility and driver recruitment pipeline constraints constitute the core structural risk to capacity access. Distribution runs through asset-light platforms with proprietary matching algorithms that displace traditional phone-and-email dispatch models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freight brokerage sector sits at an inflection point where EPA Phase 3 greenhouse gas standards and autonomous trucking liability frameworks will recalibrate intermediary value capture. Platformization and algorithmic pricing are compressing traditional margin structures while expanding addressable market scope.
For Market Incumbents: Build proprietary carrier relationship density as the defensive moat against digital freight matching disintermediation. Deepen API-first integration with shipper TMS platforms to embed contracted minimum volume commitments that resist spot market volatility. Expand independent contractor network aggregation in the Nuevo León and Bajío Region corridors where bilingual customs documentation expertise creates switching costs.
For New Entrants and Emerging Players: Mid-market manufacturers in the Chicago logistics corridor represent the most penetrable entry point as they abandon fragmented spot purchasing for integrated logistics platforms. Cross-border Mexico-US lanes with USMCA compliance complexity offer white-space opportunity where documentation expertise deters direct contracting. A white-label freight matching platform go-to-market angle preserves capital efficiency while capturing shipper relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because technology-enabled intermediaries with proprietary matching density will absorb regional broker share. Acquisition targets should display independent contractor network scale in rail-served corridors or carbon-intensity data integration capabilities for EU Green Deal compliance. The signal to watch is autonomous trucking pilot liability framework clarity that recalibrates broker risk function economics.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Carrier Onboarding Platform | Real-time insurance verification reduces friction in independent contractor network expansion across fragmented US trucking supply. |
| Cross-Border Documentation Specialization | Bilingual brokerage services capture nearshoring manufacturing shifts multiplying Mexico-US lane complexity. |
| Intermodal Chassis Pool Integration | Rail-served lane coordination creates broker value where container availability deters direct shipper-carrier contracting. |
| Carbon-Intensity Data Integration | EU Green Deal Fit for 55 compliance elevates advisory fees for modal shift optimization in German and Dutch corridors. |
| Autonomous Trucking Liability Framework Positioning | Federal and state regulatory clarity will recalibrate intermediary risk function and surety bond requirements. |
Methodological Framework
Operator-level perspectives from freight brokerage dispatch managers, shipper procurement directors, independent carrier owner-operators, and intermodal rail coordinators anchored the qualitative base. Secondary validation drew from FMCSA enforcement data, EPA Phase 3 regulatory filings, customs trade statistics, and SEC 10-K disclosures from publicly traded logistics platforms. Bottom-up capacity sourcing models and top-down e-commerce fulfillment demand projections were triangulated to establish market sizing boundaries.
Scenario-bracketing around autonomous trucking adoption curves and diesel price volatility bands framed the analytical approach across the analysis window. Segmentation dimensions modeled include service type, client vertical, technology deployment maturity, and geographic corridor density. CAGRs were derived from load volume growth trajectories and margin compression curves specific to digital freight matching penetration rates.
Practitioners should monitor FMCSA regulatory revisions and EPA emissions standard enforcement intensity for early signals of broker authority cost structure shifts. Forecasts reflect assumptions about carrier supply fragmentation persistence and shipper procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market