
 B2B Sports Nutrition Market | 2026-2036
B2B Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
B2B Sports Nutrition Market Intelligence
North American contract manufacturing capacity is fragmenting as specialty producers compete for shelf-stable protein powder tolling agreements. Glanbia Plc leverages its Irish dairy protein supply chain to anchor premium whey isolate volumes for team sports programs. PepsiCo Inc competes through direct-to-gym distribution networks that bypass traditional wholesale tiers. Abbott Laboratories sustains clinical credibility by controlling hospital-affiliated sports medicine channel access.
B2B sports nutrition encompasses scientifically formulated ingestible products—typically delivering 20-30 grams protein per serving, with amino acid profiles verified via HPLC analysis—manufactured for resale by gyms, franchises, and institutional buyers rather than direct consumer purchase. Protein powders occupy the deepest margin pools due to ingredient standardization and scale economies in dairy-derived isolate production. Custom formulation services represent the fastest-growing service type as boutique fitness chains seek differentiated macronutrient ratios unavailable from mass-market catalogs. Energy bars remain structurally mature, with wholesale distributors extracting value through consolidated procurement rather than product innovation.
FDA Current Good Manufacturing Practice regulations and NSF Certified for Sport standards govern ingredient transparency and banned-substance screening, compelling manufacturers to maintain dual certification portfolios for collegiate and professional athletic contracts. The EU's novel food approval framework under EFSA jurisdiction creates parallel compliance burdens for brands sourcing fermented or cell-cultured protein substrates. Stakeholders must monitor how state-level athletic commission testing protocols diverge from federal supplement labeling requirements, as this fragmentation determines which product lines qualify for procurement by regulated competitive leagues.
Market Dynamics
Professional sports franchises and collegiate athletic departments are consolidating procurement through exclusive supply agreements, compressing vendor counts while elevating technical specification requirements for banned-substance testing and amino acid verification protocols.
Growth Catalysts
- NSF Certified for Sport mandates:Collegiate athletic conferences in the United States now require third-party certification for all supplement categories, creating procurement pull for dual-certified manufacturers capable of batch-specific documentation.
- Fermented protein substrates:Precision fermentation technologies are expanding amino acid profile customization beyond dairy-derived isolates, enabling hypoallergenic formulations for teams with diverse athlete populations.
- Cologne-Düsseldorf fitness infrastructure cluster:Germany's concentrated boutique gym ecosystem generates localized demand for white-label custom formulation services with sub-48-hour production turnaround.
Market Restraints
- Whey protein concentrate price volatility:New Zealand and European Union dairy auction fluctuations transmit directly to contract manufacturing margins, compressing profitability on standardized powder SKUs.
- EFSA novel food approval timelines:Cell-cultured and precision-fermented protein ingredients face 18-24 month safety assessment windows, delaying commercialization for European market entrants.
- Plant protein digestibility limitations:Incomplete essential amino acid profiles in pea and rice isolates restrict formulation options for high-performance team sports applications requiring leucine thresholds above 2.5 grams per serving.
Strategic Opportunities
- Hospital-affiliated sports medicine channels:Clinical credibility positioning through Abbott Laboratories' controlled access model creates template for manufacturers seeking differentiation via physician endorsement rather than gym floor presence.
- Direct-to-gym distribution bypass:PepsiCo Inc's warehouse-direct servicing of franchise locations eliminates wholesale tier markups, enabling price-positioned volume capture in mid-market fitness chains.
- India FSSAI functional food category expansion:India's 2022 notification creating distinct regulatory pathway for sports nutrition products opens formal market access previously constrained by pharmaceutical-adjacent classification.
Industry Challenges
- HPLC analytical chemist scarcity:Batch-level amino acid verification requires specialized chromatography expertise that contract manufacturers struggle to staff at scale, creating quality control bottlenecks during peak procurement seasons.
- Dual certification portfolio maintenance:Sustaining concurrent NSF Certified for Sport and Informed Sport accreditations demands redundant testing infrastructure and documentation systems that strain mid-tier producer operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2B Sports Nutrition Market |
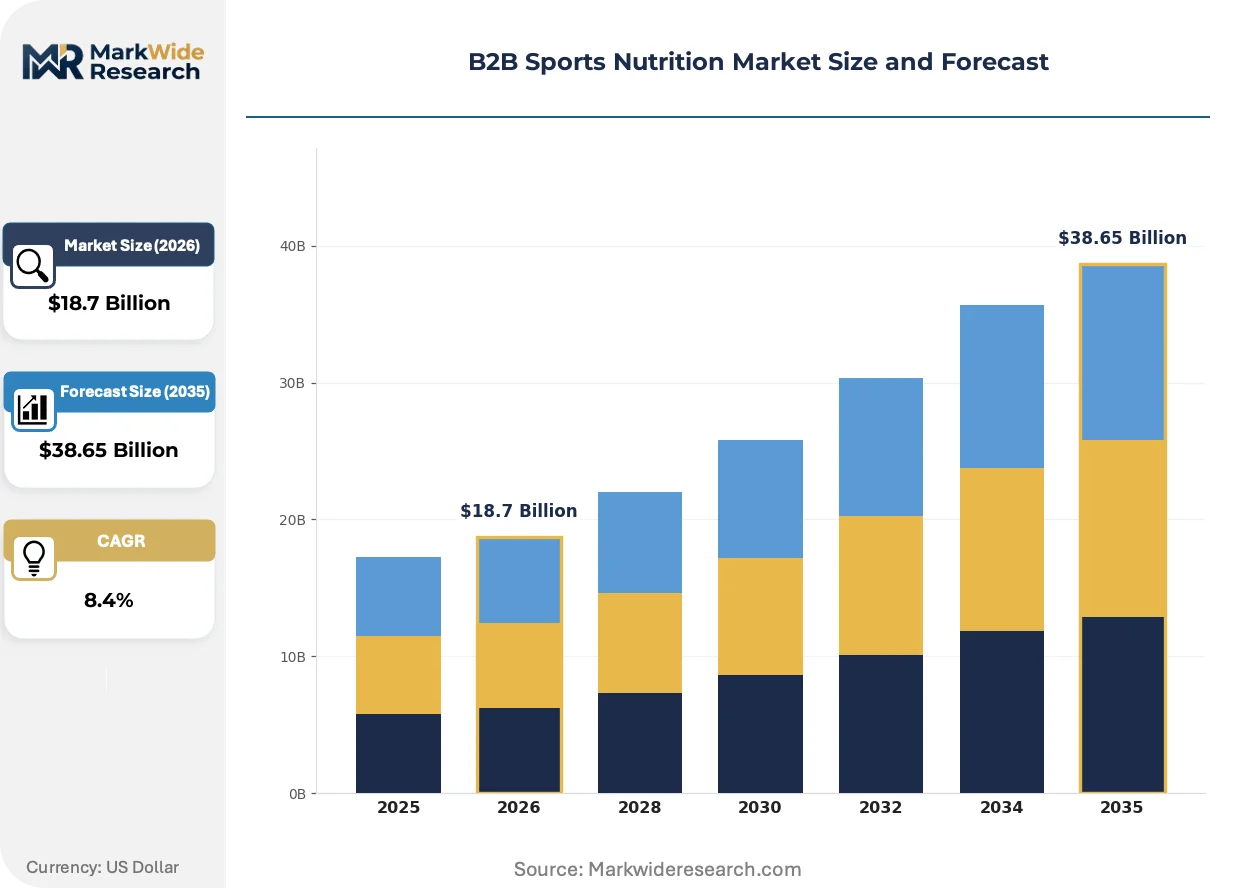
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Supplements, Meal Replacements End User: Fitness Centers, Professional Teams, Nutritional Coaches, Health Clinics Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores Service Type: Custom Formulation, Branding Solutions, Packaging Services, Educational Workshops |
| Companies Covered | Abbott Laboratories, Herbalife Ltd, Glanbia Plc, Iovate Health Sciences International, Science in Sport, PepsiCo Inc, Post Holdings Inc, MusclePharm Corp, The Bountiful Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2B Sports Nutrition Market Strategic Shifts & Innovations
Formulation science and verification technology are converging to compress development cycles while elevating transparency requirements. Three developments are restructuring how products reach institutional buyers.
Precision fermentation of individual amino acids is rendering obsolete traditional protein blending approaches that relied on dairy or plant base ratios to approximate target profiles. Boutique fitness chains in Germany and the Netherlands are adopting single-amino-acid fortification for customized recovery protocols. This molecular specificity is compressing R&D timelines from 12 months to 6 weeks for niche macronutrient configurations.
EFSA's evolving stance on novel protein substrates under the EU Green Deal protein diversification targets is accelerating approval pathway investments by European manufacturers. The industrial consequence is parallel product development tracks—one for established dairy isolates, another for fermentation-derived alternatives. German and Dutch contract manufacturers are most affected, with Cologne-based facilities expanding pilot-scale fermentation capacity ahead of regulatory clarity.
Boutique fitness chains are consolidating vendor relationships around single-source custom formulation partners rather than catalog-based procurement from multiple suppliers. Traditional wholesale distributors serving this segment face disintermediation as manufacturers develop direct technical sales capabilities. This concentration is most visible in the United Kingdom's premium gym sector, where Equinox and Third Space have moved to exclusive supply agreements with dedicated production facilities.
B2B Sports Nutrition Market Segmentation
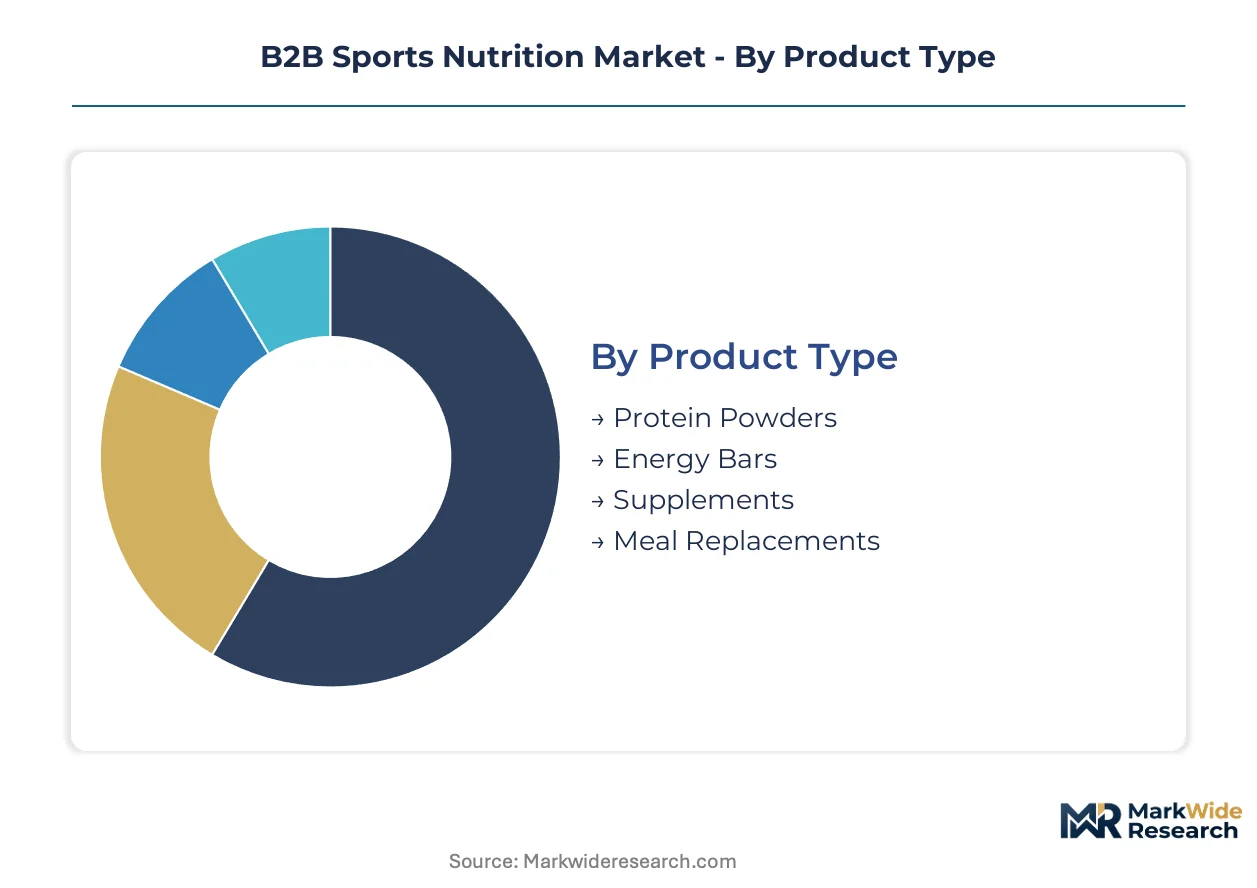
Segmentation in B2B sports nutrition reveals how procurement patterns diverge between institutional buyers seeking clinical-grade verification and commercial channels prioritizing speed-to-shelf. Understanding these divides exposes where margin pools concentrate and which service layers command pricing power.
Product Type:
Maturity varies sharply across this category, with decades-old formats coexisting alongside emerging precision-fermented alternatives.
- Protein Powders:Dairy-derived isolates and concentrates delivering 20-30 grams protein per serving remain the volume anchor, with HPLC-verified amino acid profiles now standard for collegiate and professional procurement. Demand concentrates in North American team sports programs where NSF Certified for Sport documentation is mandatory, though whey protein concentrate price volatility from New Zealand dairy auctions compresses contract manufacturing margins.
- Energy Bars:Shelf-stable formulations with standardized macronutrient ratios occupy a structurally mature position, with wholesale distributors extracting value through consolidated procurement rather than product innovation. Germany's boutique fitness chains in the Cologne-Düsseldorf cluster are shifting toward white-label custom bars with sub-48-hour production turnaround, bypassing traditional catalog suppliers.
- Supplements:Pre-workout and recovery formulations with verified banned-substance screening.
- Meal Replacements:Complete nutrition profiles targeting athletic weight management protocols.
Protein powders handle the majority of throughput; custom formulation services are expanding most quickly on share.
End User:
Customer type determines certification burden and technical specification intensity, creating distinct vendor qualification tiers.
- Professional Teams:Franchises and collegiate athletic departments now mandate dual certification portfolios—NSF Certified for Sport and Informed Sport—compelling manufacturers to maintain redundant testing infrastructure. The US NCAA and professional leagues require batch-specific documentation, compressing vendor counts to specialists with in-house chromatography capabilities.
- Fitness Centers:Boutique chains in the Netherlands and United Kingdom are consolidating around single-source custom formulation partners, disintermediating traditional wholesale distributors. Equinox and Third Space have moved to exclusive supply agreements with dedicated production facilities, prioritizing macronutrient differentiation over catalog breadth.
- Nutritional Coaches:Independent practitioners sourcing small-batch custom blends for athlete clientele.
- Health Clinics:Hospital-affiliated sports medicine channels requiring clinical credibility positioning.
Professional teams impose the steepest compliance barriers; boutique fitness centers are gaining share fastest as procurement consolidates.
Distribution Channel:
Channel economics hinge on whether intermediaries add value through consolidation or get bypassed entirely.
- Wholesale Distributors:Traditional tier extracting margin through consolidated procurement of standardized SKUs, particularly in energy bars where product innovation has stalled. Their value proposition erodes as manufacturers develop direct technical sales capabilities for custom formulation accounts.
- Direct Sales:Warehouse-direct servicing of franchise locations eliminates wholesale markups, enabling price-positioned volume capture in mid-market fitness chains. PepsiCo Inc's model bypasses traditional tiers entirely, controlling shelf placement and promotional timing.
- Online Retail:Digital procurement platforms with batch-level certification transparency.
- Specialty Stores:Curated retail environments targeting premium consumer crossover segments.
Wholesale distributors still move the most volume; direct sales channels are climbing the fastest as manufacturers build in-house logistics.
Service Type:
Margin accrual shifts upstream from finished goods toward technical services that embed manufacturers into client R&D cycles.
- Custom Formulation:Boutique fitness chains and professional teams seek differentiated macronutrient ratios unavailable from mass-market catalogs, compressing development timelines from 12 months to 6 weeks through precision fermentation of individual amino acids. Cologne-based facilities are expanding pilot-scale capacity to serve Germany's concentrated boutique gym ecosystem.
- Branding Solutions:White-label packaging and identity systems for chains building proprietary product lines.
- Packaging Services:Single-serve and bulk format configuration for diverse institutional requirements.
- Educational Workshops:Staff training on supplement timing and compliance documentation protocols.
Custom formulation commands the highest margin expansion; educational workshops remain a share-limited add-on service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between institutional procurement markets and fitness-channel economies. The United States prioritizes clinical-grade verification for collegiate athletic programs, while Germany's boutique gym cluster demands rapid-turn customization. India represents an emerging formalization opportunity as regulatory classification shifts.
United States
Collegiate athletic conferences and professional franchises drive institutional procurement volumes. The FDA's Current Good Manufacturing Practice regulations and NSF Certified for Sport mandates create dual compliance burdens that compress vendor counts to specialists with in-house chromatography capabilities. Greater Boston and the Pacific Northwest host concentrated contract manufacturing capacity serving NCAA Division I programs.
Germany
Boutique fitness chains in the Cologne-Düsseldorf corridor generate localized demand for white-label custom formulation with sub-48-hour production turnaround. The EU Green Deal protein diversification targets are accelerating EFSA novel food approval pathway investments by domestic manufacturers. North Rhine-Westphalia facilities are expanding pilot-scale fermentation capacity ahead of regulatory clarity on precision-fermented substrates.
United Kingdom
Premium gym operators including Equinox and Third Space have consolidated around exclusive supply agreements with dedicated production facilities. The country's departure from EU regulatory frameworks has created parallel compliance tracks for sports nutrition products. London and Southeast England concentrate demand for macronutrient-differentiated formulations unavailable from mass-market catalogs.
India
The FSSAI's 2022 notification creating a distinct regulatory pathway for sports nutrition products has opened formal market access previously constrained by pharmaceutical-adjacent classification. Maharashtra and Karnataka are emerging as production centers for contract manufacturers serving domestic fitness chains. The country's functional food category expansion is attracting formulation specialists seeking volume growth outside saturated Western markets.
Netherlands
Boutique fitness chains are adopting precision fermentation-derived amino acid fortification for customized recovery protocols. EFSA jurisdiction over novel protein substrates creates 18-24 month safety assessment windows that delay commercialization for fermentation-focused entrants. Randstad-based contract manufacturers are developing direct technical sales capabilities to bypass traditional wholesale distributors.
B2B Sports Nutrition Market Key Industry Players
Capability concentration sits with specialty manufacturers possessing dual certification portfolios; scale advantage sits with diversified food and beverage conglomerates with established distribution infrastructure. The vendor base stratifies across three tiers: clinical-credibility specialists serving hospital-affiliated channels, custom formulation boutiques capturing boutique fitness consolidation, and price-positioned volume players leveraging warehouse-direct logistics. Dominant competitive moves include exclusive supply agreement pursuit with consolidating fitness chains and backward integration into dairy protein supply chains.
Among publicly traded nutrition specialists, Glanbia Plc exemplifies the premium dairy-isolate archetype through Irish supply chain anchoring, while Abbott Laboratories occupies the clinical-credibility position via hospital-affiliated channel control. PepsiCo Inc represents the scale-driven distribution bypass model, eliminating wholesale tiers through direct franchise servicing. These three patterns illustrate how capability specialization and scale economics create non-overlapping competitive territories.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Herbalife Ltd |
| Glanbia Plc |
| Iovate Health Sciences International |
| Science in Sport |
| PepsiCo Inc |
| Post Holdings Inc |
| MusclePharm Corp |
| The Bountiful Company |
| Others |
Cost & Logistics Intelligence
New Zealand and European Union dairy auction concentration transmits directly to contract manufacturing economics, anchoring margin pools in premium isolate production while compressing returns on standardized whey concentrate SKUs. Procurement consolidation by professional sports franchises and collegiate athletic departments is redirecting pricing power toward manufacturers with dual NSF Certified for Sport and Informed Sport portfolios.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement, with professional teams and collegiate programs locking in 12-24 month supply contracts that guarantee batch-specific HPLC documentation and banned-substance screening. Price differentiation rests on certification grade—dual-certified manufacturers command substantial premiums over single-certified competitors—and volume scale, where franchise-wide exclusive agreements secure favorable unit economics. Cost compression in whey protein concentrate tiers is intensifying because New Zealand dairy auction volatility transmits directly to standardized powder margins. Mid-market fitness chains exhibit highest price sensitivity, while hospital-affiliated sports medicine channels prioritize clinical credibility over unit cost.
Supply Chain Analysis
EU novel food approval frameworks function as de facto export controls on precision-fermented protein substrates, limiting commercial flows of cell-cultured ingredients into European markets until 18-24 month safety assessments conclude. Geographic supply concentration centers on Ireland and New Zealand for dairy-derived isolates, with Germany and the Netherlands emerging for fermentation capacity. Raw material dependencies include whey protein concentrate, individual amino acids for fortification, and specialized packaging films for shelf-stable formats. Single-source vulnerability runs through New Zealand dairy cooperative structures that set global auction benchmarks. Distribution runs through direct technical sales capabilities that bypass traditional wholesale tiers for custom formulation accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chromatography expertise for batch-level amino acid verification represents the critical capability gap constraining quality control scale, with HPLC analytical chemist scarcity creating bottlenecks during peak collegiate procurement seasons.
For Market Incumbents: Pre-empt boutique fitness chain consolidation by securing exclusive supply agreements with Equinox-caliber operators before single-source partnerships solidify. Expand pilot-scale precision fermentation capacity in North Rhine-Westphalia ahead of EFSA regulatory clarity on novel protein substrates. Dual certification portfolio maintenance demands redundant testing infrastructure that strains mid-tier competitors—accelerate investment to widen this capability moat. For New Entrants and Emerging Players: India's Maharashtra and Karnataka production corridors offer underpenetrated contract manufacturing opportunities following FSSAI's 2022 sports nutrition category formalization. Target domestic fitness chains seeking localized supply with faster turnaround than European or North American alternatives. White-label custom formulation services for boutique gyms in secondary Indian cities represent the most penetrable entry vector, bypassing saturated Western certification barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing single-certification portfolios that cannot sustain collegiate procurement mandates. Five-to-ten year viability hinges on backward integration into dairy protein supply chains or forward integration into direct technical sales capabilities. The inflection signal to watch is EFSA novel food approval acceleration under EU Green Deal protein diversification targets, which would revalue fermentation-focused production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Portfolio Expansion | NSF Certified for Sport and Informed Sport accreditations unlock NCAA and professional franchise procurement eligibility. |
| Precision Fermentation Capacity Buildout | EFSA novel food pathway investments position manufacturers for EU protein diversification mandates under Green Deal targets. |
| Direct-to-Gym Distribution Bypass | Warehouse-direct servicing eliminates wholesale markups and captures mid-market fitness chain volume. |
| Hospital-Affiliated Channel Partnership | Clinical credibility positioning through sports medicine networks differentiates from gym-floor commodity competition. |
| Custom Formulation Technical Sales | Embedded R&D collaboration with boutique chains compresses development cycles from 12 months to 6 weeks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Current Good Manufacturing Practice guidance documents, NSF Certified for Sport certification databases, EFSA novel food approval registers, and New Zealand dairy auction price series. Primary interviews engaged contract manufacturing executives, collegiate athletic procurement directors, boutique fitness chain operations managers, and HPLC analytical chemistry specialists. Secondary validation drew from customs trade data, SEC 10-K filings of publicly traded nutrition companies, and EU Green Deal protein policy documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs include protein powder volume by certification tier, custom formulation service revenue trajectories, and energy bar wholesale channel throughput across institutional and commercial buyer segments. The analytical framework models product type, end user category, distribution channel, and service type dimensions throughout the forecast period. CAGRs derive from historical growth pattern analysis adjusted for regulatory inflection points and procurement consolidation trends. Industry-specific inputs incorporate EFSA approval timeline assumptions and FSSAI category expansion penetration curves.
Practitioners should monitor EFSA novel food approval acceleration, New Zealand dairy auction volatility spikes, and state-level athletic commission testing protocol divergence for early signals requiring forecast reassessment. Material shifts in FDA enforcement priorities or collegiate conference certification mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Creatine Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Cricket Protein Powder Market