
 Japan Fitness Ring Market | 2026-2036
Japan Fitness Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Fitness Ring Market Insights
The Act on the Protection of Personal Information is repositioning compliance costs for biometric data collectors in Japan. Oura Health Ltd leverages its Nordic engineering heritage to sustain premium positioning among health-conscious professionals. Sony Corporation anchors domestic manufacturing credibility through its sensor technology legacy. Xiaomi Corporation competes on cost-efficient Bluetooth-enabled models distributed through e-commerce platforms.
A fitness ring is a wearable device incorporating photoplethysmography sensors, accelerometers, and temperature monitors into a titanium or ceramic band form factor, designed to track sleep stages, heart rate variability, and activity metrics without wrist-based obstruction. Smart rings dominate unit economics due to higher silicon integration and subscription revenue potential, while sensor-based technology leads growth as manufacturers embed SpO2 and galvanic skin response modules. Hybrid rings occupy a narrowing middle ground as consumers polarize between full-featured smart devices and minimalist traditional designs.
METI's consumer electronics safety guidelines and Japan's Act on the Protection of Personal Information jointly elevate product certification and data encryption requirements for wearable importers. The country's national pharmaceutical regulator maintains advisory oversight on devices making health-adjacent claims, creating a dual-track compliance environment. Stakeholders must monitor whether METI expands mandatory cybersecurity labeling to biometric wearables, as this would reshape supplier qualification timelines and retail channel access for non-domestic brands.
Market Dynamics
Japan's amended Act on the Protection of Personal Information is forcing biometric wearable manufacturers to restructure data architectures, elevating compliance engineering to a core competitive capability alongside sensor miniaturization.
Growth Catalysts
- Corporate wellness mandates:Large technology and financial services employers in Greater Tokyo are subsidizing fitness ring purchases for employees, creating institutional demand channels that bypass traditional retail friction.
- METI consumer electronics safety guidelines:Clear certification pathways for biometric wearables reduce market entry uncertainty for domestic and qualified foreign manufacturers, accelerating product registration timelines.
- Photoplethysmography sensor maturation:Improved accuracy in continuous heart rate and SpO2 monitoring from finger-based placement is validating clinical-grade claims and expanding reimbursable use cases through employer health plans.
Market Restraints
- Titanium supply concentration:Premium ring casings depend on specialized Japanese and Chinese metal suppliers, exposing manufacturers to input cost volatility and qualification delays for alternative sources.
- Data localization requirements:Japan's Act on the Protection of Personal Information mandates domestic server infrastructure for health data, raising fixed costs for foreign brands without existing cloud presence in the country.
- Wrist-wearable substitution:Established smartwatch ecosystems from domestic electronics conglomerates capture consumers seeking display-based notification functionality that rings cannot replicate.
Strategic Opportunities
- Kansai region underpenetration:Osaka and Kyoto metropolitan areas lack the density of premium wearable retail and healthcare integration seen in Tokyo, representing whitespace for targeted channel expansion.
- Galvanic skin response convergence:Embedding stress biomarker detection alongside existing sleep and cardiac metrics differentiates products for corporate wellness programs targeting burnout prevention.
- Pharmacy channel innovation:Major drugstore chains are piloting biometric wearable sections with on-staff consultation, creating a trusted distribution layer for health-claiming devices.
Industry Challenges
- Biometric algorithm validation:Demonstrating clinical equivalence of finger-based PPG against chest-strap and wrist-based benchmarks requires expensive third-party studies and extended PMDA consultation timelines.
- Legacy hospital system integration:Electronic health record compatibility with regional medical networks demands proprietary API development, fragmenting engineering resources across incompatible institutional standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Fitness Ring Market |
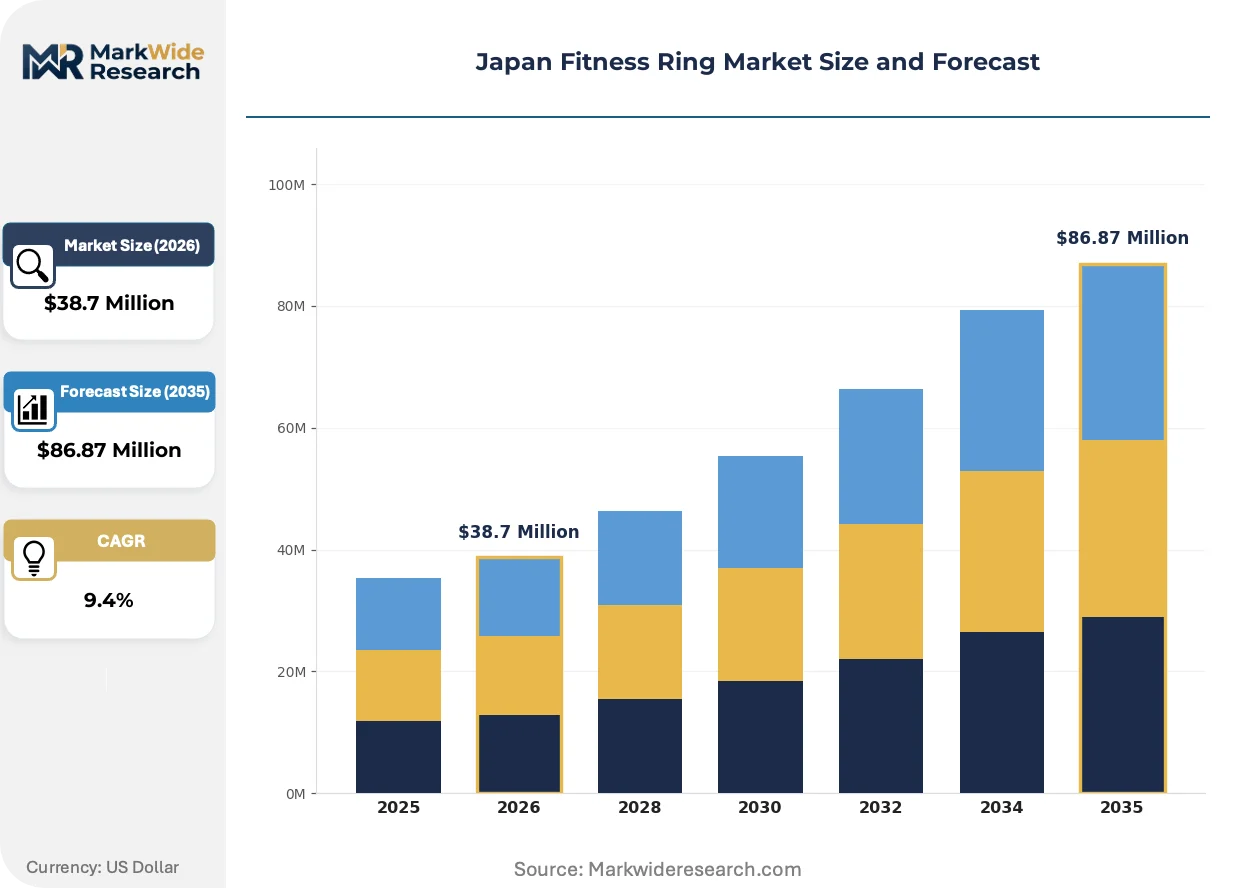
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Rings, Traditional Rings, Hybrid Rings, Adjustable Rings End User: Fitness Enthusiasts, Casual Users, Professional Athletes, Health Trackers Technology: Bluetooth, Wi-Fi, NFC, Sensor-Based Distribution Channel: Online Retail, Specialty Stores, Direct Sales, E-commerce Platforms |
| Companies Covered | Oura Health Ltd, Sony Corporation, Xiaomi Corporation, Apple Inc, Samsung Electronics Co Ltd, Fitbit Inc, Garmin Ltd, Huawei Technologies Co Ltd, Fossil Group Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Fitness Ring Market Trends and Innovations
Sensor fusion architectures are compressing the functional gap between medical-grade devices and consumer wearables, while data governance frameworks reshape how biometric information flows through institutional channels.
Photoplethysmography is decentralizing sleep and cardiac monitoring from clinical and wrist-worn settings into continuous finger-based measurement. Health-conscious professionals in Tokyo's financial and technology sectors are adopting these devices at accelerating rates for overnight recovery tracking. This technology is decentralizing diagnostic authority away from periodic clinic visits toward employer-supervised wellness ecosystems.
METI's consumer electronics safety guidelines are tightening electromagnetic compatibility and battery safety requirements for wearable importers. Manufacturers must now submit accelerated aging test data and thermal runaway containment documentation before retail authorization. Smart ring categories with integrated lithium-polymer cells face the steepest compliance burden, driving some brands toward capacitor-based minimalist designs.
Subscription revenue models are displacing one-time hardware purchases among premium wearable buyers. Direct-to-consumer brands are bundling sleep coaching and cardiovascular trend analysis with device sales, while traditional electronics retailers struggle to accommodate recurring billing relationships. This shift concentrates most visibly in Tokyo's dense urban corridors where digital payment penetration and health app literacy run highest.
Japan Fitness Ring Market Segmentation
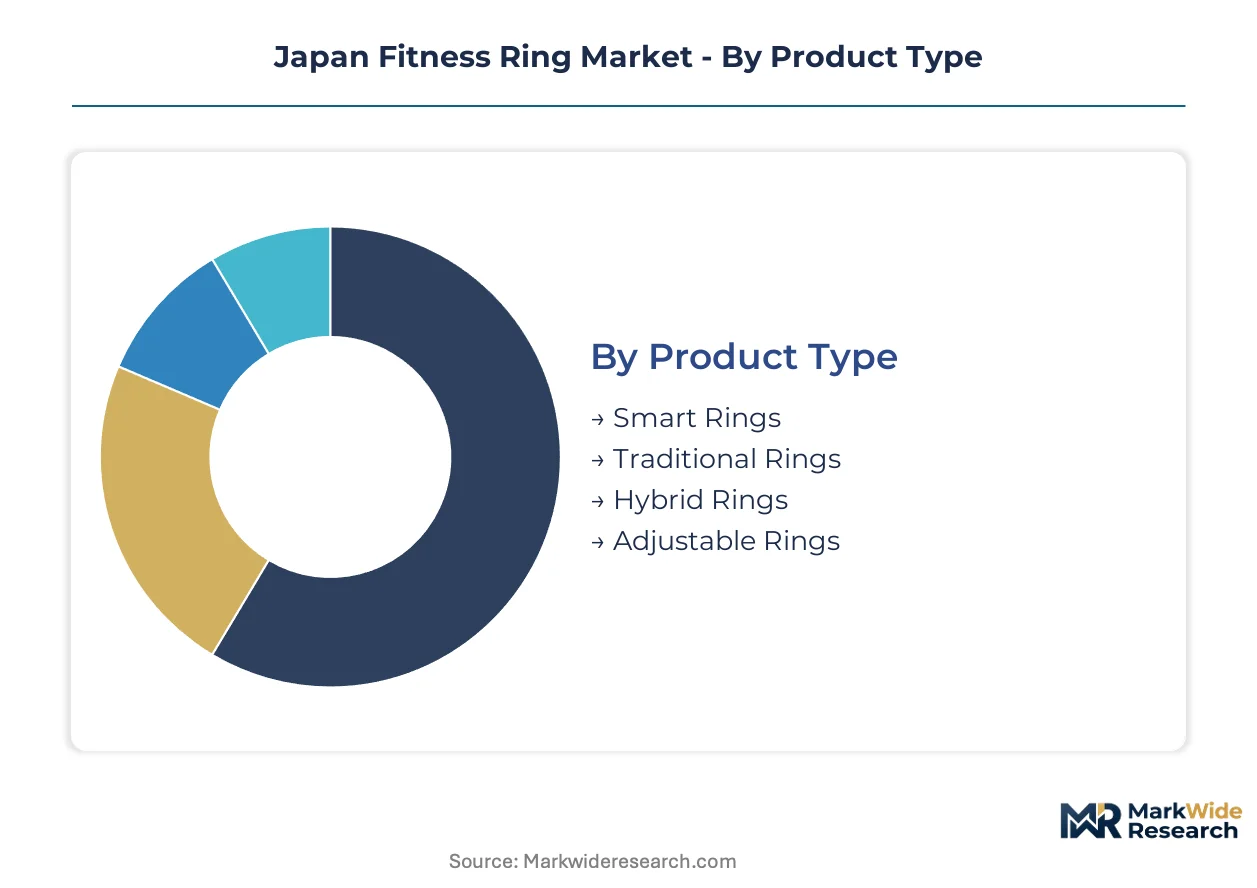
Japan's fitness ring market fragments across four distinct dimensions, each governed by divergent compliance requirements and procurement behaviors. Understanding these splits reveals how METI certification pathways and PMDA consultation timelines concentrate margin capture among prepared suppliers.
Product Type:
Certification burdens fall heaviest on smart rings requiring lithium-polymer battery safety validation under METI guidelines, while traditional rings face minimal electromagnetic compliance.
- Smart Rings:Photoplethysmography sensors, accelerometers, and temperature monitors integrate into titanium or ceramic bands for continuous biometric tracking. Tokyo's financial and technology sectors drive employer-subsidized procurement through corporate wellness mandates. PMDA scrutiny intensifies for clinical-grade health claims.
- Traditional Rings:Minimalist designs omit electronics entirely, serving aesthetic-conscious consumers in Osaka and Kyoto metropolitan areas. These products bypass METI electromagnetic compatibility requirements entirely, accelerating retail authorization timelines.
- Hybrid Rings:Limited sensor integration with replaceable battery modules occupies narrowing market positioning.
- Adjustable Rings:Modular sizing mechanisms target first-time wearable adopters in Kansai region pharmacy channels.
Leading the category by volume: Smart Rings. Expanding most quickly: Traditional Rings.
End User:
Procurement authority concentrates with institutional buyers subsidizing employee purchases, while individual consumers self-select through digital channels.
- Fitness Enthusiasts:Early adopters in Greater Tokyo Area demand SpO2 and heart rate variability validation through employer health plans. These users tolerate premium pricing for clinical-grade accuracy.
- Casual Users:Sleep-stage tracking and activity metrics satisfy recovery-conscious professionals in dense urban corridors. Subscription bundling with sleep coaching accelerates conversion.
- Professional Athletes:Specialized training facilities in Kansai pilot galvanic skin response modules for stress biomarker detection.
- Health Trackers:Chronic condition monitoring drives pharmacy channel consultation requirements for device selection.
Procurement volume leader: Fitness Enthusiasts. Steepest expansion trajectory: Health Trackers.
Technology:
Connectivity protocols determine data localization architecture under Japan's Act on the Protection of Personal Information, elevating infrastructure costs for foreign brands.
- Bluetooth:Low-energy protocols dominate cost-efficient models distributed through e-commerce platforms. Xiaomi Corporation leverages this technology for mass-market penetration.
- Sensor-Based:Photoplethysmography, SpO2, and galvanic skin response modules embed directly without continuous connectivity. Clinical-grade validation requirements concentrate engineering resources.
- Wi-Fi:Continuous cloud synchronization mandates domestic server infrastructure for health data compliance.
- NFC:Contactless payment integration appeals to Tokyo's digital payment penetration leaders.
Volume concentration: Bluetooth. Gaining share fastest: Sensor-Based.
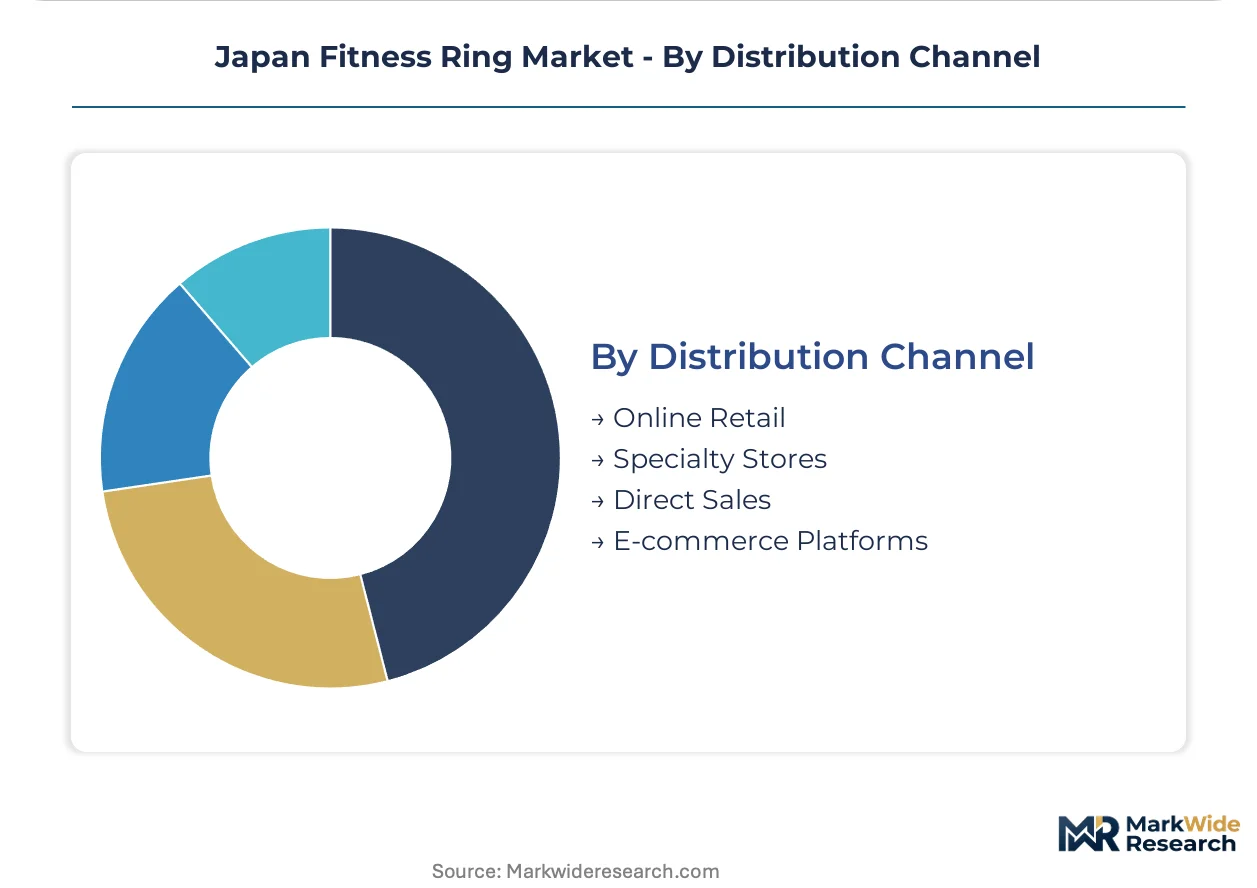
Distribution Channel:
Channel selection determines subscription revenue capture versus one-time hardware economics, with direct relationships enabling recurring billing infrastructure.
- Online Retail:Direct-to-consumer brands bundle sleep coaching and cardiovascular trend analysis with device sales. Digital payment penetration in Tokyo corridors supports subscription model viability.
- Specialty Stores:Electronics retailers struggle to accommodate recurring billing relationships, ceding premium positioning to brand-controlled channels.
- Direct Sales:Employer procurement programs at Rakuten and SoftBank bypass retail friction entirely.
- E-commerce Platforms:Cost-efficient Bluetooth-enabled models achieve mass-market scale through platform distribution.
Revenue leader by volume: Online Retail. Channel climbing fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Strategic Special Zone program accelerates wearable technology clustering in Greater Tokyo, concentrating corporate wellness procurement and healthcare infrastructure investment within designated regulatory relief areas.
Kanto/Tokyo
Corporate wellness mandates at technology and financial services employers drive institutional demand channels that bypass traditional retail friction. METI consumer electronics safety guidelines provide clear certification pathways for biometric wearables entering this market. Dense healthcare infrastructure in the Tokyo metropolitan corridor validates clinical-grade health claims through employer-supervised wellness ecosystems.
Kansai/Osaka
Osaka and Kyoto metropolitan areas lack the density of premium wearable retail and healthcare integration seen in Tokyo, representing whitespace for targeted channel expansion. The Act on the Protection of Personal Information applies uniform data localization requirements regardless of regional market maturity. Pharmacy channel innovation with on-staff consultation is piloting biometric wearable sections in this underpenetrated corridor.
Chubu/Nagoya
Manufacturing heritage in precision electronics supports component supply chains for sensor miniaturization and titanium casing fabrication. PMDA advisory oversight on health-adjacent claims creates consistent regulatory expectations across domestic production zones. Industrial clusters in Aichi Prefecture supply specialized metal suppliers for premium ring casings, though alternative source qualification delays persist.
Kyushu
Regional medical networks demand proprietary API development for electronic health record compatibility, fragmenting engineering resources across incompatible institutional standards. The amended Act on the Protection of Personal Information mandates domestic server infrastructure for health data regardless of regional patient volume. Fukuoka's emerging technology startup ecosystem attracts wearable brands seeking lower operational costs than Tokyo corridors.
Hokkaido
Seasonal tourism and outdoor recreation create niche demand for temperature-monitoring wearables among cold-climate athletes. METI electromagnetic compatibility requirements apply uniformly to all retail authorization timelines. Sapporo's healthcare providers lag in employer wellness program adoption compared to southern metropolitan concentrations.
Japan Fitness Ring Market Competitive Landscape
Nordic engineering heritage anchors one tier; East Asian electronics conglomerates hold manufacturing scale advantages. The vendor base concentrates around sensor technology legacy and cost-efficient platform distribution, creating a bifurcated structure between premium positioning and mass-market penetration. Three strategic archetypes dominate: clinical-grade accuracy specialists, consumer electronics ecosystem integrators, and direct-to-consumer subscription brands. Competitive moves center on corporate wellness program partnerships and domestic cloud infrastructure establishment for data compliance.
Within the premium-tier vector, Oura Health Ltd exemplifies Nordic engineering positioning among health-conscious professionals. Sony Corporation anchors domestic manufacturing credibility through its sensor technology heritage. Xiaomi Corporation occupies the cost-efficient platform distribution archetype through e-commerce channel penetration.
| Leading Market Players |
|---|
| Oura Health Ltd |
| Sony Corporation |
| Xiaomi Corporation |
| Apple Inc |
| Samsung Electronics Co Ltd |
| Fitbit Inc |
| Garmin Ltd |
| Huawei Technologies Co Ltd |
| Fossil Group Inc |
| Others |
Pricing and Supply Chain Analysis
Photoplethysmography sensor miniaturization is compressing silicon integration costs while concentrating procurement leverage among Japanese and South Korean foundries capable of clinical-grade validation. This production-method transition simultaneously elevates fixed certification expenses for METI compliance and rewards scale economies among incumbents with established PMDA consultation histories.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as corporate wellness programs at Greater Tokyo employers demand rapid deployment cycles. Subscription bundling with sleep coaching and cardiovascular trend analysis separates premium direct-to-consumer brands from transactional e-commerce models. Cost compression in Bluetooth-enabled tiers intensifies as Xiaomi Corporation and platform distributors compete on spot inventory availability. Casual users in Osaka and Kyoto exhibit highest price sensitivity, while fitness enthusiasts tolerate premium positioning for SpO2 validation.
Supply Chain Analysis
Freight cost volatility from Chinese titanium suppliers to Japanese assembly facilities elevates landed costs for premium ceramic and metal casings. Component sourcing draws from Taiwan for photoplethysmography sensors, South Korea for lithium-polymer cells, and domestic Chubu clusters for precision metalwork. Single-source vulnerability concentrates in specialized Japanese titanium suppliers serving Oura Health Ltd and Sony Corporation. Distribution runs through direct-to-consumer channels for subscription revenue capture, with pharmacy pilots in Kansai emerging as secondary pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium casing fabrication capacity constraints among qualified Japanese metal suppliers prop pricing power for incumbents with captive supplier relationships. This supply bottleneck sustains margin premiums despite Bluetooth-enabled tier compression.
For Market Incumbents: Acquire domestic cloud infrastructure assets to satisfy Act on the Protection of Personal Information data localization mandates without third-party dependency. Secure backward integration into photoplethysmography sensor supply through Taiwanese foundry partnerships, insulating against wrist-wearable substitution threats from domestic electronics conglomerates. For New Entrants and Emerging Players: Pharmacy chain partners in Kansai offer the most penetrable channel whitespace given underdeveloped premium wearable retail density in Osaka and Kyoto. Target health tracker segments through on-staff consultation pilots at major drugstore chains, leveraging galvanic skin response modules as burnout prevention differentiators for corporate wellness procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by consumer electronics ecosystem integrators seeking clinical-grade wearable capabilities. Long-term viability hinges on PMDA advisory relationship depth and domestic server infrastructure presence. Watch METI cybersecurity labeling expansion as the inflection signal for supplier qualification timeline restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cloud Infrastructure Establishment | Act on the Protection of Personal Information compliance eliminates foreign server dependency for health data. |
| Galvanic Skin Response Module Integration | Stress biomarker detection differentiates offerings for Rakuten and SoftBank corporate wellness programs. |
| Pharmacy Channel Partnership | On-staff consultation pilots in Kansai create trusted distribution for health-claiming devices. |
| PMDA Clinical Validation Investment | Finger-based PPG equivalence studies unlock employer health plan reimbursement pathways. |
| Titanium Supplier Qualification | Alternative source approval reduces input cost volatility from concentrated Japanese metal suppliers. |
Research Methodology
Multi-period observation of photoplethysmography sensor accuracy benchmarks and METI certification timelines anchored the trend analysis, supplemented by interviews with wearable product managers, corporate wellness procurement leads at technology employers, pharmacy chain category buyers, and PMDA regulatory consultants. Secondary validation drew from METI consumer electronics safety guidelines, PMDA advisory documentation, employer health plan reimbursement policies, and customs records for titanium and ceramic component imports. Bottom-up shipment estimates triangulated against top-down corporate wellness subsidy disbursement data.
Segment-weighting approaches distributed value projections across smart ring, traditional ring, and hybrid ring form factors, with technology splits for Bluetooth, sensor-based, Wi-Fi, and NFC connectivity protocols. End-user segmentation modeled fitness enthusiasts, casual users, professional athletes, and health trackers against channel economics for online retail, specialty stores, direct sales, and e-commerce platforms. CAGRs derived from employer subsidy expansion trajectories, sensor cost curves, and data localization infrastructure buildout rates across the analysis window.
Caveats apply where METI cybersecurity labeling expansion or PMDA algorithm validation requirement tightening could materially shift the outlook for non-domestic brand market access. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Strength Training Equipment Market
Fitness Equipment
Home Fitness Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Exercise Bike Market