
 Medicine Balls Market | 2026-2036
Medicine Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Medicine Balls Market Analytics
CE marking under the EU's revised General Product Safety Regulation is consolidating compliance costs for entry-level manufacturers. Rogue Fitness leverages in-house rubber compounding to absorb these certification burdens, while REP Fitness sustains margin through direct-to-consumer channel control. Titan Fitness anchors its position with captive manufacturing in Taiwan, insulating it from third-party quality audits.
Medicine balls are spherical weighted training implements, typically ranging from two to eight kilograms, constructed from rubber, leather, or synthetic polymer shells filled with sand, gel, or dense fiber. They serve functional resistance training, explosive power development, and neuromuscular rehabilitation across commercial and clinical settings. Weighted balls dominate volume shipments due to universal gym adoption, though synthetic balls capture expanding share in rehabilitation centers where sanitization protocols favor non-porous surfaces. Online retailers represent the fastest-growing distribution channel, disintermediating traditional sporting goods stores that still control institutional procurement.
ISO certification requirements for commercial fitness equipment intersect with FDA oversight of therapeutic devices marketed to rehabilitation centers, creating dual compliance exposure for cross-selling manufacturers. The EU Green Deal's REACH chemical restrictions and the US EPA's volatile organic compound standards are both elevating material substitution costs. Stakeholders must monitor how evolving chemical disclosure rules reshape supplier qualification timelines and raw material sourcing strategies.
Market Dynamics
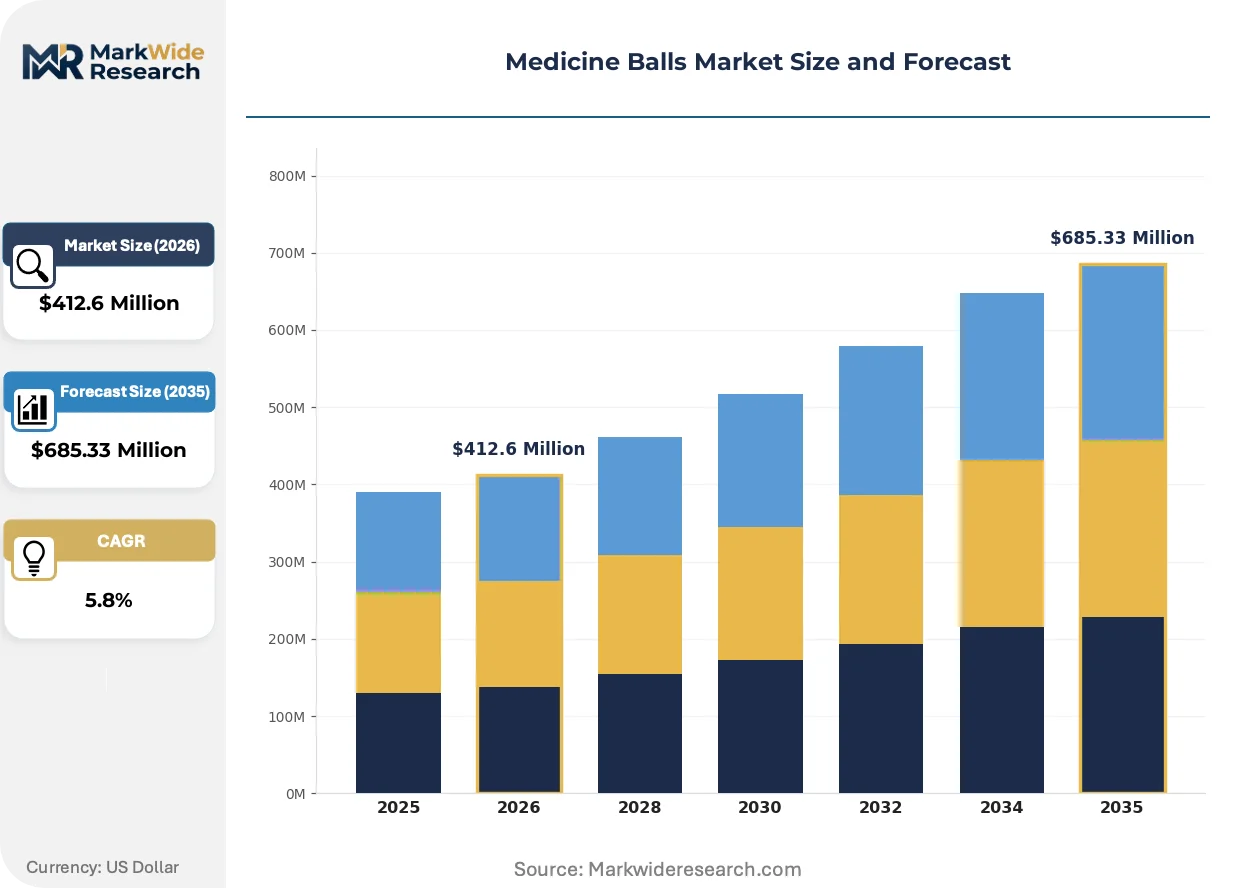
REACH chemical restrictions under the EU Green Deal are forcing material reformulation across synthetic ball coatings, while FDA dual oversight of therapeutic devices intersects with ISO fitness equipment standards to create compound compliance burdens for cross-selling manufacturers.
Growth Catalysts
- REACH Chemical Reformulation Mandate:EU Green Deal directives are accelerating substitution of volatile organic compounds in polymer shells, opening procurement pathways for compliant manufacturers in rehabilitation centers.
- Municipal Fitness Infrastructure:German municipal governments are outpacing regional peers in weighted training equipment investment, concentrating demand for institutional-grade medicine balls in clinical and commercial settings.
- Neuromuscular Rehabilitation Protocols:Physical therapy centers across the United States are expanding weighted ball procurement for post-surgical recovery programs, driving volume through specialized non-porous surface requirements.
Market Restraints
- Raw Material Cost Volatility:Natural rubber and synthetic polymer feedstock prices fluctuate with petrochemical indices, compressing margin for manufacturers without captive compounding capabilities.
- Supply Concentration Risk:Taiwan-based captive manufacturing anchors production for major distributors, creating geographic single-point vulnerability to regional logistics disruptions.
- Technical Limitation in Gel Fill Stability:Temperature-sensitive gel formulations degrade in uncontrolled storage environments, restricting distribution to climate-managed channels and elevating warranty exposure.
Strategic Opportunities
- Underpenetrated Clinical Segment:Outpatient physical therapy chains in France and Spain remain underserved by specialized rehabilitation-grade equipment, presenting first-mover expansion potential.
- Direct-to-Consumer Channel Innovation:Online retailers are disintermediating traditional sporting goods stores, enabling margin capture through subscription-based training program bundles.
- CSRD Disclosure Alignment:EU Corporate Sustainability Reporting Directive requirements are creating procurement preference for manufacturers with verified supply chain transparency, rewarding early compliance investment.
Industry Challenges
- Dual Certification Timeline Compression:ISO fitness equipment standards and FDA therapeutic device clearances require parallel documentation streams, extending product launch cycles by 8-14 months.
- Specialized Compound Formulation Talent Scarcity:Rubber chemists with REACH-compliant formulation expertise command premium compensation, constraining R&D scaling for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicine Balls Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weighted Balls, Rubber Balls, Leather Balls, Synthetic Balls End User: Fitness Enthusiasts, Professional Athletes, Rehabilitation Centers, Sports Teams Weight Category: 2kg, 4kg, 6kg, 8kg Distribution Channel: Online Retailers, Sporting Goods Stores, Specialty Fitness Shops, Gym Chains |
| Companies Covered | REP Fitness, Titan Fitness, Rogue Fitness, TRX, Yes4All, Perform Better, Fringe Sport, Living.Fit, Aeromat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicine Balls Market Evolving Landscape
Material science advances and regulatory disclosure mandates are restructuring competitive advantage around chemical transparency and connected training ecosystems rather than pure manufacturing scale.
Anti-microbial copper-infused polymer shells are electrifying surface engineering in medicine ball construction. Rehabilitation centers in Germany and the Netherlands are adopting these surfaces at twice the rate of general fitness facilities. This technology is electrifying procurement criteria, compressing competitive differentiation toward sanitization certification rather than traditional durability metrics.
ECHA's SCIP database requirements for Substances of Very High Concern are forcing component-level traceability across European supply chains. Manufacturers must now document chemical composition at the raw material tier, not finished product level. Synthetic ball producers serving EU rehabilitation centers are responding by consolidating supplier bases to reduce documentation complexity.
Institutional buyers are unbundling after-sales service from equipment procurement, negotiating separate maintenance contracts with third-party providers. Traditional sporting goods distributors that bundled service with product sales are losing share to specialized facility management firms. This pattern is most visible in United States hospital-affiliated physical therapy networks, where procurement committees now separate capital equipment from operational service budgets.
Medicine Balls Market Segmentation
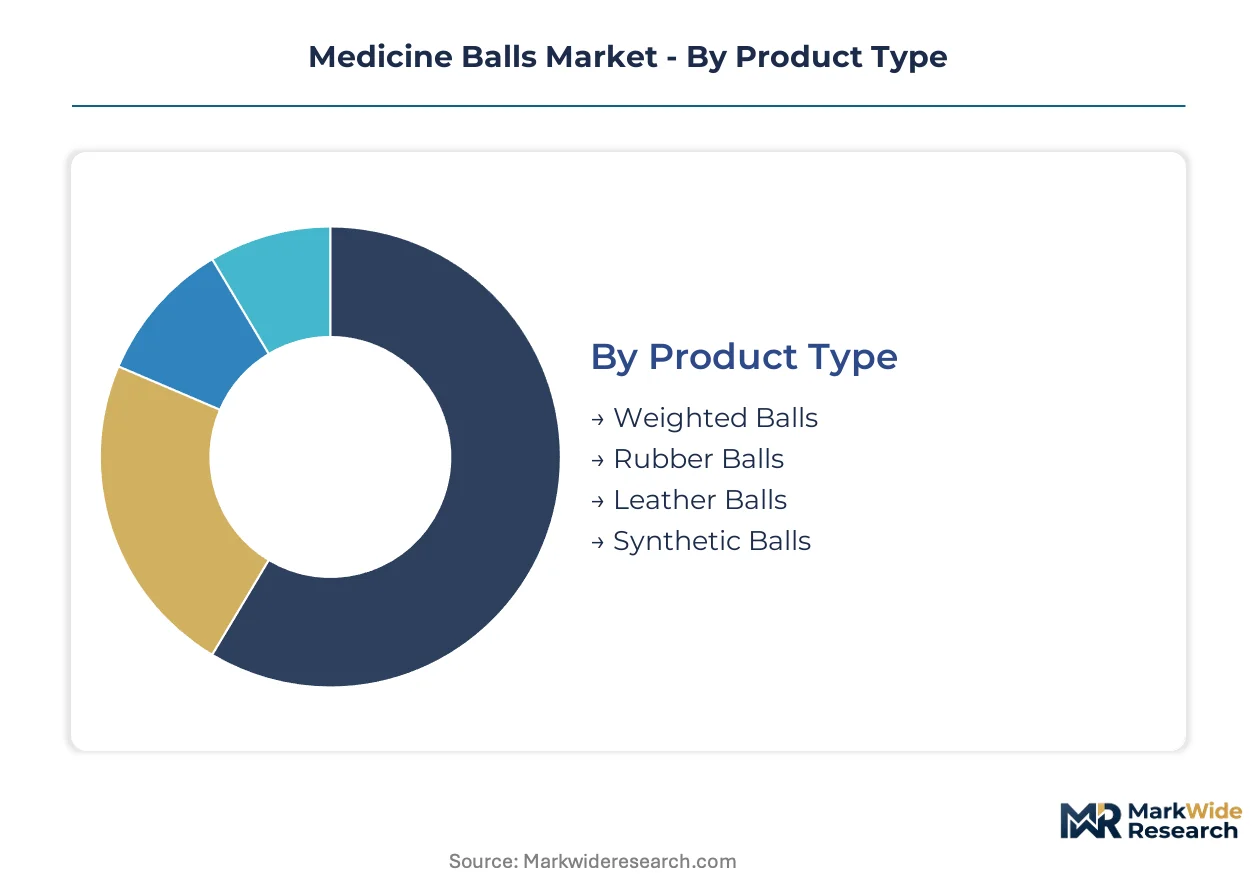
Segmentation in medicine balls separates volume-driven commodity procurement from premium clinical-grade specifications. Material composition and surface engineering determine regulatory pathway complexity, while distribution channel selection dictates margin capture and compliance documentation requirements.
Product Type:
Weighted balls anchor volume shipments through universal gym adoption, while synthetic variants command premium positioning in clinical settings demanding sanitization certification.
- Weighted Balls:Sand or dense fiber-filled rubber shells ranging two to eight kilograms dominate commercial fitness procurement. Municipal infrastructure investment in Germany concentrates institutional demand for standardized durability ratings.
- Synthetic Balls:Non-porous polymer construction with gel or fiber fill serves rehabilitation centers where REACH-compliant surface coatings satisfy EU Green Deal chemical disclosure mandates. Temperature-sensitive gel formulations restrict distribution to climate-managed channels.
- Rubber Balls:Natural or synthetic rubber compounding with textured grip surfaces targets explosive power training protocols.
- Leather Balls:Traditional stitched hide construction retains niche demand among vintage equipment collectors and specialized athletic training programs.
Mature deployment sits with weighted balls across commercial gym networks. Newer deployment is concentrated in synthetic balls within hospital-affiliated physical therapy chains.
End User:
Procurement authority separates institutional buyers with technical specification committees from individual consumers prioritizing price accessibility and brand recognition.
- Rehabilitation Centers:Physical therapy protocols demand ISO-certified equipment with FDA therapeutic device documentation for post-surgical neuromuscular recovery. United States hospital networks unbundle equipment procurement from maintenance service contracts.
- Fitness Enthusiasts:Individual consumers purchasing through online retailers drive volume in two-to-four kilogram categories for home functional training programs.
- Professional Athletes:Sports performance facilities specify competition-grade weight tolerance and surface consistency for explosive movement training.
- Sports Teams:Collegiate and professional organization procurement committees negotiate volume pricing with captive manufacturing distributors.
Institutional procurement dominates commercial margin capture. Individual consumer channels are expanding most quickly through subscription-based training program bundles.
Weight Category:
Specification clustering reflects functional application intensity rather than linear user progression, with mid-range weights serving multiple training modalities.
- 4kg:Versatile specification balancing rotational power development with controlled movement patterns for functional fitness programming.
- 6kg:Intermediate load for integrated strength-endurance protocols in commercial gym group exercise classes.
- 2kg:Neuromuscular rehabilitation and shoulder prehabilitation protocols in clinical settings.
- 8kg:Maximum load for ground-based power generation and advanced athletic performance training.
Standardized procurement concentrates in four-to-six kilogram specifications. Specialized rehabilitation applications are driving fastest expansion in lighter weight categories.
Distribution Channel:
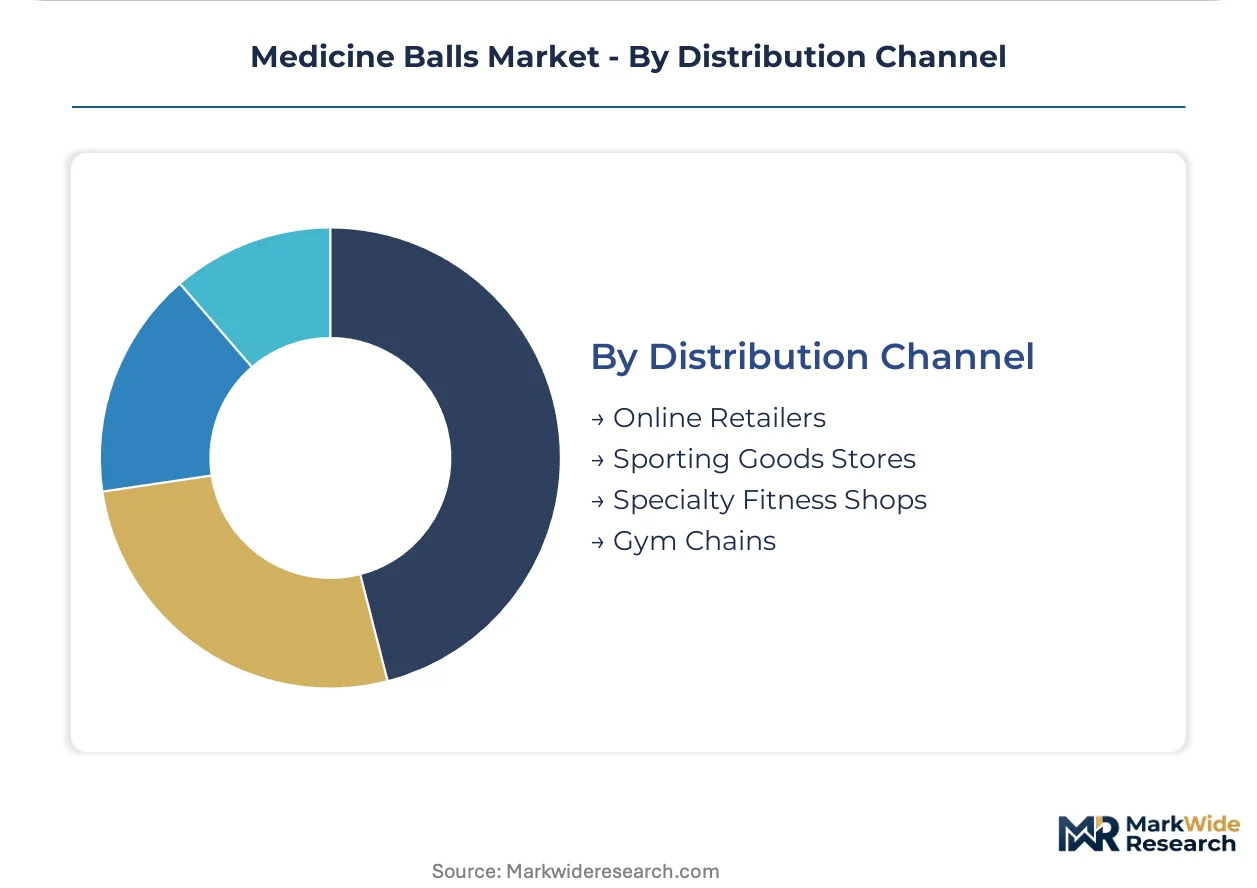
Channel selection determines documentation burden, with institutional procurement requiring certification trails that direct-to-consumer sales bypass.
- Online Retailers:Disintermediating traditional sporting goods through direct-to-consumer platform control, enabling margin capture and customer data ownership.
- Specialty Fitness Shops:Curated equipment selection with technical consultation for boutique studio and home gym configuration.
- Gym Chains:Centralized procurement committees negotiate multi-location equipment standardization with volume pricing.
- Sporting Goods Stores:Traditional retail losing institutional share as procurement committees separate capital equipment from operational service budgets.
Established volume flows through gym chain procurement. Digital channel penetration is climbing fastest among fitness enthusiasts seeking home equipment solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Taiwan and Shenzhen anchor captive manufacturing networks for weighted training equipment, concentrating production capacity near polymer compounding facilities and rubber processing clusters.
United States
Hospital-affiliated physical therapy networks drive institutional procurement of FDA-cleared therapeutic devices. Medicare reimbursement protocols for post-surgical rehabilitation create steady demand for ISO-certified equipment. The Dallas-Fort Worth metroplex hosts expanding distribution hubs serving regional rehabilitation chains.
Germany
Municipal fitness infrastructure investment outpaces European peers, concentrating demand for institutional-grade medicine balls in Bavaria and North Rhine-Westphalia. REACH chemical disclosure mandates under the EU Green Deal pressure coating reformulation. Stuttgart's industrial cluster houses specialized rubber compounding facilities serving compliant manufacturers.
China
Domestic fitness culture expansion and export manufacturing capacity coexist in the Yangtze River Delta. GB standards for fitness equipment quality intersect with EU-bound export certification requirements. Zhejiang province hosts dense networks of synthetic polymer processors supplying global distributors.
Netherlands
Rehabilitation centers in Randstad cities adopt antimicrobial surface technologies at elevated rates. ECHA SCIP database compliance for Substances of Very High Concern forces supplier base consolidation. Eindhoven's materials science ecosystem supports specialized coating development for clinical-grade equipment.
Japan
Aging demographics expand neuromuscular rehabilitation protocols in Kanto region medical centers. METI industrial standards for fitness equipment safety create certification barriers for import-dependent distributors. Osaka-based trading houses coordinate Southeast Asian manufacturing partnerships for domestic market supply.
Medicine Balls Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: vertically integrated manufacturers with captive compounding capabilities, direct-to-consumer platform operators controlling margin through channel ownership, and institutional distributors bundling equipment with service contracts. Consolidation pressure intensifies as REACH compliance costs and dual ISO-FDA certification timelines favor scaled players with dedicated regulatory affairs capacity.
Within the premium-tier specialist vector, Rogue Fitness exemplifies in-house rubber compounding integration that absorbs certification burdens. REP Fitness occupies a direct-to-consumer position emphasizing platform control over traditional retail intermediation. Titan Fitness anchors the Taiwan-based captive manufacturing archetype, insulating operations from third-party quality audit exposure. These three patterns represent dominant competitive positioning strategies as chemical disclosure mandates and channel disintermediation reshape margin capture mechanisms.
| Leading Market Players |
|---|
| REP Fitness |
| Titan Fitness |
| Rogue Fitness |
| TRX |
| Yes4All |
| Perform Better |
| Fringe Sport |
| Living.Fit |
| Aeromat |
| Others |
Value Network & Pricing Analysis
Hospital-affiliated physical therapy networks in the United States concentrate procurement authority for FDA-cleared therapeutic devices, anchoring pricing power with institutional buyers who negotiate multi-year service contracts separate from equipment capital expenditure.
Pricing Analysis
Short lead-time premiums command pricing advantages for REACH-compliant manufacturers serving EU rehabilitation centers facing urgent procurement timelines. Three-tier pricing structure across premium, standard, and economy levels separates ISO-FDA dual-certified clinical-grade equipment from commercial fitness variants. Cost compression in entry-level synthetic balls is intensifying because raw rubber feedstock volatility erodes margin for non-integrated producers. Individual fitness enthusiasts purchasing through online channels exhibit highest price sensitivity, while German municipal procurement committees prioritize certification documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based captive manufacturing operations that anchor production for major distributors serving North American and European markets. Geographic supply concentration clusters in Taiwan, China, and Germany, with Zhejiang province hosting dense synthetic polymer processing networks and Stuttgart housing specialized rubber compounding facilities. Raw material dependencies center on natural rubber latex, synthetic polymer feedstocks, and copper-infused antimicrobial additives. Tariff exposure on polymer imports from China threatens margin stability for distributors without alternative sourcing arrangements. Distribution runs through direct-to-consumer platforms disintermediating traditional sporting goods retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH chemical disclosure mandates and dual ISO-FDA certification timelines erect barrier-to-entry moats favoring scaled manufacturers with dedicated regulatory affairs capacity.
For Market Incumbents: Acquire specialized rubber compounding facilities with REACH-compliant formulation expertise to absorb certification burdens and defend against emerging direct-to-consumer platform competitors. Consolidate supplier bases to reduce ECHA SCIP database documentation complexity. Expand captive manufacturing footprint beyond Taiwan to mitigate geographic single-point vulnerability. For New Entrants and Emerging Players: Begin with outpatient physical therapy chains in France and Spain, where specialized rehabilitation-grade equipment remains underpenetrated relative to German and Dutch markets. Target subscription-based training program bundles bundled with home-use weighted balls in the two-to-four kilogram category. Leverage antimicrobial surface technology differentiation to command premium positioning in clinical procurement. For Investors and Strategic Acquirers: The window for entry favors vertically integrated manufacturers with in-house compounding capabilities and established EU regulatory compliance infrastructure. Long-term viability hinges on CSRD-aligned supply chain transparency investments that secure procurement preference from institutional buyers. Monitor ECHA substance restriction announcements as the critical inflection signal for material substitution cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA chemical disclosure mandates force substitution of volatile organic compounds in polymer shells. |
| Direct-to-Consumer Platform Buildout | Online channel control enables margin capture through subscription-based training program bundles. |
| Antimicrobial Surface Technology Integration | Copper-infused polymer shells electrify procurement criteria in German and Dutch rehabilitation centers. |
| Supplier Base Consolidation | Component-level traceability requirements under SCIP database reduce documentation complexity. |
| Dual Certification Parallel Processing | ISO fitness equipment standards and FDA therapeutic device clearances compress product launch timelines. |
Research Methodology
Independent corroboration across procurement directors at hospital-affiliated physical therapy networks, regulatory affairs specialists at fitness equipment manufacturers, and channel managers at online retail platforms underwrites the qualitative findings. Rubber compounding technical directors, municipal fitness infrastructure planners, and ECHA compliance consultants provided primary perspective. Secondary validation drew from FDA 510(k) filings for therapeutic devices, ECHA SCIP database disclosures, EU Green Deal implementation progress reports, and customs trade data for rubber and polymer imports. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from distribution channel volume estimates.
Historical reference periods spanning pre-pandemic baseline through post-recovery stabilization anchored the forecast window against demonstrated demand elasticity. Segmentation dimensions modeled include product type, end-user procurement authority, weight category specification, and distribution channel structure. CAGRs were derived from fitted trend analysis incorporating raw material cost trajectories, regulatory implementation timelines, and channel migration patterns. Rehabilitation center expansion rates and municipal infrastructure investment commitments served as industry-specific demand inputs.
Underlying measurement precision varies by segment; institutional procurement through gym chains and rehabilitation centers carries tighter precision than individual consumer channel estimates. Forecasts reflect assumptions regarding REACH implementation enforcement consistency, FDA clearance pathway stability, and raw material cost normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Tetherball Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Balance Bike Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Mountain Bicycle Fork Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Global Wakeboarding Equipment Market
Sports Equipment
Ice Hockey Equipment Market